
 3D Rendering Market | 2026-2036
3D Rendering Market Size, Share, and Industry Trends Forecast 2026-2036
3D Rendering Market Analysis
Real-time ray tracing is reshaping how digital assets are produced and consumed across film, gaming, and industrial design pipelines. NVIDIA Corporation leverages its CUDA ecosystem and RTX hardware to dominate high-fidelity rendering workloads, while Autodesk Inc. anchors professional design workflows through Maya and 3ds Max integration. Epic Games competes by extending Unreal Engine's real-time capabilities into virtual production environments, displacing traditional offline pipelines for previsualization and final-pixel output.
3D rendering encompasses the computational generation of two-dimensional images from three-dimensional scene data, typically involving polygonal mesh processing, shader calculation, and light transport simulation at resolutions from HD to 8K for commercial delivery. The technology serves architecture visualization, film production, video games, and virtual reality by enabling photorealistic or stylized imagery without physical prototyping. Real-time rendering now leads growth as game engines penetrate non-gaming verticals, while offline rendering sustains premium margins in feature film visual effects where path tracing accuracy remains non-negotiable. Cloud rendering represents the fastest-expanding delivery mode, decoupling compute intensity from local hardware constraints and opening access to mid-market studios previously blocked by capital expenditure barriers.
The EU AI Act and GDPR impose transparency and data governance requirements on generative rendering tools trained on proprietary asset libraries, compelling vendors to restructure licensing and provenance tracking. The United States faces overlapping scrutiny from the FCC on cloud-rendered content distribution and from OSHA on workstation ergonomics for intensive GPU operations. Stakeholders must monitor how divergent regulatory timelines between European transparency mandates and American sectoral enforcement reshape cross-border product roadmaps and deployment strategies.
Market Dynamics
GPU-accelerated real-time pipelines are compressing production timelines across film, architecture, and industrial design, forcing vendors to restructure licensing models around consumption-based cloud access rather than perpetual seat licenses.
Growth Catalysts
- EU AI Act transparency mandates:Architectural visualization firms in Germany and France accelerate adoption of provenance-tracked generative tools to preempt compliance deadlines, expanding addressable market for governed rendering platforms.
- Virtual production workflows:Entertainment studios in Los Angeles and London displace physical set construction with LED volume stages driven by game-engine real-time output, sustaining hardware refresh cycles.
- Cloud rendering infrastructure:Mid-market animation houses in Canada and Australia bypass capital expenditure barriers through distributed GPU farms, democratizing access to path-traced final-pixel output previously reserved for major studios.
Market Restraints
- NVIDIA supply concentration:CUDA ecosystem lock-in and RTX hardware dependency create single-supplier risk for enterprise rendering farms, amplifying vulnerability to semiconductor fab allocation decisions.
- GDPR training-data restrictions:Generative model vendors face structural friction sourcing proprietary asset libraries for European deployment, forcing costly provenance infrastructure that compresses margin.
- Offline-to-real-time capability gaps:Feature film VFX houses retain path-tracing fidelity requirements that current real-time ray tracing cannot satisfy, segmenting the market and capping volume migration.
Strategic Opportunities
- India architectural visualization:Rapid urbanization and smart-city infrastructure investment in Mumbai and Bangalore create underpenetrated demand for GPU-accelerated design review and client presentation tools.
- Digital-twin convergence:Industrial engineering software is hybridizing with real-time rendering engines, opening white space for unified platforms serving manufacturing simulation and marketing asset generation.
- US Inflation Reduction Act clean-energy credits:Renewable project developers in Texas and California require photorealistic site visualization for permitting and investor relations, mandating rendering procurement at scale.
Industry Challenges
- Shader programming talent scarcity:Pipeline technical directors with HLSL/GLSL optimization expertise command premium compensation, constraining studio expansion and cloud-service quality assurance.
- Cross-platform asset standardization:USD (Universal Scene Description) adoption remains uneven across Autodesk, Blender, and game-engine ecosystems, forcing costly translation layers and version-control complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Rendering Market |
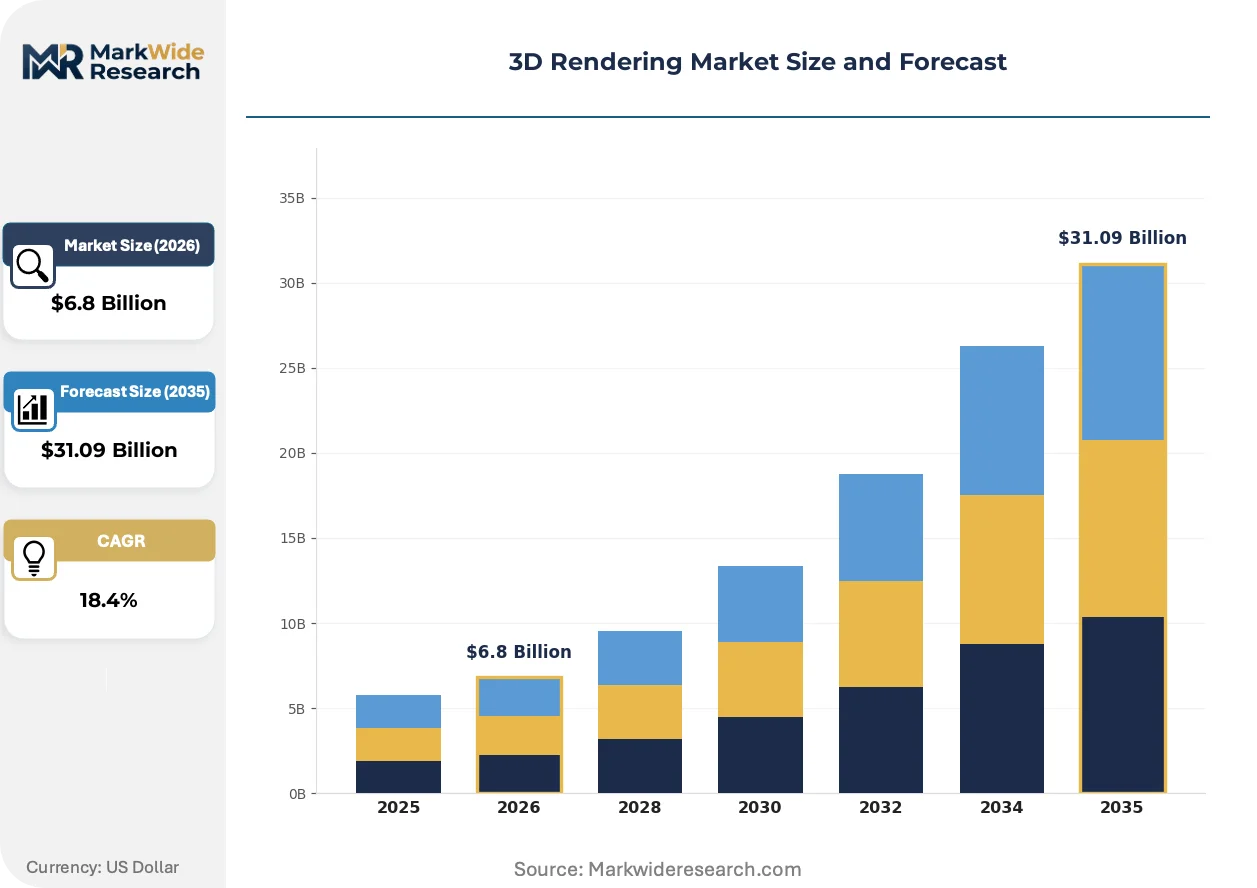
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Rendering, Offline Rendering, Cloud Rendering, Rasterization Technology: Ray Tracing, Path Tracing, Scanline Rendering, Photon Mapping Application: Video Games, Architecture Visualization, Film Production, Virtual Reality End User: Entertainment, Education, Product Design, Engineering |
| Companies Covered | Autodesk Inc., Adobe Inc., NVIDIA Corporation, Dassault Systèmes SE, Chaos Software Ltd., Unity Software Inc., Maxon Computer GmbH, Lumion, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Rendering Market Emerging Trajectories
Neural rendering techniques are compressing the boundary between real-time and offline quality thresholds, while regulatory pressure on training-data provenance forces architectural changes in how vendors structure generative product offerings.
Neural radiance fields (NeRFs) and Gaussian splatting are hybridizing volumetric capture with traditional polygonal workflows, enabling photorealistic environment reconstruction from sparse camera arrays. Automotive design studios in Stuttgart and Detroit adopt these techniques for rapid clay-model digitization, collapsing the iteration cycle between physical prototyping and virtual review. The structural consequence is displacement of structured-light scanning hardware vendors as software-based reconstruction achieves production fidelity.
GDPR Article 17 right-to-erasure and EU AI Act training-data documentation requirements impose granular provenance tracking on generative texture and model synthesis tools. Vendors serving European architectural and entertainment clients must restructure data pipelines to log every source asset contributing to synthetic output, increasing compliance overhead but creating defensible moats against ungoverned competitors. French and German regulators are already enforcing documentation audits on deployed generative rendering services.
Consumption-based licensing is displacing perpetual seat sales across mid-market visualization studios, with render-hour metering and cloud-GPU burst capacity replacing hardware ownership. Australian and Canadian animation houses lead this transition, unbundling software access from infrastructure commitment and compressing vendor switching costs. The shift pressures Autodesk and Epic to restructure enterprise agreements around outcome-based pricing rather than upfront license revenue.
3D Rendering Market Segmentation
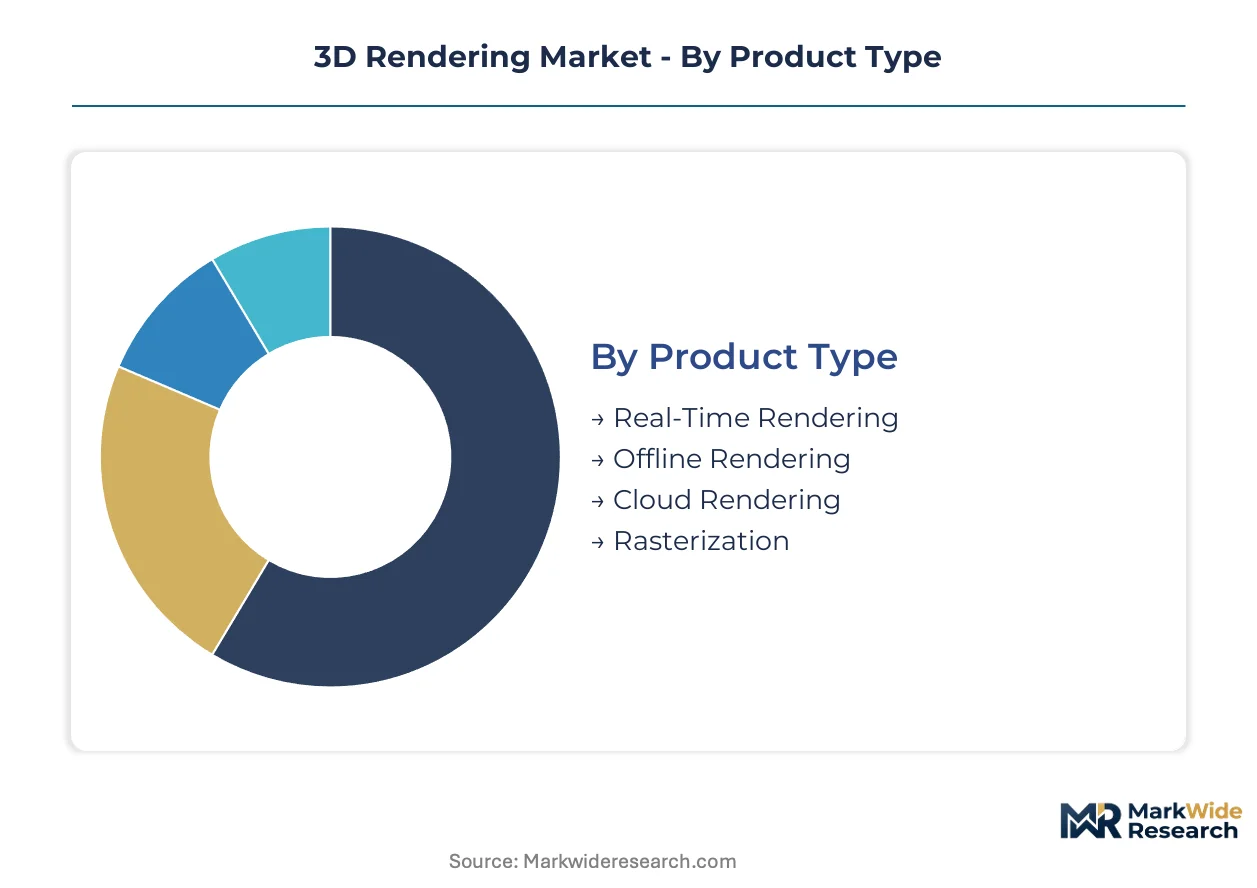
Segmentation in the 3D rendering market reveals how computational intensity, delivery latency, and visual fidelity requirements split demand across divergent hardware and licensing configurations. Vendors must architect product tiers that align with these technical boundaries rather than forcing uniform platforms across incompatible use cases.
Product Type:
Mature perpetual-license formats coexist with emerging consumption-based delivery, creating a bifurcated procurement landscape where capital efficiency competes against control preferences.
- Real-Time Rendering:Game-engine pipelines execute frame generation at 30-120 FPS for interactive environments, with Unreal Engine and Unity dominating LED volume stages in Los Angeles and London virtual production facilities. NVIDIA RTX hardware acceleration is displacing traditional previsualization workflows as final-pixel quality thresholds converge with offline alternatives.
- Cloud Rendering:Distributed GPU farms decouple compute intensity from local infrastructure, enabling mid-market Canadian and Australian studios to access path-traced output without seven-figure hardware investments. Burst capacity models align costs directly with project milestones rather than depreciating fixed assets.
- Offline Rendering:Arnold and RenderMan path-tracing engines sustain premium positioning in feature film VFX where light transport accuracy remains non-negotiable.
- Rasterization:Legacy polygon-scanline approaches retain cost advantages in mobile gaming and browser-based visualization where photorealism is secondary to frame rate stability.
Offline rendering handles the majority of high-fidelity throughput; cloud rendering is expanding most quickly as mid-market studios abandon capital expenditure models.
Technology:
Cost tier stratification separates enterprise-grade accuracy from accessible approximations, with hardware acceleration blurring traditional capability boundaries.
- Ray Tracing:NVIDIA RTX cores accelerate bounded ray intersection tests for real-time reflections and shadows, anchoring automotive design reviews in Stuttgart and Detroit studios where material accuracy accelerates approval cycles. The technology bridges game-engine responsiveness with offline-adjacent fidelity.
- Path Tracing:Unbiased Monte Carlo light simulation achieves ground-truth accuracy for feature film final frames, with Pixar's RenderMan and Chaos Group's V-Ray commanding per-hour premiums that sustain vendor margins despite lengthy render times.
- Scanline Rendering:Z-buffer depth sorting remains the default for mobile and web deployments where computational budgets are severely constrained.
- Photon Mapping:Two-pass irradiance caching approximates global illumination for architectural walkthroughs requiring faster-than-path-tracing turnaround.
Path tracing captures the highest-value contracts; ray tracing is gaining share fastest as hardware acceleration compresses quality gaps.
Application:
Volume concentration varies dramatically by vertical, with entertainment procurement cycles driving hardware refresh timing across the vendor ecosystem.
- Video Games:Real-time engines dominate asset production pipelines, with Epic Games Unreal Engine penetrating non-gaming verticals as visualization studios adopt game-technology infrastructure for client presentations and design review.
- Film Production:LED volume stages displace physical set construction in London and Los Angeles, mandating real-time output that synchronizes camera tracking with rendered backgrounds.
- Architecture Visualization:GPU-accelerated design review tools accelerate client approval cycles in Mumbai and Bangalore as urbanization drives project velocity.
- Virtual Reality:Stereoscopic frame-doubling requirements impose stringent latency budgets that favor foveated rendering and eye-tracked adaptive quality.
Video games generate the largest installed base; virtual reality is climbing the fastest on share as enterprise training applications expand.
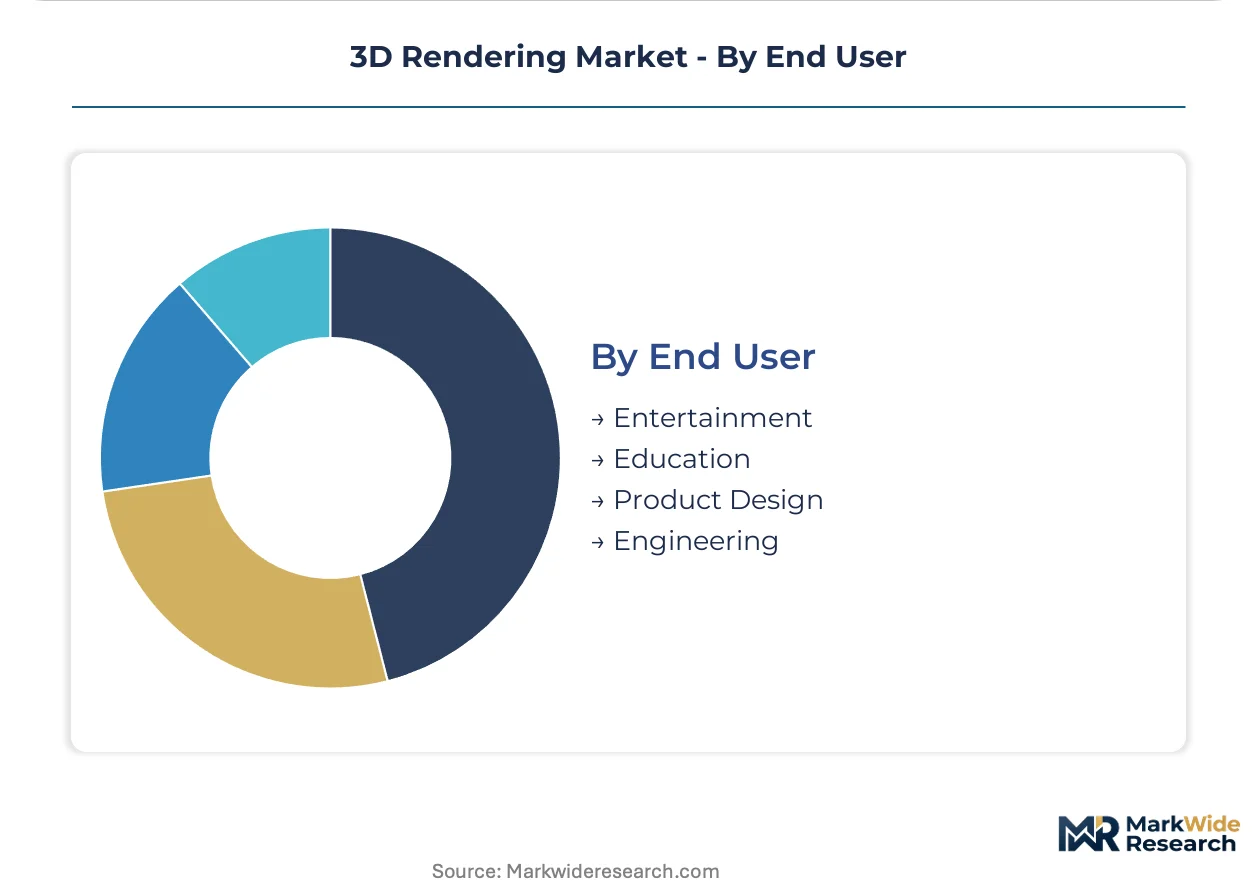
End User:
Customer type determines procurement authority and integration complexity, with enterprise engineering departments exhibiting divergent vendor selection criteria from creative studios.
- Entertainment:Major studios in Burbank and Vancouver consolidate licensing across Maya, Houdini, and Nuke pipelines, with multi-year enterprise agreements favoring vendors offering cross-product integration.
- Engineering:Siemens and Dassault Systèmes are hybridizing CAD kernels with real-time rendering engines for digital-twin visualization, creating procurement overlap between simulation and marketing asset generation.
- Product Design:Consumer electronics firms in Shenzhen and Seoul deploy rapid iteration cycles where GPU-accelerated clay-model digitization collapses physical prototyping timelines.
- Education:University programs in Melbourne and Toronto train pipeline technical directors, with institutional licensing prioritizing curriculum alignment over production-specific feature depth.
Entertainment commands the largest contract values; engineering is expanding most rapidly as manufacturing simulation converges with marketing visualization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Entertainment studios in Los Angeles and London drive enterprise licensing volumes, while engineering firms in Stuttgart and Mumbai accelerate GPU-accelerated adoption for design visualization and client presentations.
United States
Major entertainment studios in Burbank and Vancouver consolidate multi-year licensing agreements across integrated pipelines. The FCC scrutinizes cloud-rendered content distribution under emerging digital infrastructure rules. LED volume stages in Los Angeles displace physical set construction, mandating real-time rendering hardware refresh cycles.
Germany
Automotive design studios in Stuttgart deploy GPU-accelerated clay-model digitization to collapse physical prototyping timelines. The EU AI Act imposes transparency mandates on generative rendering tools, forcing provenance-tracking infrastructure investments. Architectural visualization firms in Munich accelerate adoption of governed rendering platforms to preempt compliance deadlines.
United Kingdom
Virtual production facilities in London integrate game-engine real-time output into LED volume stages for final-pixel delivery. GDPR training-data restrictions constrain generative model vendors sourcing proprietary asset libraries. VFX houses in Soho retain path-tracing fidelity requirements for feature film workloads.
India
Rapid urbanization in Mumbai and Bangalore creates underpenetrated demand for GPU-accelerated design review and client presentation tools. The country's national digital infrastructure programs support smart-city visualization procurement. Architectural visualization studios in Hyderabad expand render-hour metering contracts to bypass capital expenditure barriers.
China
Consumer electronics firms in Shenzhen deploy rapid iteration cycles where GPU-accelerated prototyping displaces traditional manufacturing workflows. National dual carbon goals mandate photorealistic site visualization for renewable energy permitting. Industrial engineering clusters in Shanghai hybridize CAD kernels with real-time rendering for digital-twin applications.
3D Rendering Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where hardware-anchored ecosystems dominate high-fidelity workloads and independent software vendors capture mid-market cloud transitions. The vendor base stratifies into three tiers: GPU-hardware platforms commanding render-farm infrastructure decisions, perpetual-license incumbents defending professional design workflows, and cloud-native challengers unbundling software access from capital commitment. Dominant competitive moves include consumption-based licensing restructuring and cross-platform asset standardization partnerships.
Within the hardware-platform tier, NVIDIA Corporation anchors CUDA-accelerated rendering infrastructure decisions across enterprise entertainment and engineering verticals. Autodesk Inc. and Adobe Inc. occupy positions within the perpetual-license incumbent tier, representing professional design workflow integration archetypes. Epic Games exemplifies the game-engine expansion vector, with Unreal Engine penetrating non-gaming verticals through real-time pipeline displacement.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Adobe Inc. |
| NVIDIA Corporation |
| Dassault Systèmes SE |
| Chaos Software Ltd. |
| Unity Software Inc. |
| Maxon Computer GmbH |
| Lumion |
| Epic Games |
| Others |
Supply Flow & Price Mechanics
Taiwanese semiconductor foundry capacity dynamics in Hsinchu and Tainan directly govern downstream pricing power for GPU-accelerated rendering infrastructure. NVIDIA's fab allocation decisions at TSMC cascade through enterprise render-farm procurement cycles, compressing margin for mid-market studios locked into RTX hardware dependencies.
Pricing Analysis
Cost-plus contracts indexed to wafer pricing at TSMC and Samsung Foundry dominate enterprise GPU procurement. Three-tier pricing structure across premium, standard, and economy levels separates path-traced final-pixel output from real-time ray tracing and rasterized mobile deployments. Cost compression in the mid-market tier is intensifying because Canadian and Australian studios unbundle software access from infrastructure commitment through render-hour metering. Independent visualization houses exhibit highest price sensitivity; major entertainment studios in Burbank and Vancouver lock in multi-year enterprise agreements that insulate them from spot-price volatility.
Supply Chain Analysis
Export controls under US Commerce Department restrictions on advanced GPU shipments to China constrain supply chain flows for AI-training-capable silicon. Taiwan, South Korea, and the United States anchor global supply for high-performance rendering hardware. Advanced packaging substrates from Japan and South Korea, EUV photoresists from Belgium and Japan, and cobalt-capacitor materials from the DRC constitute critical input dependencies. Single-source vulnerability at TSMC's N5/N3 nodes concentrates risk. Distribution runs through direct OEM relationships with Dell and HP for workstation fleets, supplemented by cloud-GPU burst capacity from AWS and Azure for elastic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as major entertainment studios in Los Angeles and London consolidate licensing across integrated Maya-Houdini-Nuke pipelines. This consolidation fragments pricing leverage for independent vendors unable to offer cross-product bundles.
For Market Incumbents: Build data-provenance infrastructure as a compliance moat against ungoverned competitors. Invest in backward integration into cloud-GPU farm capacity in Mumbai and Bangalore to capture Indian architectural visualization demand. The EU AI Act transparency mandates threaten margin for vendors lacking granular training-data tracking; certification investment in ISO-aligned provenance logging defends position against emerging cloud-native challengers unbundling software from infrastructure. For New Entrants and Emerging Players: Mid-market animation houses in Canada and Australia represent the most penetrable entry point through consumption-based render-hour metering. Indian smart-city visualization procurement in Hyderabad and Chennai offers white-space expansion as national digital infrastructure programs accelerate. Target engineering departments at Siemens and Dassault Systèmes customers with digital-twin convergence tools that hybridize CAD kernels with real-time rendering. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent EU and US compliance timelines create acquisition opportunities for provenance-compliant platforms. Target vendors with established GDPR documentation infrastructure and cloud-native delivery architectures. Watch for enforcement actions by French and German regulators on generative rendering services as the inflection signal for compliance-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Consumption-Based Licensing Restructuring | Autodesk and Epic pivot enterprise agreements toward render-hour metering to match Canadian studio procurement preferences. |
| Provenance Infrastructure Investment | Vendors deploy granular training-data tracking to satisfy EU AI Act audits in French and German markets. |
| Cloud-GPU Capacity Expansion | AWS and Azure burst capacity democratizes path-traced output for Australian mid-market animation houses. |
| Cross-Platform Asset Standardization | USD adoption partnerships reduce translation-layer costs between Blender, Maya, and Unreal Engine ecosystems. |
| Neural Rendering Technology Integration | NeRF and Gaussian splatting capabilities displace structured-light scanning vendors in Stuttgart automotive studios. |
Methodological Framework
A spread of perspectives from pipeline technical directors at Los Angeles VFX houses, cloud infrastructure procurement officers at Canadian animation studios, regulatory compliance leads at German architectural visualization firms, and GPU hardware product managers converged on the working assumptions. Primary interview insights combined with secondary validation from SEC 10-K filings, NVIDIA quarterly datacenter revenue disclosures, EU regulatory documentation in the Official Journal, and hyperscaler capex announcements. Bottom-up triangulation across render-hour metering contracts and top-down reconciliation against GPU shipment data anchored the analytical framework.
Demand-supply balance modeling across the projection horizon integrated real-time versus offline rendering segmentation, cloud versus on-premise deployment modes, and entertainment versus engineering end-use verticals. CAGRs derived from installed base expansion rates and pricing trajectory assumptions. Industry-specific forecast inputs incorporated LED volume stage deployment pipelines in London and Los Angeles, plus EU AI Act compliance deadline impacts on German and French procurement cycles.
Macroeconomic conditions sit as an overlay; deviation in semiconductor fab utilization rates, cloud infrastructure capital expenditure cycles, or cross-border data governance enforcement intensity would shift the trajectory. Material shifts in TSMC N5/N3 allocation priorities or US Commerce Department GPU export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Smartphone 3D Camera Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Printing CAD Software Market
3D Technology
3D Scanning Market
3D Technology
3D Mobile Mapping Market
3D Technology
3D Photogrammetry Software Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Reconstruction Market
3D Technology
3D Reconstruction Technology Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
Europe 3D Telepresence Market
3D Technology
UK 3D Rendering Services Market
3D Technology
Generative Design Market
3D Technology
Visualization and 3D Rendering Software Market