
 Bicycle Rim Brake Market | 2026-2036
Bicycle Rim Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Rim Brake Market Insights
The bicycle rim brake market is pivoting on a widening gap between premium CNC-machined alloy calipers and mass-market stamped steel assemblies. Shimano Inc. dominates OEM supply chains through captive forging capacity and tier-one relationships with frame manufacturers. SRAM LLC differentiates through modular pad systems that reduce service intervals for recreational riders. Tektro Technology Corporation competes on price in the commuter and entry-level enthusiast channels across Asian manufacturing hubs.
Bicycle rim brakes are mechanical or cable-actuated friction devices that clamp brake pads against the wheel rim sidewall to decelerate the bicycle, with pad compounds typically integrating rubber, Kevlar, or ceramic particulates for thermal management and wet-weather performance. Dual-pivot calipers deliver superior leverage modulation for road racing applications where precise speed control matters. Aluminum retains dominance in material selection for rim brake calipers due to its strength-to-weight ratio and machinability, though carbon fiber arms appear in ultra-premium weight-weenie segments. The enthusiast end-user category generates the highest margin pool per unit as these buyers prioritize tactile feedback and serviceability over absolute cost.
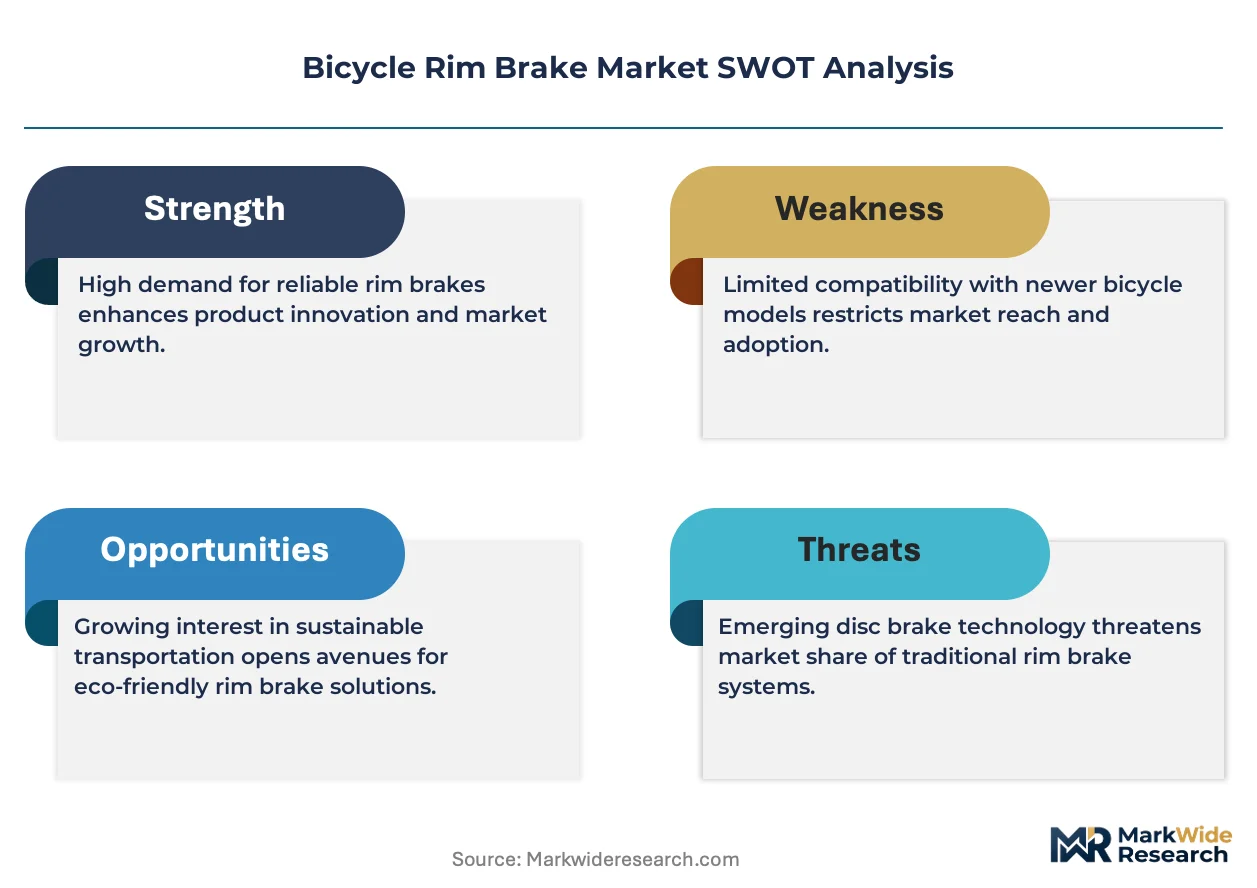
The U.S. Consumer Product Safety Commission enforces bicycle braking performance standards that mandate minimum stopping distances, directly shaping pad compound formulations and caliper mechanical advantage ratios. Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial standards for bicycle components through JIS certification protocols that govern export eligibility. ISO 4210 structural safety standards for bicycles influence rim brake mounting specifications and compatibility across frame architectures. Stakeholders must monitor regulatory divergence between disc brake mandates in certain racing federations and the persistent rim brake specification in weight-constrained professional road disciplines.
Market Dynamics
The bicycle rim brake market faces structural pressure from disc brake migration in mass-market segments, while premium road cycling maintains rim specification for weight-critical applications. Component suppliers must navigate divergent technical requirements across racing federations and consumer channels.
Growth Catalysts
- Professional road cycling specification:UCI WorldTour teams continue specifying rim brakes for mountain stages where every gram affects climbing performance. This institutional demand preserves high-margin OEM relationships.
- REACH-compliant pad compound innovation:European Union chemical regulations are forcing reformulation of brake pad matrices toward copper-free ceramics, creating technical differentiation opportunities for compound specialists.
- Heritage frame restoration:Vintage steel road bicycle collectors in Italy and Japan generate steady aftermarket demand for period-correct caliper designs and compatible replacement pads.
Market Restraints
- Aluminum alloy price volatility:CNC-machined caliper production depends on 6061-T6 and 7075-T6 billet pricing, which fluctuates with energy-intensive smelting costs in Chinese and Russian supply chains.
- Disc brake substitution in gravel and cyclocross:These formerly rim-brake disciplines have migrated almost entirely to hydraulic disc systems, eliminating a mid-tier volume channel.
- Frame manufacturer consolidation:Three Taiwanese frame houses control majority OEM specification decisions, constraining independent brake suppliers' access to new model introductions.
Strategic Opportunities
- Indian domestic bicycle manufacturing:PLI scheme incentives for component localization create openings for rim brake assembly operations serving Hero Cycles and TI Cycles export programs.
- Wet-weather compound premiumization:Ceramic-integrated pad formulations command 40-60% price premiums over standard rubber compounds in Northern European and Pacific Northwest markets.
- Direct-to-consumer service parts:E-commerce channels bypass traditional distributor markups for pad and cable replacement kits, capturing enthusiast riders performing home maintenance.
Industry Challenges
- Caliper centering precision:Manufacturing tolerance control for dual-pivot arm parallelism requires specialized fixturing that smaller machine shops struggle to maintain.
- JIS certification timeline:Japan's Ministry of Economy, Trade and Industry approval processes delay product launches by 8-14 months for suppliers seeking METI export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Rim Brake Market |
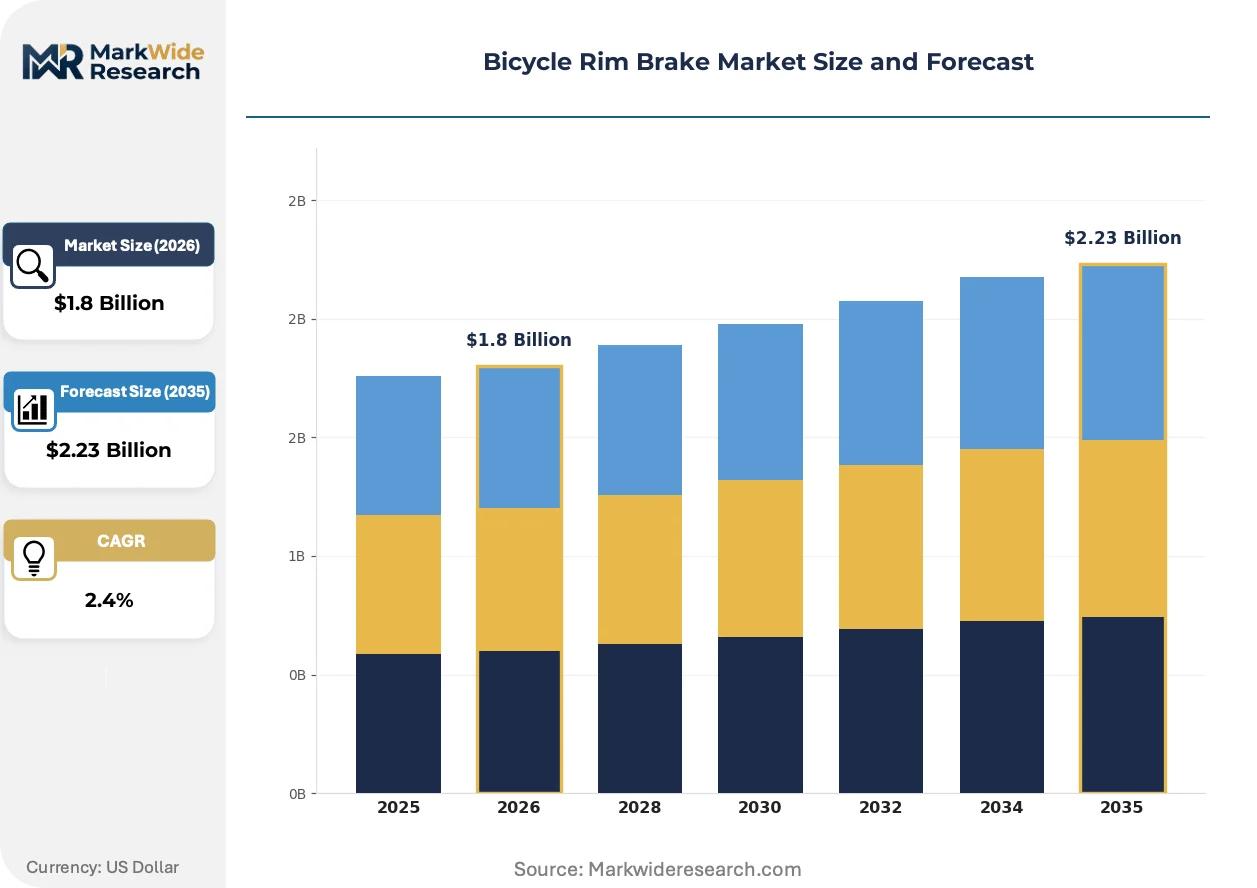
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Pull, Cantilever, V-Brakes, Dual-Pivot End User: Professional Cyclists, Recreational Riders, Commuters, Enthusiasts Material: Aluminum, Carbon Fiber, Steel, Plastic Installation Type: Front Brakes, Rear Brakes, Integrated Systems, Aftermarket |
| Companies Covered | Shimano Inc., SRAM LLC, Tektro Technology Corporation, Campagnolo S.r.l., BBB Cycling, Ashima Ltd., DIA-COMPE TAIWAN Co., Ltd., Full Speed Ahead S.r.l, Clarks Cycle Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Rim Brake Market Trends and Innovations
Titanium hardware and carbon fiber reinforcement are reshaping premium rim brake construction. Component engineers pursue absolute gram reduction while maintaining structural safety margins under ISO 4210 testing protocols.
Ceramic particulate brake pad matrices are expanding into high-performance road applications. These compounds manage thermal load during alpine descents better than organic alternatives. Professional team mechanics specify them for stage races with significant elevation change. The technology is expanding into amateur enthusiast segments as pricing normalizes.
The European Union's F-Gas Regulation and REACH directives are restricting perfluorinated compound use in brake pad binders. Manufacturers must reformulate friction materials without sacrificing wet-weather coefficient performance. Italian and German compound houses are investing in plasma-sprayed ceramic coatings as alternative friction surfaces.
Enthusiast riders are unbundling brake service from complete bicycle purchases. Independent bike shops report higher-margin pad and cable replacement revenue as owners maintain rim-brake-equipped machines longer. This pattern concentrates in markets with strong vintage bicycle culture, particularly Belgium and Japan's Keirin racing communities.
Bicycle Rim Brake Market Segmentation
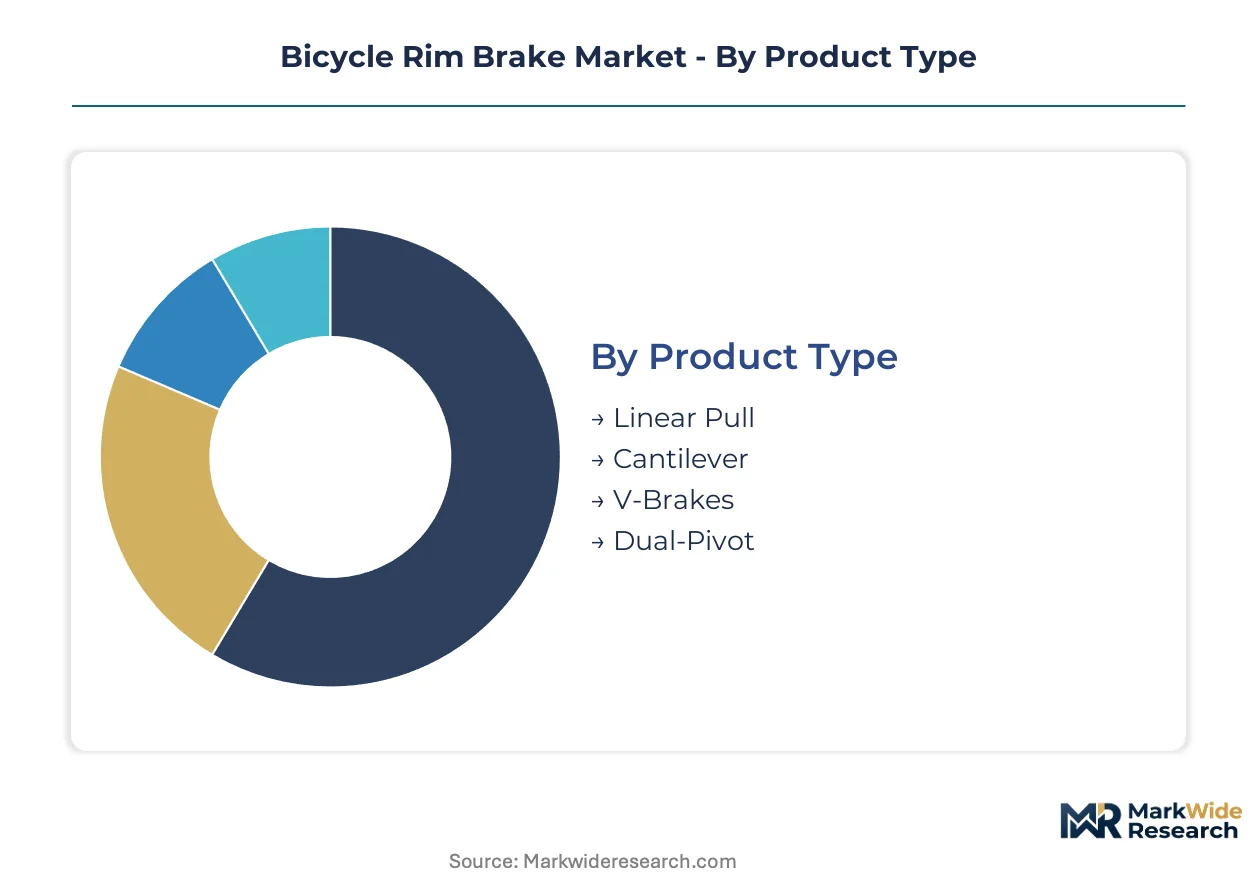
Rim brake architectures fragment across mechanical designs, user sophistication levels, and material specifications. Each segmentation axis reveals distinct margin structures and supply chain requirements. Component suppliers calibrate forging capacity and compound R&D against these divergent demand profiles.
Product Type:
Supply concentration favors forged alloy dual-pivot calipers for premium road applications, while stamped steel V-brake assemblies dominate Asian OEM supply chains for mass-market bicycles.
- Dual-Pivot:CNC-machined aluminum arms with differential mechanical advantage deliver precise modulation for drop-bar road racing. Demand concentrates in Italian and Japanese professional team supply chains where UCI weight minimums reward gram-level optimization. European frame manufacturers specify these for heritage road models.
- V-Brakes:Long-arm cantilever derivatives with increased cable pull ratio suit flat-bar hybrids and trekking bicycles. Asian manufacturing hubs in Taiwan and Vietnam produce these at scale for Hero Cycles and Giant Manufacturing OEM programs. The design persists in markets where disc brake conversion costs deter fleet operators.
- Linear Pull:Direct-pull mechanism with horizontal cable routing serves entry-level mountain bicycles and commuter hybrids. Mass-market distributors in India stock these for replacement cycles.
- Cantilever:Traditional wide-profile arms with straddle cable architecture remain specified for cyclocross and touring frames requiring wide tire clearance. Belgian and Japanese builders specify these for custom steel frames.
Today's leader: Dual-Pivot. Tomorrow's challenger: V-Brakes in Indian domestic manufacturing.
End User:
Margin stratification separates tactile-feedback-seeking enthusiasts from price-sensitive commuters, with professional specification driving compound innovation cycles.
- Enthusiasts:Home mechanics prioritize serviceability and pad availability over absolute cost, generating recurring aftermarket revenue for ceramic compound upgrades. Pacific Northwest and Northern European riders pay premiums for wet-weather formulations.
- Professional Cyclists:UCI WorldTour mechanics specify rim brakes for mountain stages where total bicycle weight affects climbing performance. Team sponsorship contracts with Shimano and Campagnolo preserve high-margin OEM relationships despite disc brake prevalence in other disciplines.
- Recreational Riders:Weekend cyclists on mid-tier road bicycles represent steady replacement pad demand through independent bike shop channels.
- Commuters:Price-sensitive urban riders on single-speed and fixed-gear bicycles drive volume for basic caliper assemblies in Asian manufacturing hubs.
Enthusiasts command the highest per-unit margin pool. Professional specification sets the technical benchmark that trickles downward.
Material:
Aluminum billet pricing volatility from Chinese and Russian smelting operations directly affects CNC-machined caliper cost structures, forcing suppliers toward long-term alloy contracts.
- Aluminum:6061-T6 and 7075-T6 alloys deliver optimal strength-to-weight ratios for forged and machined caliper bodies. Italian suppliers Campagnolo and FSA source European billet to satisfy REACH compliance documentation requirements.
- Carbon Fiber:Molded composite arms appear in sub-150 gram caliper sets for weight-constrained professional road applications. Japanese manufacturers lead plasma-sprayed friction surface integration to address thermal management limitations.
- Steel:Stamped chromoly and stainless steel constructions serve entry-level V-brake and cantilever assemblies for Asian OEM supply chains. Cost advantages persist despite weight penalties.
- Plastic:Glass-reinforced nylon composite hardware and cable housing guides reduce caliper weight in children's bicycle and budget hybrid segments. Injection molding capacity concentrates in Taiwanese component houses.
Aluminum retains structural dominance. Carbon fiber gains share fastest in premium road racing specification.
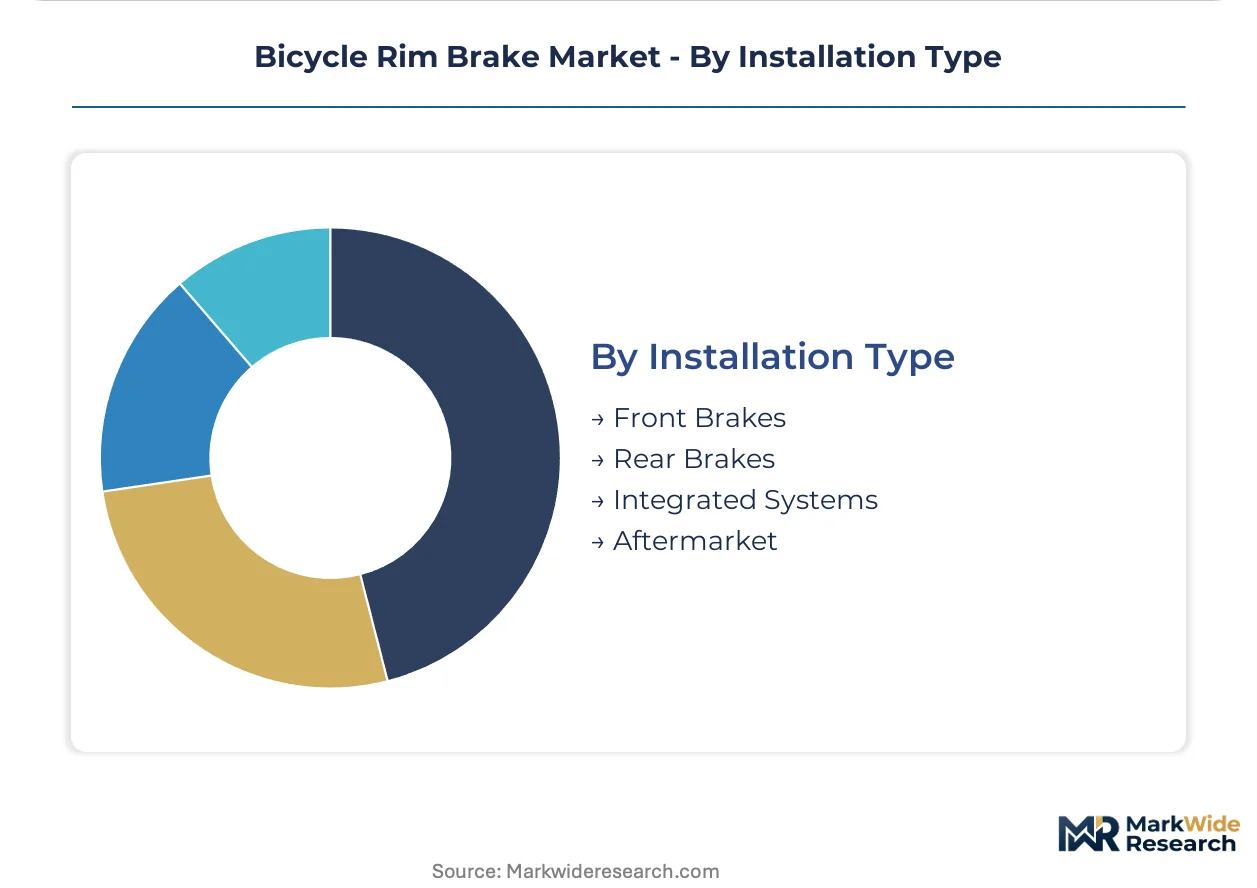
Installation Type:
Aftermarket pad and cable replacement kits bypass traditional distributor markups through direct-to-consumer channels, reshaping service revenue capture.
- Aftermarket:Pad compound specialists sell direct to enthusiast riders performing home maintenance, capturing margin previously retained by bike shops. E-commerce platforms enable ceramic formulation premiumization without retail markup.
- Front Brakes:Single-pivot and dual-pivot calipers mounted to fork crown and brake bridge handle primary deceleration loads. Frame manufacturers specify reach dimensions that constrain caliper compatibility.
- Rear Brakes:Seatstay- and chainstay-mounted calipers manage reduced thermal loads but require precise centering to avoid rim drag. Professional mechanics prioritize quick-release pad clearance for wheel changes.
- Integrated Systems:Complete brake-derailleur groupsets specified by OEM frame manufacturers lock in component supplier relationships across replacement cycles.
Aftermarket channels expand most quickly. Integrated systems defend incumbent supplier positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian tool-and-die craftsmen and Japanese precision machinists anchor the industry's geographic talent concentration, with Taiwanese forging specialists completing the triad of rim brake manufacturing expertise.
Italy
Vicenza's metallurgical heritage and Milan's design studios drive premium caliper demand for heritage road bicycles. The European Union's REACH directives restrict copper-based pad compounds, forcing reformulation toward ceramic matrices. Campagnolo's Bianzone facility maintains CNC-machining operations for WorldTour team supply chains.
Japan
Keirin racing culture and METI industrial standards sustain domestic rim brake specification against disc brake migration. Japan's Ministry of Economy, Trade and Industry enforces JIS certification protocols that govern component export eligibility. Sakai City's forging houses supply Shimano with 7075-T6 billet for Dura-Ace caliper production.
Taiwan
Taichung's bicycle component cluster controls OEM specification decisions for global frame manufacturers. The region operates under ISO 4210 structural safety standards that influence rim brake mounting geometries. Giant Manufacturing and Merida Industry source stamped steel V-brake assemblies from local forging subcontractors.
United States
Pacific Northwest recreational riders and Colorado cycling enthusiasts generate aftermarket demand for wet-weather pad compounds. The Consumer Product Safety Commission enforces minimum stopping distance standards that shape caliper mechanical advantage ratios. Boulder and Portland independent bike shops report elevated ceramic pad replacement revenue.
India
Hero Cycles and TI Cycles manufacturing programs create component localization opportunities under PLI scheme incentives. The Bureau of Indian Standards oversees bicycle safety certification for domestic market entry. Ludhiana's metalworking corridor hosts emerging rim brake assembly operations for export markets.
Bicycle Rim Brake Market Competitive Landscape
Top-tier vendors anchor premium CNC-machined alloy supply, while mass-market stamped steel fabricators compete on throughput and Asian manufacturing proximity. The vendor base stratifies across three archetypes: integrated groupset suppliers, standalone brake specialists, and contract forging operations serving OEM channels. Capacity expansion and strategic partnerships dominate competitive moves as frame manufacturer consolidation constrains independent supplier access.
Within the integrated groupset tier, Shimano Inc. and SRAM LLC represent the archetype of captive forging capacity and tier-one frame manufacturer relationships. Campagnolo S.r.l. occupies a position exemplifying Italian heritage premium positioning against Japanese scale efficiency. Tektro Technology Corporation sits within the contract manufacturing archetype, anchoring price-competitive supply for Asian OEM programs.
| Leading Market Players |
|---|
| Shimano Inc. |
| SRAM LLC |
| Tektro Technology Corporation |
| Campagnolo S.r.l. |
| BBB Cycling |
| Ashima Ltd. |
| DIA-COMPE TAIWAN Co., Ltd. |
| Full Speed Ahead S.r.l |
| Clarks Cycle Systems Ltd. |
| Others |
Pricing and Supply Chain Analysis
Vicenza's tool-and-die craftsmen anchor premium CNC-machining operations where labor-cost differentials between Italian heritage workshops and Taiwanese forging houses generate 3-4x pricing spreads across caliper tiers. The report traces how these workforce concentrations shape tier boundaries from mass-market stamped steel through WorldTour-specified alloy assemblies.
Pricing Analysis
Bundled OEM groupset pricing competes against unbundled aftermarket pad-and-cable service kits for enthusiast home mechanics. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-integrated WorldTour compounds from rubber commuter formulations and basic replacement pads. Pricing pressure stems from aluminum billet volatility in Chinese and Russian smelting operations squeezing CNC-machined caliper margins. Commuter segments exhibit highest price sensitivity while professional team specification tolerates premium positioning for gram-level optimization.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for Hero Cycles and TI Cycles assembly programs. Manufacturing gravity centers on Taiwan's Taichung forging cluster, Japan's Sakai City billet suppliers, and Italy's Vicenza machining corridor. Supply chains draw from 6061-T6 and 7075-T6 aluminum billet, ceramic particulate friction matrices, and plasma-sprayed coating systems. Single-source vulnerability concentrates in Taiwanese frame manufacturer consolidation controlling OEM specification access. Distribution runs through tier-one frame manufacturer relationships, independent bike shop channels, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle rim brake market represents a late-cycle quality story as professional road cycling specification preserves premium demand despite mass-market disc brake migration. Enthusiast rider preference for tactile feedback and serviceability sustains aftermarket premiumization.
For Market Incumbents: To counter disc brake substitution in gravel and cyclocross disciplines, incumbents should deepen backward integration into ceramic compound formulation capacity and secure long-term 7075-T6 billet contracts with Japanese forging houses. Channel control through tier-one frame manufacturer relationships defends OEM specification access against independent challengers.
For New Entrants and Emerging Players: Indian domestic bicycle manufacturers present the most penetrable buyer archetype for rim brake assembly localization under PLI scheme incentives. New entrants should target wet-weather compound premiumization in Pacific Northwest and Northern European markets through direct-to-consumer e-commerce bypassing traditional distributor markups. JIS certification investment unlocks METI export eligibility for Japanese Keirin racing community supply.
For Investors and Strategic Acquirers: Integrated groupset suppliers are the most active acquirer in this space, seeking compound specialists with REACH-compliant ceramic formulation capabilities. The long-term viability window favors targets with captive forging capacity and heritage brand positioning in Italian or Japanese markets. Watch for UCI regulatory shifts on disc brake mandates as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Formulation | REACH-compliant ceramic R&D secures European market access against regulatory restriction. |
| Long-term Aluminum Billet Contracting | Fixed-price 7075-T6 supply from Sakai City insulates margins from smelting cost volatility. |
| JIS Certification Investment | METI export eligibility unlocks Keirin racing and Japanese domestic OEM channels. |
| Direct-to-Consumer E-commerce Launch | Aftermarket pad premiumization bypasses bike shop markup capture in enthusiast segments. |
| PLI Scheme Manufacturing Localization | Indian domestic assembly positions for Hero Cycles and TI Cycles export program supply. |
Research Methodology
Bottom-up enthusiast and professional cyclist demand modeling reconciled against top-down forging capacity and OEM supply chain tracking forms the analytical core of this study. Primary interviews with WorldTour team mechanics, frame manufacturer procurement directors, compound house R&D leads, and independent bike shop service managers combined with secondary validation from UCI technical regulations, METI JIS certification protocols, EU REACH directive filings, and Bureau of Indian Standards safety documentation. Trade data from Taiwanese component export records and Italian metallurgical industry associations provided supply-side triangulation.
Historical trendline analysis of professional team specification patterns and aftermarket replacement cycle frequencies informed projection frameworks across the analysis window. Segmentation dimensions modeled include caliper architecture type, end-user sophistication tier, material specification grade, and installation channel structure. CAGRs derived from fitted trend extrapolation against structural constraint factors including regulatory divergence between racing federations and frame manufacturer consolidation dynamics.
Underlying measurement precision varies by segment; professional team specification and enthusiast aftermarket channels carry tighter precision than mass-market commuter volume estimates. Forecasts reflect documented assumptions on aluminum alloy price trajectories, regulatory enforcement timelines, and disc brake migration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Automotive Wheel Alignment Service Market