
 North America Bicycle Market | 2026-2036
North America Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bicycle Market Outlook
Urban fleet procurement for last-mile delivery and municipal bike-share programs is hardening into a concentrated buyer bloc with outsized volume leverage. Trek Bicycle Corporation leverages its domestic manufacturing footprint to anchor large institutional contracts across Midwest and Southeast networks. Rad Power Bikes specializes in direct-to-consumer electric models that compete aggressively on price against traditional retail channels.
A bicycle is a human-powered or electrically assisted vehicle consisting of a diamond or step-through frame, two wheels of 16 to 29 inches in diameter, and a chain-driven or belt-driven drivetrain, designed for individual transportation, fitness, or sport. Electric Bike configurations now command the fastest expansion within product type segmentation, propelled by lithium-ion battery cost curves and motor efficiency gains. Urban Commuters represent the most concentrated margin pool within customer type segmentation, as this cohort purchases higher-attachment accessories and replacement cycles at shorter intervals.
The U.S. Consumer Product Safety Commission enforces mechanical and electrical safety standards for bicycles sold in interstate commerce, while Transport Canada administers the Motor Vehicle Safety Act provisions affecting e-bike classification and roadway access. State-level rebate programs in California and Colorado, alongside provincial initiatives in British Columbia, are accelerating e-bike adoption by narrowing effective price gaps against conventional pedal bicycles. Stakeholders must monitor pending federal e-bike tax credit legislation and evolving municipal lane infrastructure commitments to anticipate demand inflection points.
Market Dynamics
E-bike incentive programs at the state and provincial level are compressing effective price differentials against conventional bicycles, while municipal lane infrastructure commitments in Vancouver, Seattle, and Denver are hardening route networks that sustain daily commuter adoption.
Growth Catalysts
- California Clean Vehicle Rebate Project:State-level point-of-sale incentives narrow acquisition cost gaps for electric bicycles against pedal-only alternatives, accelerating household substitution in dense metropolitan corridors.
- Lithium-ion battery cost curves:Cell price declines below $100 per kilowatt-hour enable mid-tier manufacturers to spec competitive range-to-weight ratios without premium positioning.
- Last-mile delivery fleet procurement:Urban logistics operators in Chicago and Toronto are consolidating volume commitments for cargo-capable electric bicycles, creating concentrated demand anchors.
Market Restraints
- Aluminum frame tubing supply concentration:Primary extrusion capacity clusters in specific Midwest industrial zones, exposing assemblers to regional logistics bottlenecks and input price volatility.
- Transport Canada Motor Vehicle Safety Act friction:Provincial classification discrepancies for throttle-assisted versus pedal-assist configurations create compliance fragmentation across British Columbia, Ontario, and Quebec distribution channels.
- Dockless scooter substitution:Micromobility rental fleets in Austin, Miami, and Washington D.C. capture short-trip segments that otherwise would convert to bicycle ownership.
Strategic Opportunities
- Colorado e-bike tax credit expansion:Pending legislation would extend rebate eligibility to lower-income households, opening penetration in Denver-Boulder corridor suburbs previously priced out of electric adoption.
- Belt-drive drivetrain convergence with internal hub gearing:Maintenance-free transmission architectures appeal to municipal bike-share operators seeking reduced field-service overhead.
- Direct-to-consumer channel maturation:Digital-native brands bypass traditional retail markups while capturing subscription-based accessory attachment revenue.
Industry Challenges
- Certification timeline compression:U.S. Consumer Product Safety Commission electrical safety testing protocols for battery systems extend product development cycles by four to six months.
- Specialized technician scarcity:Diagnostic and repair capability for integrated motor-controller systems concentrates in coastal metropolitan service centers, leaving interior markets underserved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bicycle Market |
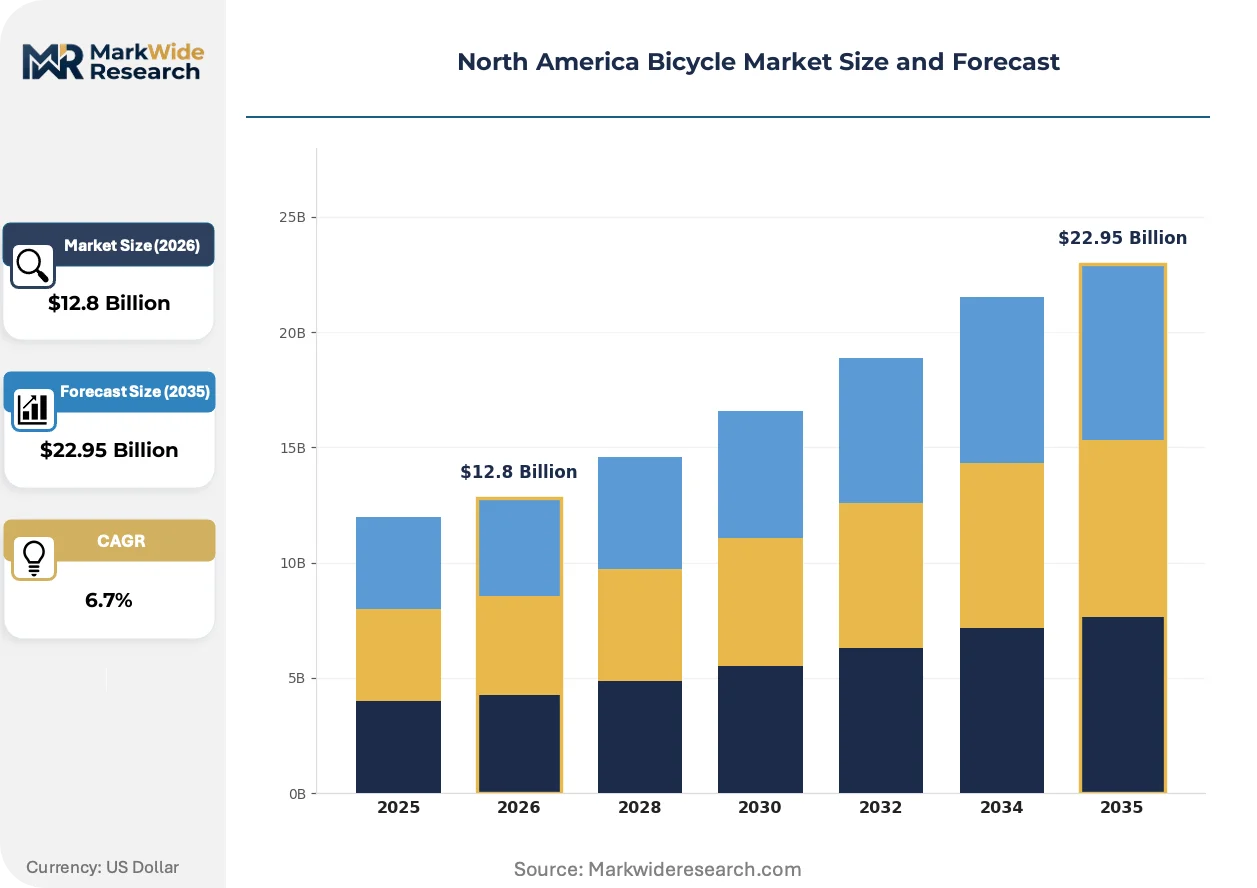
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bike, Road Bike, Hybrid Bike, Electric Bike Customer Type: Urban Commuters, Recreational Users, Professional Cyclists, Casual Riders Distribution Channel: Online Retailers, Specialty Bike Shops, Department Stores, Supermarkets Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Trek Bicycle Corporation, Specialized Bicycle Components, Giant Manufacturing Co., Cannondale Bicycle Corporation, Accell Group, Pon Bike, Schwinn Bicycle Company, Rad Power Bikes, Aventon, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bicycle Market Strategic Shifts
Electrification architectures and connectivity modules are redrawing component boundaries, while procurement patterns favor integrated system suppliers over discrete parts vendors.
Mid-drive torque-sensing motor systems are decentralizing power delivery optimization from frame manufacturers to specialized drivetrain suppliers. Trek and Specialized spec these units across urban commuter and light-trekking lines. The technology is decentralizing final assembly decisions, allowing brands to source complete electric powertrains as certified subsystems rather than engineering proprietary integrations.
Colorado and California rebate program structures are mandating point-of-sale price transparency for qualifying electric bicycles. Retailers must display net-after-incentive pricing prominently. Urban commuter segments in Denver, Los Angeles, and San Francisco respond by accelerating purchase decisions during legislative windows.
Fleet procurement for corporate wellness and last-mile logistics is consolidating through specialized distributors offering maintenance-inclusive service contracts. Traditional independent bicycle dealers lose volume to institutional channel specialists in Minneapolis, Portland, and Montreal. This rotation is most visible among healthcare and logistics employers seeking turnkey deployment without internal fleet management capability.
North America Bicycle Market Segmentation
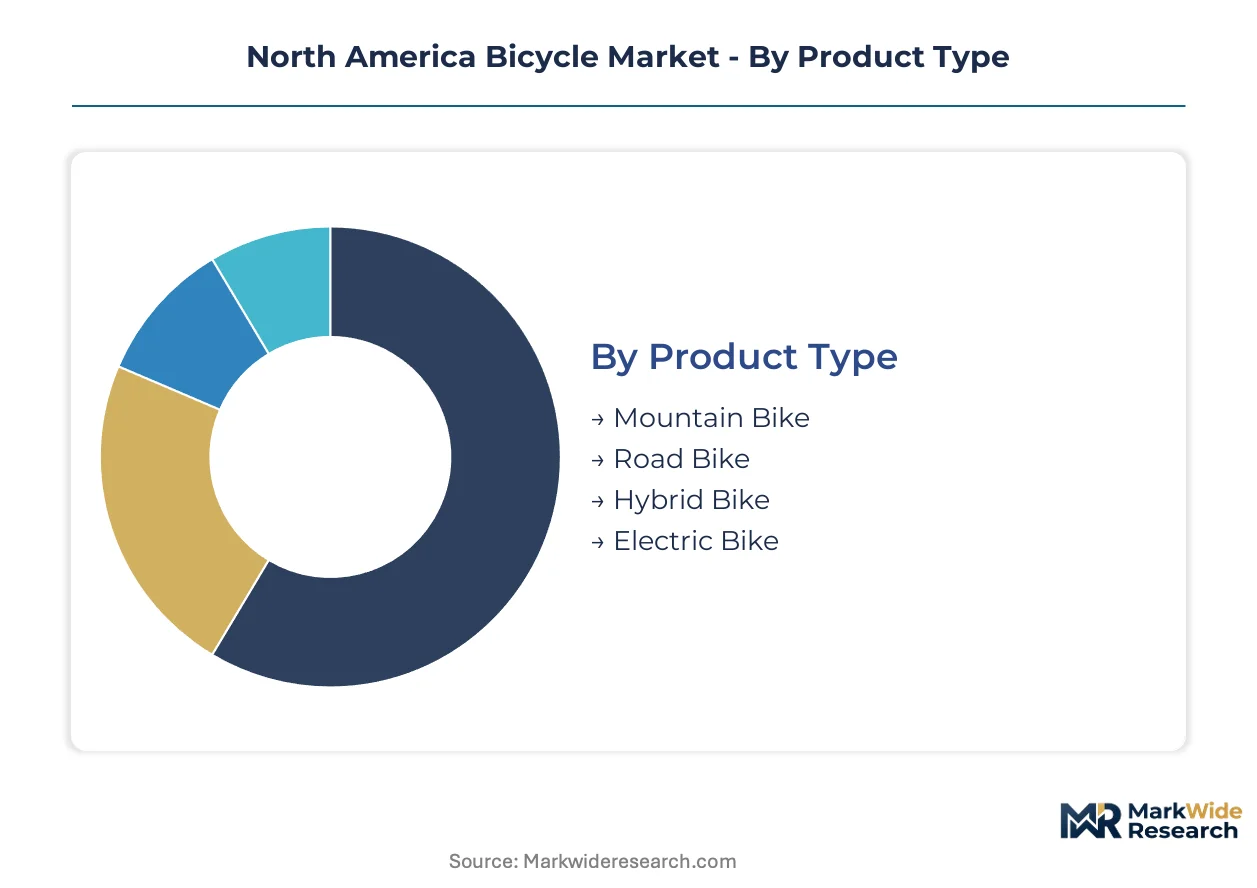
North American bicycle segmentation reveals divergent margin architectures across propulsion technologies and buyer psychographics. Product type and customer type categories dominate strategic resource allocation, while distribution channel and price tier configurations determine working capital intensity and brand positioning latitude.
Product Type:
Frame geometry, drivetrain specification, and motor integration define performance ceilings and maintenance profiles across the four product architectures.
- Mountain Bike:Suspension travel configurations range from hardtail 100mm to full-suspension 170mm systems, with carbon fiber and aluminum alloy frame options dominating the category. Demand concentrates in Colorado Front Range and British Columbia interior markets, where trail network density and elevation terrain sustain replacement cycles at 24-36 month intervals. Technical terrain capability and enduro racing participation drive premium specification uptake.
- Electric Bike:Mid-drive torque-sensing and hub-motor architectures deliver pedal-assist up to 750W under U.S. federal classification, with throttle-assisted variants facing provincial restrictions in Ontario and Quebec. California and British Columbia rebate programs are compressing price differentials against conventional pedal bicycles, accelerating household substitution in dense metropolitan corridors. Battery chemistry and motor efficiency gains are displacing range anxiety as a purchase barrier.
- Road Bike:Drop-bar geometries with carbon fiber or aluminum frames prioritize aerodynamic efficiency and power transfer stiffness for pavement-dedicated riding. Competitive cycling participation and gran fondo event calendars sustain demand in Arizona and Florida winter training markets.
- Hybrid Bike:Flat-bar configurations with moderate tire width and upright positioning balance comfort against efficiency for multi-surface utility riding. Municipal bike-share procurement and entry-level household purchases anchor volume in Midwest urban centers.
Mature deployment sits with Mountain Bike and Road Bike segments. Newer deployment is concentrated in Electric Bike configurations.
Customer Type:
Usage frequency, accessory attachment rates, and replacement cadence vary sharply across rider motivation profiles.
- Urban Commuters:Daily trip volumes exceeding 100 annual days drive accelerated wear-item replacement and higher-margin accessory attachment including lighting, rack, and lock systems. Pacific Northwest and California metropolitan corridors exhibit the highest concentration, where lane infrastructure investments and employer shower facilities sustain all-weather adoption. This cohort purchases replacement frames at 18-24 month intervals, compressing customer lifetime value realization timelines.
- Recreational Users:Weekend and seasonal riding patterns with 20-50 annual trip days characterize this segment, with purchase decisions influenced by trail access proximity and group riding social networks. Colorado and Utah outdoor recreation economies sustain above-average equipment investment per capita.
- Professional Cyclists:Sponsored athletes and elite amateur competitors operate on equipment subsidy or direct purchase models, with frame and component specifications determined by team equipment agreements or individual fit optimization protocols.
- Casual Riders:Irregular usage patterns below 20 annual trip days dominate this segment, with price sensitivity and storage convenience ranking above performance specifications in purchase criteria. Big-box retail channels capture disproportionate share.
Volume concentration rests with Casual Riders. Margin expansion is accelerating fastest among Urban Commuters.
Distribution Channel:
Service capability, inventory depth, and customer acquisition economics differentiate the four channel architectures.
- Specialty Bike Shops:Full-service repair capability and certified fit protocols support premium product positioning and high-attachment accessory sales. Independent dealers in Portland, Denver, and Montreal maintain loyalty through group ride programming and maintenance contract offerings.
- Online Retailers:Direct-to-consumer brands bypass retail markups while capturing subscription-based accessory revenue and remote diagnostic support relationships. Rad Power Bikes and comparable digital-native operators compete aggressively on price against traditional retail channels.
- Department Stores:Mass-market volume placement emphasizes price-point accessibility over technical specification or post-purchase service capability. Seasonal inventory turns concentrate in suburban and exurban trade areas.
- Supermarkets:Impulse and convenience-driven purchases of entry-level children's and adult recreational bicycles dominate this channel, with limited model year depth and no technical service integration.
Service-intensive deployment clusters in Specialty Bike Shops. Volume scaling is concentrating through Online Retailers.
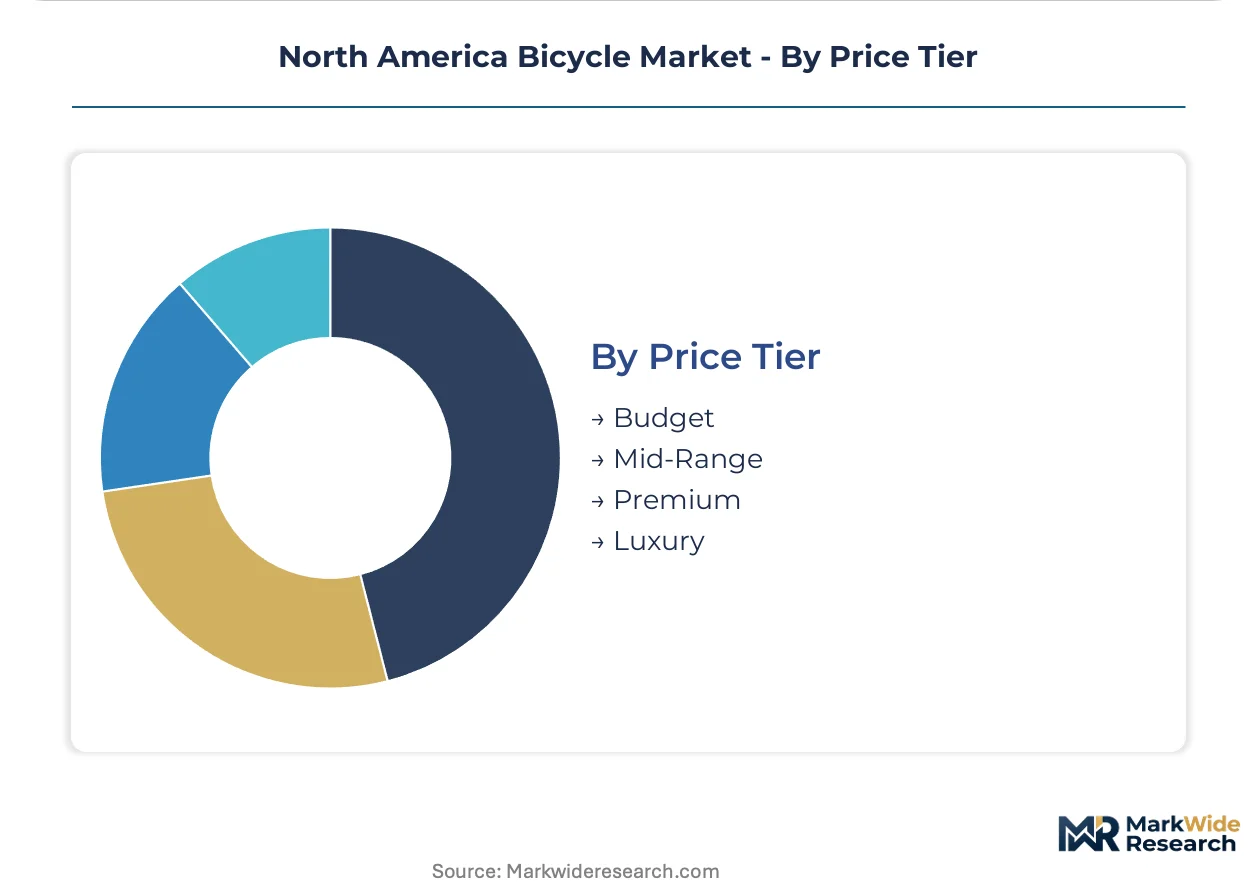
Price Tier:
Component specification, frame material, and brand positioning stratify across four cost bands.
- Premium:Carbon fiber frames, electronic shifting, and branded wheel systems characterize this tier, with Trek and Specialized dominating placement in specialty retail. Professional cyclist endorsement and racing pedigree sustain price positioning.
- Mid-Range:Aluminum frames with mechanical drivetrain and mid-tier wheel specifications capture the largest revenue pool, balancing durability against weight targets for committed recreational users.
- Budget:Steel or entry aluminum frames with basic componentry serve price-sensitive casual riders and children's segments, with department store and supermarket channels capturing dominant share.
- Luxury:Custom frame fabrication, limited edition collaborations, and concierge fitting services define this tier, with annual unit volumes constrained and margin profiles substantially elevated.
Volume deployment centers on Mid-Range specifications. Margin extraction is expanding fastest in Luxury configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Pacific Coast metropolitan corridors where lane infrastructure investment and employer density sustain daily commuter adoption. State-level incentive programs in California and Colorado compress effective price differentials for electric configurations. Provincial initiatives in British Columbia accelerate household substitution in Vancouver and Victoria.
United States
California Clean Vehicle Rebate Project and Colorado e-bike tax credit structures narrow acquisition cost gaps against pedal-only alternatives. The U.S. Consumer Product Safety Commission enforces electrical safety testing protocols that extend product development cycles for battery-integrated systems. Los Angeles, San Francisco, and Denver metropolitan areas exhibit the highest urban commuter concentration, with lane infrastructure commitments hardening route networks.
Canada
Provincial rebate programs in British Columbia and emerging initiatives in Ontario accelerate electric bicycle household penetration. Transport Canada administers Motor Vehicle Safety Act provisions that create classification friction for throttle-assisted versus pedal-assist configurations across distribution channels. Vancouver and Victoria anchor Pacific Northwest demand, while Toronto and Montreal concentrate procurement for municipal bike-share fleet renewal.
Mexico
Urban logistics operators in Mexico City and Guadalajara consolidate volume commitments for cargo-capable bicycles serving last-mile delivery networks. The national consumer protection agency enforces mechanical safety standards for imported bicycles sold through retail channels. Manufacturing assembly clusters in Baja California and central industrial zones supply North American demand with aluminum frame and component production.
North America Bicycle Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer electric specialization and fleet procurement channels. The vendor base stratifies across three tiers: legacy manufacturers with domestic assembly footprints, digital-native brands competing on price transparency, and institutional channel specialists capturing municipal and corporate volume. Strategic archetypes include full-line manufacturers, electric specialists, and fleet-service integrators. Dominant competitive moves encompass point-of-sale incentive program alignment and maintenance-inclusive service contract offerings.
Within the legacy manufacturer tier, Trek Bicycle Corporation and Specialized Bicycle Components anchor premium positioning through specialty retail networks and certified fit protocols. Rad Power Bikes occupies the digital-native electric specialist position, competing aggressively on price against traditional retail channels through direct-to-consumer distribution. Giant Manufacturing Co. represents the scale-driven transnational archetype with integrated frame and component production capabilities.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Specialized Bicycle Components |
| Giant Manufacturing Co. |
| Cannondale Bicycle Corporation |
| Accell Group |
| Pon Bike |
| Schwinn Bicycle Company |
| Rad Power Bikes |
| Aventon |
| Others |
Value Chain & Pricing Dynamics
Aluminum LME spot pricing volatility cascades through North American bicycle manufacturing, compressing mid-tier assembler margins while amplifying cost pass-through capability for vertically integrated frame producers serving premium and luxury tiers.
Pricing Analysis
Volume-midrange specifications anchor revenue pools while luxury configurations extract expanding margins through concierge fitting and limited fabrication. Three-tier pricing structure across premium, standard, and economy levels differentiates by frame material grade and certified safety tier. Cost compression in budget tiers stems from aluminum extrusion input volatility and big-box retail procurement leverage. Casual riders exhibit highest price sensitivity; urban commuters demonstrate lowest elasticity due to lifecycle cost framing and incentive program capture.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese hub-motor and mid-drive system suppliers, where Trek and Specialized source certified electric powertrain subsystems. Frame tubing draws from domestic Midwest extrusion clusters and Mexican Baja California assembly zones. Lithium-ion cell supply hinges on South Korean and Japanese chemistry suppliers. Tariff exposure on Chinese component imports creates margin pressure points. Distribution runs through specialty retail networks for premium positioning and direct-to-consumer channels for price-transparent electric models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
U.S. Consumer Product Safety Commission electrical safety testing protocols function as a cost-of-compliance moat, extending product development cycles and filtering out capital-constrained assemblers unable to absorb four-to-six-month certification timelines.
For Market Incumbents: Acquire certified electric powertrain subsystem suppliers to internalize torque-sensing motor-controller integration and compress development cycles. Consolidate Midwest aluminum extrusion capacity to defend input cost position against logistics bottlenecks. Digital-native brands competing on price transparency threaten traditional retail channel control; counter through maintenance-inclusive service contracts anchoring institutional fleet procurement. For New Entrants and Emerging Players: Interior metropolitan service centers represent an underserved buyer archetype where diagnostic and repair capability for integrated motor-controller systems concentrates on coastal corridors. Municipal bike-share operators in Minneapolis, Portland, and Montreal offer penetrable white-space through belt-drive drivetrain convergence with internal hub gearing. Direct-to-consumer channel maturation with subscription-based accessory attachment revenue provides the most viable go-to-market angle against established retail networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor digital-native electric specialists with direct-to-consumer infrastructure in Colorado and California corridors where state-level rebate programs accelerate household substitution. Long-term viability frames around point-of-sale incentive program alignment and maintenance-inclusive service contract capabilities. Monitor pending federal e-bike tax credit legislation as the signal to watch for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Sale Incentive Alignment | Colorado and California rebate program structures mandate net-after-incentive pricing transparency, accelerating purchase decisions during legislative windows. |
| Maintenance-Inclusive Service Contracts | Institutional channel specialists in Minneapolis and Montreal capture corporate wellness and last-mile logistics volume from traditional independent bicycle dealers. |
| Electric Powertrain Subsystem Integration | Mid-drive torque-sensing motor systems decentralize final assembly decisions, allowing brands to source certified subsystems rather than engineer proprietary integrations. |
| Belt-Drive Drivetrain Convergence | Maintenance-free transmission architectures appeal to municipal bike-share operators seeking reduced field-service overhead in Denver and Vancouver networks. |
| Direct-to-Consumer Channel Maturation | Digital-native brands bypass retail markups while capturing subscription-based accessory attachment revenue and remote diagnostic support relationships. |
Study Parameters
Independent corroboration across bicycle industry executives, municipal procurement officers, and component supplier technical directors underwrites the qualitative findings. Primary fieldwork incorporated discussions with specialty retail operators in Portland and Denver, fleet procurement managers at Chicago and Toronto logistics operators, and regulatory affairs leads navigating U.S. Consumer Product Safety Commission and Transport Canada compliance pathways. Secondary validation drew from U.S. Consumer Product Safety Commission enforcement records, Transport Canada Motor Vehicle Safety Act classification guidance, state-level rebate program documentation in California and Colorado, and municipal lane infrastructure commitment disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns and incentive program uptake curves across the analysis window. The analytical framework modeled volume and value outputs through product type segmentation by propulsion architecture, customer type segmentation by usage frequency and accessory attachment rates, distribution channel segmentation by service capability intensity, and price tier segmentation by frame material and component specification grade. CAGRs were derived from segment-level growth trajectory blending. Forecast inputs incorporated lithium-ion battery cost curve assumptions and municipal infrastructure commitment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal e-bike tax credit legislative passage and evolving provincial classification discrepancies for throttle-assisted versus pedal-assist configurations. Forecasts reflect documented assumptions about incentive program continuity and infrastructure deployment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Motorcycle Filter Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Motorcycle Airbag Market