
 Bicycle Rim Market | 2026-2036
Bicycle Rim Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Rim Market Outlook
Aftermarket service revenue is reshaping margin distribution in the bicycle rim sector, pulling profitability from original equipment toward replacement and upgrade cycles. DT Swiss leverages its Swiss engineering heritage to sustain premium positioning in tubeless-ready road and mountain rim categories. Alexrims competes on manufacturing scale, supplying volume-oriented bicycle manufacturers across Asia with cost-optimized aluminum rims. ENVE Composites specializes in domestic carbon fiber production, anchoring its margin structure through in-house layup facilities in Utah rather than outsourced fabrication.
A bicycle rim is the circular metal or composite structure forming the outer edge of a wheel, typically spanning 559 to 622 millimeters in bead seat diameter depending on discipline, onto which the tire mounts and which transmits rider load through spokes to the hub. The rim maintains tire pressure containment, braking surface integrity or rotor mounting interface, and lateral stiffness under cyclic fatigue across thousands of wheel rotations. Carbon fiber rims command the fastest expansion within material segmentation as riders accept premium pricing for rotational weight reduction and aerodynamic profile optimization. Clincher configurations retain volume leadership among product types due to universal tire compatibility and straightforward roadside repairability, though tubeless adoption accelerates in mountain bike and gravel applications where puncture resistance outweighs initial setup complexity. Road bicycles generate the largest application segment by value, driven by enthusiast upgrade cycles and professional team specification influence.
FDA oversight applies to bicycle rims marketed with medical or therapeutic claims, while ISO 5775 dimensional standards and CEN EN 14781 structural test protocols govern mainstream product safety and market access in Europe and aligned jurisdictions. The EU Green Deal's embodied carbon tracking requirements are pressuring rim manufacturers to document supply chain emissions from bauxite extraction through composite precursor production. Stakeholders must monitor evolving regulatory convergence between consumer product safety and environmental disclosure frameworks to anticipate compliance cost allocation across material and geographic strategies.
Market Dynamics
The bicycle rim sector pivots on the tension between carbon fiber premiumization and aluminum volume manufacturing, with e-bike drivetrain loads forcing structural redesigns that cascade through spoke drilling patterns and brake track specifications.
Growth Catalysts
- E-bike motor torque standards:EN 15194 torque requirements in Europe are mandating reinforced rim beds and higher spoke count configurations, pulling replacement demand from fleet operators upgrading legacy wheelsets.
- Tubeless bead seat technology:Hookless rim profiles with tighter tolerances are capturing share in gravel and mountain applications where sealant reliability outweighs compatibility concerns with legacy tire inventories.
- Zhejiang manufacturing clusters:Jinhua and Yongkang industrial zones anchor global aluminum rim supply, concentrating forging and anodizing capacity that shortens lead times for European and North American assemblers.
Market Restraints
- Carbon fiber precursor cost volatility:Acrylonitrile and pitch-based feedstock prices fluctuate with petrochemical indices, compressing margin stability for composite rim specialists dependent on Toray or Hexcel supply agreements.
- Single-region forging concentration:Taiwan's Taichung Precision Machinery cluster controls 70% of high-end rim extrusion dies, creating bottleneck risk for brands without captive tooling or long-term die reservation contracts.
- Rim brake obsolescence pressure:Disc brake migration in road cycling is stranding rim brake-specific rim inventories and retooling investments, particularly affecting aftermarket retailers with aged stock positions.
Strategic Opportunities
- Indian e-bike subsidy schemes:The PLI scheme for electric mobility is expanding domestic bicycle assembly, creating rim supply partnerships for manufacturers establishing local forging and welding operations in Tamil Nadu and Gujarat.
- EU Green Deal embodied carbon tracking:Mandatory Scope 3 disclosure for bicycle components entering European markets rewards rim producers with documented bauxite-to-finish low-carbon aluminum supply chains.
- Direct-to-consumer wheelset configurators:Online rim and hub selection interfaces with automated spoke length calculation are bypassing traditional distributor tiers, capturing margin previously allocated to regional wholesalers.
Industry Challenges
- Layup technician scarcity:Carbon fiber rim production requires skilled composite laminators capable of managing ply orientation and void elimination, with training pipelines failing to match capacity expansion timelines in Utah and Asian greenfield facilities.
- ISO 5775 revision compliance:Updated bead seat diameter and width tolerances are forcing retooling of rim forming dies and recalibration of quality control gauges, extending new product introduction cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Rim Market |
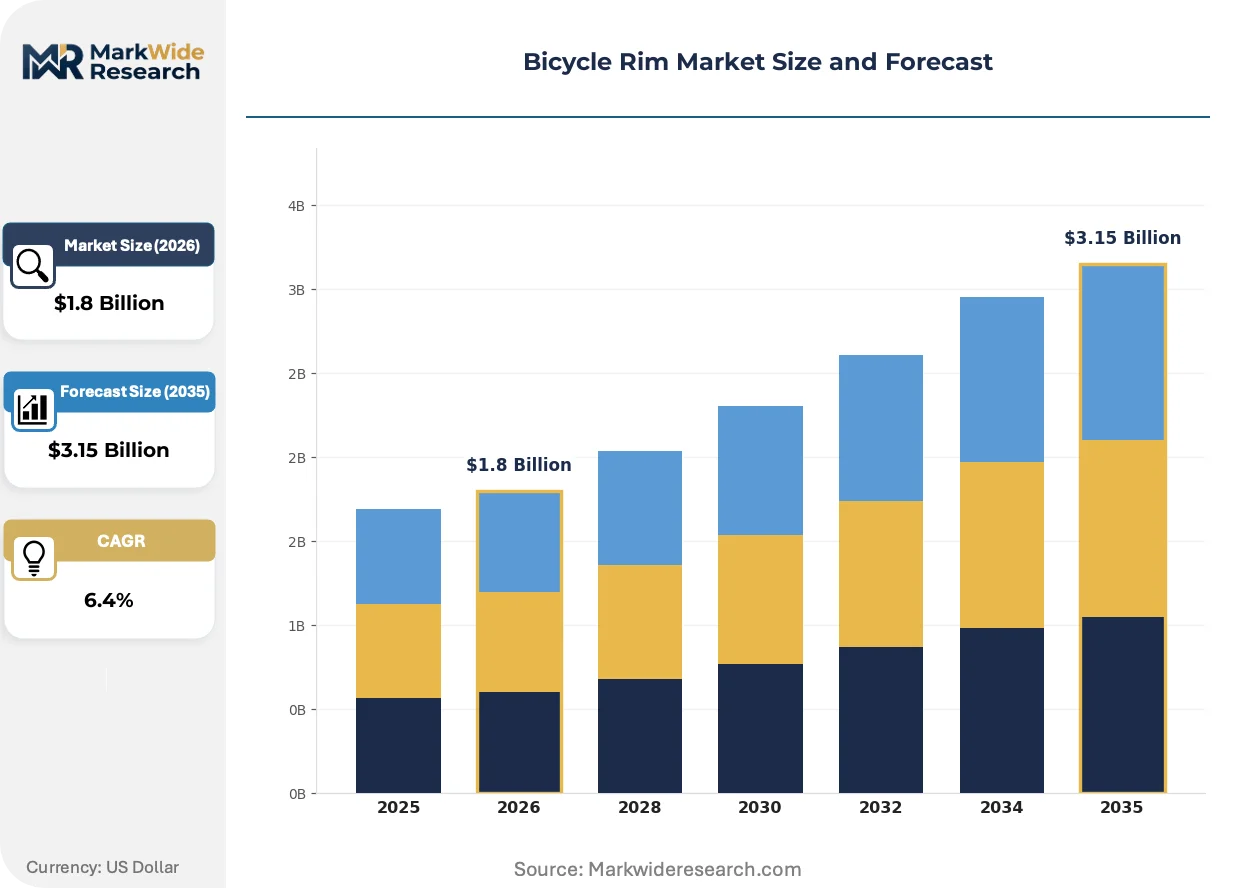
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Steel, Titanium Product Type: Clincher, Tubular, Tubeless, Hookless Application: Road Bicycles, Mountain Bikes, Hybrid Bicycles, BMX Bikes, Track Bikes End User: Professional Riders, Amateur Cyclists, Bicycle Manufacturers, Aftermarket Retailers |
| Companies Covered | Shimano, DT Swiss, Mavic, Campagnolo, SRAM, Fulcrum, ENVE Composites, HED Cycling Products, Alexrims, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Rim Market Strategic Shifts
Active molding processes and automated fiber placement are compressing the cost gap between composite and metal rims, while regulatory pressure on supply chain transparency is reshaping sourcing decisions across tier-one suppliers.
Hookless carbon rim profiles with optimized tire bed radii are rendering obsolete traditional hooked bead designs in performance-oriented road and gravel wheelsets. Professional cycling teams and enthusiast upgrade markets are adopting these configurations despite limited backward compatibility with older clincher tires. The technology is rendering obsolete inventory-heavy distribution models predicated on universal tire compatibility, forcing retailers toward specialized fitting services and compatibility databases.
REACH SVHC candidate list expansion is targeting epoxy resin hardeners and anodizing sealants used in rim finishing, compelling European manufacturers to reformulate surface treatments and bonding agents. Industrial consequence includes accelerated qualification cycles for alternative chemistries and supplier audits extending to Chinese electroplating subcontractors. Road rim producers serving EU markets are most affected, responding with pre-registration of new substance compositions and accelerated migration to powder coating alternatives.
Subscription-based wheelset refresh programs are emerging among direct-to-consumer brands, replacing outright ownership with seasonal upgrade entitlements and inclusive damage replacement. Traditional bike shops and independent wheel builders face disintermediation as these programs capture service revenue and customer data. The model is most visible in German and Dutch urban cycling markets, where e-bike commuters prioritize predictable maintenance costs over capital ownership.
Bicycle Rim Market Segmentation
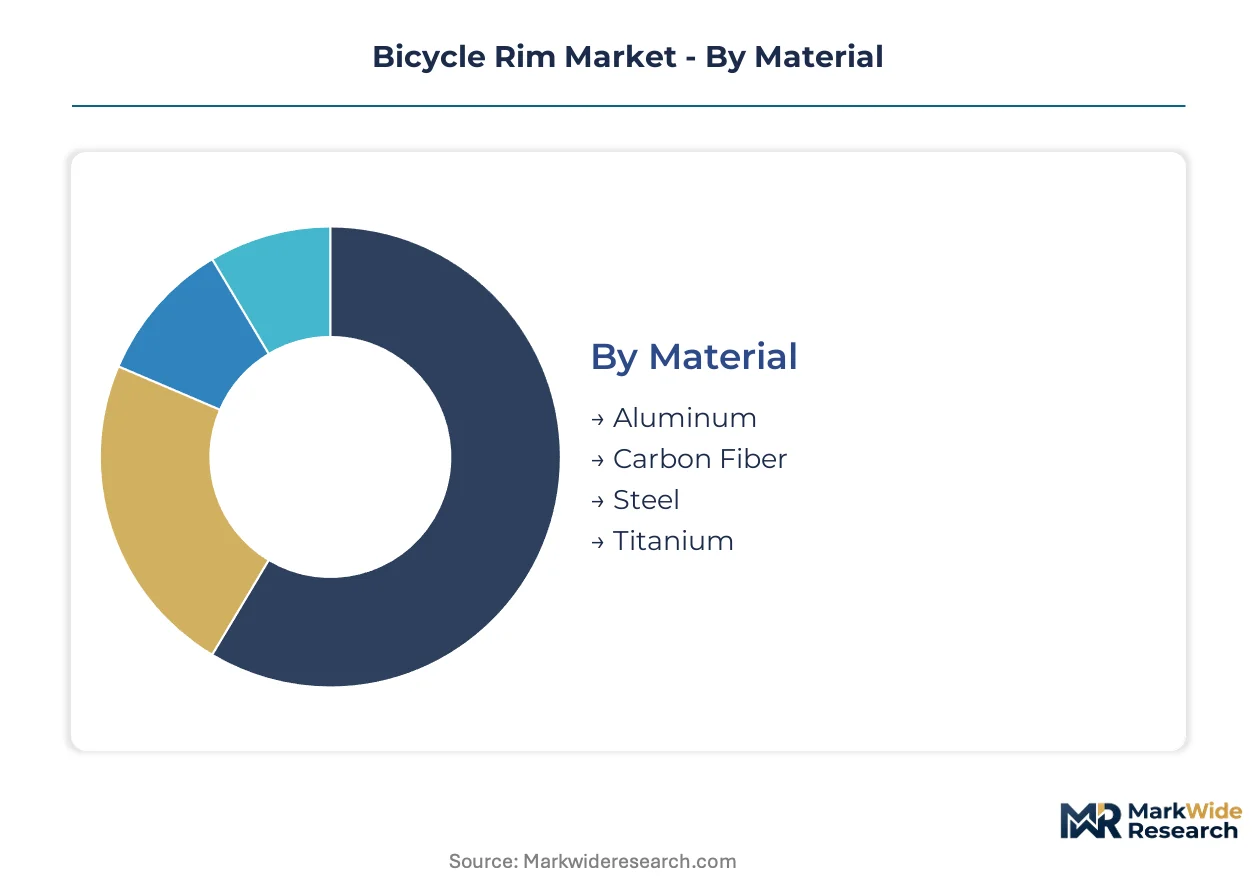
Bicycle rim segmentation determines service revenue capture, upgrade cycle frequency, and inventory risk exposure across replacement channels. Material selection and product type configuration directly influence margin structure and technical support requirements.
Material:
Aftermarket service intensity varies sharply by material, with carbon fiber demanding specialized repair protocols and aluminum enabling rapid field replacement.
- Aluminum:Extruded 6061-T6 or 7005-T6 alloys dominate volume manufacturing through forging and anodizing operations in Zhejiang and Taichung. Demand concentrates among bicycle manufacturers in China and Taiwan seeking cost-optimized supply for mass-market road and hybrid bicycles, constrained by margin compression from energy-intensive smelting and EU Green Deal carbon disclosure requirements.
- Carbon Fiber:Toray T800 and T1000 prepregs form rim beds through bladder molding or active molding processes, yielding 30-50% rotational weight reduction versus aluminum. Demand concentrates in Utah and Asian greenfield facilities serving professional road teams and enthusiast upgrade markets in Germany and the United States, driven by aerodynamic profile optimization and tubeless bead seat compatibility.
- Steel:Chrome-molybdenum construction persists in utility and cargo bicycle applications requiring impact resistance over weight savings.
- Titanium:Cold-worked Ti-3Al-2.5V tubing commands niche positioning in bespoke touring and randonneuring wheelsets.
Aluminum holds the largest share; momentum sits with carbon fiber.
Product Type:
Cost tier stratification separates premium tubeless configurations from economy clincher volumes, reshaping distributor inventory models.
- Clincher:Hooked bead profiles with separate tire and tube systems retain broadest compatibility across legacy inventories and roadside repair scenarios. Demand concentrates among amateur cyclists and aftermarket retailers in North America and Europe prioritizing accessibility over performance optimization.
- Tubeless:Hookless or hooked designs with airtight rim beds eliminate inner tubes through liquid sealant systems. Demand concentrates in mountain bike and gravel applications across Colorado and British Columbia trail networks, driven by puncture resistance requirements under high-impact riding conditions.
- Tubular:Glued tire-rim integration persists in professional road racing where catastrophic failure modes must retain tire attachment.
- Hookless:Optimized tire bed radii with straight sidewalls reduce manufacturing complexity and improve carbon fiber compaction consistency.
Clincher retains volume leadership; tubeless configurations are gaining share fastest.
Application:
Customer type divergence separates fleet procurement patterns from individual enthusiast upgrade behavior.
- Road Bicycles:700C diameter rims with 19-25mm internal widths serve competitive and recreational pavement riding. Demand concentrates in Italian and Spanish cycling clubs where professional team specification influences enthusiast purchasing decisions.
- Mountain Bikes:27.5-inch and 29-inch diameters with 25-35mm widths accommodate high-volume tires and aggressive tread patterns. Demand concentrates in Pacific Northwest and Alpine European markets where technical trail access drives wheelset durability requirements.
- Hybrid Bicycles:Moderate width configurations balance pavement efficiency with light off-road capability.
- BMX Bikes:20-inch and 24-inch diameters with reinforced sidewalls withstand repeated impact loading.
- Track Bikes:Tubular-specific high-profile rims optimize aerodynamics for velodrome competition.
Road bicycles command the highest value concentration; mountain bikes show the steepest expansion trajectory.
End User:
Supply concentration in manufacturing clusters shapes procurement patterns across OEM and replacement channels.
- Professional Riders:UCI team equipment sponsors specify rim models subject to structural certification and aerodynamic validation protocols. Demand concentrates through direct manufacturer relationships with WorldTour squads based in Belgium and Switzerland.
- Amateur Cyclists:Upgrade cycles follow event calendars and seasonal fitness peaks, with purchasing concentrated through German and Dutch specialty retailers.
- Bicycle Manufacturers:Frame assembly operations in Shenzhen and Dongguan source rim batches against production schedules with 90-120 day lead times.
- Aftermarket Retailers:Independent bike shops and online configurators manage inventory risk across multiple rim widths and brake interfaces.
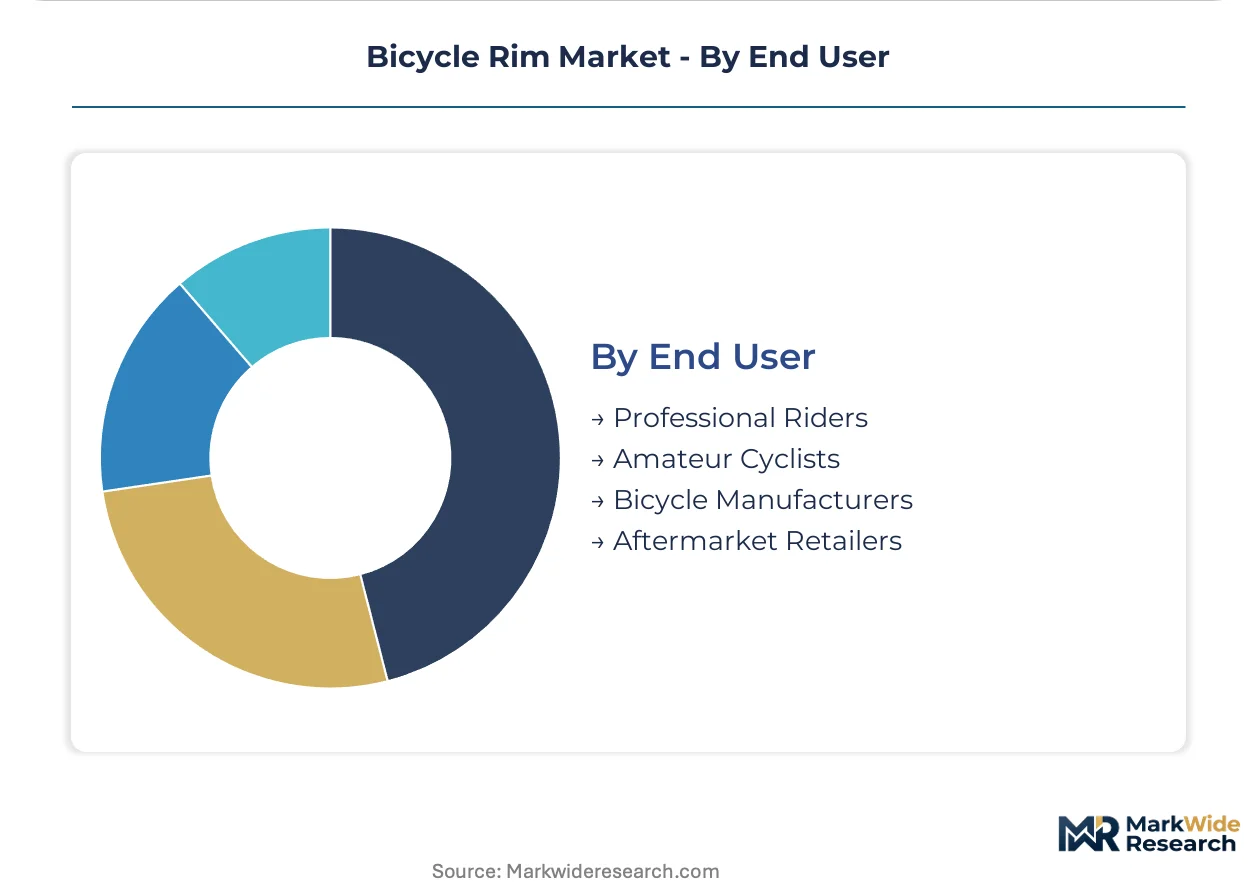
Bicycle manufacturers represent the largest procurement volume; aftermarket retailers are expanding their share of replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for bicycle rims diverges sharply across markets: European and North American enthusiasts absorb premium carbon fiber pricing, while Asian mass-market procurement prioritizes aluminum cost optimization above performance metrics.
China
E-bike fleet expansion and export-oriented OEM supply dominate rim demand, with Zhejiang province's Jinhua and Yongkang industrial zones concentrating forging, anodizing, and extrusion capacity. MIIT industrial standards govern e-bike component safety certification. Domestic manufacturers in these clusters supply rim batches to European and North American assemblers on 60-90 day compressed lead times.
Germany
Gravel and road cycling upgrade cycles drive premium rim replacement, with enthusiast purchasing concentrated through specialty retailers in Bavaria and Baden-Württemberg. EU Green Deal embodied carbon disclosure requirements pressure distributors to document supply chain emissions from bauxite extraction through finishing. The KBA maintains type-approval oversight for e-bike system integration affecting rim structural specifications.
United States
Mountain bike trail networks in Colorado and the Pacific Northwest generate tubeless rim demand prioritizing puncture resistance over weight minimization. FDA oversight applies to rims marketed with therapeutic or medical claims. Utah hosts domestic carbon fiber layup facilities serving professional teams and enthusiast markets with in-house manufacturing rather than outsourced fabrication.
India
PLI scheme subsidies for electric mobility are expanding domestic bicycle assembly, creating rim supply partnerships for manufacturers establishing forging operations in Tamil Nadu and Gujarat. BIS standards govern component safety and dimensional compliance for domestic market access. Industrial clusters in these states are attracting rim welding and finishing investments from Taiwanese and Chinese suppliers seeking tariff-advantaged production.
Switzerland
Professional team specification influence and Swiss engineering heritage sustain premium positioning in tubeless-ready road and mountain categories. Swissmedic maintains medical device oversight for rims with therapeutic marketing claims. Geneva and Zurich metropolitan areas concentrate wheel system R&D and structural validation facilities serving WorldTour squad equipment sponsors.
Bicycle Rim Market Competitive Environment
Capability concentration sits with composite specialists commanding aerodynamic optimization and layup expertise; scale advantage sits with aluminum extrusion houses serving volume bicycle manufacturers. The vendor base stratifies across three tiers: integrated component groups, standalone rim specialists, and contract forging operations. Structural consolidation remains limited, with competitive intensity expressed through die reservation contracts, spoke drilling pattern patents, and direct-to-consumer configurators bypassing distributor tiers.
Among Swiss-heritage engineering specialists, DT Swiss exemplifies premium-tier positioning through tubeless-ready system integration. ENVE Composites anchors domestic carbon fiber production archetypes with in-house Utah layup facilities rather than outsourced Asian fabrication. Alexrims occupies the scale-driven contract supply tier, serving volume-oriented bicycle manufacturers from Zhejiang-based extrusion and anodizing operations.
| Leading Market Players |
|---|
| Shimano |
| DT Swiss |
| Mavic |
| Campagnolo |
| SRAM |
| Fulcrum |
| ENVE Composites |
| HED Cycling Products |
| Alexrims |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Zhejiang forging operations is compressing spot aluminum pricing while elevating carbon fiber premiums, forcing manufacturers to choose between volume scale and margin protection. This utilization divergence rewards rim producers with captive composite layup facilities and stranded asset risk for pure-play aluminum extruders.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture through wheelset refresh subscriptions and damage replacement entitlements. Three-tier pricing structure across premium carbon, standard aluminum, and economy OEM-supply tiers separates DT Swiss and ENVE from Alexrims and contract forging houses. Cost compression in aluminum spot markets is intensifying because energy-intensive smelting faces EU Green Deal carbon disclosure requirements. Amateur cyclists in German and Dutch specialty retail channels show highest price sensitivity; professional team equipment sponsors absorb premium carbon fiber pricing without volume negotiation.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for high-end rim brands dependent on Taichung Precision Machinery cluster die access. Production concentrates in China's Zhejiang province, Taiwan's Taichung industrial zone, and Utah's domestic carbon fiber facilities. Raw material flows draw from Toray T800/T1000 prepreg supply, 6061-T6 aluminum billet, and acrylonitrile-based carbon precursors. Single-source vulnerability sits with Taiwan's 70% control of high-end extrusion die capacity. Distribution runs through direct-to-consumer configurators, European specialty retailers, and Shenzhen-based OEM procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle rim sector is accelerating through e-bike torque standard disruption, with EN 15194 compliance forcing structural redesigns that obsolete legacy inventory and create replacement cycle pull-through.
For Market Incumbents: Insulate margin structure through backward integration into carbon fiber prepreg supply or captive forging capacity reservation in Jinhua clusters. Defend against direct-to-consumer configurators by controlling spoke drilling pattern IP and tubeless bead seat tolerance specifications that require specialized fitting services. For New Entrants and Emerging Players: Build out Indian rim forging partnerships under PLI scheme subsidies, targeting Tamil Nadu and Gujarat assembly operations seeking tariff-advantaged supply. White-space opportunity concentrates in gravel-specific hookless carbon profiles where professional team specification influence has not yet locked in incumbent relationships. Go-to-market angle: compatibility databases and automated spoke length calculation tools that bypass traditional distributor tiers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with subscription-based wheelset refresh programs. Long-term viability favors composite specialists with in-house layup facilities over aluminum extrusion houses exposed to energy cost volatility and carbon disclosure compliance burdens. Acquisition target archetype: Utah-based carbon fiber rim producers with documented low-carbon supply chains qualifying for EU Green Deal preferential market access. Signal to watch: ISO 5775 revision implementation timelines that extend new product introduction cycles and consolidate advantage among pre-compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Prepreg Supply | Toray supply agreement capture insulates margin against acrylonitrile price volatility. |
| Direct-to-Consumer Configurator Launch | Automated spoke length calculation bypasses distributor margin capture in German and Dutch markets. |
| EU Green Deal Supply Chain Documentation | Bauxite-to-finish carbon disclosure qualifies rims for preferential procurement by European assemblers. |
| Hookless Rim Profile Patent Filing | Tubeless bead seat IP blocks competitor entry in gravel and mountain applications. |
| Indian Forging Joint Venture | PLI scheme access in Tamil Nadu creates tariff-advantaged supply for domestic e-bike assembly. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wheel system R&D directors, aftermarket service managers at specialty retailers, carbon fiber layup technicians, and OEM procurement officers in Shenzhen and Dongguan. Secondary validation drew from MIIT industrial standards filings, EU Green Deal technical documentation, ISO 5775 revision drafts, and customs trade data for aluminum rim exports. Bottom-up triangulation against top-down production capacity estimates anchored volume and value assessments.
Calibration against historical replacement cycle patterns and e-bike fleet expansion trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material tier, product type configuration, application discipline, and end-user procurement channel. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization assumptions. Industry-specific inputs incorporated EN 15194 torque load specifications and REACH SVHC candidate list impacts on surface treatment chemistry.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer entrants or carbon fiber composite specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Wheel Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market