
 Tire Changers Market | 2026-2036
Tire Changers Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Changers Market Outlook
Equipment leasing and pay-per-use service models is reconfiguring capital deployment for smaller automotive workshops, lowering barriers to automated tire service adoption. Hunter Engineering Company leverages its vertical integration into wheel alignment systems to sustain premium positioning. Ravaglioli anchors its competitiveness through specialized Italian manufacturing of high-precision changer platforms. Snap-on Incorporated controls distribution density through its captive franchise network of mobile tool and equipment dealers.
Tire changers are electromechanical machines designed to remove and mount tires onto wheel rims, typically operating at clamping forces between 800 and 2,200 pounds depending on vehicle class, with fully automatic variants integrating robotic bead breaking and laser-guided rim profiling to service passenger, commercial, and off-road applications. The fully automatic product segment leads value generation as fleet operators and high-volume tire retailers prioritize throughput and technician safety, while the wheel-lift sub-category captures expanding demand from electric vehicle service bays handling heavier wheel assemblies. Among end users, fleet service providers represent the fastest-growing demand pool as logistics companies internalize tire maintenance to minimize commercial vehicle downtime.
OSHA machine guarding standards, EU machinery directives requiring CE marking, and ISO 9001 quality management frameworks collectively elevate compliance costs for equipment manufacturers while creating specification advantages for certified suppliers. Germany's KBA type-approval requirements for commercial vehicle service equipment further tighten market access for non-compliant imports. Stakeholders must monitor how evolving EV wheel architectures and torque specifications reshape changer design requirements.
Market Dynamics
Fleet operators are internalizing tire maintenance operations to compress commercial vehicle downtime, redirecting equipment procurement from independent service shops toward centralized logistics hubs with volume-based automation requirements.
Growth Catalysts
- OSHA machine guarding mandates:Workplace safety enforcement in the US is compelling fleet operators to replace manual changers with automated variants featuring interlocked guards and emergency stops.
- Electric vehicle wheel architectures:Heavier EV wheel assemblies with unique torque specifications are generating replacement demand for wheel-lift equipped changers in service bays.
- Germany's automotive service corridor:Concentrated OEM and aftermarket activity around Stuttgart and Munich is anchoring premium equipment demand for high-precision changer platforms.
Market Restraints
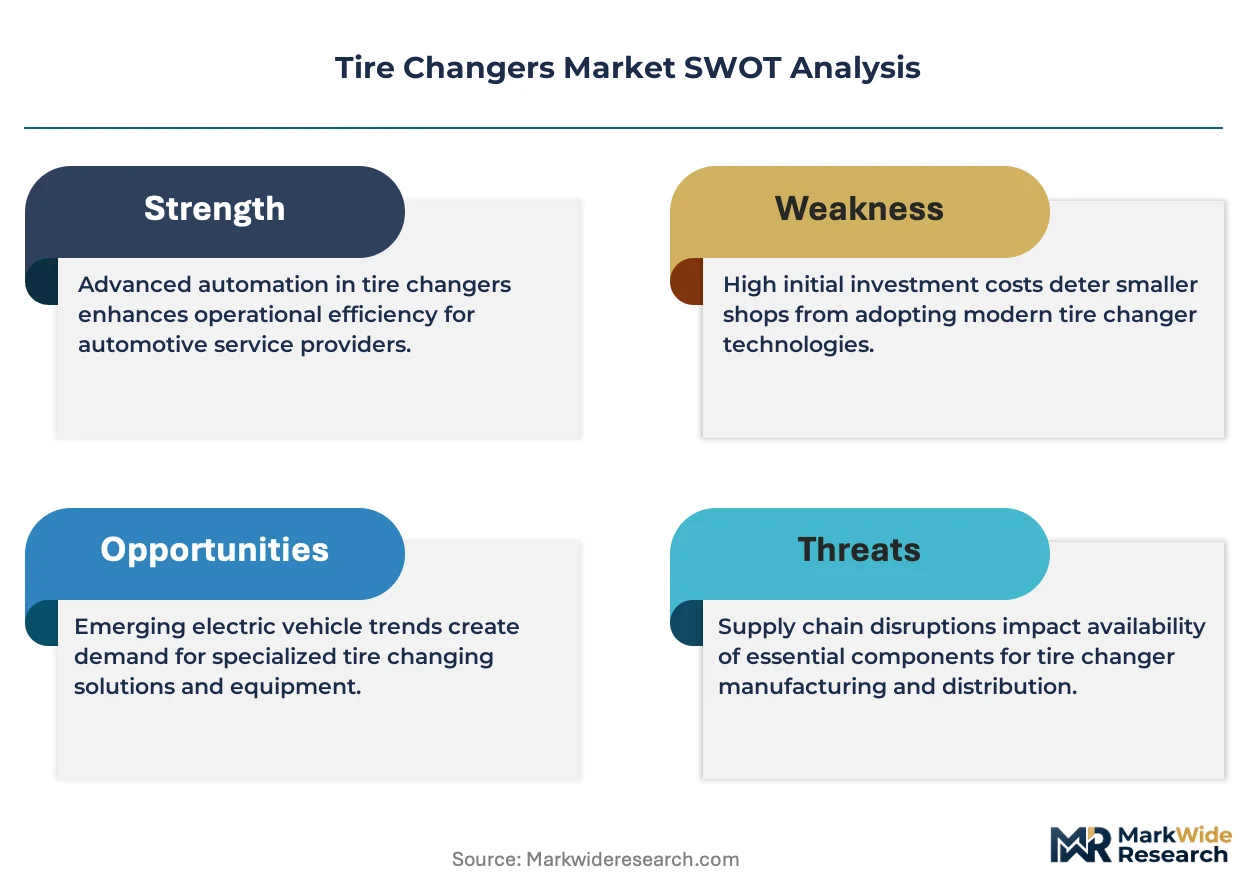
- CE marking compliance costs:EU machinery directives impose extensive documentation and testing burdens on non-European manufacturers seeking market access.
- Steel and aluminum price volatility:Fluctuating raw material costs for changer frames and clamping mechanisms compress margin stability for equipment producers.
- Specialized technician scarcity:Shortages of trained personnel capable of servicing electromechanical and robotic changer systems constrain deployment velocity.
Strategic Opportunities
- Pay-per-use service models:Equipment-as-a-service financing is unlocking smaller automotive workshops previously excluded from automated tire service adoption.
- India's commercial vehicle fleet expansion:Logistics infrastructure buildout is creating first-mover positioning for automated changer suppliers in emerging fleet maintenance networks.
- ISO 9001 certification differentiation:Quality management framework compliance is becoming a procurement filter, favoring certified suppliers in competitive tenders.
Industry Challenges
- Integration complexity with legacy shop management systems:Automated changers require API connectivity and data exchange protocols that many independent service bays lack.
- KBA type-approval timelines:Germany's commercial vehicle equipment certification process creates extended go-to-market delays for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Changers Market |
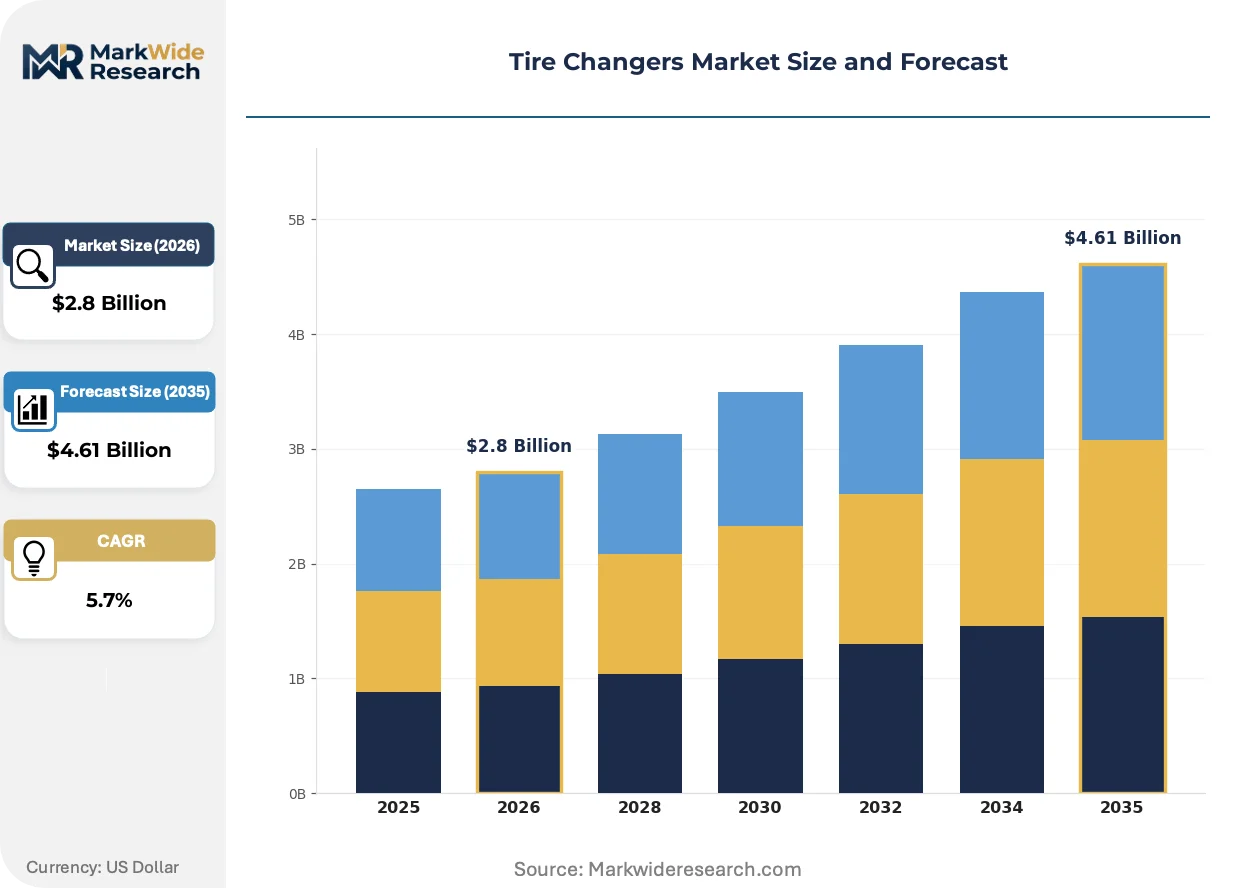
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Wheel-Lift End User: Automotive Workshops, Service Stations, Tire Retailers, Fleet Service Providers Technology: Hydraulic, Pneumatic, Electric, Mechanical Size: Compact, Standard, Heavy-Duty, Portable |
| Companies Covered | Snap-on Incorporated, Hunter Engineering Company, Ravaglioli, Corghi S.p.A., Giuliano Industrial S.p.A., CEMB S.p.A., Bosch Automotive Service Solutions Inc., Atlas Automotive Equipment, LAUNCH TECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Changers Market Strategic Shifts
Robotic bead breaking and laser-guided rim profiling are compressing service cycle times while elevating technician safety standards across high-volume tire operations.
Laser-guided rim profiling systems are collapsing the skill gap required for damage-free tire mounting on expensive alloy wheels. Premium tire retailers and luxury vehicle service centers are adopting these systems at accelerated replacement cycles. The technology is collapsing the historical trade-off between throughput speed and wheel protection quality.
EU machinery directives mandating CE marking for electromechanical service equipment are elevating documentation and conformity assessment burdens. Non-European manufacturers face extended market entry timelines and third-party testing costs. Commercial vehicle service equipment categories are experiencing the most acute compliance pressure, with German KBA requirements adding national layers.
Buyer concentration among national fleet operators is consolidating procurement authority away from distributed independent shops. Large logistics companies are establishing direct equipment supply relationships with manufacturers, bypassing traditional distributor networks. This pattern is most visible in North American long-haul trucking and last-mile delivery fleet operations.
Tire Changers Market Segmentation
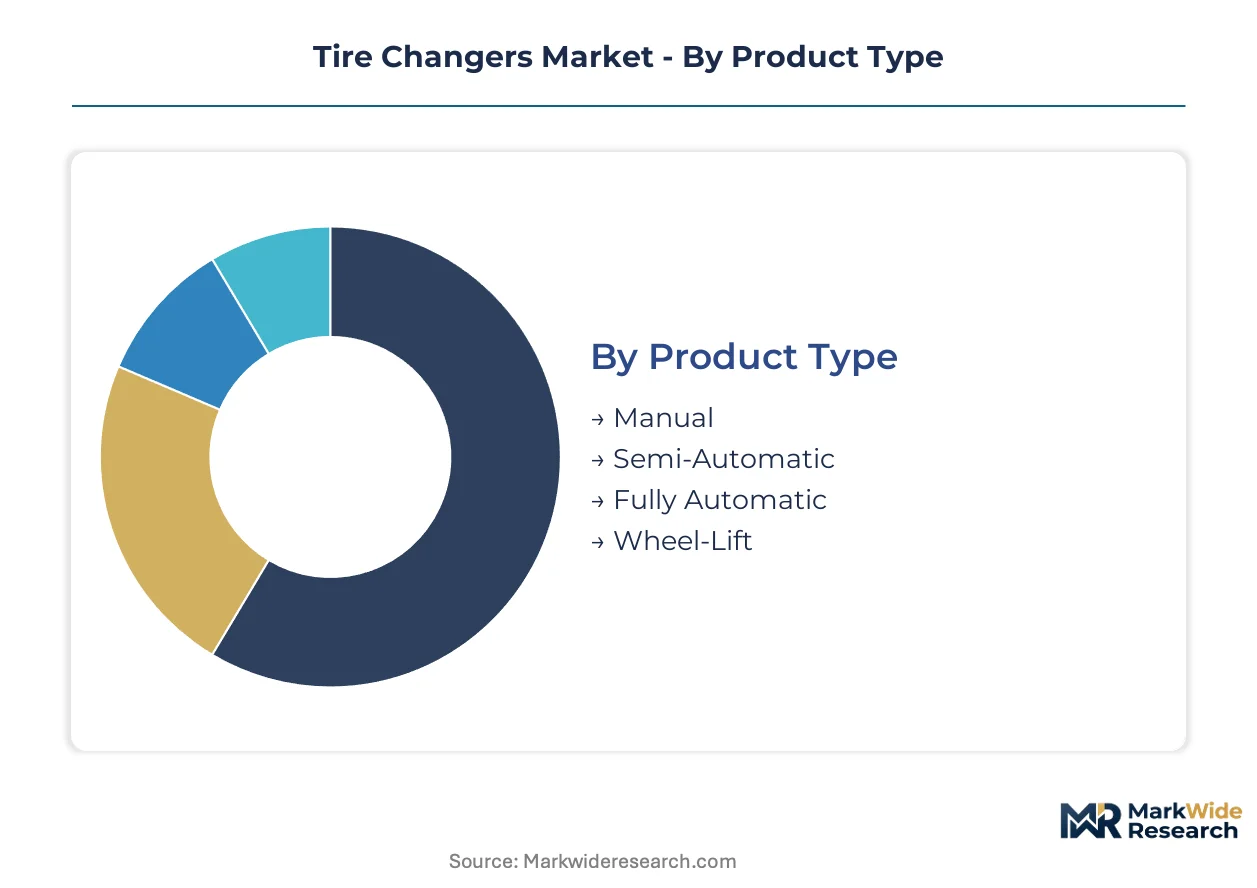
Tire changer segmentation reveals how equipment specifications align with distinct operational intensities and capital constraints across the service landscape. Each dimension captures a different axis of buyer decision-making, from throughput requirements to bay space limitations.
Product Type:
Use-case spectrum spans from occasional repair shops to high-volume fleet hubs with radically different automation needs and payback expectations.
- Fully Automatic:Robotic bead breaking and laser-guided rim profiling deliver sub-90-second cycle times with minimal technician intervention. Fleet operators and high-volume tire retailers concentrate procurement here, driven by OSHA workplace safety mandates and technician shortage pressures.
- Wheel-Lift:Integrated lifting mechanisms handle EV wheel assemblies weighing 30-50% more than conventional equivalents, with torque-calibrated clamping sequences preventing damage to battery-integrated hubs. Demand clusters in electric vehicle service bays across Germany's automotive corridor and North American fleet maintenance networks.
- Semi-Automatic:Technician-assisted operation balances capital outlay with productivity gains for mid-volume independent shops.
- Manual:Basic mechanical designs persist in developing markets and ultra-low-volume rural service points.
The dominant share belongs to Fully Automatic, while Wheel-Lift is closing the gap fastest.
End User:
Procurement authority is migrating toward centralized buyers with volume-based automation requirements and captive maintenance operations.
- Fleet Service Providers:Logistics companies internalizing tire maintenance to compress commercial vehicle downtime drive specifications for 24/7 operational durability and remote diagnostic connectivity. North American long-haul trucking operators and European last-mile delivery networks anchor this segment's expansion.
- Tire Retailers:High-throughput chains prioritize rapid customer turnaround and wheel damage prevention on expensive alloy rims, accelerating replacement cycles for laser-guided profiling systems.
- Automotive Workshops:General repair facilities balance equipment versatility against bay space constraints, favoring compact multi-function configurations.
- Service Stations:Fuel-retail integrated maintenance bays focus on passenger vehicle speed service with standardized wheel sizes.
Fleet Service Providers command the largest procurement volumes, while Tire Retailers are expanding equipment density most aggressively.
Technology:
Power transmission architecture determines maintenance burden, energy efficiency, and precision control capabilities across operating environments.
- Electric:Servo-motor actuation delivers programmable clamping force curves and regenerative energy recovery, aligning with fleet sustainability targets and precision requirements for low-profile performance tires. ISO 9001-certified manufacturers capture specification advantages in competitive tenders.
- Hydraulic:High-force density suits heavy-duty commercial vehicle applications with sustained 2,200-pound clamping requirements and extreme duty cycles.
- Pneumatic:Compressed air systems dominate legacy shop infrastructures with existing compressor investments.
- Mechanical:Direct mechanical linkages persist in manual and entry-level semi-automatic designs for cost-sensitive procurement.
Electric systems are gaining specification share fastest, though Hydraulic retains dominance in heavy-duty commercial applications.
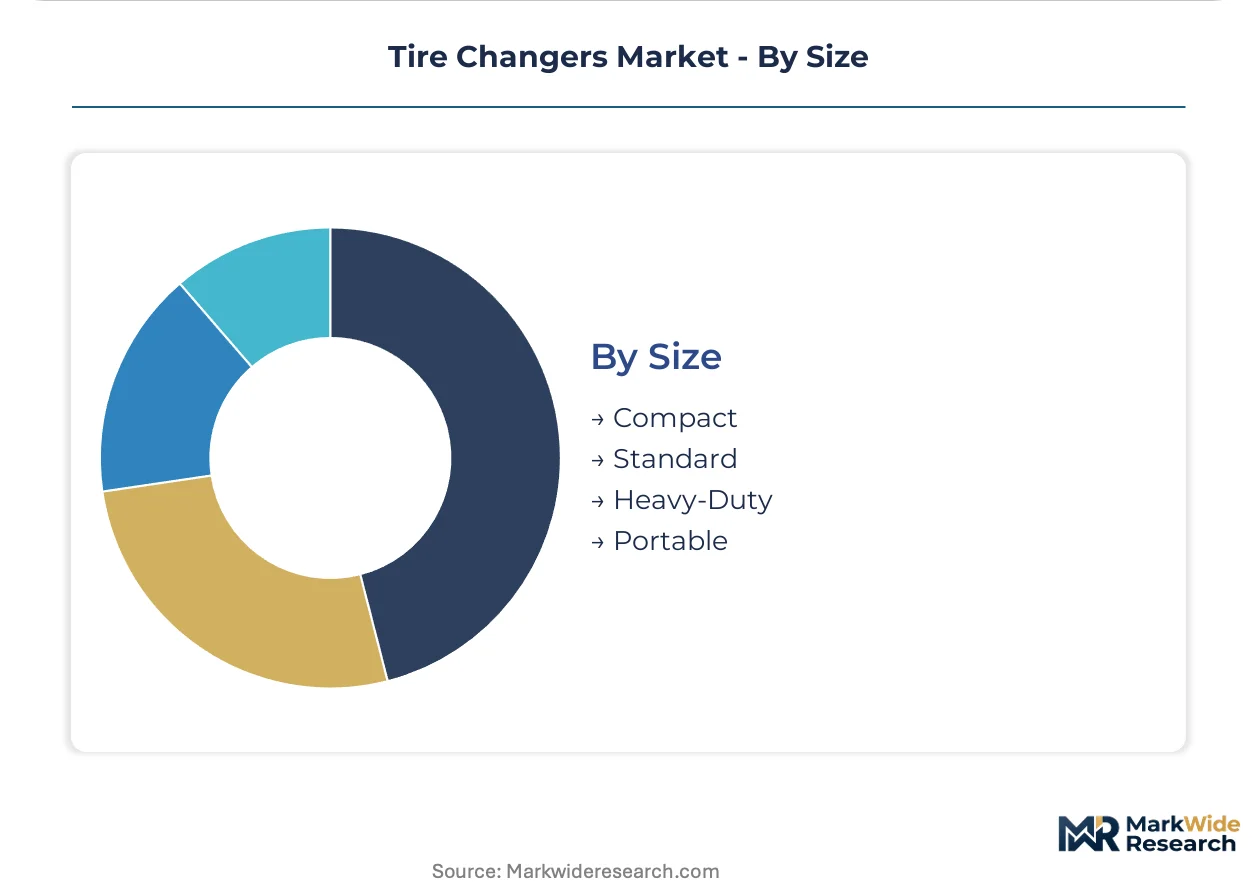
Size:
Physical footprint constraints and vehicle class coverage define bay configuration decisions across service facility types.
- Heavy-Duty:Reinforced frames and extended clamping ranges accommodate commercial truck, bus, and off-road equipment wheels up to 56 inches in diameter. Germany's KBA type-approval requirements for commercial vehicle service equipment filter procurement toward certified platforms.
- Standard:Passenger and light-truck coverage represents the volume baseline for general automotive service.
- Compact:Space-constrained urban workshops and mobile service operations prioritize minimal footprint configurations.
- Portable:Field service and emergency roadside applications demand battery-powered or manually operated units without fixed installation.
Standard configurations maintain the broadest installed base, while Heavy-Duty is climbing the fastest on fleet internalization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows favor established manufacturing bases in Germany, Italy, and the United States, while import-dependent markets in India and Brazil absorb automated changer platforms to serve expanding commercial vehicle fleets.
United States
Fleet operators across Texas and California are internalizing tire maintenance to compress commercial vehicle downtime. OSHA machine guarding mandates compel replacement of manual changers with automated variants featuring interlocked guards. The I-95 logistics corridor anchors procurement concentration for high-throughput equipment serving long-haul trucking networks.
Germany
Stuttgart and Munich anchor premium demand for high-precision changer platforms serving OEM and aftermarket service networks. KBA type-approval requirements for commercial vehicle service equipment filter procurement toward certified suppliers. The automotive service corridor concentrates specification authority for laser-guided rim profiling systems.
Italy
Specialized manufacturing of high-precision changer platforms concentrates in Emilia-Romagna's industrial machinery belt. CE marking compliance under EU machinery directives elevates documentation burdens for equipment exports. Italian fabricators leverage ISO 9001 certification to capture specification advantages in competitive tenders across European markets.
China
Domestic production of electromechanical changers scales to serve logistics infrastructure buildout and electric vehicle service bay expansion. GB standards and MIIT regulations shape equipment safety and quality benchmarks. The Yangtze River Delta concentrates manufacturing capacity for both domestic deployment and export to Southeast Asian markets.
India
Commercial vehicle fleet expansion drives first-mover positioning for automated changer suppliers in emerging maintenance networks. BIS certification requirements and PLI scheme incentives shape equipment import and local assembly decisions. Maharashtra and Gujarat anchor logistics infrastructure buildout creating concentrated demand for heavy-duty service equipment.
Tire Changers Market Competitive Environment
On the supply side, the industry is moderately consolidated around specialized machinery fabricators with deep vertical integration into wheel service ecosystems. Equipment producers cluster into three strategic archetypes: integrated automotive service conglomerates, dedicated tire machinery specialists, and diversified industrial equipment manufacturers. Competitive moves center on captive distribution network expansion and precision manufacturing capability acquisition.
Within the premium-tier vector, Hunter Engineering Company and Snap-on Incorporated exemplify integrated service equipment positioning. Ravaglioli and Corghi S.p.A. represent Italian specialist fabricators with concentrated expertise in high-precision changer platforms. LAUNCH TECH occupies a position among Asia-Pacific-scale equipment producers serving volume markets.
| Leading Market Players |
|---|
| Snap-on Incorporated |
| Hunter Engineering Company |
| Ravaglioli |
| Corghi S.p.A. |
| Giuliano Industrial S.p.A. |
| CEMB S.p.A. |
| Bosch Automotive Service Solutions Inc. |
| Atlas Automotive Equipment |
| LAUNCH TECH |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta manufacturing belt is pressuring OEM pricing discipline while compressing margin buffers for European precision fabricators, forcing suppliers to differentiate through certification tiers rather than volume scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 9001 certification and CE marking compliance commanding 15-25% premiums over uncertified alternatives. Price differentiation hinges on laser-guided rim profiling precision and after-sales service bundling, while fleet operators with captive maintenance networks exhibit the lowest price sensitivity due to downtime cost calculus. Cost compression in the economy tier is intensifying because of Chinese import competition, though German KBA type-approval requirements filter out non-compliant low-cost entrants from commercial vehicle segments.
Supply Chain Analysis
Export-control restrictions on servo-motor and precision sensor technologies limit component flows from certain jurisdictions, constraining supply flexibility for electric tire changer platforms. Manufacturing concentrates in Germany, Italy, and China, with steel and aluminum frame fabrication drawing from domestic metalworking bases in each region. Single-source vulnerability persists for high-torque servo drives sourced from Japanese and German suppliers, while distribution runs through captive franchise networks for integrated equipment conglomerates and independent industrial distributors for specialist fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory certification entrenchment and high switching costs protect incumbent positions against price-based disruption.
For Market Incumbents: Entrench market position by deepening backward integration into wheel alignment and diagnostic systems, creating bundled service ecosystems that raise rival replacement costs. Acquire specialized Italian precision fabricators to capture laser-guided rim profiling IP and block emerging Asian competitors from premium tier access. Prioritize KBA and CE marking certification maintenance as regulatory moats against low-cost import erosion. For New Entrants and Emerging Players: India's commercial vehicle fleet expansion offers first-mover positioning in automated heavy-duty changer deployment, with logistics infrastructure buildout outpacing domestic equipment supply. Target pay-per-use service models for capital-constrained independent workshops previously excluded from automated adoption, leveraging equipment-as-a-service financing to bypass upfront procurement barriers. Pursue ISO 9001 certification as table stakes for European tender participation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet service providers with captive maintenance networks and long-term equipment service agreements, offering visibility across extended holding periods. Target acquisition profiles should prioritize Italian specialist fabricators with concentrated high-precision manufacturing expertise and established CE marking compliance. Monitor EV wheel architecture standardization as the critical inflection signal for wheel-lift equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheel Alignment Systems | Hunter Engineering leverages captive supply of diagnostic platforms to bundle tire service equipment and raise rival replacement costs. |
| CE Marking and KBA Certification Investment | Italian fabricators capture specification advantages in German commercial vehicle tenders through dual regulatory compliance. |
| Pay-per-Use Service Model Deployment | Equipment-as-a-service financing unlocks smaller automotive workshops previously excluded from automated tire changer adoption. |
| Laser-Guided Rim Profiling R&D Expansion | Premium tire retailers accelerate replacement cycles for damage-prevention systems serving expensive alloy wheel segments. |
| India Commercial Vehicle Fleet Partnership | First-mover suppliers anchor automated changer positioning in Maharashtra and Gujarat logistics infrastructure buildout. |
Study Parameters
Operator-level perspectives from fleet maintenance directors, automotive workshop owners, OEM procurement teams, and aftermarket service heads anchored the qualitative base, combined with secondary validation from SEC equipment manufacturer filings, EU machinery directive documentation, OSHA enforcement databases, and customs trade flow records. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, technology, and size segmentation dimensions.
Scenario-bracketing framed volume and value outputs across the analysis window, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Modeled dimensions span fully automatic through manual product tiers, fleet service provider through service station end users, and electric through mechanical technology architectures. EV wheel weight specifications and OSHA machine guarding mandate enforcement timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by Chinese electromechanical producers would shift outcomes beyond modeled ranges. Material shifts in EU machinery directive enforcement intensity or EV wheel torque standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Automotive Alloy Wheels Market