
 Industrial Tire Market | 2026-2036
Industrial Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Tire Market Outlook
Skilled compound formulation chemists is reorganizing how manufacturers scale production of heat-resistant industrial tire blends. Michelin leverages captive rubber plantations in Southeast Asia to secure natural supply chains. Bridgestone anchors its position through advanced robotics in Japanese production facilities. Continental differentiates via integrated sensor systems embedded in pneumatic tire architectures.
Industrial tires are reinforced rubber structures engineered to carry loads from 2,000 to over 100,000 pounds while operating on unpaved surfaces, concrete floors, or mining haul roads, with tread compounds formulated from natural rubber, synthetic polyisoprene, and carbon black fillers to resist cutting, heat buildup, and abrasion under sustained duty cycles. Their primary purpose is to maintain vehicle stability, traction, and load distribution in material-handling equipment where downtime costs exceed tire replacement expenses by orders of magnitude. Pneumatic tires occupy the dominant revenue position across construction and mining applications where shock absorption protects machinery frames from fracture. Solid tires are gaining share in warehousing as three-shift operations eliminate puncture tolerance and demand zero-maintenance uptime. The OEM end-user channel concentrates margin pools through long-term supply agreements tied to original equipment specifications.
FDA regulations govern rubber compound safety in food-processing facility tires where material contact occurs, while EPA emissions standards indirectly shape demand through electric forklift penetration requiring low-rolling-resistance designs. OSHA workplace safety mandates dictate load-rating visibility and inspection protocols that influence replacement scheduling and product labeling requirements across US industrial sites. Stakeholders must monitor how EU Ecodesign requirements and emerging battery-electric heavy equipment specifications will recalibrate tire thermal management and compound conductivity standards before committing capital to next-generation production lines.
Market Dynamics
Automation in warehousing is compressing replacement cycles as three-shift operations demand zero-downtime tire performance, while REACH compliance forces compound reformulation across European supply chains.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA rules on tire compound transparency are accelerating R&D investment in alternative filler materials and synthetic rubber blends.
- Electric forklift penetration:Battery-powered material-handling equipment in Germany's Hamburg-Munich logistics corridor requires low-rolling-resistance tire designs.
- Heat-resistant compound advances:Sustained high-speed warehouse automation is pulling demand for thermally stable tread formulations in continuous-duty applications.
Market Restraints
- Natural rubber supply concentration:Southeast Asian plantation geography exposes manufacturers to climate volatility and logistics disruption.
- Carbon black cost volatility:Petroleum-derived filler prices fluctuate with crude oil markets, compressing compound margin predictability.
- Technical limitation in solid-pneumatic hybrid designs:Current architectures cannot simultaneously achieve solid-tire puncture immunity and pneumatic shock absorption.
Strategic Opportunities
- EU Ecodesign requirements:Emerging tire thermal management and conductivity standards create first-mover advantage for compound innovators.
- Sensor-embedded architectures:Convergence of pneumatic tire structures with IoT pressure-monitoring systems opens predictive maintenance revenue streams.
- India's logistics infrastructure buildout:Warehouse automation adoption in Mumbai-Delhi industrial corridors presents underpenetrated demand for solid forklift tires.
Industry Challenges
- Compound formulation chemist scarcity:Skilled specialists capable of balancing heat resistance, abrasion tolerance, and regulatory compliance command premium compensation.
- OSHA inspection protocol compliance:US workplace safety mandates on load-rating visibility require systematic relabeling and documentation across installed tire fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Tire Market |
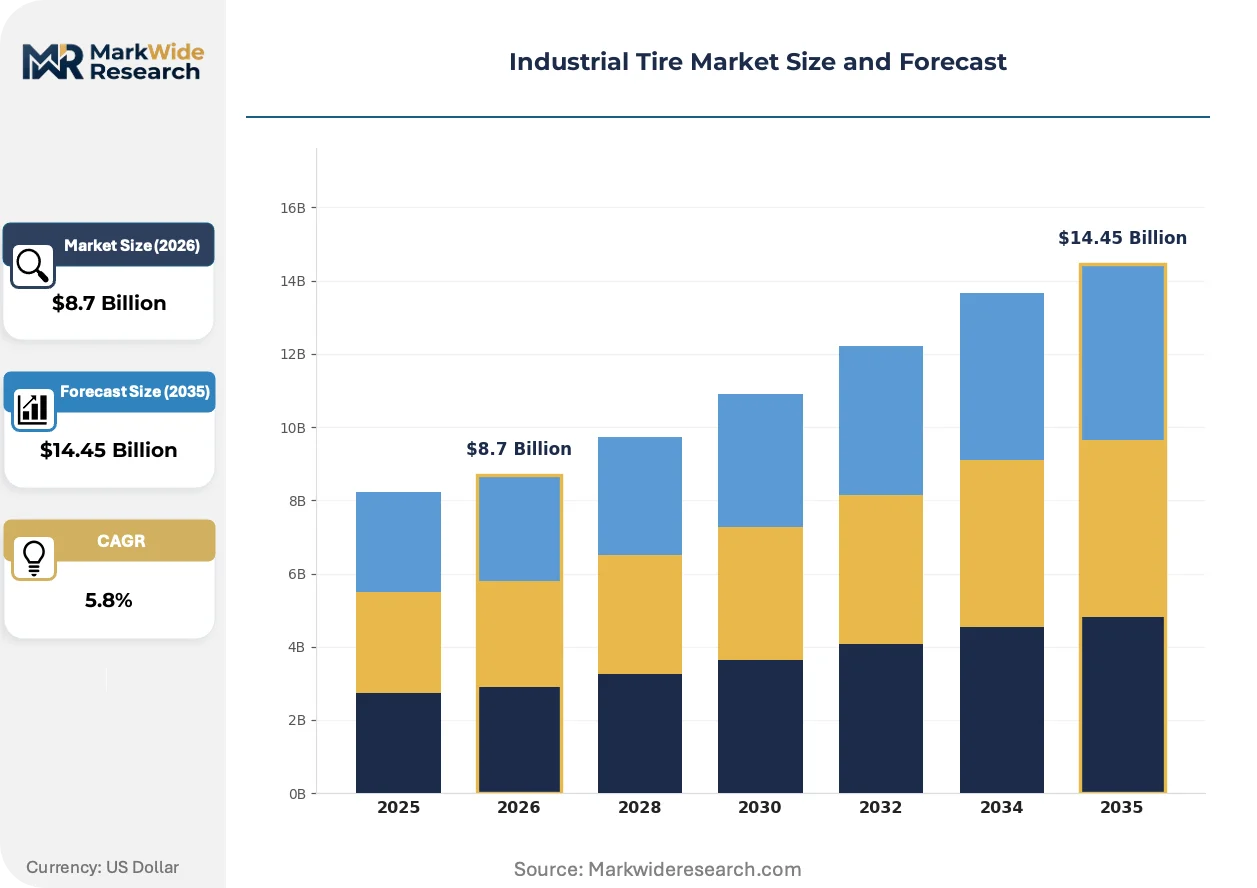
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Solid, Press-on Band, Foam-filled Application: Construction, Warehousing, Agriculture, Mining End User: OEMs, Rental Companies, Fleet Operators, Distributors Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Michelin, Bridgestone, Goodyear, Continental, Pirelli, Sumitomo Rubber Industries, Balkrishna Industries, Titan International, Triangle Tire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Tire Market Strategic Shifts
Embedded sensor systems and low-rolling-resistance compounds are redefining tire value propositions as electrification and predictive maintenance reshape buyer expectations.
Integrated pressure and temperature monitoring hardware is miniaturizing within pneumatic tire carcasses, enabling real-time fleet tracking. Mining operators in Australia's Pilbara region are piloting these systems to preempt blowouts on haul trucks. The technology is compressing maintenance scheduling from calendar-based to condition-based intervals.
EPA emissions standards are indirectly mandating tire efficiency improvements through electric forklift penetration requirements. Low-rolling-resistance designs reduce battery drain and extend operating range. Food-processing facilities under FDA rubber compound safety rules are particularly affected, as material contact specifications limit available formulation options.
Buyer consolidation among third-party logistics providers is concentrating procurement volume with fleet management companies. Long-term supply agreements tied to total-cost-of-ownership metrics are displacing spot purchasing. Germany's automotive supplier parks demonstrate this shift most visibly, where tire-as-a-service models are gaining contractual traction.
Industrial Tire Market Segmentation
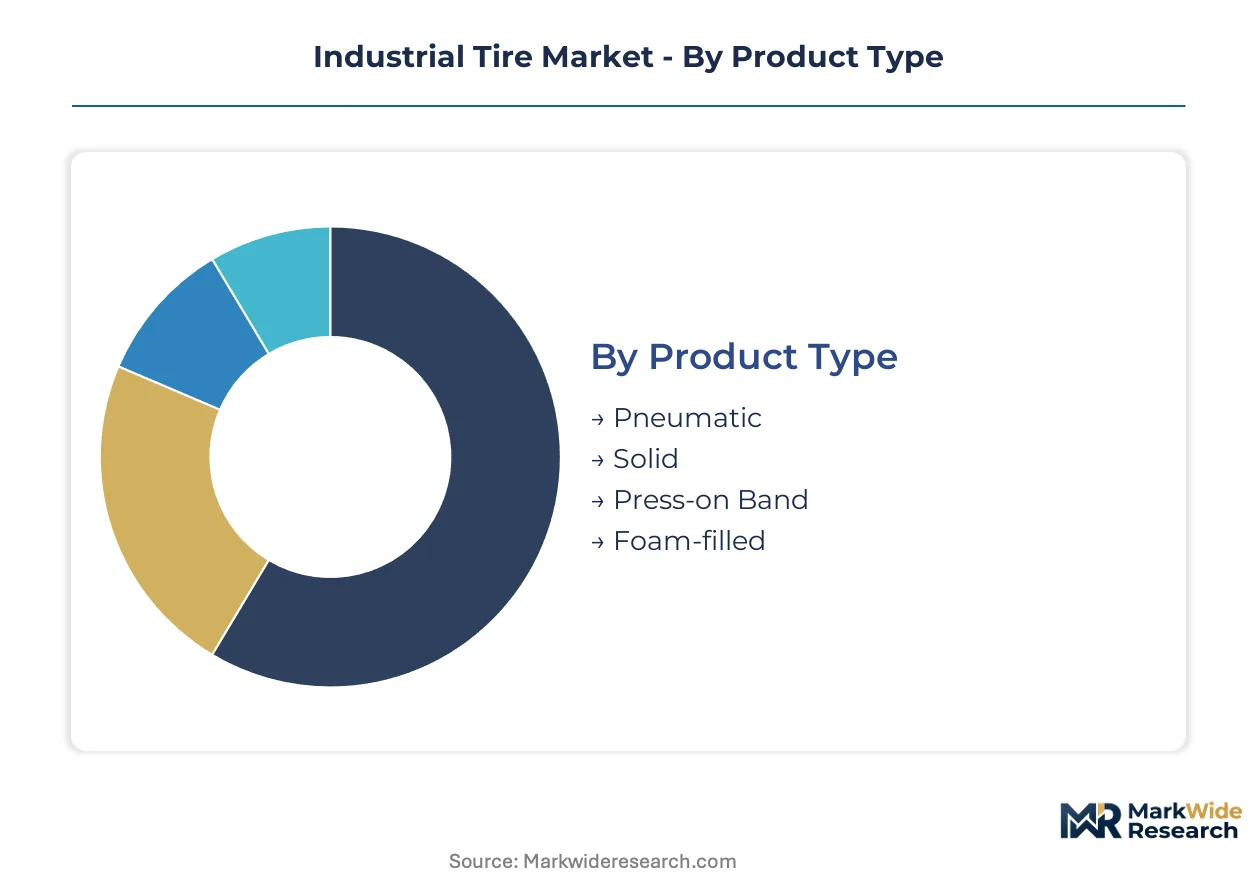
Industrial tire segmentation reflects divergent performance requirements across surface conditions, load intensities, and uptime mandates. Each category channels procurement decisions toward distinct technical specifications and commercial relationships.
Product Type:
Pneumatic tires dominate export flows to mining-intensive economies, while solid tires anchor domestic replacement cycles in automated warehousing corridors.
- Pneumatic:Air-filled carcasses with reinforced sidewalls absorb shock loads on unpaved haul roads and protect heavy machinery frames from fracture. Demand concentrates in Australia's Pilbara iron ore operations and Chilean copper belts where terrain irregularity mandates cushioning. REACH compliance is forcing reformulation of natural rubber blends to reduce aromatic oil content.
- Solid:Molded rubber structures eliminate puncture risk through homogeneous construction, enabling zero-downtime performance in three-shift distribution centers. Germany's Hamburg-Munich logistics corridor drives specification intensity as fleet operators prioritize thermal stability over ride comfort. Heat-resistant compound advances are compressing replacement intervals.
- Press-on Band:Bonded tread rings mount onto industrial wheel rims for rapid field replacement in high-wear environments.
- Foam-filled:Polyurethane-injected pneumatic casings combine puncture immunity with moderate shock absorption for mixed-surface applications.
Pneumatic tires hold the largest share; momentum sits with solid configurations as automation raises uptime requirements.
Application:
Construction and mining applications command premium pricing tiers due to duty-cycle severity, while warehousing volumes scale through fleet standardization.
- Construction:Rough-terrain forklifts and telehandlers require deep-lug tread patterns with cut-resistant compounds to navigate demolition debris and aggregate stockpiles. German equipment OEMs specify integrated pressure-monitoring systems for their export machines to meet emerging EU Ecodesign requirements.
- Warehousing:Narrow-aisle reach trucks and automated guided vehicles operate on smooth concrete at sustained speeds, prioritizing low-rolling-resistance designs that extend battery range. India's Mumbai-Delhi industrial corridor presents underpenetrated demand as third-party logistics providers consolidate procurement.
- Agriculture:Flotation tires distribute combine harvester loads across soft field conditions to minimize soil compaction.
- Mining:Ultra-class haul trucks require heat-dissipating tread compounds that withstand continuous braking cycles on steep grades.
Construction generates the highest unit margins; warehousing is expanding most quickly through fleet electrification.
End User:
OEM supply agreements concentrate volume through multi-year contracts, while rental companies standardize across mixed fleets to simplify maintenance protocols.
- OEMs:Original equipment manufacturers embed tires within total-machine specifications, locking compound formulations and load ratings through design validation. Japanese robotics-integrated production facilities demand dimensional tolerances that constrain supplier pools.
- Rental Companies:Equipment lessors prioritize universal fitment and rapid availability over application-specific optimization, compressing margin capture.
- Fleet Operators:Direct procurement by logistics and mining companies enables total-cost-of-ownership modeling and predictive maintenance integration.
- Distributors:Independent dealers stock breadth across product types to serve fragmented replacement demand in secondary markets.
OEMs hold the largest share; momentum sits with fleet operators as tire-as-a-service models gain contractual traction.
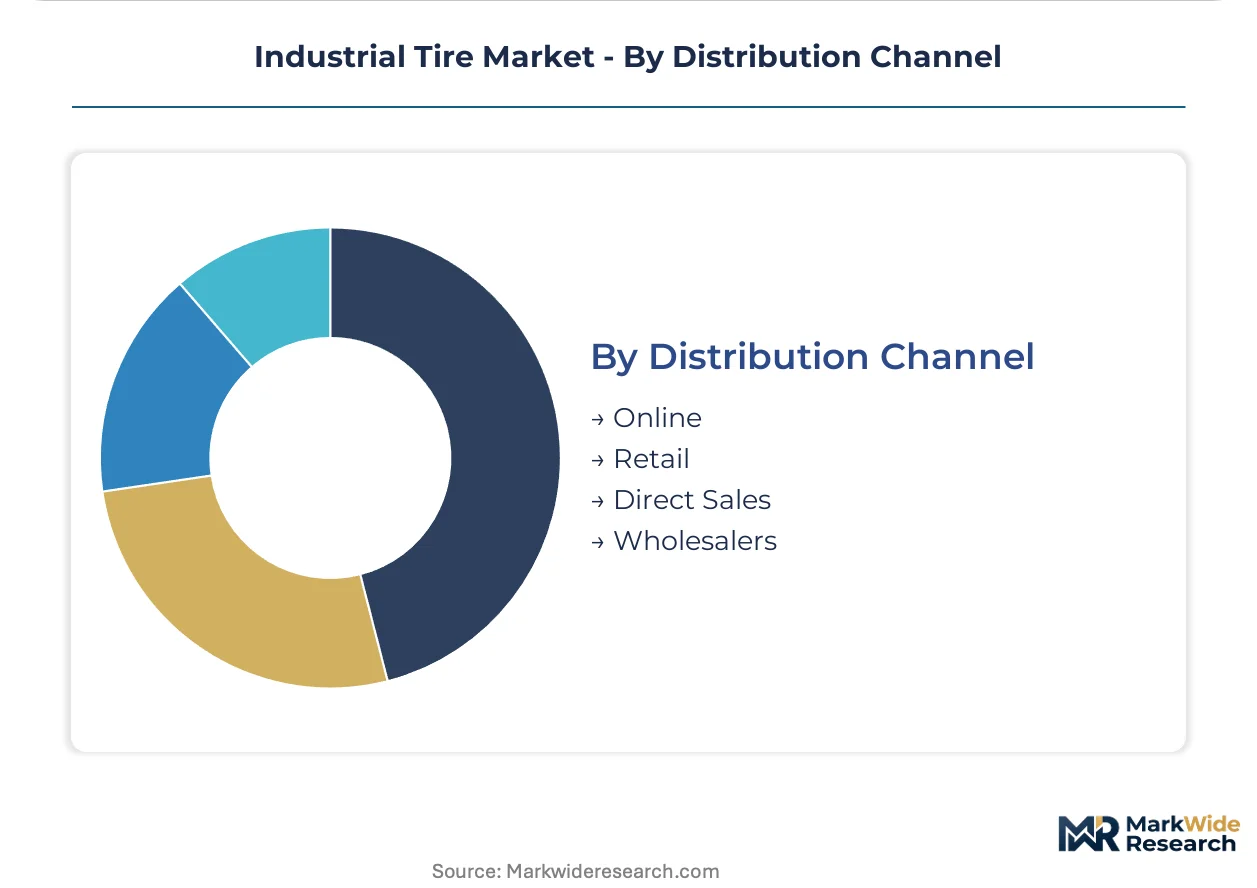
Distribution Channel:
Direct sales anchor high-volume relationships with mining and construction conglomerates, while online channels penetrate standardized warehousing replacements.
- Direct Sales:Manufacturer field engineers negotiate multi-year supply agreements with Pilbara mining operators and German automotive supplier parks, embedding sensor-embedded architectures within predictive maintenance contracts.
- Wholesalers:Regional distributors aggregate fragmented demand from independent repair shops and smaller fleet operators, carrying inventory risk for slower-moving mining sizes.
- Retail:Counter sales serve immediate replacement needs in construction and agriculture segments with limited supply chain sophistication.
- Online:E-procurement platforms standardize specifications for warehousing tires, enabling price transparency and consolidated billing for multi-site operators.
Direct sales hold the largest share; online channels are gaining share fastest among standardized product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial tire consumption patterns diverge sharply across geographies. Mining-intensive economies favor pneumatic shock-absorbing designs, while automated warehousing corridors drive solid-tire specification intensity.
Germany
The Hamburg-Munich logistics corridor anchors European demand for heat-resistant solid tires in three-shift distribution centers. REACH compliance through ECHA mandates aromatic oil reduction in rubber compounds, forcing reformulation investments. Stuttgart's automotive supplier parks are piloting tire-as-a-service contracts with embedded sensor architectures.
United States
OSHA workplace safety mandates on load-rating visibility drive systematic fleet relabeling across industrial sites. EPA emissions standards indirectly shape procurement through electric forklift penetration requiring low-rolling-resistance designs. The Great Lakes manufacturing belt concentrates warehousing automation adoption and compressed replacement cycles.
China
Yangtze River Delta logistics hubs are scaling automated guided vehicle fleets that prioritize zero-puncture uptime. GB standards on industrial equipment safety intersect with MIIT directives on smart manufacturing infrastructure. Qingdao's rubber processing clusters are integrating backward into synthetic polyisoprene production.
Australia
Pilbara iron ore operations command premium pneumatic specifications for ultra-class haul truck shock absorption. The country's national mining safety regulator mandates tire pressure monitoring on steep-grade haulage routes. Perth-based fleet operators are piloting condition-based maintenance scheduling through embedded sensor systems.
India
The Mumbai-Delhi industrial corridor presents underpenetrated demand for solid forklift tires as third-party logistics providers consolidate procurement. BIS certification requirements for industrial rubber products shape import substitution dynamics. Chennai's automotive component parks are emerging as domestic tire fabrication clusters.
Industrial Tire Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in industrial tire supply. The upper tier commands captive natural rubber supply chains and robotics-integrated production scale. Mid-scale regional fabricators compete on rapid availability and application-specific customization. Dominant competitive moves include backward integration into plantation assets and predictive maintenance service bundling.
Among Japanese fabricators, Sumitomo Rubber Industries occupies a position exemplifying advanced production automation archetypes. Continental AG and Michelin represent the integrated leader tier with captive supply chain control and sensor-embedded product architectures. Balkrishna Industries anchors the specialist tier focused on off-highway equipment segments.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone |
| Goodyear |
| Continental |
| Pirelli |
| Sumitomo Rubber Industries |
| Balkrishna Industries |
| Titan International |
| Triangle Tire |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Southeast Asian rubber processing clusters shapes both supply concentration and price floors across industrial tire tiers. German automotive supplier parks and Australian mining operators face divergent cost structures as plantation geography and automation intensity recalibrate margin pools.
Pricing Analysis
Long-term offtake contracts anchor pricing between integrated manufacturers and OEM equipment suppliers, compressing spot market liquidity for standard solid tire grades. Three-tier pricing structure across premium sensor-embedded, standard heat-resistant, and economy press-on band levels reflects certification intensity and after-sales bundling. Cost compression in economy tiers is intensifying because carbon black feedstock volatility feeds through compound formulations. Fleet operators in warehousing automation corridors demonstrate lowest price sensitivity due to total-cost-of-ownership procurement models, while independent distributors in secondary markets face margin erosion.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows from Thai and Indonesian plantations to Qingdao processing clusters and Japanese fabrication facilities. Natural rubber latex, synthetic polyisoprene, and petroleum-derived carbon black constitute the critical input trinity. Single-source vulnerability concentrates in Southeast Asian plantation geography exposed to climate volatility and logistics disruption. Distribution runs through manufacturer-direct field engineering for mining conglomerates and tiered wholesaler networks for fragmented replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial tire incumbents must defend against substitution from airless wheel architectures and continuous-track material-handling systems as electrification reshapes equipment design priorities.
For Market Incumbents: Secure captive natural rubber supply through plantation equity stakes or long-term offtake agreements with Thai and Indonesian processors. Deepen backward integration into heat-resistant compound R&D to meet EU Ecodesign thermal management standards before regulatory deadlines tighten supplier pools. For New Entrants and Emerging Players: Anchor in India's Mumbai-Delhi logistics corridor where third-party logistics consolidation creates fleet standardization opportunities absent entrenched supplier relationships. Target solid forklift tire specifications for automated guided vehicle fleets through e-procurement platform partnerships that bypass traditional wholesaler channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound formulation specialists with REACH-compliant synthetic rubber capabilities and sensor-embedded architecture pipelines. Five-to-ten year viability hinges on regulatory compliance moats rather than scale economies alone. Monitor EU Ecodesign implementation timelines as the inflection signal for thermal management technology premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive natural rubber supply from Thai and Indonesian sources insulates against climate-driven price volatility. |
| Sensor-Embedded Architecture Development | Integrated pressure-monitoring hardware enables predictive maintenance contracts with Pilbara mining operators. |
| REACH-Compliant Compound Reformulation | Aromatic oil reduction meets ECHA disclosure mandates for European logistics corridor access. |
| Long-term Supply Agreement with OEMs | Multi-year contracts with German equipment manufacturers lock specification standards and volume commitments. |
| Joint Venture in Qingdao Processing Cluster | Synthetic polyisoprene production partnerships reduce petroleum-derived input dependency. |
Study Parameters
The analysis maps pneumatic, solid, press-on band, and foam-filled tire configurations, each validated through compound formulation chemists, OEM procurement directors, mining fleet maintenance heads, and third-party logistics operators. Primary interviews with plant engineers at German automotive supplier parks and Australian Pilbara operations combined with secondary validation from customs trade data, ECHA regulatory filings, SEC 10-K disclosures, and tire industry association reports. Bottom-up unit economics and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. Segmentation modeling spanned product type, application intensity, end-user procurement model, and regional regulatory cluster dimensions. CAGRs derived from historical replacement cycle compression rates, electrification penetration curves, and automation adoption thresholds in warehousing corridors.
Decision-makers should treat outputs as directional under base assumptions of sustained electrification and REACH enforcement; material deviation in carbon black feedstock costs or plantation climate events would warrant model refresh. Practitioners should keep alternative scenarios live as EU Ecodesign thermal management specifications and battery-electric heavy equipment standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Wheel Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
E-Bike Tire Market