
 Steel Cord for Tire Reinforcement Market | 2026-2036
Steel Cord for Tire Reinforcement Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Cord for Tire Reinforcement Market Insights
China's steel cord capacity build-out is reshaping regional supply dynamics for tire reinforcement. N.V. Bekaert S.A. leverages its Belgian metallurgical heritage to dominate premium-grade cord specifications for European OEMs. Henan Hengxing Science & Technology Co., Ltd. anchors the mid-tier segment through captive supply relationships with domestic tire manufacturers in Henan province. ArcelorMittal competes on raw material integration, controlling iron ore-to-wire rod cost structures that smaller producers cannot match.
Steel cord consists of high-carbon steel wires twisted into multi-strand cables with tensile strengths exceeding 2,800 MPa, manufactured through patenting, wire drawing, and brass plating processes to ensure rubber adhesion in tire belts and carcasses. Radial tires command the largest application share due to their dominance in passenger and commercial vehicle fitments, while specialty tires for mining and agricultural equipment represent the fastest-growing margin pool. Steel wire products sustain the majority of volume demand, though aramid fiber alternatives are gaining traction in ultra-high-performance segments where weight reduction justifies premium pricing.
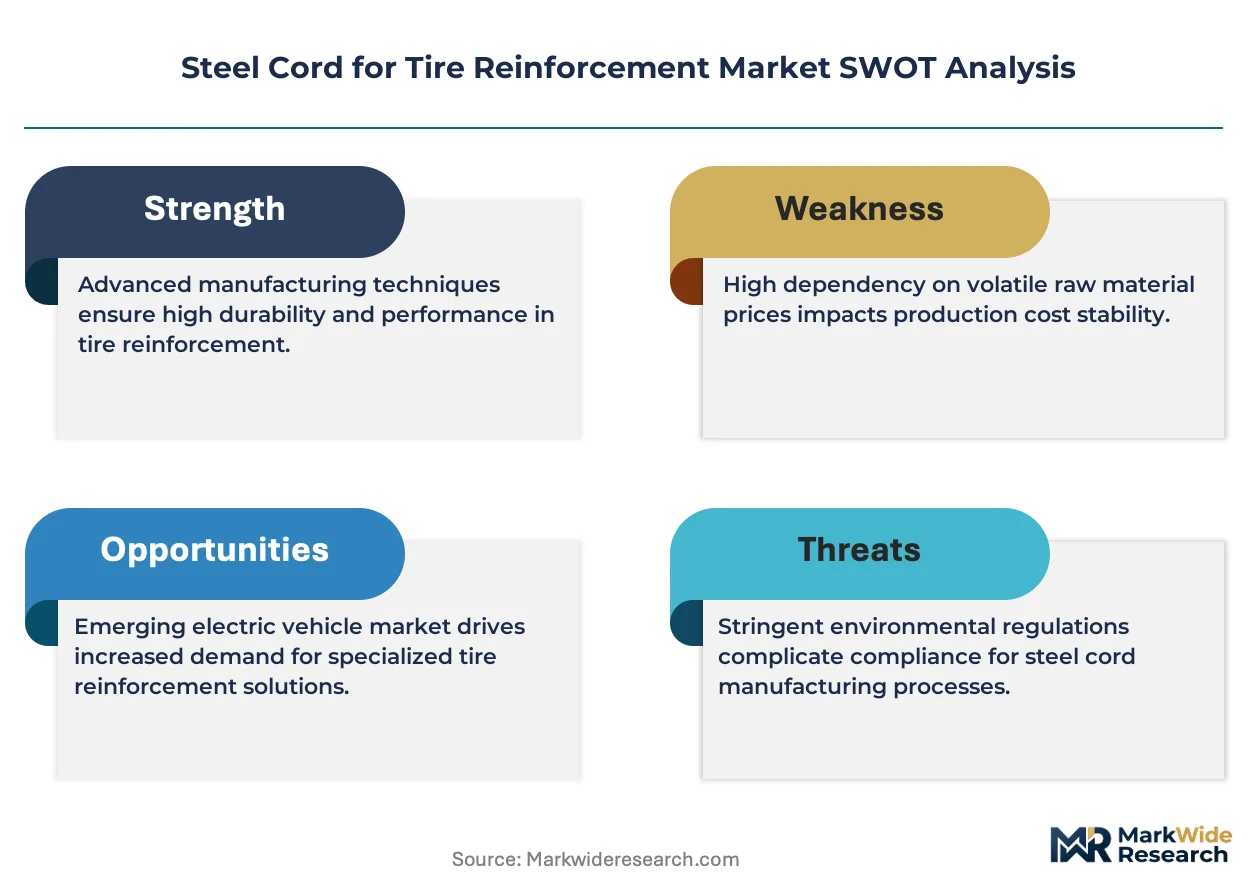
The EPA enforces emissions-linked fuel economy standards that indirectly mandate low-rolling-resistance tires, while China's GB standards specify steel cord mechanical properties for domestic tire certification. REACH compliance in Europe restricts certain brass plating chemistries, compelling suppliers to reformulate coating processes. Stakeholders must monitor evolving tire labeling schemes and carbon border adjustments that will redefine competitive access across major demand centers.
Market Dynamics
Radial tire architecture now commands virtually all passenger and commercial fitments, concentrating steel cord demand into high-strength, thin-diameter specifications that only a handful of metallurgical suppliers can reliably produce at scale.
Growth Catalysts
- EU tire labeling mandates:Rolling resistance grades under EU regulations are forcing OEMs to specify ultra-high-strength cord grades that reduce belt weight while maintaining fatigue performance.
- Electric vehicle platform expansion:Battery-electric vehicle manufacturers specify reinforced belts to manage instant torque loads and extended range requirements.
- Shandong-Jiangsu cluster concentration:Tire production agglomeration in these provinces generates captive demand pull that stabilizes capacity utilization for adjacent steel cord mills.
Market Restraints
- Scrap steel cost volatility:Electric arc furnace operators face input cost swings that compress margin predictability for wire rod producers.
- Single-source brass plating chemistry:REACH restrictions on certain coating formulations have eliminated European suppliers of legacy plating additives, creating formulation bottlenecks.
- Aramid fiber substitution in UHP segments:Weight-critical performance tires in motorsport and premium EV applications are specifying hybrid belt packages that displace steel entirely.
Strategic Opportunities
- India PLI scheme for tire manufacturing:Production-linked incentives are attracting greenfield tire capacity that will require localized steel cord supply infrastructure.
- Smart tire sensor integration:Embedding strain sensors within steel cord belts enables real-time pressure and wear monitoring, creating value-added tier differentiation.
- Mining tire aftermarket:Off-the-road retread programs represent an underserved channel for high-durability cord specifications purpose-built for abrasive operating environments.
Industry Challenges
- Patenting heat treatment expertise:The specialized furnace engineering required for 2,800+ MPa tensile strength resides with a shrinking cohort of process engineers approaching retirement.
- Dual certification timelines:Simultaneous GB standard compliance for China and ECE R30 homologation for export markets extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Cord for Tire Reinforcement Market |
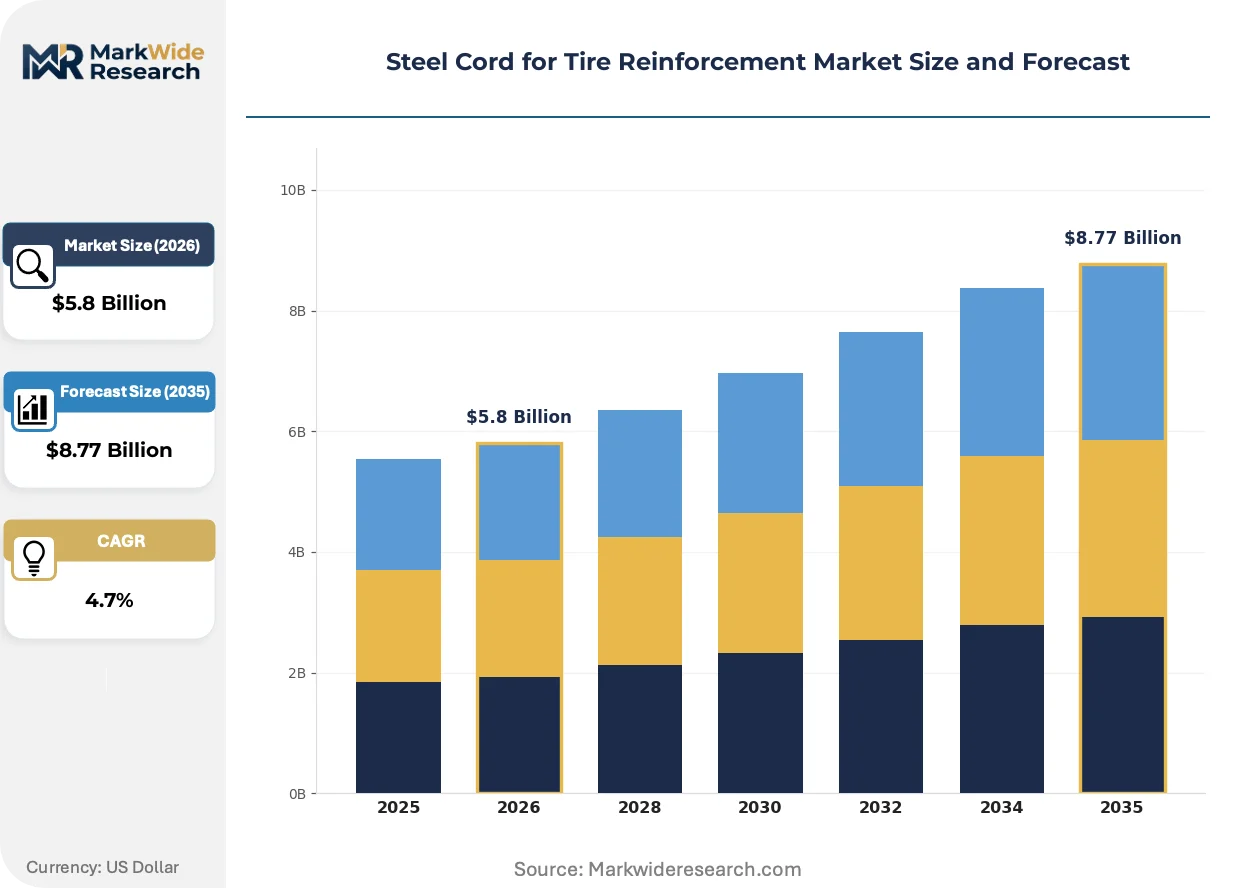
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wire, Polyester Cord, Nylon Cord, Aramid Fiber Industry Vertical: Automotive, Aerospace, Heavy Machinery, Construction Application: Radial Tires, Bias Tires, Specialty Tires, Tubeless Tires Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Tokusen Kogyo Co., Ltd., Henan Hengxing Science & Technology Co., Ltd., N.V. Bekaert S.A., ArcelorMittal, Shougang Century Holdings Limited, Hyosung Corporation, Tokyo Rope Mfg. Co., Ltd., Baosteel Group Corporation, Sumitomo Electric Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Cord for Tire Reinforcement Market Trends and Innovations
Digital thread technologies are compressing the feedback loop between tire performance data and cord specification refinement, collapsing traditional multi-year product development cycles into continuous iteration protocols.
Finite element modeling of cord-rubber composite behavior is virtualizing physical prototyping requirements for new tire constructions. Tier 1 tire engineers now simulate belt fatigue across millions of load cycles before committing to mold trials. This capability is virtualizing the traditional sequential handoff between cord supplier compound recommendations and tire manufacturer belt design, compressing development timelines and reducing scrap rates.
REACH Article 33 disclosure obligations for brass plating constituents are compelling reformulation of adhesion promoter chemistries across European supply chains. ECHA substance of very high concern listings have eliminated several legacy coating intermediates from qualified supplier lists. Tire manufacturers serving EU markets are responding by dual-sourcing cord from Bekaert's Belgian facilities and qualifying Asian suppliers with REACH-compliant process certifications.
Fleet operators are consolidating procurement decisions at the holding-company level, bypassing traditional distributor networks that historically aggregated fragmented regional demand. Large logistics and ride-hail fleets now negotiate direct supply agreements with tire manufacturers, specifying cord grade and construction in their technical requirements. This concentration is most visible in North American long-haul trucking and European last-mile delivery segments, where total cost of ownership modeling has displaced upfront unit price as the primary selection criterion.
Steel Cord for Tire Reinforcement Market Segmentation
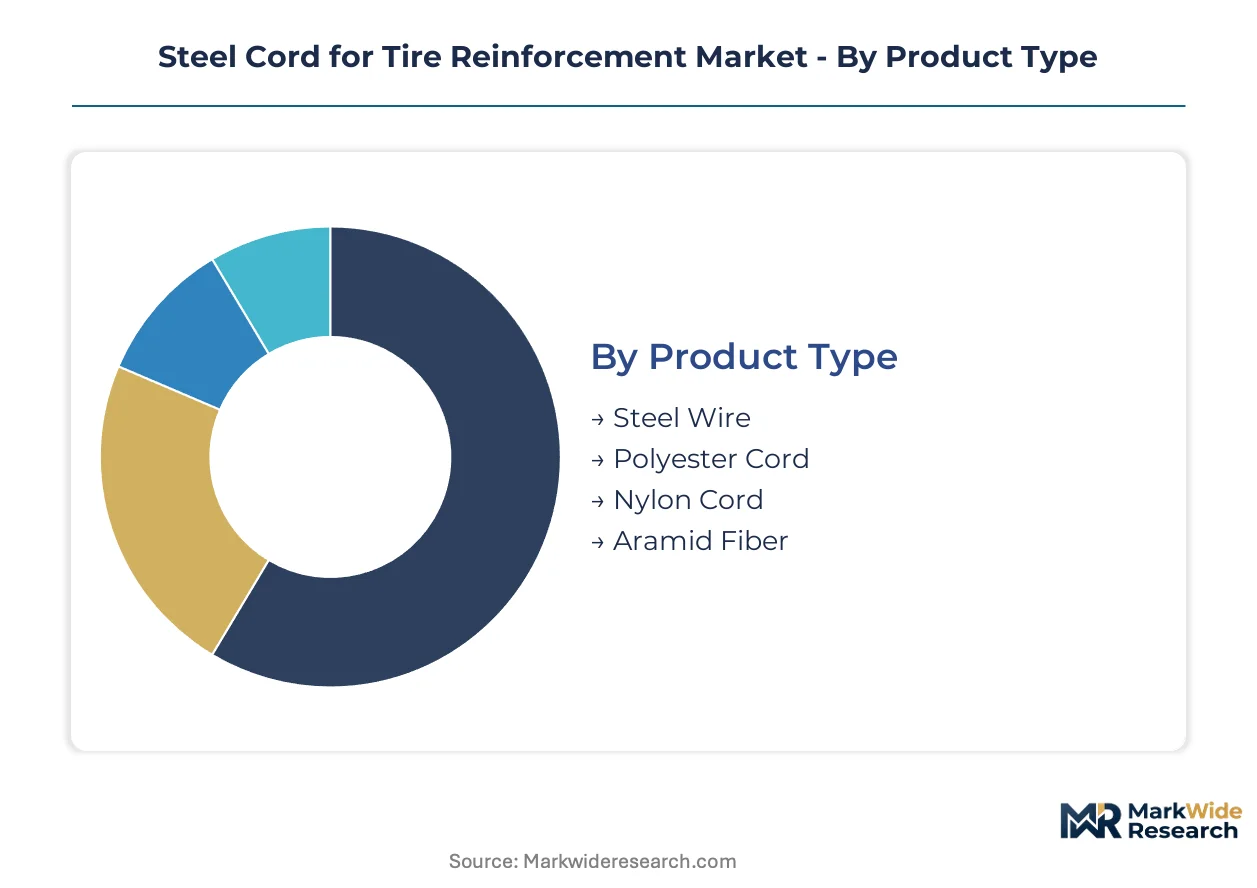
Steel cord specification tiers map directly to tire performance categories, with material selection determining fatigue resistance, adhesion properties, and weight targets across passenger, commercial, and off-road applications. Procurement patterns vary sharply by end-use, with OEM tire manufacturers demanding certified batch consistency while aftermarket channels prioritize availability and price competitiveness.
Product Type:
Mature steel wire specifications dominate volume throughput, while emerging fiber alternatives carve share in performance-critical niches where weight reduction commands premium economics.
- Steel Wire:High-carbon steel filaments twisted into multi-strand cables with tensile strengths exceeding 2,800 MPa, processed through patenting, wire drawing, and brass plating sequences to ensure rubber adhesion. Passenger and commercial radial tire production in China's Shandong province consumes the majority of global steel wire output, driven by EU tire labeling mandates that penalize rolling resistance inefficiency.
- Aramid Fiber:Synthetic aromatic polyamide filaments delivering strength-to-weight ratios superior to steel at five to ten times the unit cost. Ultra-high-performance tires for electric vehicles and motorsport applications in Germany and Japan specify aramid hybrid belts to offset battery weight and reduce unsprung mass.
- Polyester Cord:PET-based reinforcement for bias-ply tire carcasses where moderate strength requirements and cost sensitivity predominate in emerging market two-wheeler and light truck segments.
- Nylon Cord:Polyamide 6.6 construction offering superior impact resistance for heavy-duty bias tires in mining and agricultural equipment operating across abrasive terrain.
Steel wire handles the majority of throughput; aramid fiber is the fastest mover on share.
Industry Vertical:
Cost tier differentiation separates specification-intensive OEM supply from price-sensitive replacement market procurement, with each vertical demanding distinct certification protocols and volume commitments.
- Automotive:Passenger vehicle and commercial truck tire manufacturers specify steel cord by fatigue performance grade, with European OEMs mandating REACH-compliant brass plating chemistries and Chinese producers adhering to GB standard mechanical property specifications. Battery-electric vehicle platforms are driving specification upgrades to manage instant torque loads.
- Heavy Machinery:Off-the-road tire producers for mining and construction equipment demand high-durability cord constructions purpose-built for retread programs and abrasive operating environments.
- Aerospace:Aircraft tire applications require ultra-high-strength specifications with zero-defect quality assurance protocols and extended fatigue life certification.
- Construction:Mobile crane and earthmover tire reinforcement emphasizes cut resistance and load-bearing capacity over rolling resistance optimization.
Automotive absorbs the dominant share of steel cord procurement; heavy machinery is expanding most quickly as mining fleet operators consolidate procurement at the holding-company level.
Application:
Volume concentration follows tire architecture adoption curves, with radial designs commanding nearly all passenger and commercial fitments while specialty constructions serve equipment categories with unique load and terrain requirements.
- Radial Tires:Belted radial construction with steel cord reinforcing plies oriented at 90 degrees to the direction of travel, delivering superior tread wear and fuel efficiency. Manufacturing clusters in China's Jiangsu province and Thailand's Rayong province consume high-strength, thin-diameter specifications that only metallurgical specialists with patenting furnace expertise can reliably produce.
- Specialty Tires:Mining, agricultural, and port equipment tires requiring reinforced shoulders and enhanced bead durability for severe service cycles. Retread programs for off-the-road segments represent an underserved aftermarket channel with above-average margin structures.
- Bias Tires:Cross-ply construction with diagonal cord angles, retaining share in motorcycle, agricultural, and some heavy truck applications where load capacity and sidewall flexibility outweigh rolling resistance targets.
- Tubeless Tires:Radial designs with airtight inner liners, universally specified for passenger vehicles and increasingly mandated for commercial truck applications by NHTSA regulations in the US and ECE R30 homologation in Europe.
Radial tires manage the bulk of steel cord consumption; specialty tires are climbing the fastest on margin contribution.
Distribution Channel:
Customer type fragmentation separates direct OEM supply relationships from fragmented aftermarket channels, with fleet operator consolidation reshaping procurement concentration.
- Direct Sales:Long-term supply agreements between steel cord mills and tier 1 tire manufacturers, with technical collaboration on belt design and finite element modeling of cord-rubber composite behavior. Bekaert's Belgian facilities and Henan Hengxing's captive relationships with domestic Chinese producers exemplify this channel.
- Distributors:Regional inventory aggregation serving independent tire retreaders and smaller manufacturers without volume leverage for mill-direct procurement.
- Retailers:Point-of-sale availability for replacement tire consumers and independent repair shops, with limited steel cord visibility as a discrete purchase category.
- Online Platforms:Emerging channel for specialty cord specifications and small-batch procurement by custom tire builders and motorsport teams.
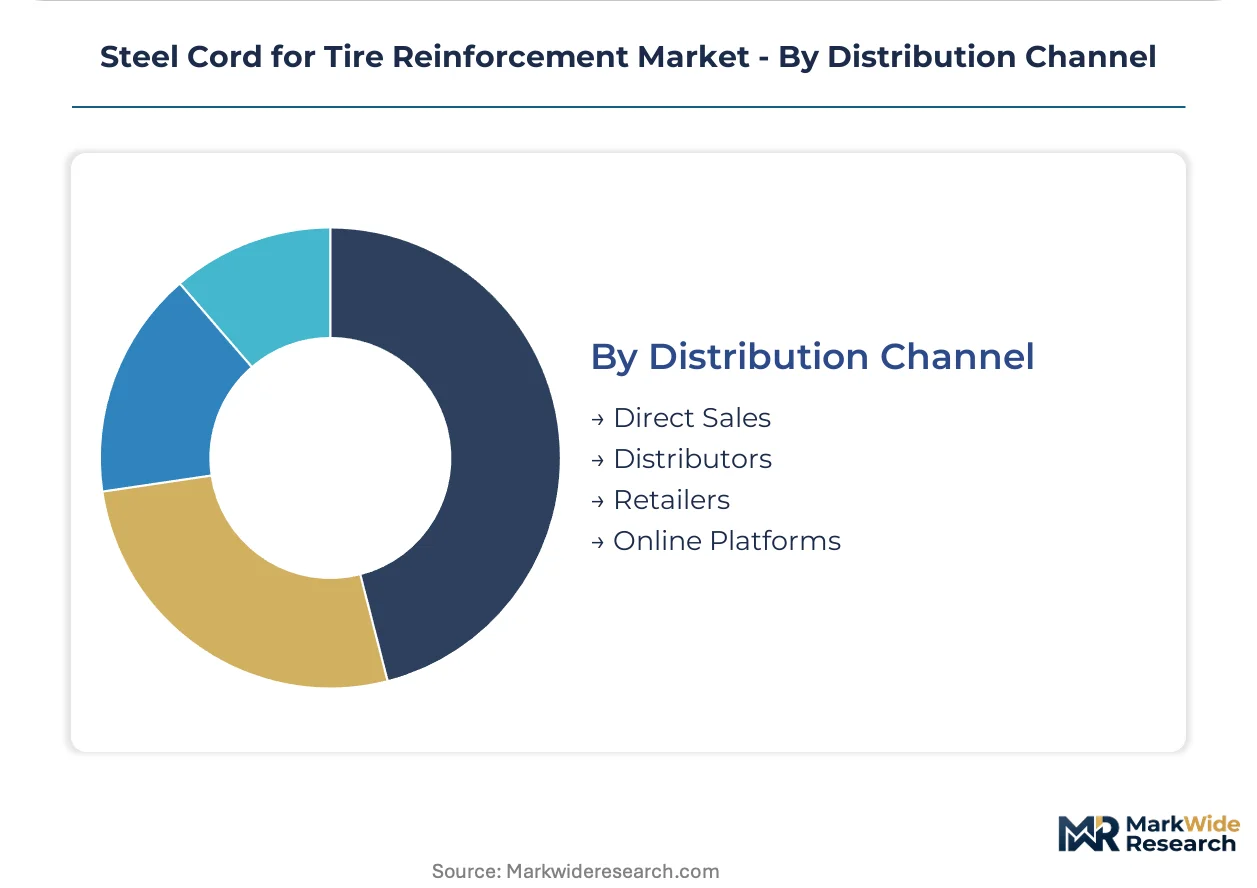
Direct sales channels capture the preponderance of volume value; online platforms are gaining traction fastest among specialty and racing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's steel handling infrastructure anchors European supply chain connectivity for metallurgical inputs, while China's coastal port network enables raw material throughput that underwrites tire manufacturing clusters across three provinces.
China
Shandong and Jiangsu provinces concentrate tire production capacity that consumes the majority of domestic steel cord output, with Qingdao and Nanjing serving as logistics hubs for both domestic distribution and export. GB standards specify steel cord mechanical properties for tire certification, creating compliance requirements that domestic mills must satisfy before supplying OEM manufacturers. The Yangtze River Delta manufacturing corridor generates captive demand pull that stabilizes capacity utilization for adjacent steel cord facilities.
Germany
Baden-Württemberg and Lower Saxony host automotive OEM headquarters that specify ultra-high-strength cord grades for European tire labeling compliance. REACH restrictions on brass plating chemistries have eliminated legacy coating intermediates from qualified supplier lists, compelling reformulation across European supply chains. Continental and Michelin procurement teams in Hanover and Frankfurt coordinate technical collaboration with metallurgical suppliers on belt design optimization.
United States
Southeastern tire manufacturing corridors in South Carolina and Tennessee generate demand for high-strength reinforcement materials serving domestic OEM and replacement markets. NHTSA regulations mandate tubeless tire specifications for commercial truck applications, indirectly influencing steel cord grade selection. The Port of Charleston handles bulk steel imports that feed wire rod production for regional tire belt manufacturing.
Japan
Kanto and Kansai industrial belts concentrate tire engineering expertise that specifies fatigue-resistant cord constructions for premium passenger and motorsport applications. METI industrial standards govern material specifications for domestic tire certification, creating technical barriers for non-compliant imports. Yokohama and Osaka-based tire manufacturers maintain long-term supply relationships with domestic metallurgical specialists for high-performance belt packages.
India
Tamil Nadu and Gujarat are attracting greenfield tire capacity under the PLI scheme for manufacturing, creating localized demand for steel cord supply infrastructure. BIS standards specify mechanical property requirements for domestic tire reinforcement materials. Chennai and Ahmedabad industrial zones are emerging as procurement centers where tire manufacturers negotiate direct supply agreements bypassing traditional distributor networks.
Steel Cord for Tire Reinforcement Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling metallurgical process expertise. The market structures around three tiers: integrated steel producers with captive wire rod supply, independent cord manufacturers with patenting furnace specialization, and regional fabricators serving replacement market channels. Two competitive moves dominate: backward integration into wire rod production to secure raw material cost structures, and strategic partnerships with tire OEMs for co-development of fatigue-optimized belt specifications.
Within the metallurgical heritage tier, N.V. Bekaert S.A. and ArcelorMittal occupy positions that exemplify divergent strategic archetypes—Belgian process specialization versus raw material integration. Henan Hengxing Science & Technology Co., Ltd. anchors the mid-tier segment through captive supply relationships with domestic Chinese tire manufacturers. These three entities represent the spectrum from premium-grade European specifications to volume-driven Asian production, with each archetype commanding distinct certification protocols and customer loyalty structures.
| Leading Market Players |
|---|
| Tokusen Kogyo Co., Ltd. |
| Henan Hengxing Science & Technology Co., Ltd. |
| N.V. Bekaert S.A. |
| ArcelorMittal |
| Shougang Century Holdings Limited |
| Hyosung Corporation |
| Tokyo Rope Mfg. Co., Ltd. |
| Baosteel Group Corporation |
| Sumitomo Electric Industries, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Shandong wire rod mills is compressing spot pricing for standard-grade tire cord while simultaneously forcing suppliers toward extended payment terms and technical service bundling to defend account relationships.
Pricing Analysis
Volume-discount tiering separates annual contract commitments exceeding 10,000 metric tons from spot-market procurement, with European OEMs paying certification premiums for REACH-compliant brass plating while Chinese domestic tire makers negotiate raw-material-pass-through clauses. Price differentiation hinges on fatigue-grade certification and captive wire rod supply, with integrated producers capturing margin stability that merchant mills cannot match. Cost compression in the standard-grade segment is intensifying because Indonesian and Vietnamese tire capacity is qualifying lower-specification cord alternatives. Fleet operators consolidating at the holding-company level exhibit the lowest price sensitivity, while independent retreaders in fragmented aftermarket channels drive aggressive spot-market negotiation.
Supply Chain Analysis
Supplier-financing facilities now extend 90-120 day payment terms to Tier 1 tire manufacturers, with Bekaert's Belgian operations and Henan Hengxing's captive Chinese mills anchoring the trade-credit architecture. Geographic supply concentration centers on China, Belgium, and Japan, with wire rod feedstock drawing from ArcelorMittal's integrated European facilities and Baosteel's coastal Chinese mills. Raw material dependencies rest on high-carbon scrap steel, brass coating alloys, and patenting furnace natural gas. Single-source vulnerability in REACH-compliant plating chemistry creates formulation bottlenecks. Distribution runs through direct mill-to-OEM contracts for volume tire production, with regional distributors serving aftermarket retread channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel cord suppliers can attach sensor-embedded belt monitoring services that generate recurring telemetry revenue growing faster than commodity cord shipments as fleet operators adopt predictive maintenance platforms.
For Market Incumbents: Entrench patenting furnace expertise through apprenticeship programs targeting retiring process engineers, while securing captive wire rod supply via backward integration into electric arc furnace operations. Aramid fiber substitution in ultra-high-performance electric vehicle tires threatens premium-grade margin pools; defend through co-development agreements with OEM platform engineers on fatigue-optimized hybrid belt specifications. For New Entrants and Emerging Players: Pursue India's PLI-subsidized tire manufacturing corridor in Tamil Nadu and Gujarat, where localized steel cord supply infrastructure remains underdeveloped relative to announced greenfield capacity. Mining tire retread programs represent the most penetrable aftermarket segment, with above-average durability specifications and fragmented incumbent presence. A technical-service-led go-to-market approach emphasizing abrasive-environment belt design support can differentiate against commodity-focused established suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among metallurgical specialists with embedded sensor-integration capabilities and long-term OEM co-development contracts. Five-to-ten year viability favors patenting furnace operators with proprietary heat-treatment IP and REACH-compliant process certifications rather than merchant wire rod converters. The signal to watch is fleet-operator adoption of smart-tire platforms requiring supplier-side telemetry infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Patenting Furnace Capacity Expansion | Secures 2,800+ MPa tensile strength production capability that only a shrinking cohort of process engineers can reliably operate. |
| REACH-Compliant Plating Chemistry Reformulation | Eliminates single-source vulnerability in European brass coating intermediates while maintaining OEM qualification status. |
| Smart Tire Sensor Integration Partnership | Creates value-added tier differentiation through embedded strain monitoring for fleet predictive maintenance platforms. |
| India PLI Corridor Supply Localization | Captures demand from greenfield tire capacity in Tamil Nadu and Gujarat requiring domestic steel cord infrastructure. |
| Mining Tire Retread Program Development | Targets underserved aftermarket channel with high-durability specifications purpose-built for abrasive operating environments. |
Research Methodology
A spread of perspectives from tire OEM procurement directors, patenting furnace operations managers, metallurgical R&D leads, and fleet telematics specialists converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through customs wire rod trade data, tire manufacturer SEC filings, and GB standard certification registries. Bottom-up volume modeling across radial, specialty, and bias tire architectures triangulated against top-down steel cord consumption estimates from regional production cluster analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, tire architecture, vehicle propulsion category, and regional regulatory cluster. CAGRs were derived from elasticity modeling of tire production volumes against steel cord intensity per tire. Industry-specific forecast inputs included EU tire labeling mandate compliance trajectories and electric vehicle platform torque-load specifications driving belt reinforcement upgrades.
Sensitivities concentrate around scrap steel cost volatility, REACH substance restriction expansions, and aramid fiber substitution rates in premium segments. Forecasts reflect documented assumptions regarding patenting furnace capacity retirement schedules and PLI scheme implementation pace in India. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Automotive Tire Analytics Market