
 North America Industrial IoT Market | 2026-2036
North America Industrial IoT Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial IoT Market Intelligence
The substitution of on-premise data centers with distributed edge computing is recalibrating the economic models for deploying IIoT solutions in North America. Cisco Systems leverages its networking hardware portfolio to capture value at the network edge. Rockwell Automation specializes in integrating edge devices directly into its control systems for manufacturing clients. Honeywell International extends its domain expertise in process control to offer comprehensive IIoT platforms.
Industrial IoT involves the network of interconnected sensors, instruments, and other devices within industrial settings. These systems utilize protocols like LPWAN or Zigbee to transmit operational data, often with sub-second latency requirements for real-time control. Within applications, predictive maintenance represents the fastest-growing segment, driven by its direct impact on operational uptime. The manufacturing and utilities sectors constitute the largest end-user markets, deploying gateways and sensors for asset tracking and process automation.
Regulations from the US Federal Communications Commission (FCC) govern the wireless spectrum allocation for IIoT devices, impacting technology choices. Concurrently, cybersecurity guidelines from entities like the Cybersecurity and Infrastructure Security Agency (CISA) are shaping security requirements for critical infrastructure deployments. Stakeholder success depends on navigating the fragmented technology standards and developing scalable, secure-by-design architectures.
Market Dynamics
The US Inflation Reduction Act is a primary force, channeling investment toward smart factory and clean energy infrastructure. This policy accelerates IIoT deployment for energy efficiency and automated manufacturing processes.
Growth Catalysts
- Predictive Maintenance Value:The US automotive sector adopts IIoT to maximize asset uptime, directly impacting operational efficiency and reducing costly unplanned downtime.
- US Inflation Reduction Act:This policy accelerates IIoT deployment by incentivizing smart grid modernization, primarily impacting the North American utilities sector.
- Low-Latency Networks:The expansion of LPWAN provides the reliable, real-time connectivity required for process automation in manufacturing and logistics.
Market Restraints
- Protocol Fragmentation:The lack of a universal communication standard complicates system integration and creates vendor lock-in risk for industrial operators.
- FCC Spectrum Constraints:Rules from the US Federal Communications Commission on wireless spectrum limit technology choices and can increase IIoT network deployment costs.
- Legacy System Integration:High costs and operational risks in connecting new platforms to aging industrial control systems slow adoption in established factories.
Strategic Opportunities
- Mexico's Manufacturing Base:Deploying asset tracking and production monitoring solutions in Mexico’s automotive manufacturing sector presents a key expansion opportunity.
- Water Utility Modernization:IIoT for leak detection and quality sensing is an underpenetrated application within municipal water and wastewater utilities.
- Digital Twin Convergence:Integrating IIoT sensor data with digital twin platforms enables advanced predictive modeling for complex manufacturing assets.
Industry Challenges
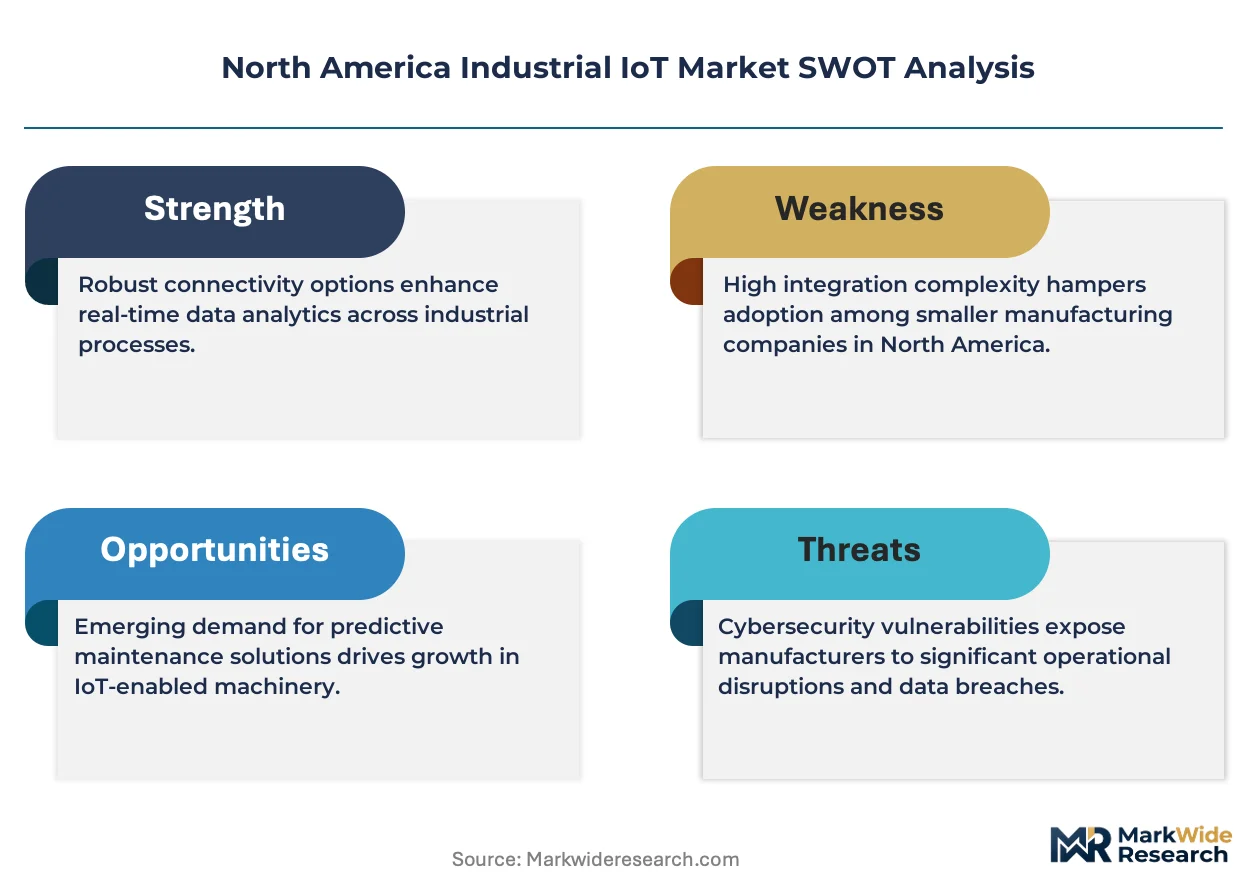
- Endpoint Security:Securing thousands of distributed IIoT devices in critical infrastructure against cyber threats is a primary operational challenge, guided by CISA frameworks.
- Hybrid Skills Shortage:A lack of personnel with combined expertise in operational technology (OT) and IT data management constrains effective IIoT system deployment and maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial IoT Market |
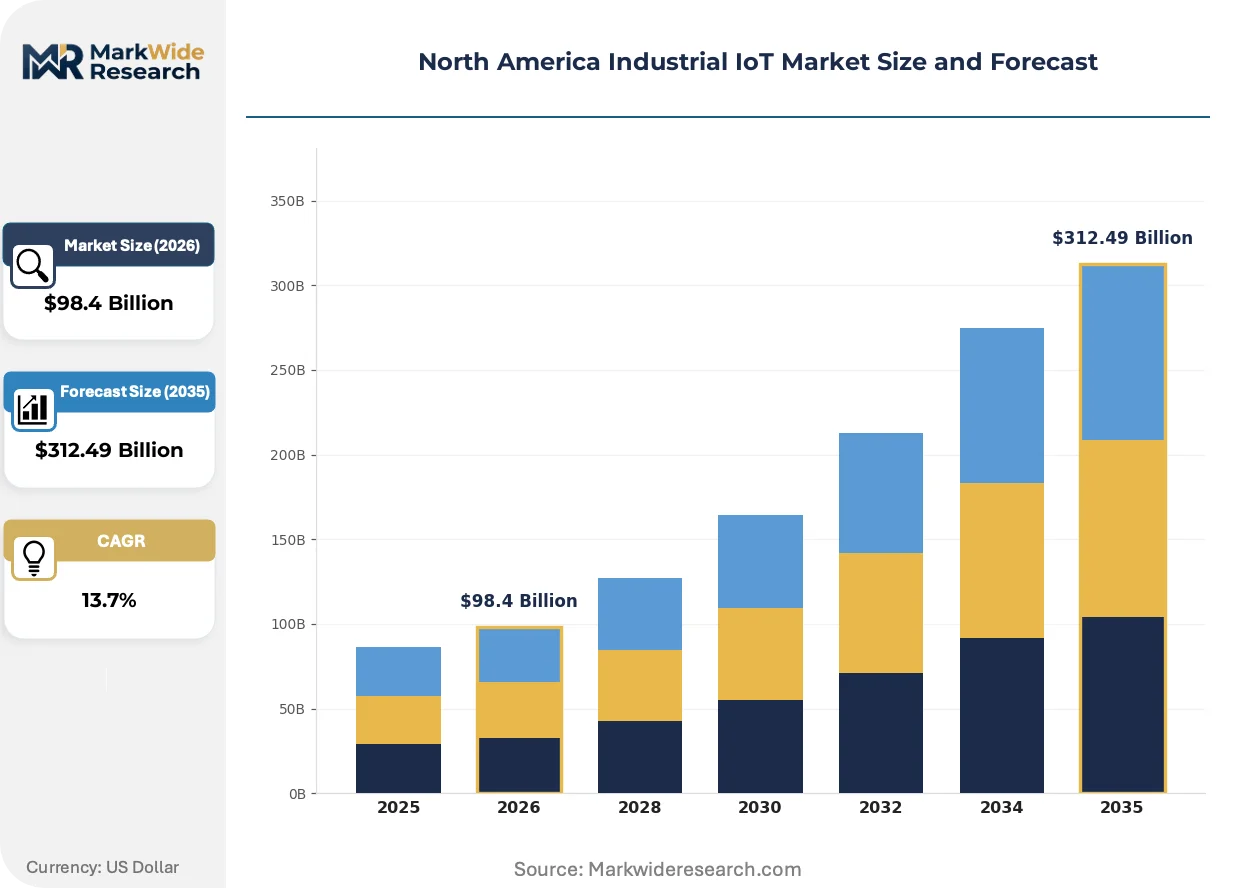
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $312.49 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Devices, Sensors, PLCs, Gateways Technology: LPWAN, Zigbee, Bluetooth, RFID End User: Manufacturing, Oil & Gas, Chemicals, Utilities Application: Predictive Maintenance, Asset Tracking, Process Automation, Supply Chain Management |
| Companies Covered | General Electric, Cisco Systems, IBM Corporation, Intel Corporation, Honeywell International, Rockwell Automation, Emerson Electric, ABB, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial IoT Market Strategic Shifts & Innovations
A core transformation in the North America Industrial IoT market involves moving intelligence from centralized clouds to the network edge. This shift enables more autonomous, low-latency control within industrial environments, altering operational models.
Edge computing hardware, including ruggedized gateways, provides localized data analysis. Manufacturing and utilities sectors adopt this technology for sub-second latency requirements in real-time control. This adoption is decentralizing analytics from remote data centers to the factory floor, enabling faster operational decisions.
The US Inflation Reduction Act creates powerful financial incentives for deploying IIoT. Its tax credits accelerate capital investment into smart factory and clean energy projects that depend on sensor networks. The utilities sector is responding most quickly, fast-tracking grid modernization programs.
Industrial operators are moving from one-time capital purchases to subscription-based "as-a-service" contracts. This model disrupts traditional equipment sales, favoring vendors who bundle hardware, software, and analytics into outcome-based agreements. The trend is prominent in the US Midwest's heavy equipment manufacturing sector.
North America Industrial IoT Market Segmentation
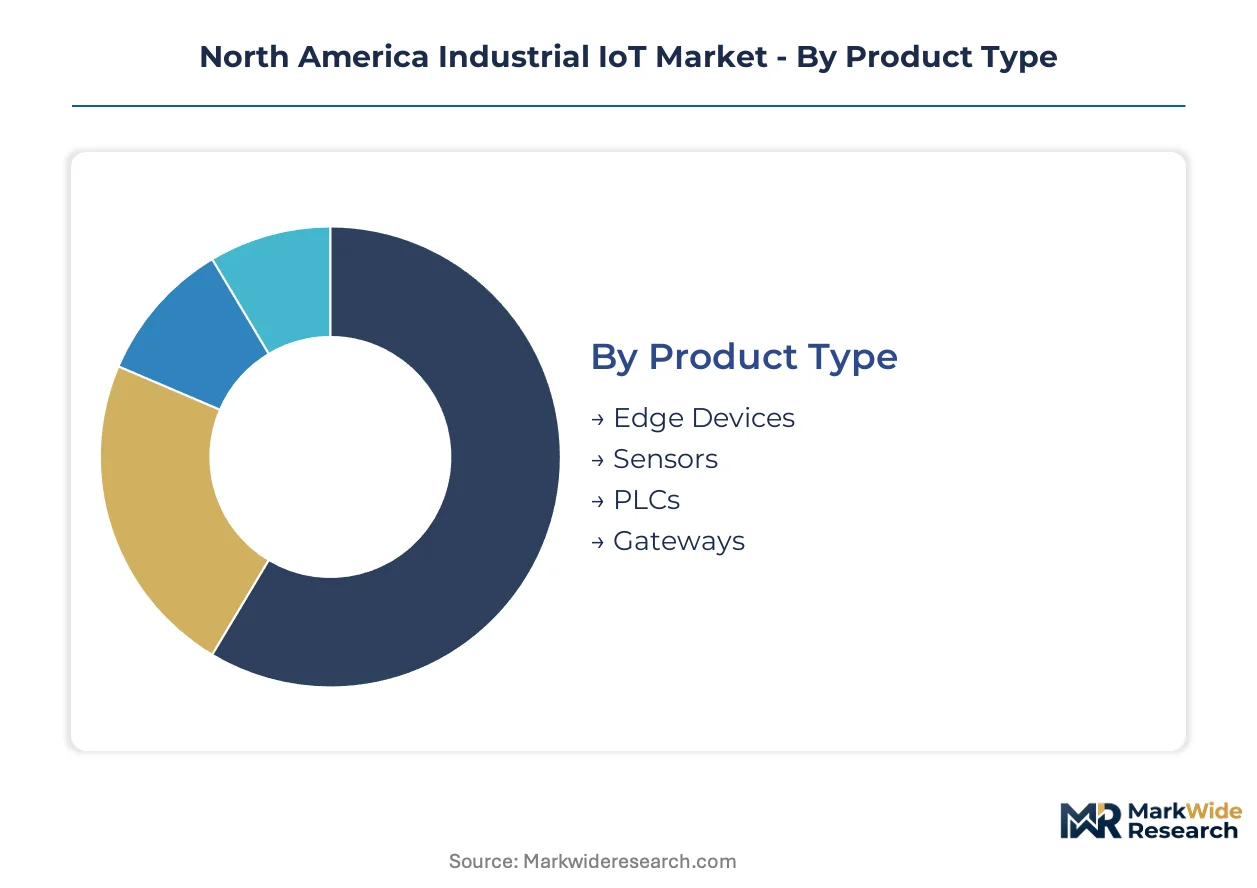
The North America Industrial IoT market exhibits distinct characteristics across its various segments, reflecting the diverse operational needs and regulatory environments of industrial sectors. Understanding these segmentations is crucial for identifying targeted growth opportunities and tailoring IIoT solutions to specific industry challenges.
Product Type:
The varying regulatory compliance burdens from entities like the FCC significantly influence the selection and deployment of different IIoT product types in North America.
- Edge Devices:These ruggedized computing units perform localized data processing and analytics, reducing latency and bandwidth usage in industrial environments. Demand concentrates in the US manufacturing sector, driven by requirements for real-time control and data privacy compliance.
- Sensors:These components detect and measure physical parameters such as temperature, pressure, or vibration, converting them into digital signals. The North American utilities sector drives significant demand for environmental monitoring sensors, often requiring specific EPA certifications for deployment.
- PLCs:Programmable Logic Controllers manage automated processes in factories, integrating directly into legacy industrial control systems.
- Gateways:These devices bridge industrial networks with cloud platforms, facilitating data aggregation and secure transmission between disparate protocols.
Edge Devices sits at the top of the volume ranking, with **Sensors** climbing the fastest.
Technology:
The deployment of IIoT technologies in North America often hinges on the total cost of ownership, influencing choices across different connectivity standards.
- LPWAN:Low-Power Wide-Area Networks offer long-range communication with minimal power consumption, ideal for geographically dispersed assets and remote monitoring. The US utilities sector widely adopts LPWAN for smart grid applications, driven by its efficiency in transmitting small data packets over vast areas.
- Zigbee:This low-power, short-range wireless technology forms mesh networks, enabling robust communication among devices in localized industrial settings. Demand is strong in North American smart factory deployments, where it supports dense sensor arrays for process automation.
- Bluetooth:Bluetooth facilitates short-range, peer-to-peer connectivity for IIoT applications, often used for local data transfer and device configuration.
- RFID:Radio-Frequency Identification tags enable automated asset tracking and inventory management within warehouses and production lines.
The margin profile for **LPWAN** solutions remains robust, while **RFID** technology faces pressure from alternative tracking methods.
End User:
Diverse end-user sectors in North America adopt IIoT solutions based on their specific operational application requirements and existing infrastructure.
- Manufacturing:This sector leverages IIoT for process automation, quality control, and predictive maintenance across assembly lines and discrete production. The US automotive industry, particularly in the Midwest, drives significant IIoT investment to optimize production efficiency and reduce downtime.
- Utilities:IIoT transforms grid management, enabling real-time monitoring of infrastructure, leak detection, and demand-side management for energy and water. Modernization efforts in North American power grids, spurred by the US Inflation Reduction Act, accelerate IIoT deployment for enhanced reliability.
- Oil & Gas:The sector utilizes IIoT for remote asset monitoring, pipeline integrity management, and optimizing extraction processes in challenging environments.
- Chemicals:IIoT supports process optimization, safety monitoring, and environmental compliance within chemical plants, managing hazardous materials and complex reactions.
Manufacturing maintains a steady growth trajectory, with **Utilities** demonstrating an accelerated expansion due to policy incentives.
Application:
Different customer types within North America prioritize IIoT applications based on their immediate operational pain points and return on investment potential.
- Predictive Maintenance:This application utilizes sensor data and analytics to forecast equipment failures, minimizing unplanned downtime and extending asset lifecycles. The North American automotive sector heavily invests in predictive maintenance to maximize production line uptime and reduce operational costs.
- Process Automation:IIoT enables automated control and optimization of industrial processes, from discrete manufacturing to continuous flow operations. Demand in the US aerospace industry focuses on achieving higher precision and consistency in complex assembly tasks.
- Asset Tracking:This application provides real-time location and status monitoring of equipment, vehicles, and inventory across industrial facilities and supply chains.
- Supply Chain Management:IIoT enhances visibility across the supply chain, tracking goods, monitoring environmental conditions, and optimizing logistics from raw materials to delivery.
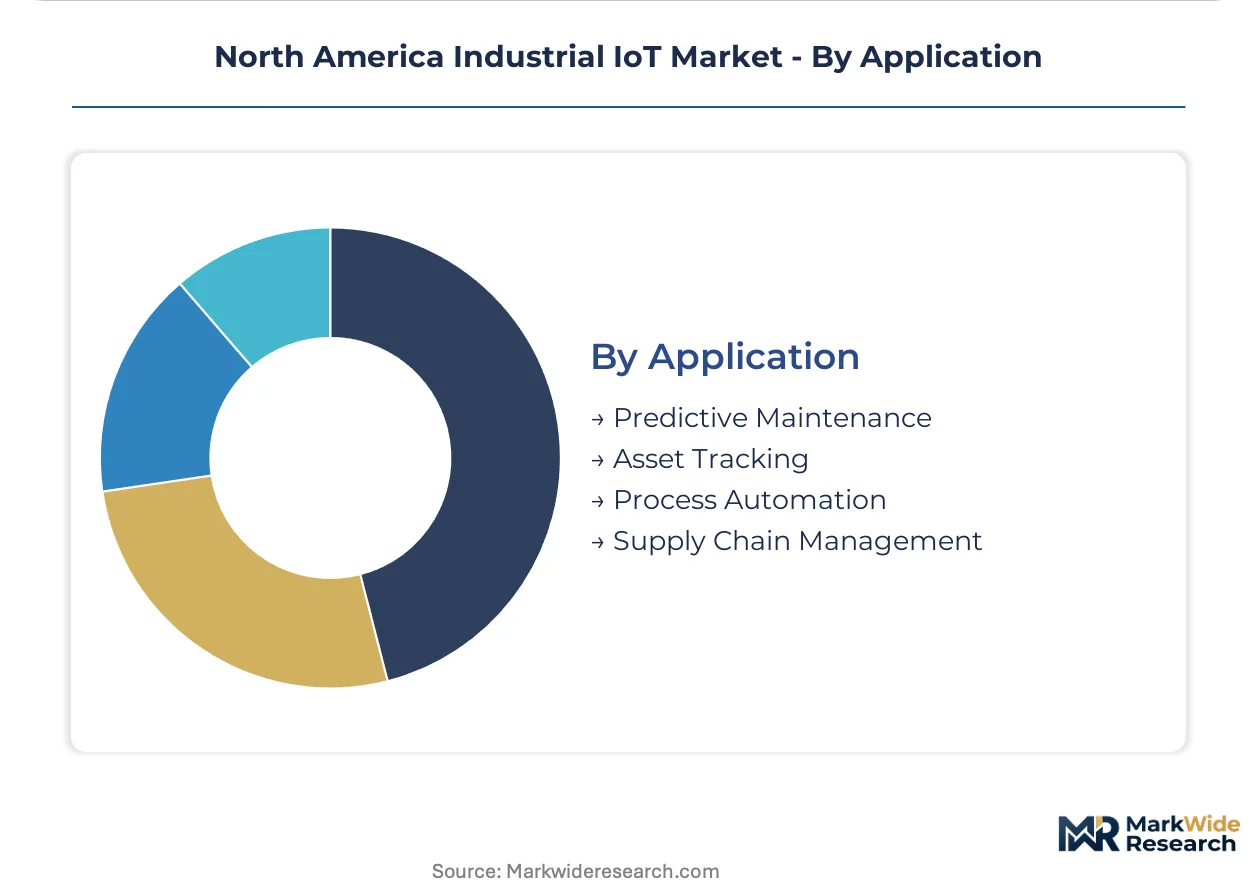
Predictive Maintenance exhibits a high adoption rate, while **Asset Tracking** is gaining traction in logistics-intensive industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US automotive sector drives significant IIoT demand across North America, particularly for optimizing production efficiency. Investment is further accelerated by policy incentives like the US Inflation Reduction Act. Regional dynamics shape technology choices and deployment strategies.
United States
Predictive maintenance applications for manufacturing assets drive IIoT adoption across the United States. The US Inflation Reduction Act accelerates smart factory and clean energy infrastructure investments. Automotive and aerospace manufacturing clusters in the Midwest and Southeast concentrate demand for asset tracking and process automation solutions.
Canada
Canadian utilities seek IIoT solutions for grid modernization and remote asset monitoring, enhancing operational reliability. Regulatory frameworks from federal agencies guide wireless spectrum allocation and cybersecurity standards for critical infrastructure. Industrial hubs in Ontario and Quebec deploy IIoT for process optimization in discrete manufacturing.
Mexico
Mexico's expanding manufacturing base demands IIoT for production monitoring and supply chain optimization, particularly in export-oriented sectors. Government initiatives support industrial digitization efforts to enhance global competitiveness. Automotive assembly plants in the Bajío region leverage IIoT for asset tracking and quality control.
US Midwest
The US Midwest heavy equipment manufacturing sector prioritizes IIoT for outcome-based "as-a-service" contracts. State-level incentives complement federal policies to encourage smart factory deployments. Industrial clusters in Michigan and Ohio focus on maximizing asset uptime through advanced predictive analytics.
US Southeast
Aerospace and defense manufacturing in the US Southeast drives demand for high-precision IIoT applications and process automation. Federal cybersecurity guidelines from CISA influence secure-by-design architectures for critical infrastructure. Manufacturing facilities in Georgia and South Carolina implement IIoT for real-time control and quality assurance.
North America Industrial IoT Market Key Industry Players
Global majors compete with regional champions across IIoT solution deployment in North America, leading to a dynamic market structure. The market exhibits a tiered structure, with established industrial automation vendors alongside specialized networking and software providers. Strategic archetypes include comprehensive platform providers, niche edge computing specialists, and connectivity infrastructure suppliers. Companies actively pursue strategic partnerships and portfolio diversification to capture market share and address fragmented technology standards.
Within the comprehensive platform provider archetype, Cisco Systems and Honeywell International exemplify established players leveraging extensive domain expertise. Cisco Systems, a networking hardware specialist, captures value at the network edge with its robust portfolio. Honeywell International extends its process control heritage to offer integrated IIoT platforms. Rockwell Automation represents a specialized industrial automation vendor, integrating edge devices directly into control systems for manufacturing clients.
| Leading Market Players |
|---|
| General Electric |
| Cisco Systems |
| IBM Corporation |
| Intel Corporation |
| Honeywell International |
| Rockwell Automation |
| Emerson Electric |
| ABB |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Outsourced component manufacturing for specialized IIoT hardware anchors the supply position for many North American vendors, influencing their pricing power for integrated solutions. This model allows for cost efficiencies but introduces dependencies on global supply chains.
Pricing Analysis
Input costs for specialized sensors and edge computing hardware influence IIoT solution pricing across North America. The dominant pricing model is shifting towards subscription-based "as-a-service" contracts, particularly in the US Midwest heavy equipment manufacturing sector. Price differentiation stems from customization level and the extent of after-sales service bundled into outcome-based agreements. Pricing pressure stems from increasing standardization efforts and the need to integrate with diverse legacy systems. The US automotive sector, focused on maximizing uptime, is less price-sensitive than municipal utilities prioritizing initial capital expenditure.
Supply Chain Analysis
Domestic content mandates, particularly from US government incentives, reshape sourcing strategies for IIoT hardware within North America. Geographic supply concentration for key components like semiconductors and specialized sensors primarily lies in Asia, with assembly and integration occurring in the United States, Mexico, and Canada. The supply chain relies on a stable flow of networking components and ruggedized enclosures. A structural risk involves single-source vulnerability for advanced edge processors. Distribution runs through a mix of direct sales channels and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Industrial IoT market presents a compelling margin expansion story, driven by the shift towards outcome-based "as-a-service" contracts that command premium pricing.
For Market Incumbents: Anchor existing client relationships by deepening integration of IIoT solutions into legacy industrial control systems. Expand comprehensive IIoT platforms to counter niche edge computing entrants. Invest in R&D for secure-by-design architectures to mitigate cybersecurity threats. Reinforce channel control through strategic partnerships with system integrators.
For New Entrants and Emerging Players: The US Inflation Reduction Act in the United States opens a window for specialized IIoT providers focusing on smart grid modernization. Target underpenetrated applications like water utility modernization for leak detection and quality sensing. Offer subscription-based "as-a-service" models to lower entry barriers for municipal utilities. Focus on Mexico's manufacturing base for asset tracking solutions.
For Investors and Strategic Acquirers: Consolidation pressure builds where protocol fragmentation creates integration challenges for industrial operators. The market offers sustained long-term growth driven by operational efficiency gains across industrial sectors. Target niche edge computing specialists or cybersecurity solution providers with strong domain expertise. Increased adoption of digital twin platforms serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating IIoT platforms with existing enterprise systems enhances data utility for manufacturing clients. |
| Geographic Expansion | Expanding into Mexico's automotive manufacturing sector captures new production monitoring demand. |
| Strategic Partnership | Partnering with cybersecurity firms addresses endpoint security challenges in critical infrastructure. |
| Product Launch | Introducing ruggedized gateways tailored for specific industrial environments meets demand for localized processing. |
| Green Manufacturing Transition | Developing IIoT solutions for clean energy infrastructure aligns with US Inflation Reduction Act incentives. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and proprietary databases — were reconciled to construct a robust market view. Primary engagement involved discussions with plant managers, IT directors, OT engineers, and cybersecurity specialists across North America. Secondary validation drew from FCC filings, CISA guidelines, industry association reports, and financial disclosures, ensuring comprehensive data coverage. Bottom-up and top-down triangulation methods were applied to ensure data consistency.
Historical market performance was cross-referenced against expert panel input to project future market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, end-user, application, and regional regulatory environment. Compound annual growth rates were derived from historical trends and expert panel projections. Key industry-specific forecast inputs included US Inflation Reduction Act incentives and manufacturing output forecasts for the automotive sector.
Revisions become necessary when unforeseen regulatory shifts or major technological breakthroughs materialize within the IIoT ecosystem. Forecasts reflect assumptions on regulatory stability, technological advancement, and economic growth. Significant shifts in FCC spectrum allocation, CISA cybersecurity mandates, or global supply chain disruptions pose key risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
IoT Smart Poles Market