
 Internet of Things (IoT) Platform Market | 2026-2036
Internet of Things (IoT) Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) Platform Market Insights
Cloud marketplace distribution is tilting toward integrated IoT stacks as enterprises consolidate vendor relationships. Microsoft Azure leverages its industrial cloud partnerships to anchor manufacturing deployments. Amazon Web Services sustains dominance in connected-device data pipelines through specialized edge-to-cloud infrastructure. Siemens competes with embedded platform offerings that merge operational technology interfaces with IT-native architectures.
An Internet of Things platform constitutes a middleware software layer that ingests telemetry from distributed sensors and actuators, processes streams through protocol adapters such as MQTT and CoAP, and exposes device management APIs to enterprise applications. The platform serves primarily to abstract hardware heterogeneity and enable scalable remote monitoring across operational environments. Public cloud deployment captures the largest revenue pool given elastic infrastructure economics, while private cloud and hybrid configurations expand fastest among regulated sectors requiring data sovereignty. Industrial automation applications command premium pricing due to uptime guarantees and predictive maintenance integrations, whereas smart home deployments operate on thinner margins at higher volumes.
FDA cybersecurity guidance for connected medical devices, EU GDPR data-localization mandates, and China's GB standards for IoT terminal security collectively elevate compliance costs for cross-border platform operators. The EU AI Act introduces additional algorithmic transparency requirements when IoT platforms embed automated decision-making for critical infrastructure. Stakeholders must weigh jurisdictional fragmentation against unified platform architectures when prioritizing R&D allocation and market entry sequencing.
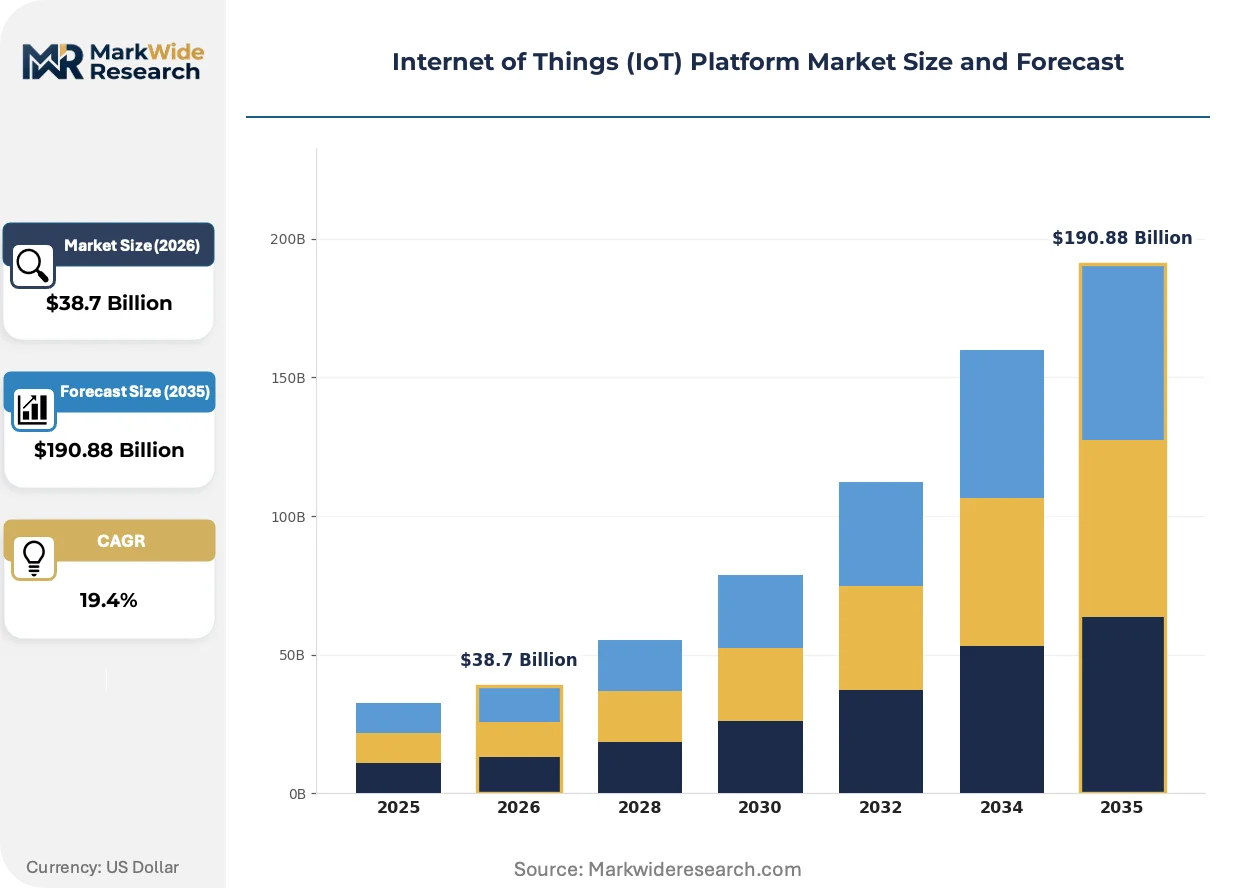
Market Dynamics
Cloud-native architectures are compressing deployment timelines for industrial IoT platforms while EU AI Act compliance mandates force algorithmic transparency investments that reshape vendor cost structures.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Critical infrastructure operators must deploy explainable AI for automated decisions, creating pull for platforms with built-in audit trails and model documentation capabilities.
- Automotive predictive maintenance integration:Connected vehicle fleets require real-time telemetry processing at scale, driving demand for edge-to-cloud orchestration layers that guarantee sub-100ms latency.
- Germany industrial digitization subsidies:Federal funding programs for Industrie 4.0 adoption lower switching costs for mid-sized manufacturers, accelerating platform procurement cycles.
Market Restraints
- Semiconductor supply concentration in Taiwan:Edge gateway chip shortages create 12-18 month lead times for hardware-dependent platform deployments, forcing customers into extended evaluation phases.
- GDPR data-localization infrastructure costs:Sovereign cloud requirements mandate redundant regional data centers, raising operational expenditure thresholds that exclude price-sensitive smart home segments.
- Legacy SCADA protocol fragmentation:Proprietary industrial communication standards (Modbus, PROFIBUS, EtherNet/IP) require costly protocol adapters that erode platform margin structures.
Strategic Opportunities
- India manufacturing PLI scheme:Production-linked incentives for electronics and automotive sectors create first-mover advantage for platforms offering localized edge infrastructure and rupee-denominated pricing.
- Digital twin convergence with physics simulation:Integration of IoT telemetry with CAD/CAE models enables predictive asset modeling, opening premium service tiers for aerospace and energy verticals.
- China GB standards compliance services:Mandatory IoT terminal security certifications (GB/T 36951, GB/T 38626) create recurring revenue streams for platforms bundling certification support with core subscriptions.
Industry Challenges
- OT-IT cybersecurity skill scarcity:Platform vendors struggle to hire engineers fluent in both Purdue model operational technology and zero-trust cloud security architectures.
- FDA 510(k) cybersecurity documentation:Connected medical device platforms face 14-18 month approval timelines when algorithmic components trigger software-as-medical-device classification.
- Multi-cloud integration complexity:Enterprise customers demand seamless workload portability across AWS, Azure, and GCP, forcing vendors to maintain three parallel certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) Platform Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Manufacturing, Healthcare, Retail, Transportation Technology: LPWAN, Zigbee, Bluetooth, Wi-Fi Application: Smart Homes, Industrial Automation, Asset Tracking, Wearable Technology |
| Companies Covered | Amazon Web Services, Microsoft Azure, IBM Watson, Cisco Systems, Google Cloud, PTC ThingWorx, SAP, Siemens, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) Platform Market Trends and Innovations
Agentic AI architectures are redefining how IoT platforms process telemetry streams, shifting from rule-based automation toward autonomous system optimization that reduces human-in-the-loop requirements.
Containerized microservices at the edge are rendering obsolete monolithic gateway software stacks that required full firmware updates for security patches. Automotive and logistics fleets now deploy Kubernetes-native edge runtimes that enable granular component updates without vehicle downtime. This architecture compresses security response cycles from weeks to hours while reducing memory footprints on resource-constrained devices.
The EU AI Act's risk-based classification system imposes mandatory conformity assessments on IoT platforms deployed in critical infrastructure. High-risk applications must maintain technical documentation, human oversight protocols, and accuracy metrics that platform vendors previously treated as optional. German energy utilities and French water treatment operators are now requiring AI Act compliance certifications in procurement specifications, filtering vendor pools before technical evaluation begins.
Subscription pricing for platform access is displacing perpetual licensing across industrial buyer segments. German automotive suppliers and Japanese electronics manufacturers now prefer consumption-based models that align costs with active device counts rather than upfront capex commitments. This shift pressures legacy platform vendors to restructure revenue recognition while creating entry points for cloud-native competitors with elastic pricing infrastructure.
Internet of Things (IoT) Platform Market Segmentation
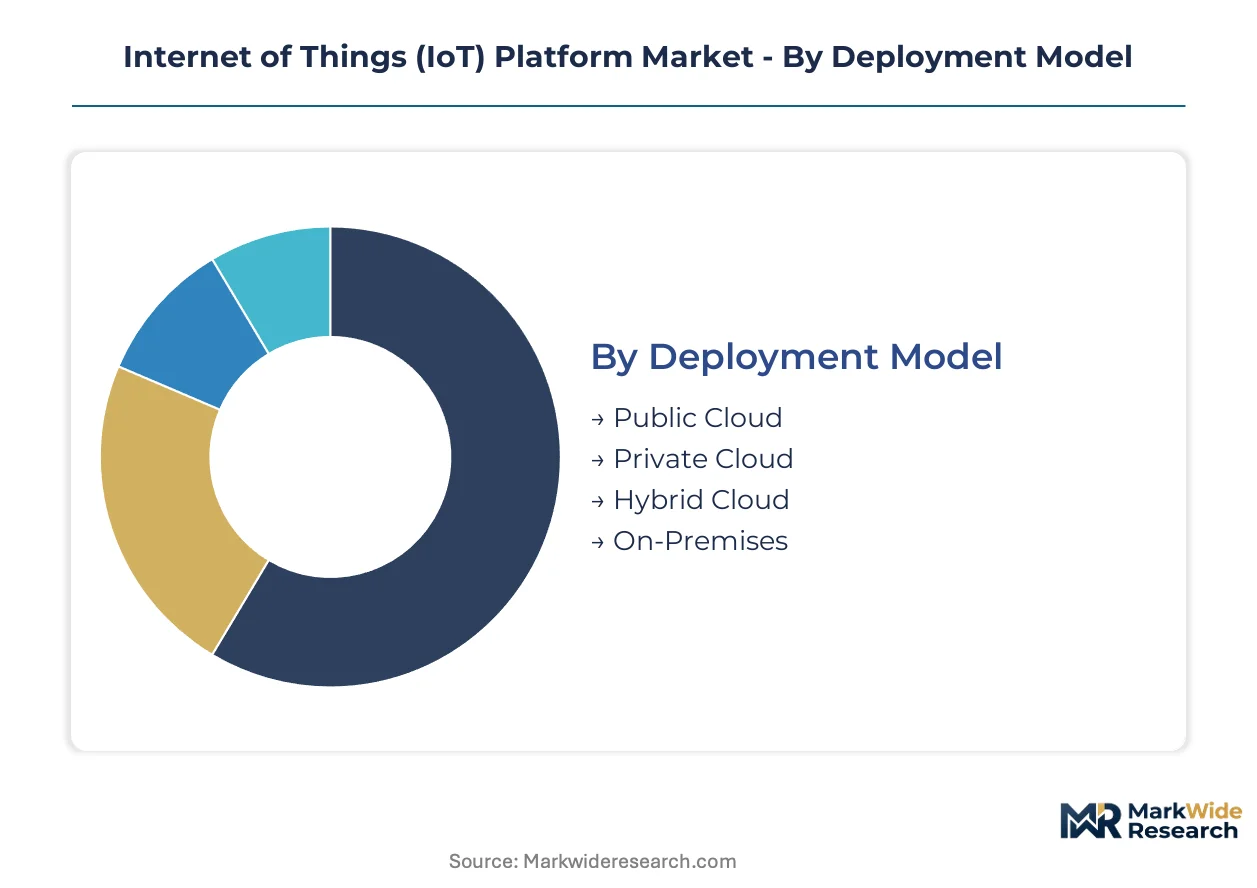
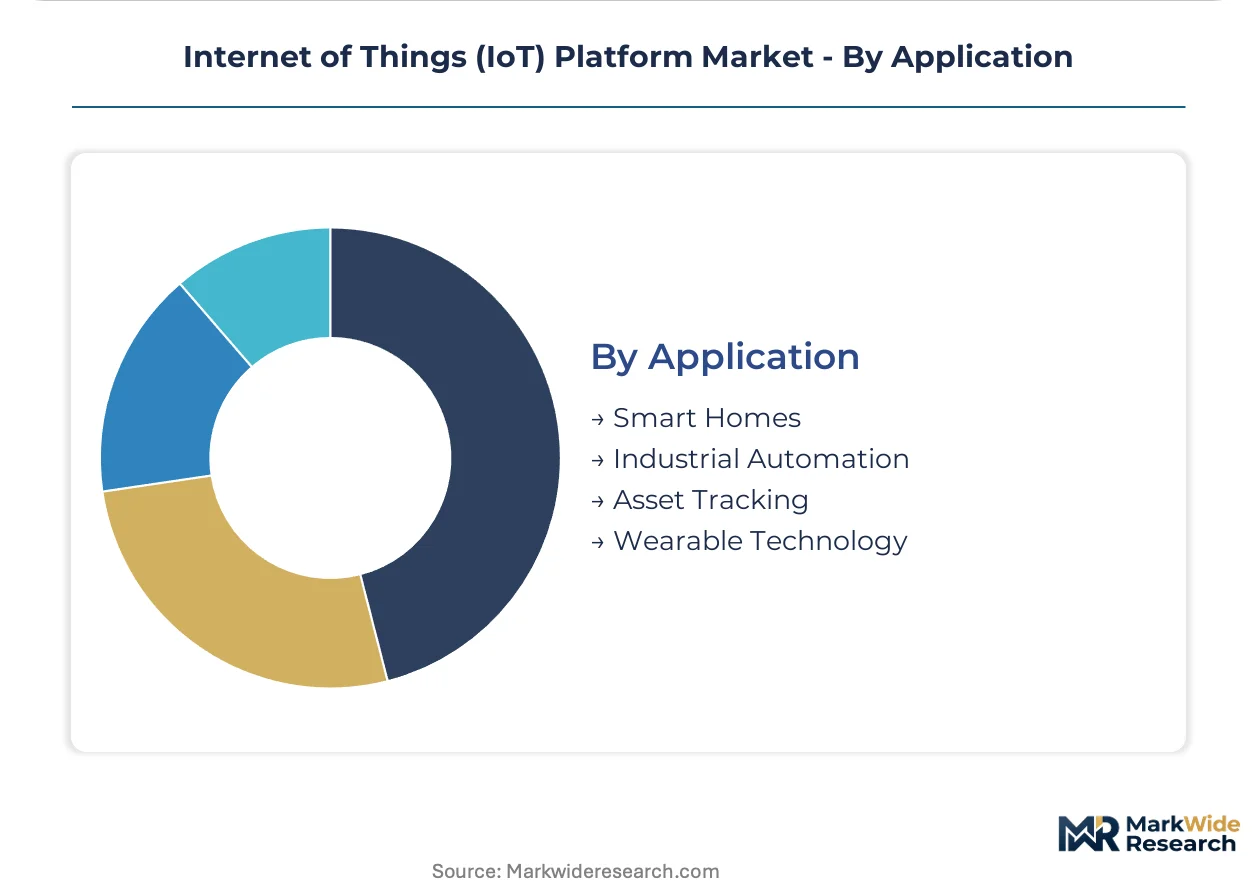
IoT platform segmentation reveals divergent commercial rhythms across deployment architectures and connectivity technologies. Procurement cycles stretch from months for on-premises industrial contracts to days for public cloud smart home pilots. Understanding these velocity differentials shapes vendor resource allocation and partnership prioritization.
Deployment Model:
Cycle times compress from multi-year on-premises negotiations to elastic public cloud provisioning measured in hours.
- Public Cloud:Elastic infrastructure pools enable rapid scaling without capital commitment. German automotive suppliers and Japanese electronics manufacturers favor consumption-based billing that aligns platform costs with active device volumes.
- Private Cloud:Dedicated tenant environments address data sovereignty requirements under GDPR and China's GB standards. French water treatment operators and German energy utilities mandate private deployments for critical infrastructure AI Act compliance.
- Hybrid Cloud:Workload portability across edge and core satisfies latency-sensitive industrial applications.
- On-Premises:Air-gapped installations serve defense and classified manufacturing with zero external connectivity.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
End User:
Customer procurement sophistication spans from standardized healthcare compliance templates to bespoke manufacturing integration requirements.
- Manufacturing:Predictive maintenance integrations command premium pricing due to uptime guarantees. Industrie 4.0 subsidies in Germany accelerate procurement cycles for mid-sized automotive and electronics producers.
- Healthcare:FDA 510(k) cybersecurity documentation extends sales cycles to 14-18 months when algorithmic components trigger software-as-medical-device classification.
- Retail:Inventory visibility and cold chain monitoring drive demand for low-cost, high-volume device management.
- Transportation:Connected vehicle fleets require sub-100ms latency orchestration layers.
Manufacturing anchors the volume base while healthcare gains share at the steepest rate.
Technology:
Connectivity economics stratify from cellular-licensed premiums to unlicensed spectrum deployments at minimal marginal cost.
- LPWAN:Narrowband protocols optimize battery life for distributed asset tracking across logistics networks. Low infrastructure requirements enable rapid deployment in India manufacturing zones under PLI scheme incentives.
- Zigbee:Mesh networking protocols dominate smart home ecosystems with self-healing topology.
- Bluetooth:Proximity-based protocols serve wearable technology and indoor positioning with minimal power draw.
- Wi-Fi:High-throughput connectivity supports video-rich industrial automation and surveillance applications.
Wi-Fi anchors the volume base while LPWAN gains share at the steepest rate.
Application:
Margin structures diverge sharply between consumer volume plays and industrial premium service tiers.
- Industrial Automation:SCADA protocol adapters and predictive maintenance integrations command substantial platform premiums. Aerospace and energy verticals open premium service tiers through digital twin convergence with physics simulation.
- Smart Homes:Thin margins at high volumes characterize thermostat, lighting, and security device management.
- Asset Tracking:Logistics and supply chain visibility drive demand for geolocation-tagged telemetry processing.
- Wearable Technology:Health monitoring and workforce safety applications require continuous biometric stream processing.
Smart homes anchor the volume base while industrial automation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber-optic cable landing stations at Cork and Dublin anchor Ireland's role as a data transit hub for European IoT platform traffic, while the NordLink interconnector enables Norway's edge computing facilities to leverage surplus hydroelectric capacity for low-carbon data processing.
United States
Automotive predictive maintenance integration and connected vehicle fleet expansion drive platform procurement from Detroit-based suppliers. FDA cybersecurity guidance for connected medical devices extends sales cycles for healthcare IoT deployments. The Dallas-Fort Worth metroplex hosts concentrated edge data center infrastructure serving oilfield automation and logistics verticals.
Germany
Industrie 4.0 federal subsidies accelerate platform adoption among mid-sized automotive and electronics manufacturers in Baden-Württemberg. EU AI Act algorithmic transparency mandates reshape procurement specifications for critical infrastructure operators. Munich and Stuttgart industrial clusters demand edge-to-cloud orchestration layers with sub-100ms latency guarantees for smart factory deployments.
China
GB standards for IoT terminal security (GB/T 36951, GB/T 38626) create mandatory certification requirements for platform vendors serving state-owned enterprises. MIIT industrial internet initiatives channel investment toward Yangtze River Delta manufacturing zones. Shenzhen's electronics ecosystem generates high-volume demand for low-cost device management solutions across consumer and industrial segments.
India
Production-linked incentive schemes for electronics and automotive manufacturing create first-mover opportunities for platforms offering localized edge infrastructure. TRAI spectrum allocation for unlicensed LPWAN protocols enables rapid deployment in Gujarat and Tamil Nadu industrial corridors. Bangalore's technology cluster drives demand for cloud-native IoT stacks among IT services exporters integrating operational technology offerings.
Internet of Things (IoT) Platform Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cloud-native stacks that merge infrastructure, platform, and application layers into unified subscriptions. Hyperscale cloud providers anchor the volume tier through elastic consumption models, while industrial automation specialists command premium positioning through embedded operational technology interfaces. Strategic moves concentrate on vertical acquisition targets with proprietary protocol adapters and multi-cloud certification tracks that reduce customer switching costs.
Among hyperscale cloud providers, Amazon Web Services and Microsoft Azure exemplify the infrastructure-first archetype, leveraging global data center footprints to capture connected-device data pipeline workloads. IBM Watson occupies a position within the enterprise AI integration tier, representing vendors that bundle explainable AI capabilities to satisfy EU AI Act compliance requirements for critical infrastructure deployments.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| IBM Watson |
| Cisco Systems |
| Google Cloud |
| PTC ThingWorx |
| SAP |
| Siemens |
| Oracle |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's electronics manufacturing cluster compresses component lead times for edge gateway hardware, translating into pricing leverage for platform vendors that secure preferential allocation from local contract manufacturers serving industrial IoT deployments.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade platforms with EU AI Act compliance documentation from mid-market offerings and basic device management tiers. Certification-grade differentiation anchors premium positioning, with FDA-cleared and GB/T 36951-certified deployments commanding substantial uplifts over uncertified alternatives. Cost compression in the smart home tier intensifies as Shenzhen-based hardware commoditizes gateway components, while industrial buyers show lowest price sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Supply-chain finance facilities from Taiwanese semiconductor foundries and Chinese EMS providers extend payment terms for platform vendors managing 12-18 month chip allocation cycles. Component sourcing draws from Taiwan for edge processors, South Korea for memory modules, and China for passive components. Single-source vulnerability concentrates in advanced node semiconductors. Distribution runs through hyperscaler marketplaces and industrial automation channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform vendors face acute scarcity of engineers fluent in both Purdue model operational technology and zero-trust cloud architectures, constraining delivery capacity for complex industrial deployments.
For Market Incumbents: Harden edge-to-cloud orchestration capabilities through backward integration into containerized microservices runtime development, defending against cloud-native entrants with elastic pricing infrastructure. Prioritize EU AI Act conformity assessment pre-certification to filter vendor pools before German energy utilities and French water treatment operators issue RFPs. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing corridors by bundling localized edge infrastructure with rupee-denominated consumption billing. Target mid-sized automotive suppliers in Gujarat and Tamil Nadu with Kubernetes-native deployments that compress security response cycles from weeks to hours. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because industrial automation specialists with proprietary SCADA protocol adapters command durable premium positioning against infrastructure-first hyperscalers. Watch FDA 510(k) cybersecurity documentation timelines as an inflection signal—extended approval cycles for software-as-medical-device classifications indicate tightening regulatory moats.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merges operational technology interfaces with IT-native architectures for German Industrie 4.0 deployments. |
| Acquisition of Specialist Firm | Captures proprietary Modbus and EtherNet/IP protocol adapters that erode margin structures for generic vendors. |
| Geographic Expansion | Positions localized edge infrastructure in India's Gujarat corridor under PLI scheme incentives. |
| Regulatory Certification Program | Builds recurring revenue streams from mandatory GB/T 36951 and EU AI Act compliance services. |
| Strategic Partnership | Secures sub-100ms latency guarantees through Dallas-Fort Worth edge data center colocation. |
Research Methodology
Operator-level perspectives from IoT platform engineers, industrial automation procurement leads, OT-IT integration specialists, and hyperscaler marketplace managers anchored the qualitative base. Secondary validation drew from SEC filings of cloud infrastructure providers, ETSI technical specifications, FDA cybersecurity guidance documents, and EU AI Act implementing acts. Bottom-up device count estimates and top-down enterprise IT spending analysis were triangulated to anchor market sizing.
Scenario-bracketing framed demand projections across the analysis window, modeling deployment architecture splits, connectivity technology adoption curves, and end-user vertical penetration. Segmentation dimensions included deployment model elasticity, protocol complexity tiers, and regional regulatory cluster stringency. CAGRs were derived from logistic diffusion curves fitted to historical platform procurement data, with inputs from industrial digitization subsidy disbursement trajectories and semiconductor capacity expansion announcements.
Stress conditions across edge gateway chip allocation cycles, GDPR data-localization infrastructure buildout rates, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsidy program continuity and certification timeline stability. Macroeconomic contraction, regulatory fragmentation, or generative AI disruption of telemetry processing economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
IoT in Energy Market