
 IoT Utilities Market | 2026-2036
IoT Utilities Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Utilities Market Analysis
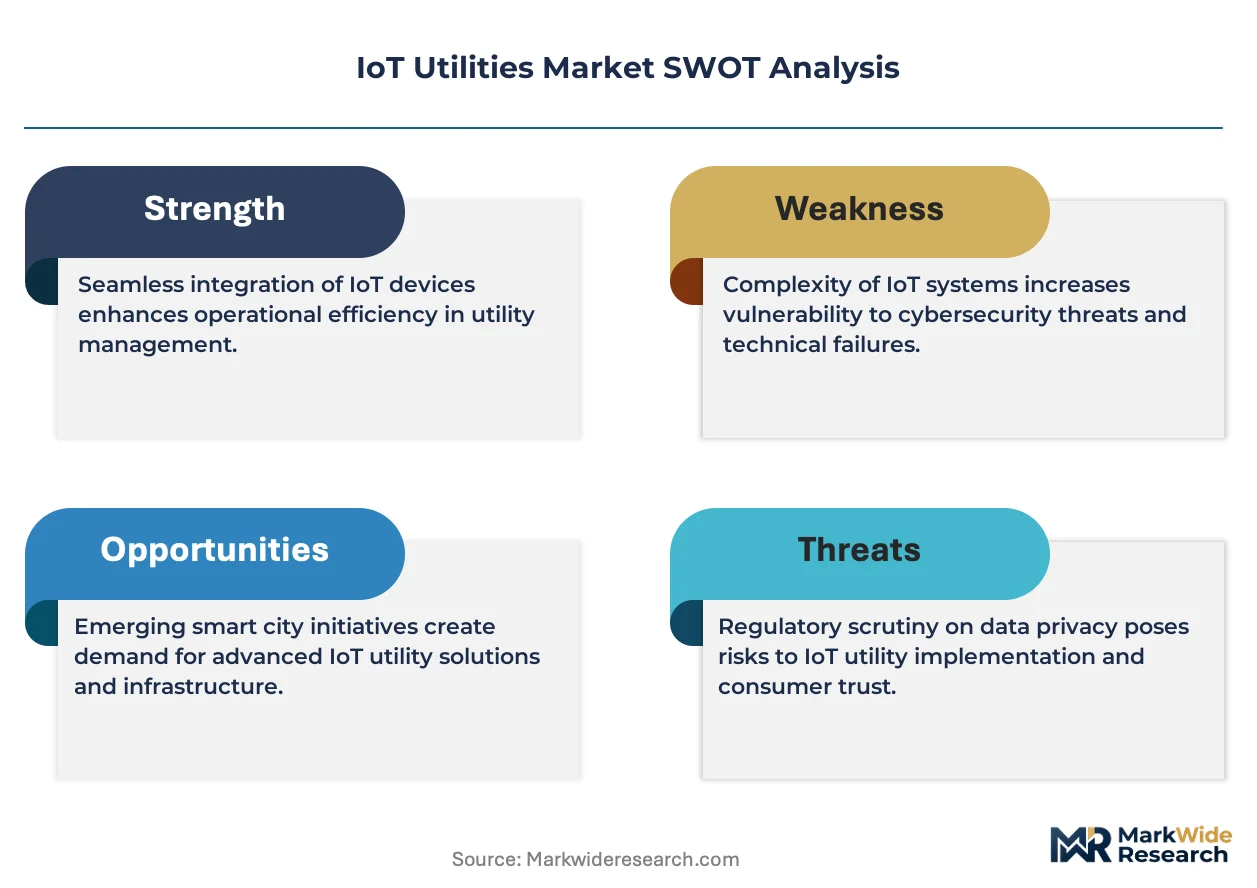
The gap between premium cybersecurity-hardened platforms and commodity meter hardware is hardening as utility procurement teams separate operational-technology budgets from IT-analytics spending. Cisco Systems leverages its industrial networking pedigree to dominate edge-computing deployments for grid operators. Siemens anchors its position through captive manufacturing of ruggedized sensors purpose-built for substation environments.
IoT Utilities denotes interconnected sensor, communication, and analytics infrastructure deployed across electricity, water, and gas distribution systems, typically operating over LPWAN, cellular, or fiber protocols with latency requirements under 100 milliseconds for real-time grid balancing. Smart meters and sensor networks occupy the mature volume tier where hardware margins compress, while data analytics commands expanding margin pools as utilities monetize predictive load-forecasting services. Communication protocols represent the fastest-growing technology segment as multi-protocol gateways proliferate to bridge legacy SCADA with cloud-native architectures.
The Federal Energy Regulatory Commission in the United States mandates cybersecurity standards for bulk power system assets, directly shaping procurement specifications for connected grid infrastructure. Europe's Cyber Resilience Act and CE marking requirements for radio equipment are tightening market access for non-compliant IoT device vendors. China's MIIT issues GB standards for industrial IoT communication that dictate interoperability testing for foreign suppliers seeking utility contracts. Stakeholders must monitor which regulatory jurisdiction's certification timeline becomes the critical-path gate for multi-country product rollouts.
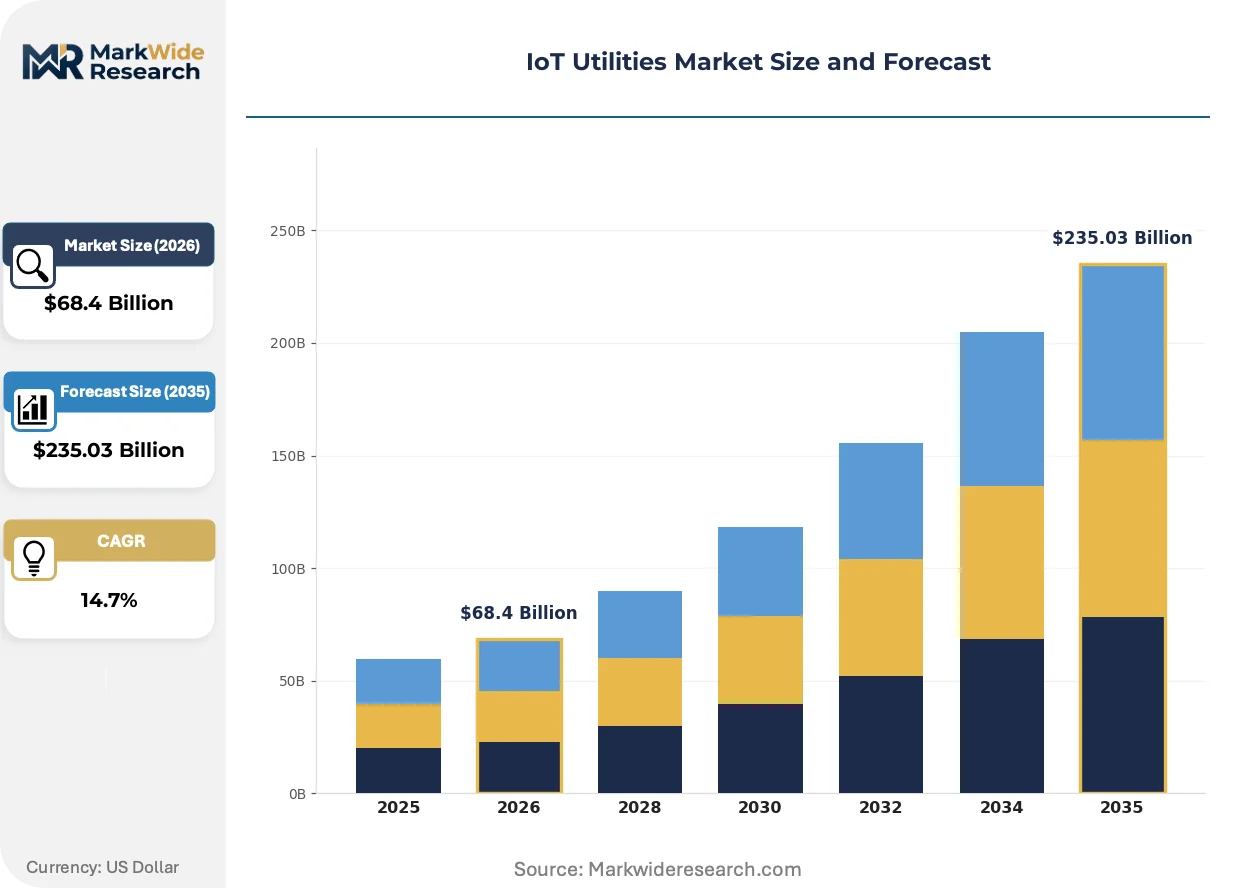
Market Dynamics
The bifurcation of utility procurement budgets into operational-technology hardware and IT-analytics software is restructuring vendor relationships and margin distribution across the IoT utilities value chain.
Growth Catalysts
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon refrigerants is compelling utilities to deploy sensor networks for real-time leak detection and automated compliance reporting across substation infrastructure.
- Water quality mandates:Municipal utilities in the Rhine-Ruhr corridor are expanding dissolved oxygen and turbidity sensor deployments to meet tightening effluent standards under the EU Green Deal.
- Edge computing architectures:Grid operators are installing multi-protocol gateways that bridge legacy SCADA systems with cloud-native platforms, reducing latency for real-time load balancing below 100 milliseconds.
Market Restraints
- Semiconductor supply concentration:Ruggedized sensor production depends on specialized foundry capacity concentrated in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Cellular module cost volatility:NB-IoT and LTE-M radio modules face pricing pressure from memory chip shortages and rare earth magnet supply constraints.
- Interoperability friction:China's GB standards for industrial IoT communication impose mandatory interoperability testing that extends certification timelines for foreign suppliers.
Strategic Opportunities
- Predictive load forecasting:Data analytics platforms monetize AI-driven demand prediction services to commercial and industrial electricity customers seeking tariff optimization.
- LPWAN network convergence:LoRaWAN and Sigfox infrastructure rollouts in secondary German cities are opening sensor deployment opportunities outside capital-intensive cellular coverage zones.
- Cybersecurity certification premiums:FERC-mandated cybersecurity standards for bulk power systems create pricing power for vendors with pre-certified, hardened platform architectures.
Industry Challenges
- OT-IT integration complexity:Utilities struggle to merge operational technology teams managing physical infrastructure with IT departments overseeing cloud analytics, creating procurement deadlock.
- Multi-jurisdiction certification timelines:Vendors must synchronize CE marking under Europe's Cyber Resilience Act with FERC compliance and China's GB testing, making regulatory timeline alignment the critical path for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Utilities Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $235.03 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Meters, Sensor Networks, Data Analytics, Communication Protocols Application: Energy Management, Water Quality Monitoring, Grid Management, Predictive Maintenance End User: Utility Companies, Government Agencies, Industrial Operators, Residential Consumers Installation: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Cisco Systems, Inc., IBM Corporation, General Electric Company, Siemens AG, Microsoft Corporation, Huawei Technologies, SAP SE, Honeywell International Inc., Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Utilities Market Emerging Trajectories
Digital twin architectures and AI-driven asset management are displacing scheduled maintenance regimes with condition-based intervention models across electricity, water, and gas distribution networks.
Digital twin platforms for substation equipment are automating thermal monitoring and fault prediction. German transmission operators are deploying these systems at scale across the Rhine-Ruhr corridor. The technology is automating workforce allocation decisions that previously required manual inspection rounds.
The EU Cyber Resilience Act mandates security-by-design requirements for connected devices with network functionality. Hardware vendors must embed update mechanisms and vulnerability disclosure processes from product conception. Grid sensor manufacturers targeting European utility procurement are re-engineering firmware architectures to satisfy CE marking prerequisites.
Subscription-based analytics licensing is displacing perpetual software purchases in utility procurement departments. European water utilities are piloting outcome-based contracts tying vendor payments to leakage reduction metrics. Municipal buyers in Germany and the Netherlands are driving this shift through framework agreements that bundle sensor hardware with predictive maintenance services.
IoT Utilities Market Segmentation
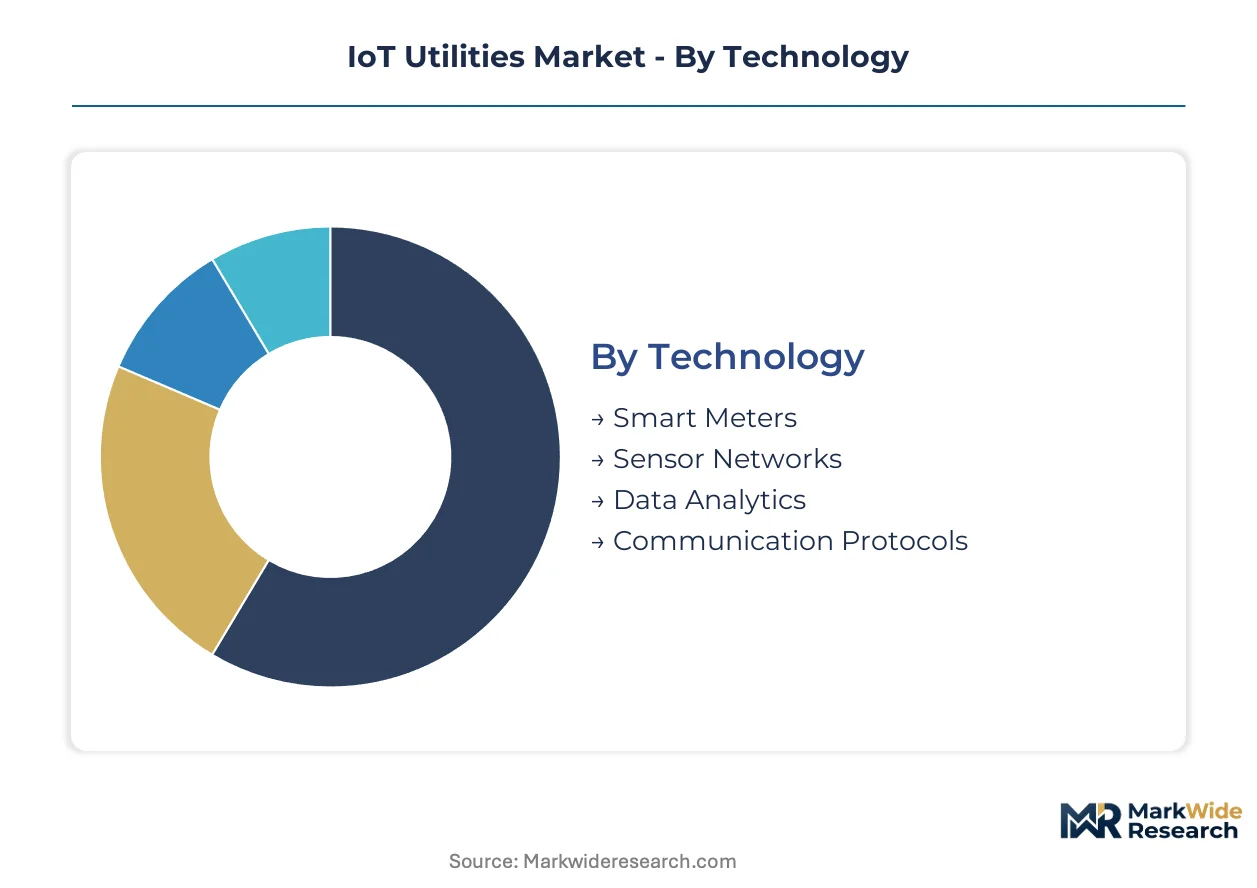
IoT utilities procurement splits sharply between capital-intensive hardware deployments and recurring software subscriptions. Understanding where upfront investment concentrates versus where operational spending flows determines vendor positioning and margin capture strategies.
Technology:
Capital intensity peaks in sensor hardware requiring ruggedized manufacturing and multi-year certification cycles, while software layers monetize through recurring licensing with minimal incremental deployment cost.
- Smart Meters:These devices measure electricity, water, or gas consumption with embedded cellular or mesh radio modules for automated billing integration. Municipal utilities in Germany's Rhine-Ruhr corridor are replacing legacy electromechanical units with IP-enabled meters to meet F-Gas Regulation compliance timelines.
- Sensor Networks:Distributed arrays of temperature, pressure, and chemical detection nodes feed real-time operational data to central platforms. Water quality mandates under the EU Green Deal are accelerating dissolved oxygen and turbidity sensor rollouts across European municipal treatment facilities.
- Data Analytics:AI-driven platforms process utility telemetry to generate predictive load forecasts and leakage detection alerts.
- Communication Protocols:Multi-protocol gateways bridge legacy SCADA infrastructure with cloud-native architectures.
Most installed capacity flows through Smart Meters. Expansion is steepest in Communication Protocols.
Application:
Application selection tracks regulatory pressure intensity, with compliance-driven deployments commanding faster procurement cycles than efficiency-motivated upgrades.
- Energy Management:Systems optimize electricity distribution through demand-response programs and distributed generation integration. Industrial operators in energy-intensive sectors deploy these platforms to minimize exposure to peak pricing tariffs.
- Water Quality Monitoring:Real-time sensor networks track pH, turbidity, and contaminant levels throughout distribution infrastructure. Municipal utilities facing tightening effluent standards under the EU Green Deal are prioritizing these deployments over other IoT categories.
- Grid Management:Voltage regulation and fault detection systems maintain stability across transmission and distribution networks.
- Predictive Maintenance:Machine learning models analyze equipment vibration and thermal patterns to schedule interventions before failure.
Grid Management absorbs the largest share of current utility capital budgets. Water Quality Monitoring is gaining share fastest as environmental enforcement tightens.
End User:
End user type determines procurement complexity, with government agencies imposing lengthiest certification requirements and residential segments demanding lowest per-unit price points.
- Utility Companies:Electric, water, and gas distribution operators constitute the core demand base for integrated IoT platforms. These buyers separate operational-technology hardware budgets from IT-analytics software spending, creating dual vendor relationships.
- Industrial Operators:Manufacturing and processing facilities deploy private sensor networks for energy cost optimization and environmental compliance. Rhine-Ruhr corridor chemical plants are piloting edge computing architectures to reduce latency for real-time process control.
- Government Agencies:Municipal and national bodies mandate standards and often directly procure infrastructure for public service delivery.
- Residential Consumers:Individual households receive smart meters through utility-managed rollout programs with limited direct purchasing involvement.
Utility Companies account for the dominant share of installed systems. Industrial Operators are expanding deployment fastest as energy price volatility intensifies.
Installation:
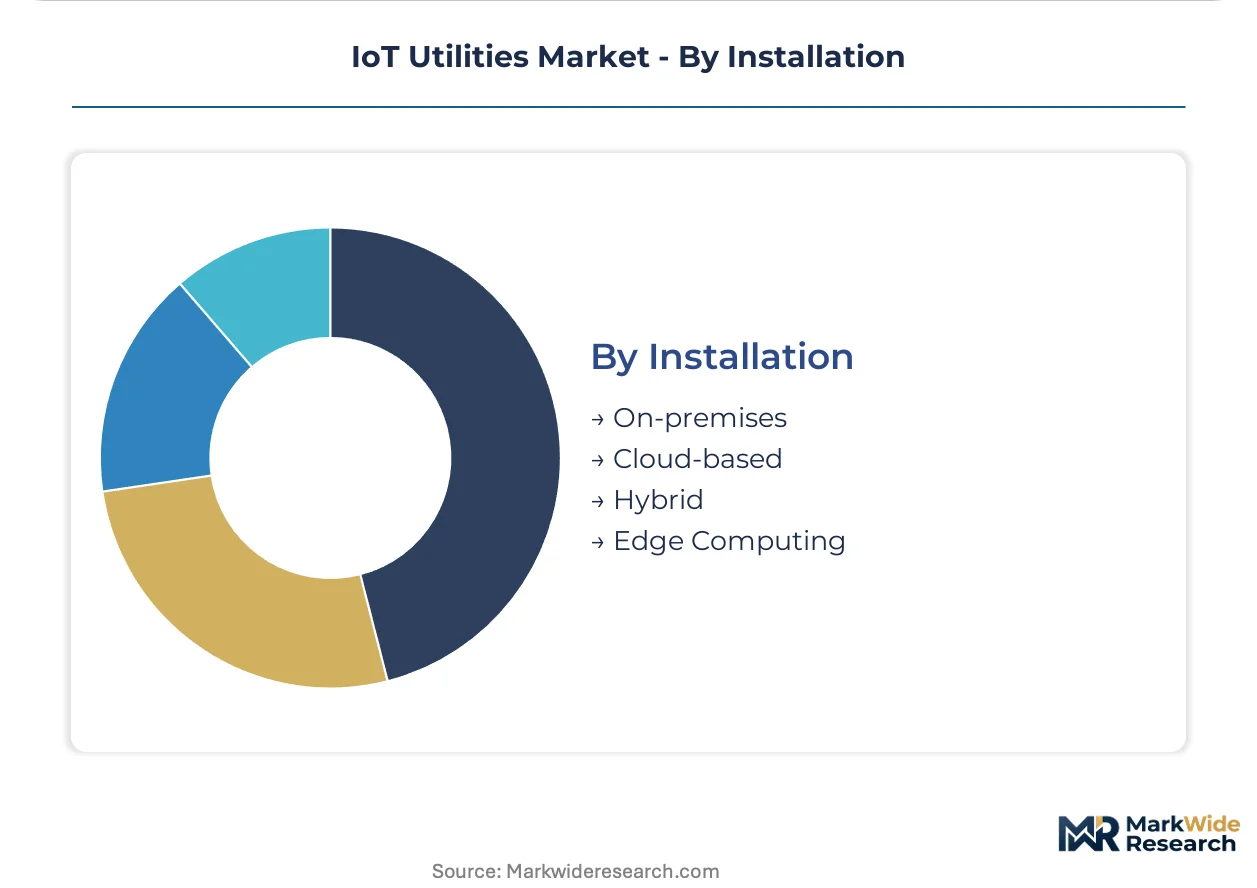
Installation architecture selection trades latency performance against capital expenditure, with edge and hybrid configurations commanding premium pricing for real-time applications.
- Edge Computing:Processing occurs at distributed gateway devices near data sources, enabling sub-100 millisecond response times for grid balancing. German transmission operators favor this architecture for substation automation where cloud latency is unacceptable.
- Cloud-based:Centralized data processing minimizes on-site hardware requirements and enables rapid analytics scaling. European water utilities prefer this model for predictive maintenance platforms where millisecond response is unnecessary.
- Hybrid:Critical control functions run at edge nodes while analytics and reporting flow to cloud infrastructure.
- On-premises:Fully localized deployment meets strictest cybersecurity requirements for critical infrastructure protection.
Cloud-based deployments hold the largest installed base. Edge Computing is climbing the fastest as real-time control applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent clusters in Germany's industrial corridor anchor European IoT utilities deployment. Utility procurement teams in the Rhine-Ruhr region command deep expertise in substation automation and sensor integration. This concentration shapes vendor prioritization across the continent.
United States
FERC cybersecurity mandates for bulk power systems drive procurement specifications for hardened grid infrastructure. The Federal Energy Regulatory Commission mandates NERC CIP standards that filter vendor selection for transmission operators. Texas and California utilities lead edge-computing deployments for real-time demand response.
Germany
The EU F-Gas Regulation compels sensor networks for refrigerant leak detection across substation infrastructure. CE marking under the Cyber Resilience Act imposes security-by-design requirements on connected device vendors. The Rhine-Ruhr corridor concentrates dissolved oxygen and turbidity sensor rollouts for municipal water compliance.
China
MIIT GB standards for industrial IoT communication dictate mandatory interoperability testing for foreign suppliers. The Ministry of Industry and Information Technology certification timelines gate multi-country product launches. Yangtze River Delta utilities pilot private 5G networks for distribution automation.
Japan
METI smart city initiatives accelerate LPWAN sensor deployment for aging water infrastructure. The Ministry of Economy, Trade and Industry promotes LoRaWAN convergence in secondary metropolitan areas. Kansai region utilities integrate predictive maintenance platforms with existing SCADA investments.
United Kingdom
Ofwat price review cycles incentivize leakage reduction through AI-driven pressure monitoring networks. The Environment Agency's tightening effluent standards mandate real-time water quality telemetry. Thames Water and United Utilities anchor sensor procurement volumes in England's privatized utility structure.
IoT Utilities Market Vendor Landscape
Top-tier vendors anchor multi-protocol platform supply, while specialized sensor fabricators occupy mid-tier niches. The vendor base stratifies across three tiers: integrated industrial conglomerates with captive manufacturing, networking specialists with edge-computing pedigree, and pure-play analytics platforms. Strategic archetypes include cybersecurity-hardened platform providers, ruggedized sensor specialists, and cloud-native software vendors. Competitive moves concentrate on M&A for protocol convergence capabilities and strategic partnerships bridging OT-IT integration gaps.
Within the integrated industrial tier, Siemens AG and General Electric Company exemplify captive manufacturing strategies for substation-hardened hardware. Cisco Systems, Inc. anchors the networking-specialist archetype through edge-computing deployments. These three corporations represent distinct competitive vectors: Siemens AG and General Electric Company occupy positions tied to physical infrastructure longevity, while Cisco Systems, Inc. sits within the protocol-layer convergence space.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| IBM Corporation |
| General Electric Company |
| Siemens AG |
| Microsoft Corporation |
| Huawei Technologies |
| SAP SE |
| Honeywell International Inc. |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Edge computing architectures are compressing hardware margins while concentrating pricing power among multi-protocol gateway vendors serving German transmission operators. This technology transition simultaneously elevates software licensing premiums and consolidates procurement influence around systems integrators bridging legacy SCADA with cloud-native platforms.
Pricing Analysis
Bundled hardware-software contracts are fragmenting into unbundled sensor procurement and separate analytics subscriptions. Three-tier pricing structure across cybersecurity-hardened, standard-certified, and economy-grade hardware tiers separates FERC-compliant platforms from commodity meter alternatives. Price differentiation hinges on CE marking under the Cyber Resilience Act and volume scale in municipal utility rollouts. Cost compression in cellular radio modules is intensifying because memory chip shortages persist, making industrial operators the least price-sensitive segment due to latency-critical applications.
Supply Chain Analysis
Ruggedized sensor production rests on specialized foundry capacity concentrated in Taiwan, South Korea, and Japan. Manufacturing draws from rare earth magnets for NB-IoT modules, industrial-grade semiconductors, and hardened enclosure materials. Single-source vulnerability in Taiwan semiconductor fabrication creates exposure to geopolitical disruption. Distribution runs through systems integrators serving Rhine-Ruhr corridor utilities with direct OEM relationships for substation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from software analytics overtaking hardware as the primary value capture layer. Subscription-based predictive maintenance contracts are lifting recurring revenue shares above capital-intensive sensor deployments.
For Market Incumbents: Anticipate procurement bifurcation by separating ruggedized sensor manufacturing from cloud analytics platform development. Cisco Systems and Siemens AG already anchor distinct competitive vectors through edge-computing pedigree versus captive substation hardware production. Defend position by deepening certification investments for FERC cybersecurity mandates and CE marking under the Cyber Resilience Act. Channel control through direct utility relationships in Germany's Rhine-Ruhr corridor remains essential. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for refrigerant leak detection sensor specialists targeting substation compliance deadlines. LPWAN network convergence in secondary German cities presents the most penetrable geography outside cellular coverage zones. Water quality monitoring applications under the EU Green Deal offer faster procurement cycles than grid management. Pursue outcome-based contracts tying vendor payments to leakage reduction metrics as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play analytics platforms lacking captive hardware manufacturing. Long-term viability over the coming decade favors vendors with dual OT-IT integration capabilities spanning ruggedized sensors and cloud-native software. Target acquisition archetypes include multi-protocol gateway specialists with pre-certified cybersecurity architectures. Watch FERC enforcement intensity and CE marking timeline acceleration as the critical inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Gateway Development | Bridges legacy SCADA with cloud platforms for Rhine-Ruhr substation operators. |
| Cybersecurity Certification Investment | Captures FERC-mandated premiums for bulk power system infrastructure. |
| Subscription Analytics Licensing | Aligns vendor economics with European water utility outcome-based procurement. |
| LPWAN Infrastructure Partnership | Expands sensor deployment reach beyond capital-intensive cellular zones. |
| Digital Twin Platform Integration | Automates workforce allocation for German transmission operators. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each regional cluster. Utility planning officers, substation automation engineers, municipal procurement managers, and IoT platform architects provided structured interviews across the analysis window. Secondary validation drew from FERC filings, EU regulatory databases, MIIT GB standard publications, and utility capex disclosures. Bottom-up sensor deployment tracking and top-down market sizing triangulated volume estimates.
Granularity-level modeling segmented the market by technology layer, application type, end-user archetype, and installation architecture. Forecasts across the projection horizon incorporated regulatory compliance timelines, LPWAN network rollout schedules, and semiconductor supply constraints. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Edge computing adoption curves and predictive maintenance contract penetration served as industry-specific forecast inputs.
Revisions become necessary when semiconductor supply disruption, regulatory timeline acceleration, or cybersecurity standard updates materialize. Forecasts reflect assumptions about F-Gas Regulation compliance schedules, CE marking enforcement intensity, and utility procurement budget bifurcation persistence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market