
 Internet of Things (IoT) Connected Cars Market | 2026-2036
Internet of Things (IoT) Connected Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) Connected Cars Market Intelligence
The unbundling of data services from core telematics hardware is expanding buyer choice for automotive suppliers and fleet operators. BlackBerry leverages its QNX operating system to secure a foundational position in in-vehicle infotainment systems. In contrast, Samsara specializes in integrated platforms for commercial fleets, combining hardware with cloud analytics, while Upstream Security focuses purely on cloud-native cybersecurity for vehicle data.
IoT connected cars are vehicles with embedded internet access that use telematics modules and onboard diagnostics to transmit real-time data. These systems enable functionalities ranging from remote vehicle control to advanced driver-assistance systems. The telematics module component segment is pivotal for enabling connectivity. Within applications, fleet management constitutes a large, established market, whereas usage-based insurance and predictive maintenance represent high-growth areas attracting investment from insurance providers and automotive suppliers.
Regulatory frameworks directly influence product design and data handling. The EU's GDPR imposes strict rules on personal data processing, while the US NHTSA's cybersecurity guidelines shape security protocols for vehicle-to-everything communication. Automaker compliance with these differing standards is essential for market access. Consequently, balancing data monetization opportunities with the escalating costs of robust cybersecurity remains a central strategic challenge for all stakeholders.
Market Dynamics
The fundamental dynamic shaping the IoT connected cars market is the unbundling of software and data services from the underlying telematics hardware. This separation is creating new value pools and forcing a realignment of business models for automakers and suppliers.
Growth Catalysts
- Regulatory Mandates:Safety-driven regulations, such as the eCall initiative in the European Union, mandate the inclusion of automatic emergency response telematics in new vehicles, creating a foundational level of connectivity.
- 5G Network Expansion:The ongoing deployment of 5G infrastructure provides the low-latency, high-bandwidth connectivity required for advanced vehicle-to-everything (V2X) applications, including real-time traffic and hazard alerts.
- Commercial Fleet Efficiency:Demand from the logistics and transportation sectors for solutions that optimize fuel consumption, monitor driver behavior, and improve vehicle uptime is a significant driver for telematics adoption in commercial vehicles.
Market Restraints
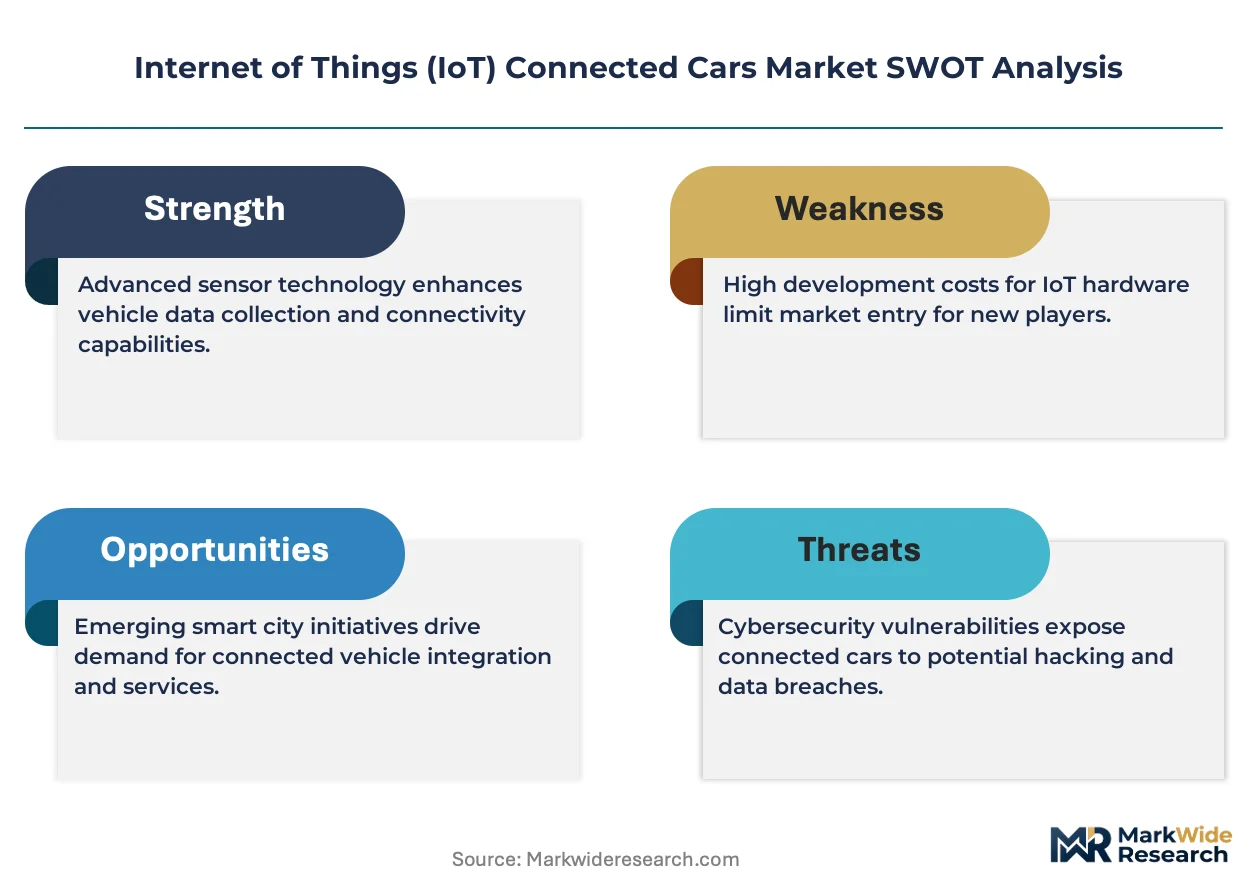
- Semiconductor Supply Volatility:The supply of microprocessors and specialized chips essential for telematics control units is concentrated in a few Asian countries, making the market vulnerable to geopolitical tensions and supply chain disruptions.
- High Initial Investment:The upfront cost of integrating advanced telematics systems and sensors into vehicle platforms remains a considerable barrier, particularly for economy-segment automobiles and smaller commercial fleet operators.
- Standardization Fragmentation:Competing communication standards, such as Dedicated Short-Range Communications (DSRC) and Cellular V2X (C-V2X), create interoperability issues and slow the pace of large-scale infrastructure deployment for connected vehicles.
Strategic Opportunities
- Usage-Based Insurance Models:Collaboration with insurance providers to offer policies based on real-time driving data represents a high-growth opportunity, enabling personalized premiums and promoting safer driving habits.
- Predictive Maintenance Services:The convergence of IoT sensor data with AI analytics allows for the development of services that predict component failures before they occur, creating new recurring revenue streams for automakers and suppliers.
- Emerging Market Penetration:Government initiatives to improve transportation infrastructure in countries like Brazil and India, coupled with a rising middle class, present significant white-space opportunities for connected vehicle services.
Industry Challenges
- Cybersecurity Talent Scarcity:A persistent shortage of software engineers and security professionals with expertise in both automotive engineering and cloud-native cybersecurity protocols hinders the development of secure connected vehicle architectures.
- Legacy System Integration:Automakers face significant operational hurdles in integrating new, software-defined vehicle platforms with decades-old dealership, manufacturing, and IT systems, often causing delays and cost overruns.
- Complex Regulatory Compliance:Navigating the patchwork of data privacy laws, such as the EU's GDPR and various state-level regulations in the US, creates a substantial and costly compliance burden for global automakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) Connected Cars Market |
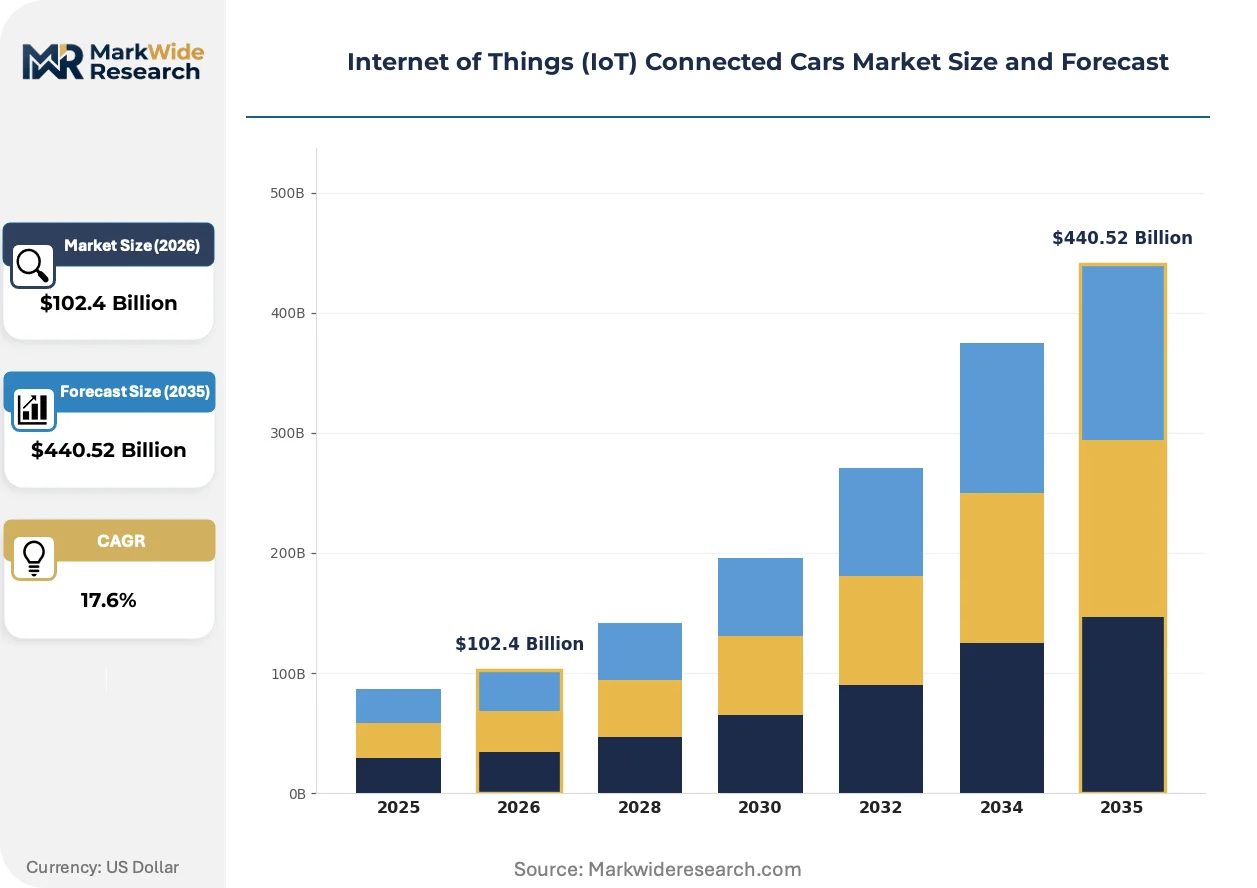
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $440.52 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Telematics Module, Infotainment Systems, Sensors, Connectivity Modules, Onboard Diagnostics Technology: 5G, LTE, Dedicated Short Range Communication, Bluetooth, Wi-Fi Application: Fleet Management, Predictive Maintenance, Remote Vehicle Control, Usage-Based Insurance, Driver Behavior Monitoring End User: Commercial Fleets, Automotive Suppliers, Insurance Providers, Ride-Hailing Services, Vehicle Leasing Companies |
| Companies Covered | Wejo, EMQX, Sibros, BlackBerry, Otonomo, Upstream Security, Motorq, Samsara, Argus Cyber Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) Connected Cars Market Strategic Shifts & Innovations
The redefinition of the vehicle as a software-defined platform is the central theme of innovation. Value is migrating from mechanical hardware to upgradeable software, recurring data services, and the in-cabin digital experience, fundamentally altering automaker business models.
Edge computing allows for the processing of sensor data directly on the vehicle's onboard computers. Automakers and Tier-1 suppliers are rapidly adopting this technology to reduce latency for critical advanced driver-assistance systems (ADAS) and to minimize the volume of data sent to the cloud. By handling analysis locally, edge computing is decentralizing processing power away from centralized data centers, enabling more responsive and autonomous vehicle functions.
The US National Highway Traffic Safety Administration's (NHTSA) updated cybersecurity guidelines for vehicles are setting stricter standards for the industry. These guidelines push manufacturers to adopt a multi-layered, defense-in-depth security strategy throughout the vehicle's lifecycle. Consequently, the vehicle-to-everything (V2X) segment is most directly impacted, compelling developers to embed more sophisticated encryption and intrusion detection protocols into their communication modules.
Subscription-based purchasing for on-demand vehicle features is changing consumer behavior. This model moves away from the traditional, one-time sale of option packages at the point of purchase, enabling automakers to generate recurring revenue via over-the-air (OTA) software activations. The trend is most prominent in the premium electric vehicle segments in North America and Europe, where customers can unlock functionalities post-sale.
Internet of Things (IoT) Connected Cars Market Segmentation
The segmentation of the IoT connected cars market illuminates how value is captured across distinct technological layers and end-user applications. This granular view helps stakeholders understand where investment is concentrating and which areas are poised for significant expansion. Analyzing these segments reveals the underlying market structure and competitive dynamics.
Component:
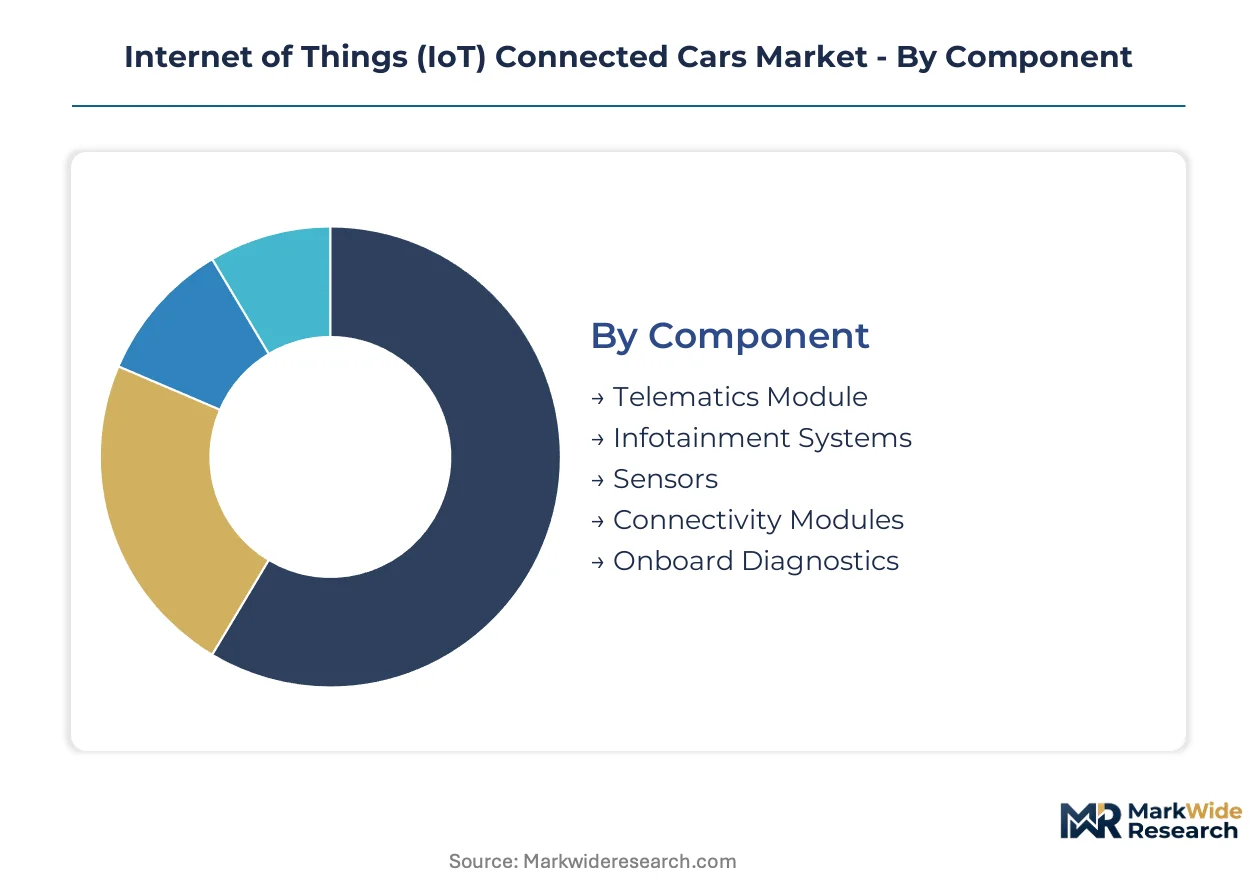
The component segment for IoT connected cars illustrates the critical balance between high-volume, standardized hardware and premium, feature-rich systems. Each element provides a distinct function essential for connected vehicle operation.
- Telematics Module:This embedded hardware unit collects and transmits vehicle data, enabling essential functionalities like emergency calling and remote diagnostics. Its pivotal role in connectivity drives consistent demand across all vehicle segments.
- Infotainment Systems:These integrated platforms provide navigation, communication, and entertainment services within the vehicle cabin. Demand for rich digital experiences, especially in premium vehicles, drives continuous innovation and software integration.
- Sensors:Various sensors gather real-time data on vehicle performance, environmental conditions, and driver behavior.
- Connectivity Modules:These modules facilitate wireless communication, supporting various protocols for vehicle-to-cloud data exchange.
- Onboard Diagnostics:Standardized systems monitor vehicle health and fault codes, crucial for maintenance and regulatory compliance.
Today's leader: Telematics Module. Tomorrow's challenger: Infotainment Systems.
Technology:
Connectivity technology choices are increasingly dictated by the specific application requirements of connected vehicles, influencing latency, bandwidth, and coverage. Each technology supports different levels of data exchange and real-time interaction.
- 5G:This next-generation wireless technology offers ultra-low latency and high bandwidth, essential for advanced V2X communication and autonomous driving applications. Global network expansion is critical for its widespread adoption.
- LTE:Long Term Evolution (4G) provides reliable, widespread mobile broadband connectivity, serving as the current backbone for most connected car services. Its mature infrastructure supports a broad range of telematics functions.
- Dedicated Short Range Communication:DSRC is a short-to-medium range wireless technology specifically designed for vehicle safety applications.
- Bluetooth:This short-range wireless protocol primarily facilitates in-cabin device connectivity and hands-free communication.
- Wi-Fi:Wi-Fi enables local network connectivity within the vehicle, often used for infotainment and software updates when parked.
The strategic shift favors 5G for its low-latency capabilities, while LTE maintains a foundational role for widespread coverage.
Application:
The application segment reveals a spectrum from mature, established services to rapidly evolving, data-intensive offerings that redefine vehicle utility. These applications address diverse needs across commercial and consumer markets.
- Fleet Management:This established application optimizes commercial vehicle operations through GPS tracking, route optimization, and driver performance monitoring. Logistics and transportation sectors drive consistent demand for efficiency gains.
- Predictive Maintenance:Utilizing IoT sensor data and AI analytics, this application anticipates component failures, reducing downtime and operational costs for vehicle owners and operators. Automotive suppliers are heavily investing in these services.
- Remote Vehicle Control:This functionality allows users to remotely lock/unlock doors, start engines, or pre-condition vehicle cabins.
- Usage-Based Insurance:Policies are tailored to individual driving behavior collected via telematics data, promoting safer habits and personalized premiums.
- Driver Behavior Monitoring:This application tracks and analyzes driving patterns to improve safety, reduce fuel consumption, and assess risk.
Long-term revenue expansion will increasingly derive from Predictive Maintenance, building on the established base of Fleet Management.
End User:
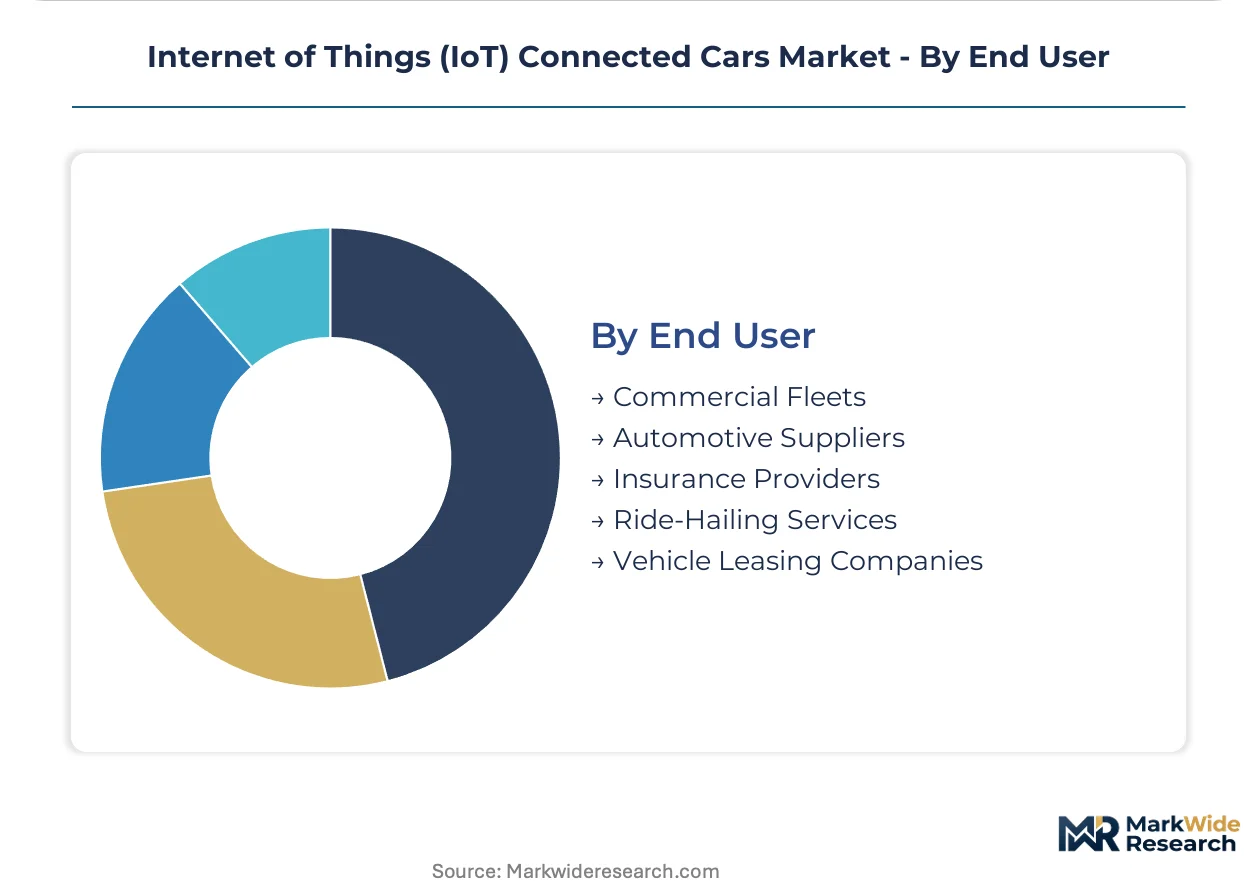
End-user demand for connected car services is diversifying across distinct customer types, each with unique operational needs and value propositions. Each segment seeks specific benefits from vehicle connectivity.
- Commercial Fleets:These operators leverage connected car technologies for operational efficiency, asset tracking, and regulatory compliance across large vehicle populations. Demand is high for solutions that reduce operating expenses.
- Automotive Suppliers:These entities integrate connected technologies into vehicle platforms, often developing proprietary solutions for OEMs and aftermarket segments. They focus on delivering advanced components and software.
- Insurance Providers:Insurers utilize telematics data to assess risk, offer personalized policies, and encourage safer driving practices.
- Ride-Hailing Services:These platforms depend on connected car data for vehicle location, dispatch optimization, and driver performance management.
- Vehicle Leasing Companies:Leasing firms use connected car data for asset management, mileage tracking, and predictive maintenance scheduling.
The market is diversifying beyond its traditional Commercial Fleets base, with rapid expansion in Insurance Providers segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Internet of Things (IoT) connected cars market traces its origins to early telematics systems developed for emergency services and fleet tracking. Germany and the United States were early innovators, integrating digital communication into vehicles. This foundational work paved the way for advanced connectivity.
China
Demand for advanced connectivity is heavily concentrated in China's automotive manufacturing sector, driven by consumer preference for digital experiences. State-backed initiatives for intelligent transportation systems, like the "Intelligent Vehicle Innovation Development Strategy," accelerate market growth. Cities like Shenzhen and Shanghai are hubs for EV and connected car R&D.
United States
The United States sees significant demand for advanced driver-assistance systems and V2X communication. The US NHTSA's cybersecurity guidelines shape security protocols for vehicle-to-everything communication, mandating higher standards. Silicon Valley and Detroit converge on connected car technology, with firms investing in autonomous vehicle testing.
Germany
Germany's automotive industry drives demand for high-end telematics and software-defined vehicle platforms. Regulatory mandates like the EU's eCall initiative ensure a baseline of connectivity in new vehicles across the region. Stuttgart and Munich remain central to automotive engineering, developing secure in-vehicle infotainment and advanced telematics modules.
South Korea
South Korea exhibits strong demand for 5G-enabled V2X applications and sophisticated infotainment systems. The Ministry of Land, Infrastructure and Transport actively promotes smart road infrastructure and autonomous driving pilot projects. Seoul's tech clusters and Ulsan's automotive base are collaborating on next-generation connected mobility solutions.
India
India's market is experiencing rising demand for fleet management solutions and usage-based insurance models. Government initiatives to improve transportation infrastructure and safety encourage local telematics production. Major metropolitan areas like Bengaluru and Pune are emerging as software development centers for automotive embedded systems.
Internet of Things (IoT) Connected Cars Market Key Industry Players
Premium-margin players sit above commodity-margin players across the software and data services dimension, particularly in advanced analytics and cybersecurity. The market structure exhibits a tiered consolidation, with established automotive suppliers and specialized tech firms vying for influence. Strategic archetypes include integrated hardware-software platform providers, pure-play cloud-native cybersecurity specialists, and vehicle data monetization enablers. Companies prioritize strategic partnerships and portfolio diversification to capture new revenue streams and expand geographic reach.
Within the specialized cybersecurity segment, Upstream Security exemplifies a focused approach to cloud-native protection for vehicle data, safeguarding against evolving threats. Samsara represents integrated platforms designed for commercial fleets, combining proprietary hardware with robust cloud analytics to optimize operational efficiency and driver behavior. BlackBerry, leveraging its widely adopted QNX operating system, occupies a foundational position in securing in-vehicle infotainment systems and critical telematics modules. These companies anchor distinct segments of the connected car ecosystem, reflecting diverse strategies for value creation.
| Leading Market Players |
|---|
| Wejo |
| EMQX |
| Sibros |
| BlackBerry |
| Otonomo |
| Upstream Security |
| Motorq |
| Samsara |
| Argus Cyber Security |
| Others |
Cost & Logistics Intelligence
Cybersecurity talent concentration in tech hubs like Silicon Valley and Bengaluru drives significant labor-cost differentials. These cost structures directly influence the pricing tiers for advanced software and data services in the connected car market.
Pricing Analysis
Subscription-based and value-based pricing models dominate the IoT connected cars market. Price differentiation stems from the level of software customization and the robustness of after-sales services, including critical cybersecurity updates. Pricing pressure affects basic telematics modules due to commoditization, while advanced software features command a premium. Commercial fleet operators and economy-segment automakers exhibit the highest price sensitivity, contrasting with premium vehicle buyers who prioritize advanced functionalities.
Supply Chain Analysis
Microprocessor and specialized chip supply for telematics control units rests heavily on manufacturing hubs in Taiwan, South Korea, and China. This concentration creates a significant single-source vulnerability, exposing the market to geopolitical tensions and potential disruptions. Key components are primarily integrated into vehicle platforms by automotive suppliers and OEMs. Downstream distribution for telematics services often runs through direct-to-fleet operators and aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT connected cars market acts as a stable compounder, driven by continuous regulatory mandates for safety and efficiency. These foundational requirements ensure sustained demand and technological evolution across vehicle segments.
For Market Incumbents: To counter the unbundling of software from hardware and the rise of specialized tech firms, incumbent automakers must aggressively invest in software-defined vehicle platforms. Deepening R&D in cloud-native cybersecurity and AI analytics will secure future revenue streams. Strategic partnerships with pure-play cybersecurity specialists like Upstream Security can mitigate talent scarcity and accelerate secure system development.
For New Entrants and Emerging Players: Capture white-space opportunities within high-growth applications like predictive maintenance and usage-based insurance models. Targeting emerging markets such as India and Brazil with localized, cost-effective telematics solutions offers significant penetration potential. A go-to-market strategy focusing on cloud-native analytics and AI-driven insights will differentiate offerings from traditional hardware-centric approaches.
For Investors and Strategic Acquirers: Automotive suppliers and insurance providers are the most active acquirers in this space, seeking to integrate advanced software capabilities and data monetization platforms. The market offers long-term viability over the next decade due to the vehicle's evolution into a software-defined platform generating recurring service revenues. Acquisition targets should prioritize pure-play cloud-native cybersecurity firms and AI analytics specialists. The sustained increase in patent filings for V2X security protocols is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined Vehicle Platforms | Enables recurring revenue from over-the-air updates and new feature activations for OEMs. |
| Develop AI-Powered Predictive Maintenance | Reduces vehicle downtime and operational costs for commercial fleet operators and end-users. |
| Form Cybersecurity Partnerships | Strengthens vehicle data protection against evolving threats, ensuring regulatory compliance. |
| Expand 5G V2X Solution Portfolio | Supports advanced driver-assistance systems and autonomous driving with low-latency connectivity. |
| Target Emerging Market Fleet Solutions | Addresses demand for efficiency gains and asset tracking in regions like India and Brazil. |
Research Approach
Bottom-up application-level modeling reconciled against top-down component-level tracking forms the analytical core of this study. Primary interviews with automotive OEM engineers, Tier-1 suppliers, commercial fleet managers, and insurance telematics leads provided critical insights. Secondary validation drew from NHTSA publications, EU eCall reports, and global automotive industry association data. This approach ensures robust data triangulation.
Historical trendline analysis, combined with forward-looking adoption curves, informed the forecast framework across the analysis window. The model segmented the market by component, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from these projections, integrating key inputs such as global vehicle production volumes and 5G network rollout schedules.
Geopolitical supply chain disruptions, rapid regulatory shifts, and unforeseen technological breakthroughs are the dominant revision risks for these forecasts. The projections reflect current market dynamics and known policy trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Global Agile IoT Market