
 Cellular M2M Market | 2026-2036
Cellular M2M Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular M2M Market Intelligence
Asian module manufacturers are pivoting toward integrated chipset-to-cloud platforms as 5G NR coverage deepens across industrial corridors. AT&T leverages its FirstNet spectrum holdings to dominate public safety connectivity contracts. Vodafone Group anchors European M2M roaming through unified SIM provisioning across thirty markets. Huawei Technologies competes on baseband integration density, sustaining cost advantages in NB-IoT module production.
Cellular M2M denotes machine-to-machine communication over licensed cellular infrastructure, typically employing embedded SIM modules operating between 700 MHz and 3.5 GHz bands with latency requirements from 10 ms to 10 s depending on application criticality. Its primary purpose is to transmit telemetry, command, and status data between dispersed assets and central management systems without human intervention. LTE and 5G technologies command the highest value per connection due to bandwidth-intensive video telemetry and edge computing offload requirements. NB-IoT penetration is deepening in smart metering where fifteen-year battery life and underground signal reach override throughput needs. Fleet management applications generate the largest addressable revenue pool as real-time route optimization and driver behavior analytics become standard in logistics procurement.
The FCC governs spectrum allocation and device certification for cellular M2M deployments in the United States, while ETSI coordinates harmonized frequency bands and interoperability standards across European member states. China's MIIT mandates domestic encryption modules and network access licenses, creating segmented certification pathways that foreign suppliers must navigate. Stakeholders should monitor evolving national security screening of foreign telecommunications equipment as this determines which module vendors qualify for critical infrastructure contracts.
Market Dynamics
5G spectrum allocation policies in Germany, South Korea, and the United States are compressing carrier infrastructure deployment timelines and redrawing competitive boundaries among module suppliers. Licensed cellular bands between 700 MHz and 3.5 GHz now face simultaneous contention from public safety networks, industrial automation, and consumer broadband.
Growth Catalysts
- Fleet management digitization:Logistics providers embed LTE modules for real-time route optimization and driver behavior analytics, converting procurement contracts into connectivity-mandated specifications.
- China's smart city mandates:Domestic module production scales under MIIT network access licenses, concentrating demand for NB-IoT in metering and streetlight infrastructure.
- FirstNet spectrum utilization:Dedicated public safety bandwidth in the United States accelerates mission-critical M2M deployments for emergency response vehicle telemetry.
Market Restraints
- Baseband chipset concentration:Advanced node fabrication for 5G NR modems depends on a limited foundry base in Taiwan and South Korea, exposing supply continuity risk.
- Domestic encryption mandates:China's MIIT requires localized security modules, fragmenting certification pathways and extending product qualification cycles for foreign suppliers.
- Unlicensed LPWAN substitution:LoRa and Sigfox networks capture price-sensitive smart metering volumes where fifteen-year battery life outweighs cellular reliability premiums.
Strategic Opportunities
- Edge computing convergence:5G NR modules with embedded GPU capacity enable video analytics offload at industrial sites, opening premium pricing tiers for bandwidth-intensive telemetry.
- India's industrial corridor expansion:PLI scheme incentives for electronics manufacturing attract module assembly investments serving domestic agricultural IoT and utility monitoring.
- Unified SIM provisioning:Cross-border roaming platforms eliminate multi-carrier contract complexity for logistics fleets operating across European Union member states.
Industry Challenges
- Radio frequency engineering scarcity:5G NR antenna design and millimeter-wave calibration require specialized talent pools concentrated in South Korea and Finland.
- Multi-band certification complexity:FCC Part 15, ETSI EN 301 511, and MIIT SRRC testing sequences extend product launch timelines by eight to fourteen months.
- Legacy SCADA integration:Industrial automation protocols Modbus and Profinet demand protocol translation layers that increase module bill-of-materials cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular M2M Market |
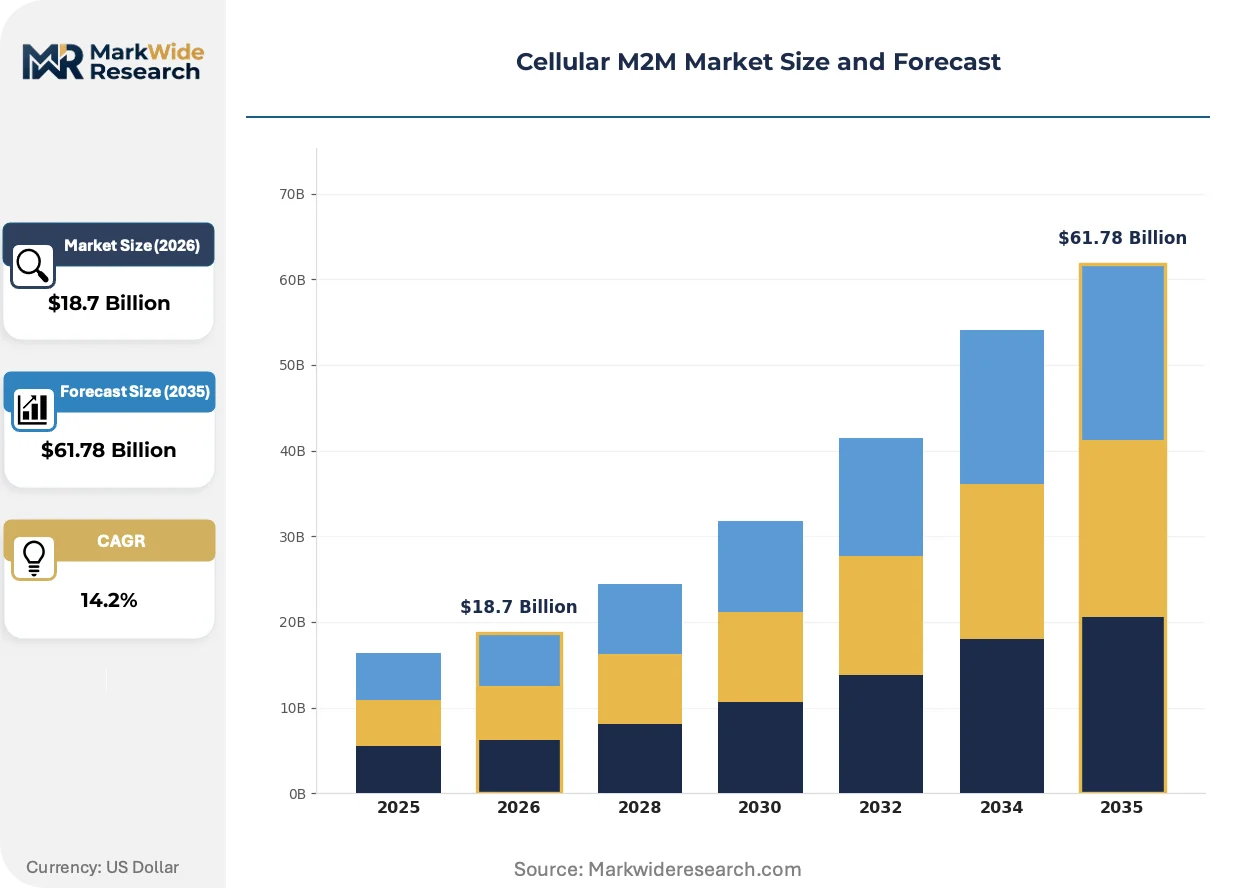
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, NB-IoT, GSM, CDMA Application: Smart Metering, Fleet Management, Environmental Monitoring, Asset Tracking, Telemetry End User: Logistics Providers, Utility Operators, Agricultural Producers, Public Safety Organizations Deployment Model: Private Networks, Public Networks, Hybrid Networks, Hosted Connectivity |
| Companies Covered | AT&T, Verizon Communications, Vodafone Group, Deutsche Telekom, Orange S.A., Telefónica, China Mobile, Ericsson, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular M2M Market Strategic Shifts & Innovations
Module architecture is converging toward integrated chipset-to-cloud platforms as carriers deepen 5G standalone coverage. This integration compresses supply chain tiers and shifts value capture toward software-defined connectivity orchestration.
5G RedCap (Reduced Capability) is overtaking LTE Cat-4 in industrial sensor networks. The technology trims bandwidth and power consumption for mid-tier IoT while preserving cellular reliability. Manufacturing facility operators in Germany and Japan are piloting RedCap modules for predictive maintenance vibration monitoring. The standard is compressing addressable market scope for legacy LTE-only suppliers.
ETSI's harmonized cybersecurity certification framework for IoT devices is reshaping European procurement specifications. The regulation mandates vulnerability disclosure and secure update mechanisms for network-connected equipment. Industrial automation buyers in France and Italy now require CE-RED compliance with EN 303 645 as a contractual precondition. Module vendors are reengineering firmware architectures to satisfy automated audit requirements.
Buyers are consolidating connectivity procurement under managed service contracts rather than per-module hardware purchases. Logistics fleet operators now contract for guaranteed uptime and data throughput rather than owning SIM inventory. This model concentrates vendor selection authority with carriers and platform aggregators. The shift is most pronounced in United States long-haul trucking and German automotive supplier networks.
Cellular M2M Market Segmentation
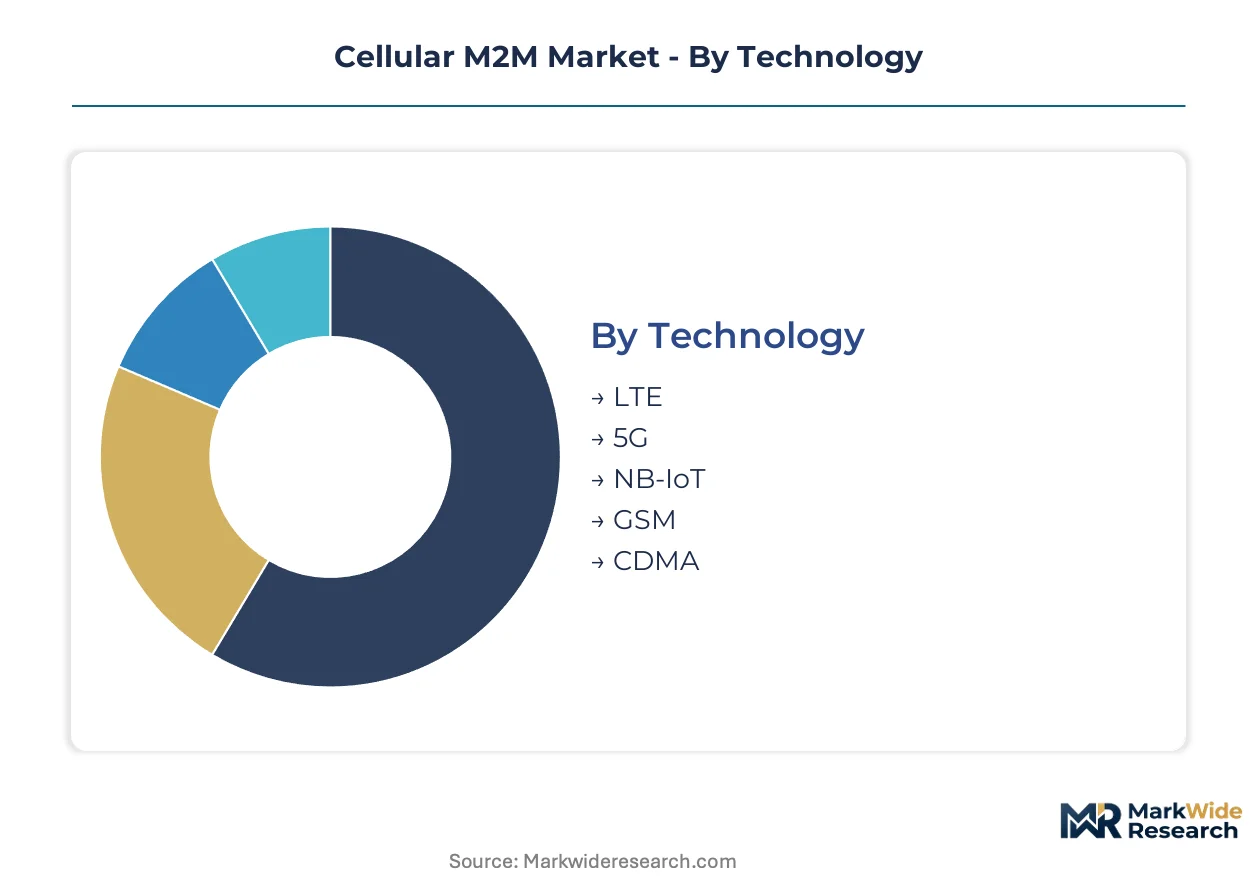
Cellular M2M procurement decisions hinge on latency tolerance, coverage depth, and total cost of ownership across device lifecycles. Buyers prioritize technology tiers that match application criticality while navigating fragmented certification requirements across deployment geographies.
Technology:
Module selection pivots on bandwidth requirements and battery constraints rather than headline data rates alone.
- LTE:Cat-1 and Cat-4 modems dominate video telemetry and fleet telematics where 10 Mbps throughput supports real-time driver analytics. Logistics providers in Germany and the United States specify LTE modules as baseline procurement requirements for route optimization platforms.
- 5G:NR modules with RedCap capability are displacing legacy LTE in industrial sensor networks, trimming power consumption while preserving sub-20 ms latency for predictive maintenance applications. Manufacturing clusters in South Korea and Japan are piloting these modules for vibration monitoring.
- NB-IoT:Narrowband modules penetrate smart metering deployments where fifteen-year battery life and underground signal reach override throughput needs.
- GSM:Legacy 2G modules persist in low-cost asset tracking for developing markets with delayed spectrum refarming.
- CDMA:Remaining CDMA deployments concentrate in specialized public safety networks with long equipment refresh cycles.
Volume sits with LTE; growth tilts toward 5G RedCap as industrial automation upgrades accelerate.
Application:
Revenue concentration follows procurement contract structures that embed connectivity as a mandated specification.
- Fleet Management:Real-time route optimization and driver behavior analytics convert logistics procurement into connectivity-dependent contracts. Long-haul trucking operators in the United States and freight networks across the European Union now require guaranteed uptime SLAs rather than per-device hardware purchases.
- Smart Metering:Fifteen-year operational lifecycles and underground installation environments favor NB-IoT modules with extended signal penetration. China's MIIT-licensed deployments dominate volume as domestic production scales under network access mandates.
- Environmental Monitoring:Agricultural soil sensors and air quality stations deploy across remote corridors with sporadic cellular coverage.
- Asset Tracking:Container and equipment monitoring applications prioritize low-power wide-area connectivity with intermittent transmission bursts.
- Telemetry:Industrial equipment status reporting demands reliable connectivity for predictive maintenance platforms.
Fleet management commands the largest revenue pool; smart metering exhibits the steepest expansion trajectory as utility digitization mandates proliferate.
End User:
Buyer sophistication varies sharply across sectors, with procurement authority consolidating among carriers and platform aggregators.
- Logistics Providers:Fleet operators contract for managed connectivity services covering guaranteed uptime and data throughput across multi-country routes. German automotive supplier networks and United States long-haul trucking fleets have shifted from SIM inventory ownership to outcome-based service agreements.
- Utility Operators:Electricity and water distribution companies specify NB-IoT modules with domestic encryption compliance for smart metering infrastructure.
- Agricultural Producers:Precision farming deployments favor low-cost modules with extended battery life for soil moisture and livestock monitoring.
- Public Safety Organizations:Emergency response vehicle telemetry exploits dedicated FirstNet spectrum holdings in the United States for mission-critical connectivity.
Procurement sophistication peaks with logistics providers; agricultural producers represent the most price-sensitive segment with highest LoRa substitution risk.
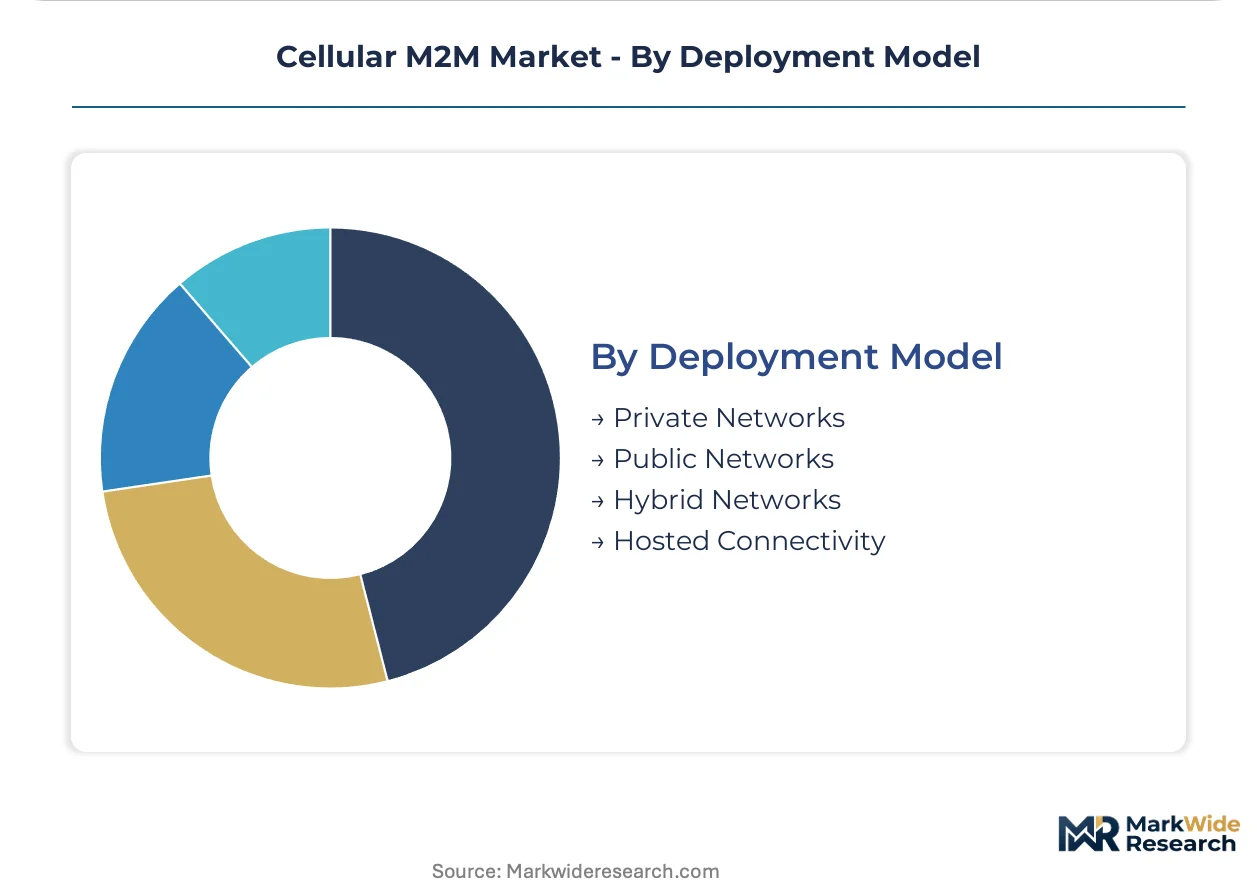
Deployment Model:
Network architecture choices reflect data sovereignty requirements and latency sensitivity for specific operational contexts.
- Private Networks:Dedicated 5G campus deployments serve manufacturing facilities and mining operations where data localization and sub-10 ms latency are non-negotiable. Germany's industrial corridors are piloting these configurations for automated guided vehicle coordination.
- Public Networks:Standard carrier connectivity remains the default for dispersed assets with moderate latency tolerance and no sovereignty constraints.
- Hybrid Networks:Combinations of private 5G and public LTE provide failover redundancy for critical infrastructure monitoring.
- Hosted Connectivity:Platform-as-a-service models eliminate carrier contract complexity for small and mid-sized fleet operators.
Public networks retain volume dominance; private networks are climbing fastest as industrial automation security requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors cellular M2M module production, while demand concentrates in industrial corridors across Germany, China, Japan, and the United States where 5G spectrum allocation policies are compressing deployment timelines.
United States
FirstNet spectrum holdings accelerate mission-critical M2M deployments for emergency response vehicle telemetry. The FCC governs device certification under Part 15 rules, creating multi-month testing sequences for multi-band modules. Dallas-Fort Worth logistics clusters embed LTE connectivity as baseline procurement requirements for long-haul fleet optimization.
Germany
Industrial automation corridors drive 5G RedCap adoption for predictive maintenance vibration monitoring. ETSI harmonizes cybersecurity certification through EN 303 645 mandates that now precondition procurement contracts. Bavarian manufacturing facilities pilot private 5G campus networks for automated guided vehicle coordination with sub-10 millisecond latency.
China
Domestic module production scales under MIIT network access licenses, concentrating NB-IoT demand for smart metering and streetlight infrastructure. The ministry mandates localized encryption modules, fragmenting certification pathways for foreign suppliers. Yangtze River Delta smart city deployments multiply as state-backed utility digitization mandates proliferate.
South Korea
5G NR coverage depth enables integrated chipset-to-cloud platform pivots among module manufacturers. The MFDS coordinates harmonized frequency bands for industrial IoT alongside consumer broadband allocation. Seoul metropolitan manufacturing clusters deploy RedCap modules for factory automation sensor networks at compressed power consumption levels.
Japan
Manufacturing facility operators pilot RedCap modules for equipment condition monitoring, displacing legacy LTE Cat-4 installations. METI guides spectrum allocation toward industrial automation alongside automotive and consumer applications. Nagoya industrial corridors concentrate module integration demand as predictive maintenance platforms proliferate among automotive suppliers.
Cellular M2M Market Key Industry Players
Global majors compete with regional champions across spectrum access and roaming platform integration, producing a tiered structure where carrier-owned module channels coexist with independent hardware vendors. The vendor base stratifies across three archetypes: telecommunications carriers with captive connectivity services, dedicated module manufacturers with baseband integration expertise, and industrial automation suppliers embedding cellular radios into equipment. M&A activity concentrates on software-defined connectivity orchestration capabilities, while strategic partnerships between module vendors and cloud platforms compress supply chain tiers.
Among carrier-based service providers, AT&T and Verizon Communications exemplify the spectrum-anchored archetype, leveraging dedicated public safety bandwidth and national infrastructure scale to dominate mission-critical connectivity contracts. Vodafone Group occupies a position within the European roaming tier, anchoring cross-border unified SIM provisioning across multiple markets. Huawei Technologies sits within the integrated manufacturing archetype, sustaining cost advantages through baseband integration density in licensed and unlicensed module production.
| Leading Market Players |
|---|
| AT&T |
| Verizon Communications |
| Vodafone Group |
| Deutsche Telekom |
| Orange S.A. |
| Telefónica |
| China Mobile |
| Ericsson |
| Huawei Technologies |
| Others |
Cost & Logistics Intelligence
Logistics fleet operators with managed connectivity service contracts dominate procurement volumes, compressing module suppliers toward subscription-based pricing with embedded uptime guarantees rather than discrete hardware transactions.
Pricing Analysis
Warranty and service bundling separates premium-tier 5G RedCap modules with embedded GPU capacity for edge analytics from standard LTE configurations and economy NB-IoT units for basic telemetry. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth, with FCC Part 15 and ETSI EN 303 645 compliance commanding measurable premiums. Cost compression in economy NB-IoT tiers is intensifying because domestic Chinese production scales under MIIT licensing mandates. Agricultural producers exhibit highest price sensitivity, while public safety organizations purchasing through FirstNet spectrum programs show lowest elasticity due to mission-critical reliability requirements.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and United States logistics providers mandate qualified second-source arrangements for baseband chipsets and RF front-end components. Module production draws from Taiwan and South Korea for advanced node fabrication, with China concentrating final assembly and test operations. Silicon wafers, ceramic antenna substrates, and embedded SIM secure elements constitute critical input dependencies. Single-source vulnerability in Taiwan-based foundry capacity for 5G NR modems represents the dominant structural risk. Distribution runs through carrier-direct channels and industrial automation OEMs embedding cellular radios into equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular M2M sits in a technology-transition phase as 5G RedCap displaces legacy LTE Cat-4 in industrial sensor networks, compressing addressable scope for single-mode suppliers while opening premium tiers for edge-capable modules.
For Market Incumbents: Anticipate margin compression from Asian module manufacturers pivoting toward integrated chipset-to-cloud platforms by deepening vertical integration into RF front-end design and securing ETSI EN 303 645 certification ahead of European procurement mandates. Prioritize captive supply of millimeter-wave calibration talent pools concentrated in South Korea and Finland to defend engineering differentiation.
For New Entrants and Emerging Players: Cloud platform partnerships offer the most penetrable channel for bypassing carrier-dominated procurement, particularly targeting mid-sized logistics fleet operators in India's industrial corridors where PLI scheme incentives attract electronics manufacturing investment. White-space exists in private 5G campus network integration for German manufacturing facilities seeking sub-10 millisecond latency without public network dependency.
For Investors and Strategic Acquirers: The window for entry favors module vendors with software-defined connectivity orchestration capabilities and established MIIT network access licenses for China market participation. Long-term viability hinges on differentiation through baseband integration density rather than discrete hardware margins. The signal to watch is spectrum refarming timelines in developed markets, which would accelerate legacy GSM module obsolescence and reshape replacement demand curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Chipset-to-cloud convergence compresses supply tiers toward software-defined orchestration layers. |
| Certification Investment | ETSI EN 303 645 compliance preconditions procurement contracts in France and Italy. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract module assembly for agricultural IoT and utility monitoring. |
| Strategic Partnership | Cloud platform alliances bypass carrier-direct channels for mid-sized fleet operators. |
| Acquisition of Specialist Firm | RF engineering talent pools in South Korea and Finland anchor 5G NR antenna design capability. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with module vendor product managers, carrier IoT platform directors, industrial automation procurement leads, and logistics fleet operations executives. FCC Part 15 device certification databases, ETSI harmonized standards documentation, MIIT network access license registries, and semiconductor trade flow statistics provided quantitative grounding. Bottom-up module shipment analysis triangulated against top-down connectivity service revenue estimates across carrier financial disclosures.
Data-stream reconciliation across technology tier adoption curves, application-specific latency requirements, and regional spectrum allocation policies shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include connectivity technology, end-use application, deployment model architecture, and buyer procurement sophistication tier. CAGRs derived from fitted growth curves against historical adoption patterns, with 5G RedCap displacement timelines and NB-IoT utility mandate proliferation serving as industry-specific forecast inputs.
Caveats apply where baseband chipset foundry capacity constraints, national security screening of foreign telecommunications equipment, or unlicensed LPWAN substitution in price-sensitive metering segments could materially shift the outlook. Deviation in China's MIIT encryption mandate enforcement or Taiwan supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Wireless Connected Devices Market