
 Continuous Blood Pressure Monitoring Devices Market | 2026-2036
Continuous Blood Pressure Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Blood Pressure Monitoring Devices Market Outlook
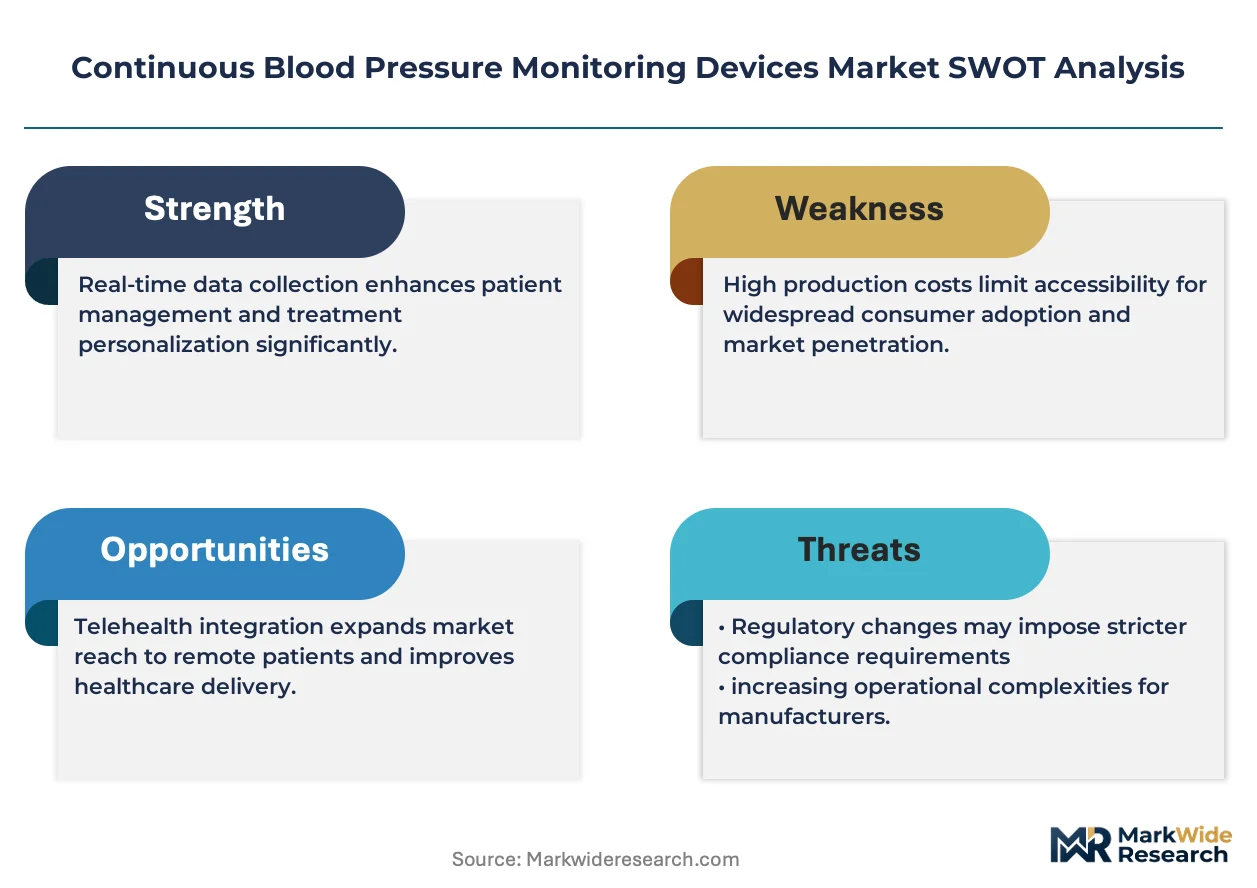
Subscription-based leasing for remote monitoring hardware is rewriting capital allocation across healthcare systems. Philips Healthcare leverages its installed base of hospital telemetry to anchor recurring revenue streams. Omron Healthcare competes through retail channel control in home-use segments. Biobeat specializes in photoplethysmography patch designs that reduce clinical workflow friction.
Continuous blood pressure monitoring devices employ non-invasive optical or oscillometric sensors to capture arterial pressure waveforms at sampling rates exceeding 30 Hz, transmitting data via Bluetooth or cellular modules to cloud platforms for trend analysis and alert generation. Wearable devices dominate volume shipments while implantable devices capture premium pricing in critical-care settings. Optical technology leads consumer adoption due to miniaturization, whereas invasive monitoring retains procedural relevance in operating rooms. Telehealth providers now drive fastest-growing demand for cloud-based platform delivery modes.
FDA premarket notification requirements and EU MDR conformity assessments shape product development roadmaps and market access timelines for device manufacturers. HIPAA privacy rules and GDPR data-protection standards constrain how cloud platforms store and share hemodynamic patient data across jurisdictions. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring as payer policies determine whether home-based continuous blood pressure surveillance achieves sustainable clinical adoption.
Market Dynamics
Remote patient monitoring programs in hospital systems are compressing traditional episodic care models into continuous data streams, forcing device manufacturers to rearchitect hardware for cloud-native telemetry rather than bedside standalone units.
Growth Catalysts
- Telehealth reimbursement expansion:Medicare remote physiological monitoring codes now cover continuous blood pressure surveillance in home settings, accelerating clinical adoption across US health systems.
- Photoplethysmography miniaturization:Optical sensor arrays now fit within watch-form factors while maintaining waveform fidelity, unlocking consumer-grade deployment at scale.
- South Korea's national digital health infrastructure:Government-backed pilot programs for cuffless monitoring in chronic disease management are creating procurement templates adopted across East Asian markets.
Market Restraints
- EU MDR conformity assessment bottlenecks:Extended notified body review timelines for Class IIa wearable devices delay market access by 12-18 months versus pre-2021 pathways.
- Sensor calibration drift:Optical algorithms require periodic recalibration against oscillometric baselines, creating reliability concerns in unsupervised home environments.
- Semiconductor foundry concentration:Bluetooth Low Energy module supply depends heavily on Taiwan-based fabrication capacity, exposing hardware schedules to geopolitical disruption.
Strategic Opportunities
- Perioperative continuous monitoring:Ambulatory surgical centers lack invasive arterial line infrastructure, creating demand for validated non-invasive alternatives during recovery protocols.
- Japan's Society 5.0 healthcare digitization:METI funding streams prioritize preventive cardiovascular surveillance, directing procurement toward wearable form factors with clinical-grade accuracy.
- AI-enabled arrhythmia-blood pressure correlation:Machine learning models trained on simultaneous PPG and ECG signals open diagnostic applications beyond hypertension management alone.
Industry Challenges
- FDA 510(k) predicate device scarcity:Cuffless optical monitors lack established comparison benchmarks, forcing sponsors toward de novo pathways with expanded clinical trial requirements.
- Interoperability with legacy EHR systems:HL7 FHIR integration remains inconsistently implemented across hospital networks, fragmenting data flow architecture for device vendors.
- Biomedical signal processing talent scarcity:Specialized expertise in artifact rejection algorithms for motion-corrupted PPG waveforms concentrates within academic research labs rather than commercial engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Blood Pressure Monitoring Devices Market |
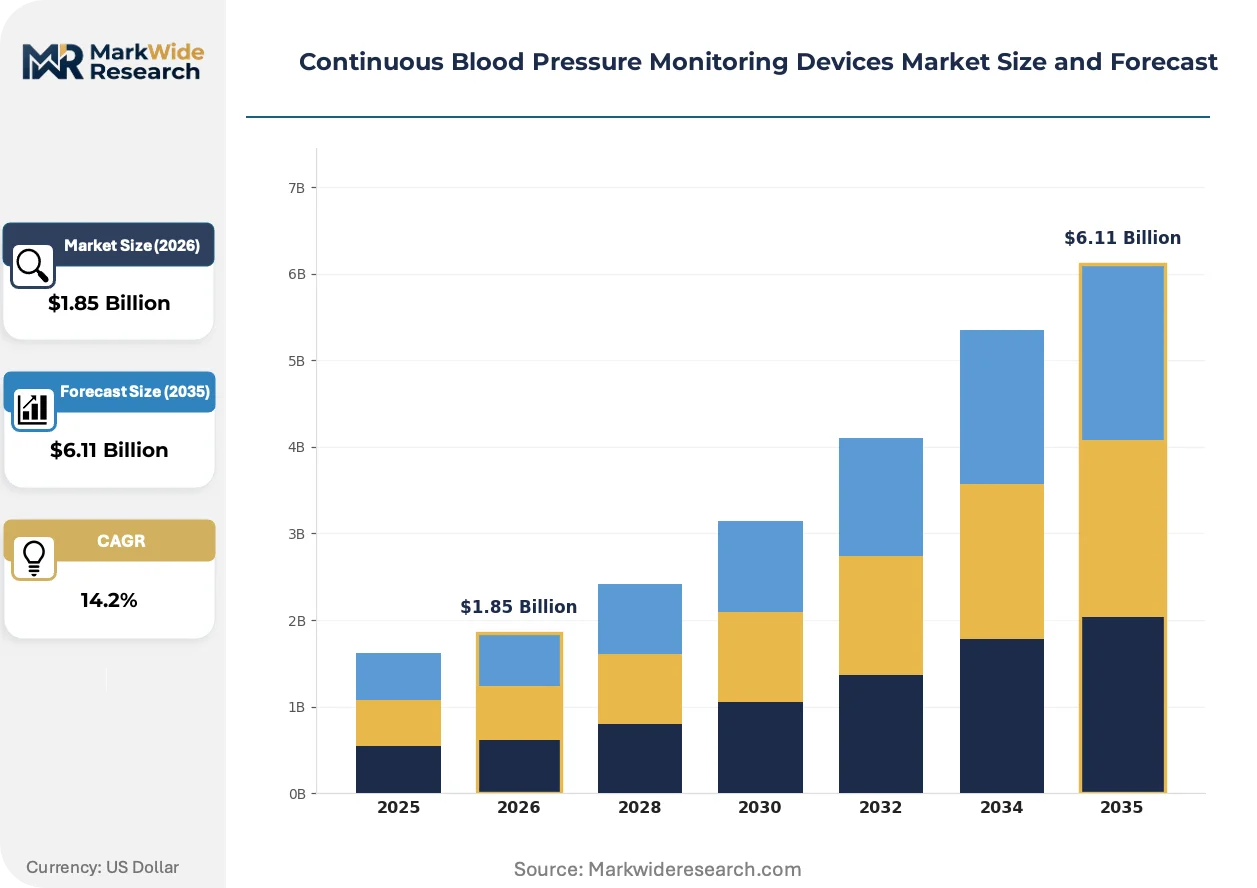
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Mobile Applications, Remote Monitors Technology: Oscillometric, Tonometric, Invasive, Optical End User: Homecare Patients, Hospitals, Clinics, Telehealth Providers Delivery Mode: Telemonitoring, Cloud-Based Platforms, Mobile Alerts, Direct Integration |
| Companies Covered | Omron Healthcare, Philips Healthcare, GE Healthcare, Hill-Rom Holdings, Withings, A&D Medical, SunTech Medical, Biobeat, Aktiia SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Blood Pressure Monitoring Devices Market Strategic Shifts
Continuous blood pressure monitoring is migrating from clinical settings toward ambulatory and home environments, driven by sensor fusion advances and reimbursement model restructuring. Three concurrent developments are reshaping competitive requirements for hardware and platform vendors.
Multi-wavelength photoplethysmography is digitizing arterial waveform capture through simultaneous red, green, and infrared LED arrays processed by adaptive filtering algorithms. Cardiology departments in tertiary hospitals are piloting these systems for post-discharge hypertension management. The technology is digitizing patient data infrastructure by enabling direct-to-cloud transmission without intermediary bedside consoles.
EU MDR's enhanced clinical evidence requirements for wearable physiological monitors are extending development timelines while elevating barrier-to-entry for new market participants. Manufacturers must now submit post-market surveillance plans with defined performance thresholds rather than pre-market equivalence alone. German notified bodies are processing Class IIa device applications at half the rate of 2019, compressing competitive windows for second-mover entrants.
Hospital procurement departments are unbundling device hardware from software analytics platforms, treating continuous monitoring as a service line rather than capital equipment. Health systems in the US are negotiating per-patient-per-month pricing for remote monitoring ecosystems. This restructuring is most visible in Medicare Advantage plan contracts, where risk-adjusted reimbursement creates direct incentives for sustained patient engagement through wearable data streams.
Continuous Blood Pressure Monitoring Devices Market Segmentation
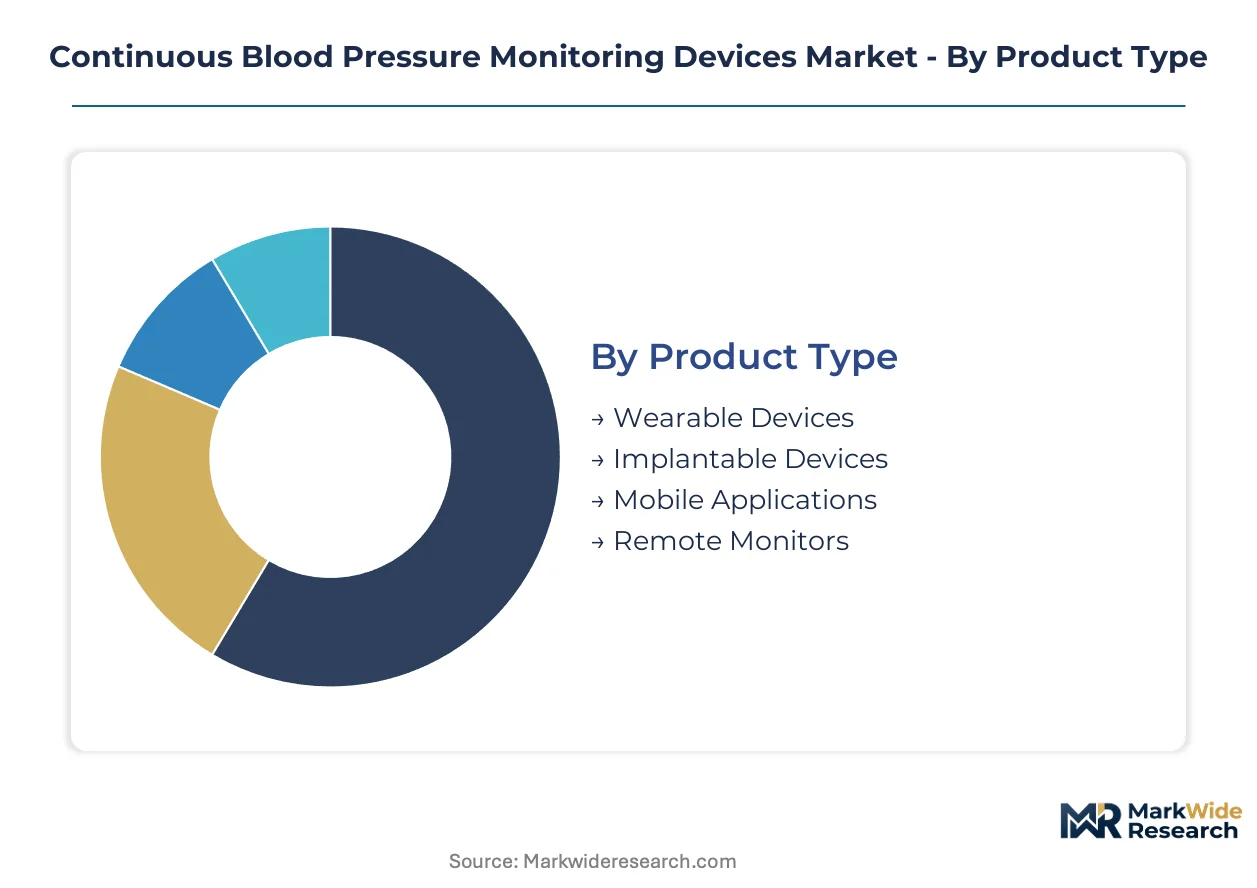
Segmentation in continuous blood pressure monitoring reveals divergent hardware refresh cycles and margin structures. Product type determines capital intensity while technology selection drives regulatory pathway complexity and time-to-market.
Product Type:
Wearable devices turn inventory fastest through consumer retail channels, whereas implantable units operate on extended replacement cycles tied to surgical scheduling.
- Wearable Devices:Photoplethysmography-enabled watches and patches sample arterial waveforms at 30+ Hz. Demand clusters in US Medicare Advantage plans where risk-adjusted reimbursement rewards sustained patient engagement through daily data streams.
- Implantable Devices:Miniaturized pressure sensors with biocompatible encapsulation deliver continuous readings from within the arterial tree. German university hospitals anchor procurement for heart failure monitoring protocols requiring hemodynamic precision unavailable from surface sensors.
- Mobile Applications:Smartphone-based algorithms process camera-captured PPG signals for episodic screening. South Korea's national digital health pilots validate software-only approaches for hypertension population management.
- Remote Monitors:Cellular-connected bedside units transmit data to cloud platforms without patient smartphone dependency. US rural health systems deploy these for home-based chronic disease surveillance where broadband access remains inconsistent.
Wearable devices dominate installed base. Implantable devices are where expansion concentrates in critical-care settings demanding invasive-grade accuracy.
Technology:
Cost tier stratification separates premium invasive monitoring from mass-market optical alternatives, with reimbursement codes determining viable price points across clinical versus home environments.
- Oscillometric:Cuff-based brachial pressure measurement with automated inflation cycles remains the clinical gold standard for calibration reference. Japanese Society 5.0 procurement prioritizes oscillometric validation in wearable form factors for preventive cardiovascular programs.
- Tonometric:Arterial wall applanation sensors capture radial artery pressure waveforms with pulse transit time calculation. Swiss university cardiology departments pilot wrist-worn tonometric systems for ambulatory hypertension management.
- Invasive:Intra-arterial catheter systems deliver beat-to-beat accuracy in operating rooms and ICUs. Australian tertiary hospitals maintain installed base concentration for perioperative hemodynamic optimization.
- Optical:Multi-wavelength LED arrays with adaptive filtering enable cuffless consumer deployment at scale. FDA de novo pathways for optical algorithms are compressing development timelines for sponsors with robust clinical evidence packages.
Optical technology captures volume leadership in consumer channels. Invasive monitoring retains margin concentration in surgical settings where accuracy thresholds exclude non-invasive alternatives.
End User:
Customer type determines purchasing authority structure, with hospital procurement departments negotiating enterprise contracts while homecare patients respond to direct-to-consumer marketing and retail availability.
- Homecare Patients:Individual consumers acquiring devices through retail pharmacy and e-commerce channels. US telehealth reimbursement expansion for remote physiological monitoring codes is accelerating clinical-grade device adoption in residential settings.
- Hospitals:Enterprise procurement of telemetry systems for inpatient wards and emergency departments. EU MDR conformity assessments for Class IIa wearable devices are extending vendor qualification timelines across German and French hospital networks.
- Clinics:Ambulatory care sites requiring portable monitoring for same-day procedures. Canadian primary care networks pilot cuffless optical systems for hypertension screening in resource-constrained community settings.
- Telehealth Providers:Virtual-first healthcare platforms integrating device data into remote care workflows. Cloud-native platform delivery modes are expanding fastest among US-based telehealth operators serving Medicare populations.
Hospitals anchor current revenue concentration. Telehealth providers are climbing the fastest as reimbursement restructuring enables virtual care models at scale.
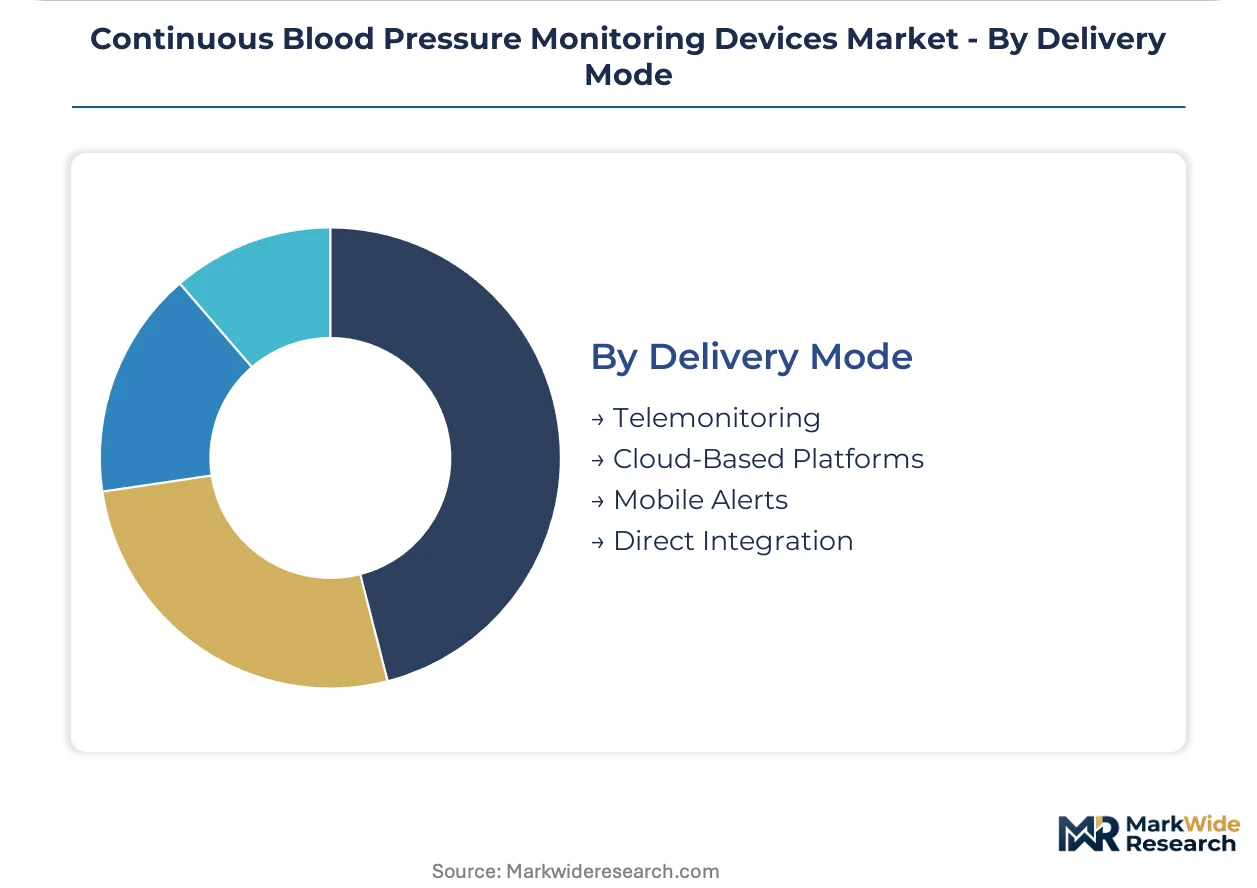
Delivery Mode:
Supply concentration in semiconductor fabrication shapes hardware availability, while software platform maturity determines which delivery architectures achieve clinical workflow integration.
- Telemonitoring:Centralized nursing teams review transmitted data and escalate alerts to physicians. UK National Health Service pilot programs validate telemonitoring for post-discharge heart failure management.
- Cloud-Based Platforms:Scalable data infrastructure enabling population-level analytics and machine learning model training. HL7 FHIR integration requirements are fragmenting vendor competitive position across US hospital networks with inconsistent EHR implementations.
- Mobile Alerts:Patient-facing notifications for threshold breaches and medication reminders. GDPR data-protection constraints shape how European platforms store and transmit hemodynamic data across jurisdictions.
- Direct Integration:API-connected data flows into provider EHR systems without intermediary dashboards. Interoperability certification is becoming a gating factor for US hospital procurement decisions.
Cloud-based platforms dominate vendor R&D investment. Direct integration is where competitive differentiation concentrates as health systems demand seamless EHR connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of optical sensor modules concentrate in economies with advanced healthcare digitization agendas, while device assembly gravitates toward manufacturing clusters with established electronics supply chains. Export competitiveness hinges on regulatory clearance velocity and reimbursement code alignment.
United States
Medicare Advantage plans drive procurement volume through risk-adjusted reimbursement structures rewarding sustained patient engagement. FDA de novo pathways for cuffless optical algorithms compress development timelines for sponsors with robust clinical evidence. The Boston-Cambridge corridor anchors photoplethysmography research talent concentration.
Germany
University hospital procurement for heart failure monitoring protocols sustains demand for invasive-grade accuracy devices. EU MDR conformity assessments extend vendor qualification timelines across hospital networks. The Munich-Stuttgart axis concentrates wearable monitor engineering and notified body consulting capacity.
Japan
METI funding streams under Society 5.0 digitization prioritize preventive cardiovascular surveillance procurement. PMDA consultation procedures for software-as-medical-device classifications shape product roadmaps. The Tokyo-Osaka corridor hosts precision optics manufacturing clusters serving medical device OEMs.
South Korea
Government-backed pilot programs for cuffless monitoring in chronic disease management create procurement templates adopted across East Asian markets. MFDS expedited review pathways for AI-enabled diagnostic software accelerate market access. Seoul's Digital Health Innovation Complex concentrates telehealth platform development.
United Kingdom
NHS pilot programs validate telemonitoring for post-discharge heart failure management, directing procurement toward cloud-integrated systems. MHRA recognition of EU MDR certificates maintains transitional market access for continental manufacturers. The Oxford-Cambridge Arc anchors biomedical signal processing research commercialization.
Continuous Blood Pressure Monitoring Devices Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: diversified healthcare conglomerates leveraging installed telemetry bases, specialized optical sensor developers, and platform-native telehealth integrators. Established medical device incumbents compete through recurring revenue service models, while emerging players attack through cuffless form factor innovation. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent cardiovascular monitoring applications.
Within the diversified healthcare tier, Philips Healthcare and GE Healthcare exemplify scale-driven positioning anchored by hospital telemetry infrastructure. Among specialized developers, Biobeat occupies a position representing photoplethysmography patch innovation, while Aktiia SA sits within the cuffless wrist-worn monitoring archetype. Omron Healthcare anchors the home-use retail channel control segment. These players collectively represent the competitive spectrum from enterprise clinical sales to direct-to-consumer distribution.
| Leading Market Players |
|---|
| Omron Healthcare |
| Philips Healthcare |
| GE Healthcare |
| Hill-Rom Holdings |
| Withings |
| A&D Medical |
| SunTech Medical |
| Biobeat |
| Aktiia SA |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry undercapacity in Bluetooth Low Energy module fabrication is compressing hardware availability timelines and forcing device OEMs into premium pricing postures for optical sensor arrays. This utilization squeeze propagates through contract manufacturer negotiations and elevates component costs for cuffless monitor producers.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium clinical-grade, standard ambulatory, and economy consumer tiers. FDA de novo pathway certification commands substantial premiums over 510(k) predicate equivalents, while volume scale discounts concentrate among Medicare Advantage plan aggregators. Pricing pressure stems from EU MDR conformity assessment delays extending vendor qualification costs. Telehealth platforms exhibit highest price sensitivity due to per-patient-per-month reimbursement constraints.
Supply Chain Analysis
Extended payment terms from South Korean electronics distributors are stabilizing working capital for photoplethysmography LED array suppliers. Component sourcing concentrates in Taiwan for semiconductor modules, Japan for precision optics, and China for battery cell integration. Raw material dependencies include gallium nitride substrates, lithium cobalt oxide cathodes, and medical-grade silicone encapsulants. Single-source vulnerability in Taiwan-based BLE fabrication exposes hardware schedules to geopolitical disruption. Distribution runs through hospital GPO contracts, retail pharmacy chains, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous blood pressure monitoring sits in early-cycle expansion as Medicare remote physiological monitoring reimbursement codes unlock home-based clinical adoption at scale.
For Market Incumbents: Entrench installed telemetry infrastructure through backward integration into cloud platform development and exclusive hospital system partnerships. Cuffless optical sensor startups threaten premium pricing power in ambulatory segments. Prioritize FDA de novo pathway investment to accelerate regulatory clearance velocity against emerging competitors. For New Entrants and Emerging Players: Perioperative monitoring in US ambulatory surgical centers represents the most penetrable entry point given invasive arterial line infrastructure gaps. South Korean government-backed chronic disease pilot programs offer template procurement pathways across East Asian markets. Pursue software-as-medical-device regulatory positioning to bypass hardware manufacturing capital requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across optical algorithm development as photoplethysmography miniaturization matures. Five-to-ten year viability favors platform-native telehealth integrators with established EHR connectivity over pure-play hardware vendors. Signal to monitor: FDA de novo clearance velocity for cuffless algorithms as inflection indicator for competitive positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Investment | Accelerates market access for cuffless optical algorithms against predicate device scarcity constraints. |
| Hospital System Partnership | Locks recurring revenue through remote patient monitoring program integration and telemetry infrastructure. |
| Software Companion Development | Enables AI-enabled arrhythmia-blood pressure correlation beyond hypertension management alone. |
| CE Marking Pathway | Navigates EU MDR conformity assessment bottlenecks for Class IIa wearable device market access. |
| Reimbursement Strategy | Aligns remote physiological monitoring codes with Medicare Advantage risk-adjusted reimbursement structures. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, telehealth platform CTOs, GPO contracts managers, and photoplethysmography R&D directors. Secondary validation drew from FDA 510(k) and de novo submission databases, CMS Medicare reimbursement code filings, EU MDR notified body assessment records, and hospital procurement contract disclosures. Bottom-up device shipment modeling triangulated against top-down healthcare expenditure allocation estimates.
Calibration against historical regulatory clearance timelines and reimbursement adoption curves anchored projection methodology across the analysis window. Segmentation dimensions modeled include product type, technology platform, end-user archetype, and delivery mode complexity. CAGRs derived from fitted adoption curves incorporating optical sensor miniaturization trajectories and telehealth reimbursement expansion scenarios. Forecast inputs included semiconductor foundry capacity utilization rates and EU notified body processing velocity indices.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, semiconductor trade flows, or EU regulatory processing capacity would shift the trajectory. Forecasts reflect documented assumptions regarding optical algorithm validation standards and remote monitoring code permanence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market