
 Non-Infectious Macular Edema Treatment Market | 2026-2036
Non-Infectious Macular Edema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Infectious Macular Edema Treatment Market Analytics
Buyer concentration across ophthalmology clinics is rebalancing as independent practices consolidate into multi-site retinal care networks while hospital-affiliated eye institutes fragment into specialized ambulatory surgery centers. Novartis AG leverages its sustained-release implant pipeline to anchor positions in maintenance therapy segments. Regeneron Pharmaceuticals competes through high-dose aflibercept formulations that extend dosing intervals. F. Hoffmann-La Roche sustains R&D intensity in bispecific antibody architectures for refractory cases.
Non-infectious macular edema treatment encompasses pharmacological and procedural interventions targeting fluid accumulation in the macula without infectious etiology, primarily employing intravitreal anti-VEGF agents that inhibit vascular permeability signaling or corticosteroid implants that modulate inflammatory cytokine cascades, with micropulse laser emerging as a tissue-sparing alternative to conventional photocoagulation. Anti-VEGF agents dominate value pools due to chronic reinjection requirements, though steroid implants capture premium positioning in pseudophakic patients seeking reduced treatment burden. Intravitreal injection remains the procedural backbone, while topical administration routes represent an active development frontier targeting patient compliance gaps.
The FDA governs ocular biologic approvals through specialized ophthalmology divisions, while the EMA's MDR framework imposes escalating clinical evidence requirements on sustained-release devices, collectively elevating barriers for novel entrants without established retinal expertise. Health Canada and Australia's TGA align with FDA precedents on anti-VEGF biosimilar pathways, compressing originator exclusivity windows across North American and Asia-Pacific markets. Stakeholders must monitor real-world evidence generation capabilities and payer contracting dynamics as anti-VEGF commoditization accelerates and gene therapy approaches advance through early-phase trials.
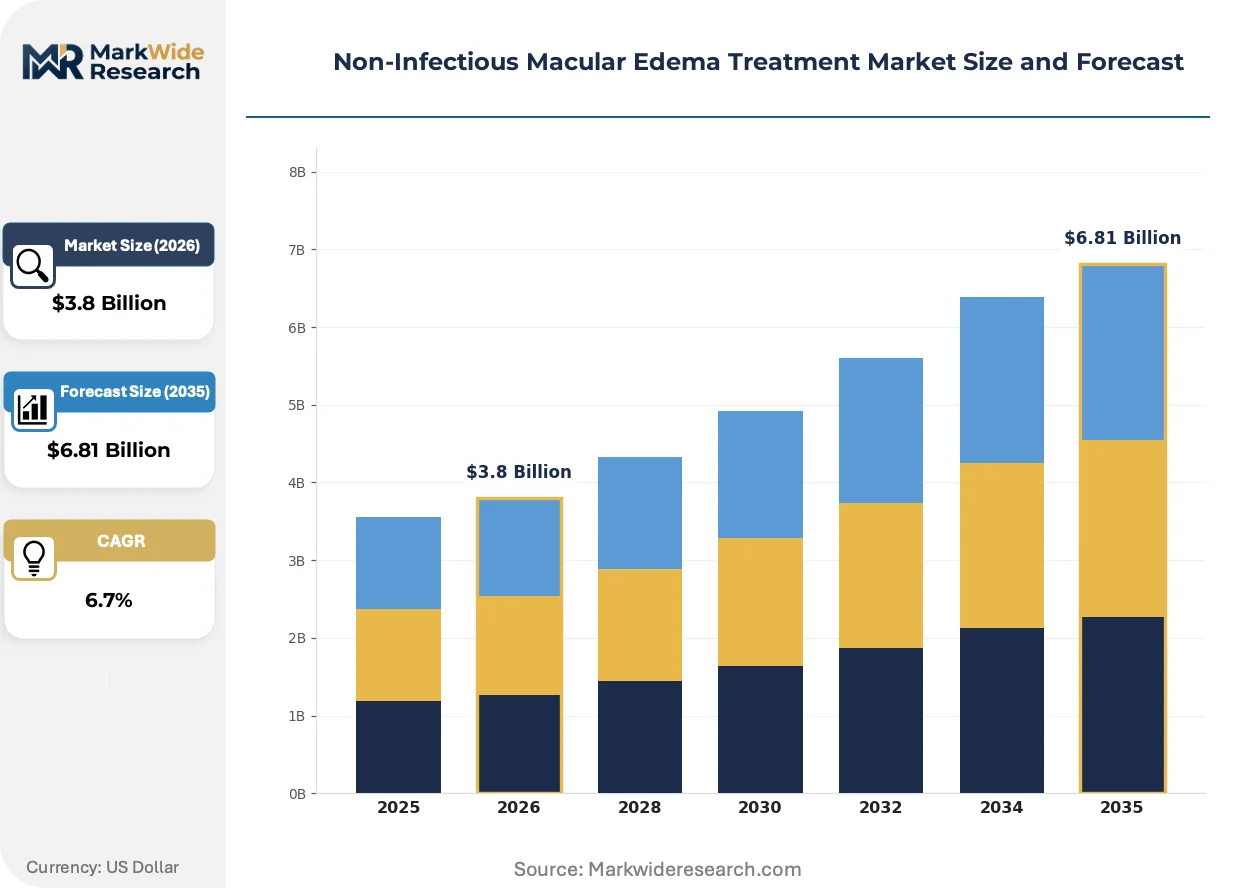
Market Dynamics
The FDA's accelerated approval pathways for sustained-release ocular implants are compressing development timelines and forcing incumbents to retool manufacturing for depot-based delivery systems rather than conventional vial-and-syringe formats.
Growth Catalysts
- Intravitreal anti-VEGF protocols:Ophthalmology clinics are expanding adoption of these first-line therapies as standard care for diabetic macular edema and retinal vein occlusion.
- MDR framework compliance:The EMA's escalating clinical evidence requirements for sustained-release devices are paradoxically validating premium positioning for approved products.
- Medicare reimbursement structures:United States outpatient retinal procedures receive favorable coverage, concentrating demand in ambulatory surgery centers.
Market Restraints
- Silicone oil and polymer feedstock volatility:Sustained-release implant manufacturing depends on specialized medical-grade materials with concentrated supplier bases.
- Intravitreal injection skill concentration:Retinal specialists capable of safe posterior segment delivery cluster in urban academic medical centers, limiting rural access.
- Anti-VEGF biosimilar commoditization:Health Canada and Australia's TGA alignment with FDA pathways is compressing originator exclusivity windows.
Strategic Opportunities
- Gene therapy advancement:Early-phase trials for one-time genetic interventions target chronic reinjection fatigue among pseudophakic patients.
- Topical administration routes:Penetrating eye drop formulations address compliance gaps in elderly populations struggling with monthly clinic visits.
- Real-world evidence generation:Payer contracting dynamics increasingly favor manufacturers with robust post-market surveillance capabilities.
Industry Challenges
- Vitreoretinal surgical fellowship pipeline:Training programs produce insufficient specialists to match expanding patient volumes.
- Cleanroom manufacturing capex:Aseptic filling capacity for biologics requires eight-figure facility investments with multi-year construction timelines.
- ISO 13485 and MDR dual certification:Device-biologic combination products face overlapping quality system audits from multiple notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Infectious Macular Edema Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Agents, Steroids, Laser Therapy, Micropulse Laser End User: Hospitals, Ophthalmology Clinics, Research Institutions, Home Care Settings Delivery Mode: Intravitreal Injection, Topical Administration, Systemic Administration, Surgical Intervention Treatment Stage: First-line Treatment, Second-line Treatment, Combination Therapy, Maintenance Therapy |
| Companies Covered | Novartis AG, Regeneron Pharmaceuticals, F. Hoffmann-La Roche, Allergan (AbbVie), Bayer AG, Amgen, Pfizer, Kodiak Sciences, Clearside Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Infectious Macular Edema Treatment Market Evolving Landscape
Sustained-release depot formulations are disrupting chronic reinjection paradigms, while regulatory convergence across North American and Asia-Pacific markets accelerates biosimilar entry. Micropulse laser technology is carving maintenance therapy niches previously reserved for pharmacological intervention.
Micropulse laser systems deliver subthreshold thermal energy to the retinal pigment epithelium without visible photocoagulation scars. Retinal specialists in high-volume academic centers are adopting these platforms for patients with persistent fluid despite anti-VEGF therapy. This tissue-sparing modality is overtaking conventional photocoagulation in maintenance-phase treatment algorithms.
The FDA's specialized ophthalmology divisions have streamlined breakthrough therapy designations for sustained-release implants, reducing Phase III enrollment requirements. EMA's MDR framework imposes stricter post-market surveillance on these same devices, creating divergent compliance burdens. Manufacturers with established European notified body relationships are capturing first-mover advantage in depot-based delivery.
Independent ophthalmology practices are consolidating into multi-site retinal care networks to secure favorable anti-VEGF purchasing contracts. Hospital-affiliated eye institutes are fragmenting into specialized ambulatory surgery centers to optimize Medicare reimbursement capture. This structural reorganization is most visible in United States metropolitan markets where payer consolidation has intensified price negotiation leverage.
Non-Infectious Macular Edema Treatment Market Segmentation
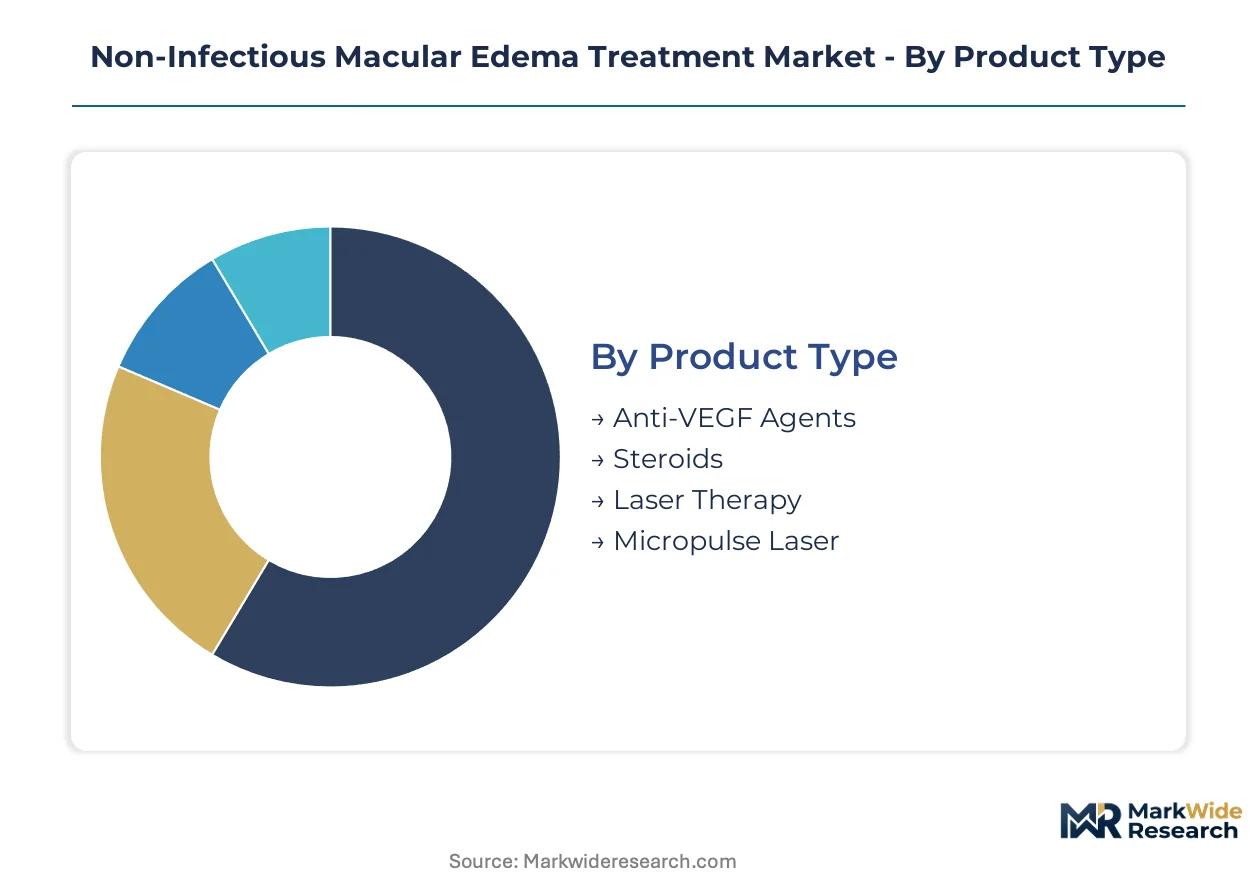
Non-infectious macular edema treatment segments diverge sharply between chronic reinjection-dependent modalities and one-time procedural interventions. Product type stratification reveals anti-VEGF volume dominance against steroid implant premium capture, while delivery mode and treatment stage classifications expose compliance-driven innovation frontiers.
Product Type:
Anti-VEGF agents command volume share through monthly injection requirements, while sustained-release steroid implants capture premium positioning in pseudophakic populations seeking reduced treatment burden.
- Anti-VEGF Agents:Intravitreal biologics inhibit vascular endothelial growth factor signaling to reduce retinal permeability. Demand concentrates in United States ophthalmology clinics where Medicare reimbursement supports frequent reinjection schedules, though biosimilar entry is compressing originator pricing power.
- Steroids:Corticosteroid implants and triamcinolone formulations modulate inflammatory cytokine cascades through sustained intravitreal release. Pseudophakic patients in academic medical centers drive adoption for refractory cases where anti-VEGF monotherapy fails, accepting elevated cataract and glaucoma risk profiles.
- Laser Therapy:Conventional photocoagulation delivers thermal energy to microaneurysms and leaking vessels.
- Micropulse Laser:Subthreshold diode laser systems spare retinal tissue through duty-cycle modulation.
Mature deployment sits with Anti-VEGF Agents. Newer deployment is concentrated in Micropulse Laser.
End User:
Institutional purchasing power separates high-volume academic centers from distributed community practice networks, with reimbursement mechanics determining site-of-care migration patterns.
- Hospitals:Tertiary care centers manage complex comorbid cases requiring multidisciplinary coordination. United States hospital-affiliated eye institutes fragment into specialized ambulatory surgery centers to optimize Medicare reimbursement capture, concentrating surgical intervention volumes in metropolitan markets.
- Ophthalmology Clinics:Independent retinal practices and multi-site networks dominate anti-VEGF administration. Consolidation into purchasing cooperatives strengthens contract negotiation leverage against manufacturer pricing, particularly in competitive Florida and California markets.
- Research Institutions:Academic medical centers host gene therapy trials and sustained-release device investigations.
- Home Care Settings:Self-administered topical formulations remain investigational with no approved home-based intravitreal protocols.
Revenue concentration favors Ophthalmology Clinics. Steepest expansion trajectory is emerging in Research Institutions.
Delivery Mode:
Procedural skill requirements create supply-side bottlenecks that shape competitive dynamics across administration routes.
- Intravitreal Injection:Posterior segment needle delivery remains the pharmacological backbone. Vitreoretinal surgical fellowship training constraints limit specialist supply, clustering capable providers in urban United States academic centers and restricting rural access.
- Topical Administration:Penetrating eye drop formulations target patient compliance gaps. Development programs focus on elderly diabetic populations struggling with monthly clinic visit burdens.
- Systemic Administration:Oral and intravenous routes address bilateral disease or patient refusal of ocular injection.
- Surgical Intervention:Vitrectomy with membrane peeling resolves tractional components.
Established utilization centers on Intravitreal Injection. Development-stage investment flows toward Topical Administration.
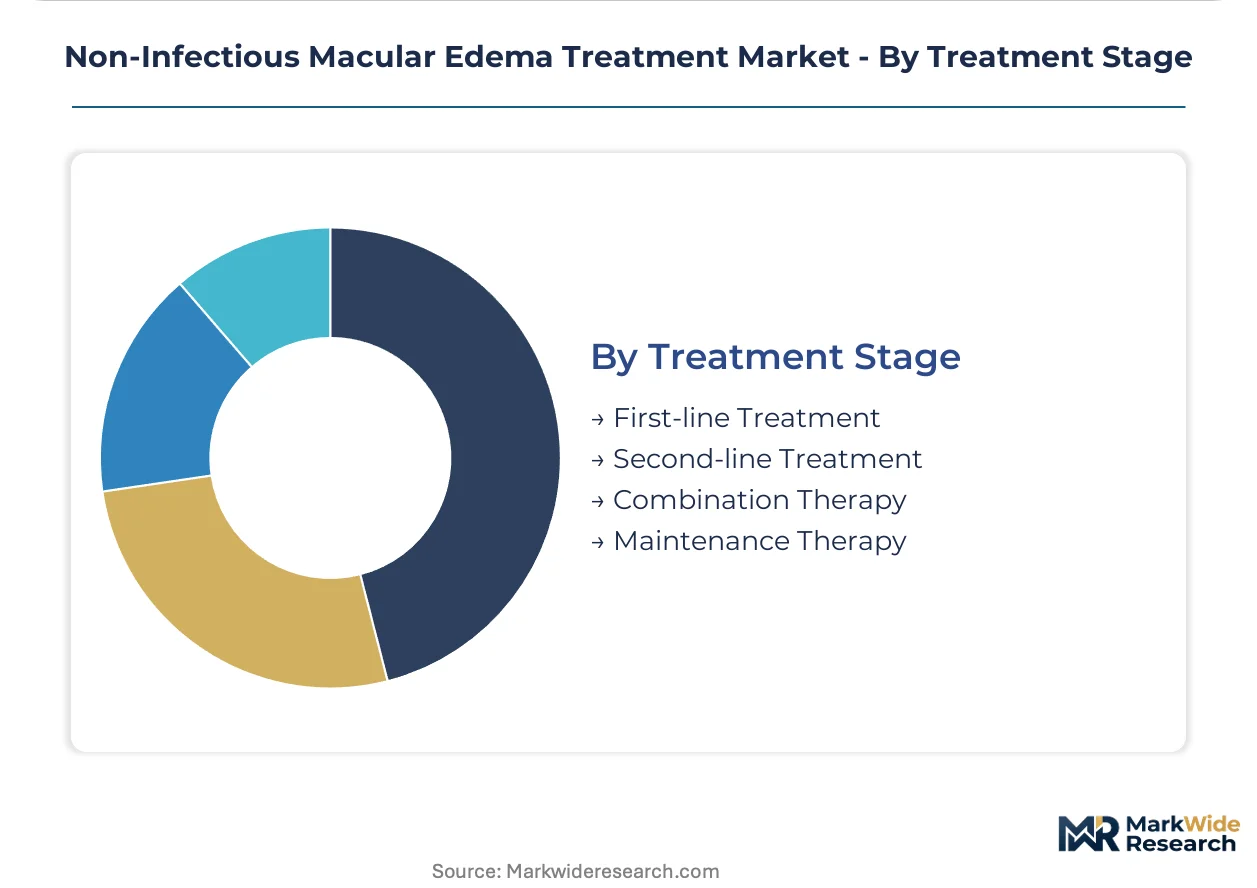
Treatment Stage:
Algorithm positioning determines pricing power and duration of commercial exclusivity across the care continuum.
- First-line Treatment:Anti-VEGF monotherapy dominates initial diabetic macular edema and retinal vein occlusion management. FDA-approved agents anchor formulary placement through extensive real-world evidence libraries.
- Second-line Treatment:Steroid implants and combination protocols activate after anti-VEGF failure. Pseudophakic status becomes a critical patient selection criterion given cataractogenesis risk.
- Combination Therapy:Simultaneous anti-VEGF and steroid administration or laser adjuncts address persistent fluid.
- Maintenance Therapy:Extended-interval dosing and sustained-release depots target reinjection fatigue. Novartis leverages its implant pipeline to anchor positions in this segment.
Volume scale resides with First-line Treatment. Commercial development intensity is shifting toward Maintenance Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ophthalmology clinics generate the dominant share of procedural volume, with Medicare reimbursement mechanics concentrating anti-VEGF administration in ambulatory surgery centers across metropolitan markets.
United States
Retinal specialists cluster in academic medical centers along the Boston-Cambridge corridor and Manhattan, where fellowship-trained providers manage complex diabetic macular edema cases. FDA breakthrough therapy designations for sustained-release implants compress development timelines for depot-based delivery systems. The Cleveland Clinic and Bascom Palmer Eye Institute anchor multi-site networks that negotiate favorable anti-VEGF purchasing contracts.
Germany
EMA MDR framework compliance elevates clinical evidence requirements for sustained-release devices, validating premium positioning for approved steroid implants. Germany's notified bodies conduct overlapping quality system audits for device-biologic combination products. The Rhine-Main region hosts specialized ophthalmology practices consolidating into purchasing cooperatives to strengthen manufacturer negotiation leverage.
Japan
PMDA regulatory alignment with FDA precedents accelerates anti-VEGF biosimilar pathways, compressing originator exclusivity windows. Japan's aging diabetic population drives demand for reduced treatment burden in pseudophakic patients. Tokyo and Osaka academic centers pioneer micropulse laser adoption for maintenance-phase therapy algorithms.
United Kingdom
NICE technology appraisals prioritize cost-effectiveness thresholds for intravitreal therapy selection in National Health Service retinal services. The UK's MHRA post-Brexit regulatory autonomy enables accelerated access schemes for novel sustained-release formulations. Moorfields Eye Hospital and Manchester Royal Eye Hospital anchor specialized networks generating real-world evidence for payer contracting.
Australia
TGA alignment with FDA anti-VEGF biosimilar pathways mirrors North American regulatory convergence patterns. Australia's geographically dispersed population concentrates vitreoretinal surgical expertise in Sydney and Melbourne academic centers. The Pharmaceutical Benefits Scheme reimbursement structures favor outpatient retinal procedures, concentrating demand in specialized ophthalmology clinics.
Non-Infectious Macular Edema Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue depot-based delivery and gene therapy vectors as differentiation vectors. Market structure concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with retinal franchises, biotechnology specialists in sustained-release architectures, and emerging platform companies targeting one-time genetic interventions. Competitive dynamics center on manufacturing scale for aseptic filling capacity and real-world evidence generation capabilities for payer contracting.
Within the diversified pharmaceutical tier, Novartis AG and F. Hoffmann-La Roche occupy positions anchored by established intravitreal franchises and implant pipeline investments. Regeneron Pharmaceuticals exemplifies the biotechnology specialist archetype, with its high-dose formulation strategy representing an approach to extend dosing intervals and reduce treatment burden. These three entities collectively illustrate the competitive tension between chronic reinjection paradigms and sustained-release depot formulations reshaping maintenance therapy positioning.
| Leading Market Players |
|---|
| Novartis AG |
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche |
| Allergan (AbbVie) |
| Bayer AG |
| Amgen |
| Pfizer |
| Kodiak Sciences |
| Clearside Biomedical |
| Others |
Value Network & Pricing Analysis
Multi-site retinal care networks in the United States concentrate purchasing power through group purchasing organizations, anchoring contract-based pricing for intravitreal biologics while Medicare reimbursement mechanics cap outpatient procedure margins.
Pricing Analysis
Volume scale resides with anti-VEGF agents, while margin capture concentrates in sustained-release steroid implants. Three-tier pricing structure across premium depot formulations, standard intravitreal biologics, and economy-positioned biosimilars reflects FDA approval tier and real-world evidence depth. Cost compression in standard biologics is intensifying because Health Canada and TGA alignment with FDA biosimilar pathways accelerates originator erosion. Community ophthalmology clinics exhibit highest price sensitivity due to thin reimbursement spreads, whereas academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
ISO 13485 and MDR dual certification requirements gate supplier entry for device-biologic combination products, elevating qualification burdens for sustained-release implant components. Manufacturing concentrates in the United States, Germany, and Switzerland, where notified body relationships and aseptic filling infrastructure cluster. Medical-grade silicone oil and polymer feedstocks draw from concentrated chemical supplier bases in Germany and Japan. Single-source vulnerability for specialized polymer resins creates exposure to feedstock volatility. Distribution runs through cold-chain logistics networks serving ambulatory surgery centers and hospital-affiliated eye institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR framework compliance costs erect a barrier-to-entry moat that favors established players with European notified body relationships and multi-year quality system investments.
For Market Incumbents: Deepen vertical integration into aseptic filling capacity to secure biologic supply continuity against cleanroom manufacturing capex inflation. Consolidate real-world evidence generation capabilities to strengthen payer contracting leverage as anti-VEGF commoditization accelerates. Threat: gene therapy platform companies targeting one-time interventions. Lever: backward integration into polymer feedstock supply agreements. For New Entrants and Emerging Players: Rural ophthalmology clinics lacking retinal specialist access represent the most penetrable buyer archetype for topical administration route development. Micropulse laser maintenance therapy algorithms in Japan and United Kingdom academic centers offer white-space positioning against pharmacological incumbents. Go-to-market angle: penetrate through purchasing cooperatives in consolidated Florida and California markets with compliance-light device offerings. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotechnology specialists with sustained-release device pipelines in Germany and Switzerland, where MDR transition costs strain mid-cap balance sheets. Long-term viability centers on manufacturers with depot-based delivery architectures and gene therapy vector capabilities. Signal to watch: FDA breakthrough therapy designation velocity for sustained-release implants as inflection indicator for platform validation.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Dual Certification Investment | EMA notified body relationships secure European market access for depot-based delivery systems. |
| Real-World Evidence Generation | Moorfields Eye Hospital and Cleveland Clinic partnerships strengthen Medicare payer contracting leverage. |
| Aseptic Filling Capacity Expansion | Multi-site retinal care networks demand reliable biologic supply for high-frequency anti-VEGF protocols. |
| Gene Therapy Platform Development | One-time genetic interventions target chronic reinjection fatigue among pseudophakic patient populations. |
| Topical Formulation Advancement | Penetrating eye drop development addresses compliance gaps in elderly diabetic macular edema patients. |
Research Methodology
FDA filings, EMA MDR submission databases, and ClinicalTrials.gov formed the secondary backbone, cross-referenced against CMS Medicare reimbursement data and hospital procurement records. Primary interviews with vitreoretinal specialists, formulary directors at academic medical centers, GPO contracts managers, and regulatory affairs leads at sustained-release device manufacturers validated demand assumptions. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Historical trendline analysis of intravitreal injection procedure volumes and anti-VEGF agent sales trajectories informed baseline calibration across the projection horizon. Segmentation dimensions encompassed product type, delivery mode, treatment stage, and end-user institutional category. CAGRs derived from logarithmic trend fitting of approved therapy adoption curves, adjusted for biosimilar entry velocity and sustained-release device pipeline maturation. Forecast inputs incorporated vitreoretinal surgical fellowship graduation rates and cleanroom manufacturing capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy clinical trial readouts and FDA accelerated approval pathway evolution. Model outputs reflect assumptions regarding Medicare reimbursement stability and EMA MDR enforcement consistency. A model refresh is warranted upon material change in anti-VEGF biosimilar interchangeability determinations or sustained-release implant safety signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Vision Care Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Brazil Ophthalmic Devices Market