
 Non-Destructive Medical Technologies Market | 2026-2036
Non-Destructive Medical Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Destructive Medical Technologies Market Outlook
A capital-intensity divergence between installed-base incumbents and emerging point-of-care specialists is reorganizing competitive dynamics across non-destructive medical imaging. Siemens Healthineers leverages its magnet manufacturing scale to dominate superconducting MRI supply chains. Fujifilm Holdings Corporation specializes in digital X-ray detector panels, anchoring its position in retrofit markets across Asia-Pacific and European hospital networks.
Non-destructive medical technologies encompass imaging and diagnostic systems that evaluate tissue, organ, and skeletal integrity without invasive incision or radiation exposure beyond calibrated safety thresholds, typically operating at field strengths from 1.5 to 7 Tesla for MRI or frequency ranges of 2-18 MHz for diagnostic ultrasound. Their primary purpose centers on early disease detection, treatment planning, and post-therapeutic monitoring while minimizing patient risk and recovery time. Ultrasound systems lead volume deployment in outpatient clinics due to lower capital requirements and portability, while MRI machines command the deepest margin pools tied to neurology and oncology applications requiring high soft-tissue resolution. CT scanners remain structurally mature in hospital settings, with replacement cycles now stretching as facilities prioritize AI-enabled image reconstruction over hardware turnover.
FDA 510(k) premarket notification requirements shape product development timelines for US-bound manufacturers, while EU MDR conformity assessment and CE marking protocols govern market access across European member states. Japan's PMDA enforces stringent clinical evidence standards for novel imaging modalities, filtering out undercapitalized entrants. Stakeholders must monitor convergence between regulatory data requirements and AI diagnostic software qualification pathways to anticipate which technology platforms will secure accelerated approval designations.
Market Dynamics
Magnet supply concentration among three Japanese and German superconductor foundries is forcing imaging OEMs to renegotiate long-term procurement contracts or pursue backward integration into cryogenic wire production.
Growth Catalysts
- EU MDR conformity acceleration:Streamlined CE marking pathways for Class IIa diagnostic devices are compressing time-to-market for ultrasound and digital X-ray manufacturers targeting European hospital networks.
- Outpatient clinic expansion:Portable ultrasound systems with AI-assisted image interpretation are penetrating ambulatory surgical centers and primary care practices across India and Brazil.
- Helium-3 recycling infrastructure:Closed-loop cryogen recovery systems are extending MRI magnet operational lifespans and reducing dependency on volatile noble gas supply chains.
Market Restraints
- Superconducting wire supply chokepoint:Niobium-titanium filament production concentrates in a single Japanese industrial cluster, exposing OEMs to earthquake and trade disruption risks.
- FDA 510(k) evidentiary inflation:Software-as-medical-device classification for AI diagnostic modules now requires prospective clinical validation studies, extending clearance timelines.
- CT scanner replacement drought:Extended depreciation schedules and AI reconstruction software upgrades are deferring hardware refresh cycles in US hospital systems.
Strategic Opportunities
- Sub-Saharan Africa point-of-care gap:Solar-powered, tablet-integrated ultrasound units address radiologist scarcity in Nigeria and Kenya's rural health districts.
- Japan PMDA fast-track designation:Breakthrough medical device status for photon-counting CT detectors offers accelerated review for manufacturers with novel material science.
- Cloud-native PACS convergence:Edge-computing architectures and 5G transmission protocols are enabling teleradiology networks to bypass on-premise infrastructure investments.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized magnet maintenance technicians command premium wages as training pipelines fail to match installed-base expansion.
- Legacy DICOM integration friction:Hospital information systems built on 1990s-era protocols resist seamless API connectivity with modern AI diagnostic overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Destructive Medical Technologies Market |
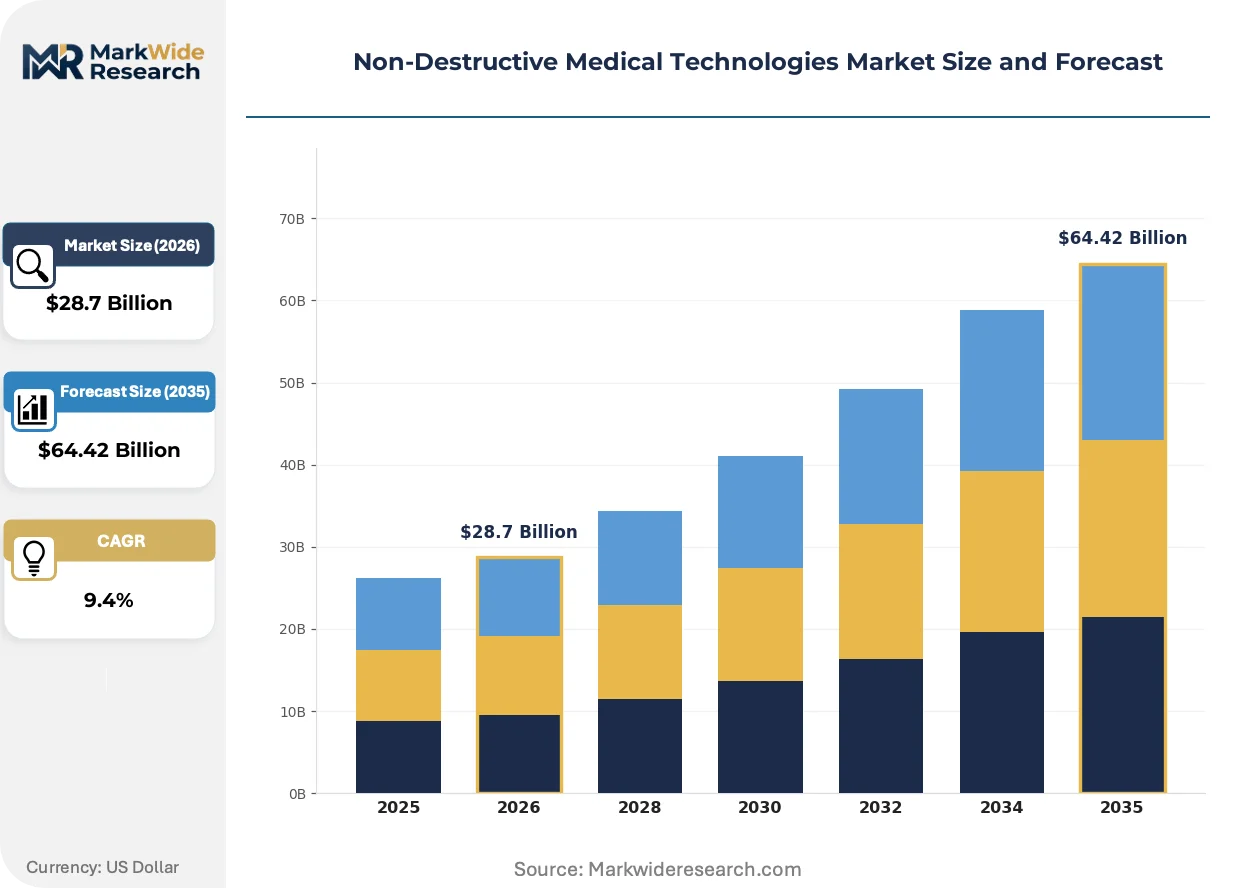
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Imaging, Ultrasound Systems, MRI Machines, CT Scanners Technology: Ultrasonic, Electromagnetic Radiation, Magnetic Field, Thermal Imaging End User: Hospitals, Outpatient Clinics, Research Laboratories, Academic Institutions Application: Cardiology, Oncology, Orthopedics, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Fujifilm Holdings Corporation, Hitachi Medical Corporation, Medtronic, Carestream Health, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Destructive Medical Technologies Market Strategic Shifts
Artificial intelligence is restructuring how diagnostic images are acquired, interpreted, and reimbursed, compressing radiologist workflow time while elevating hardware performance requirements.
Photonic detector materials are fragmenting traditional scintillator-crystal supply chains in CT imaging. Cadmium zinc telluride direct-conversion sensors eliminate light-loss intermediaries, enabling spectral imaging at reduced radiation dose. Siemens Healthineers and Canon Medical are retrofitting premium gantry lines with photon-counting modules, while academic medical centers in Germany and Massachusetts negotiate priority allocation contracts.
FDA's evolving software pre-certification pilot is reshaping AI diagnostic module deployment timelines. The program permits continuous algorithmic updates without redundant 510(k) submissions for validated manufacturers. Radiology groups in Texas and California are piloting these pathways for mammography triage tools, though liability frameworks for autonomous reads remain unresolved.
After-sales service unbundling is disrupting traditional equipment financing bundles. Hospital procurement departments in France and the Netherlands now negotiate separate contracts for hardware, software licenses, and maintenance labor. Independent service organizations specializing in MRI coldhead refurbishment are capturing mid-life system contracts previously held by OEM captive service arms.
Non-Destructive Medical Technologies Market Segmentation
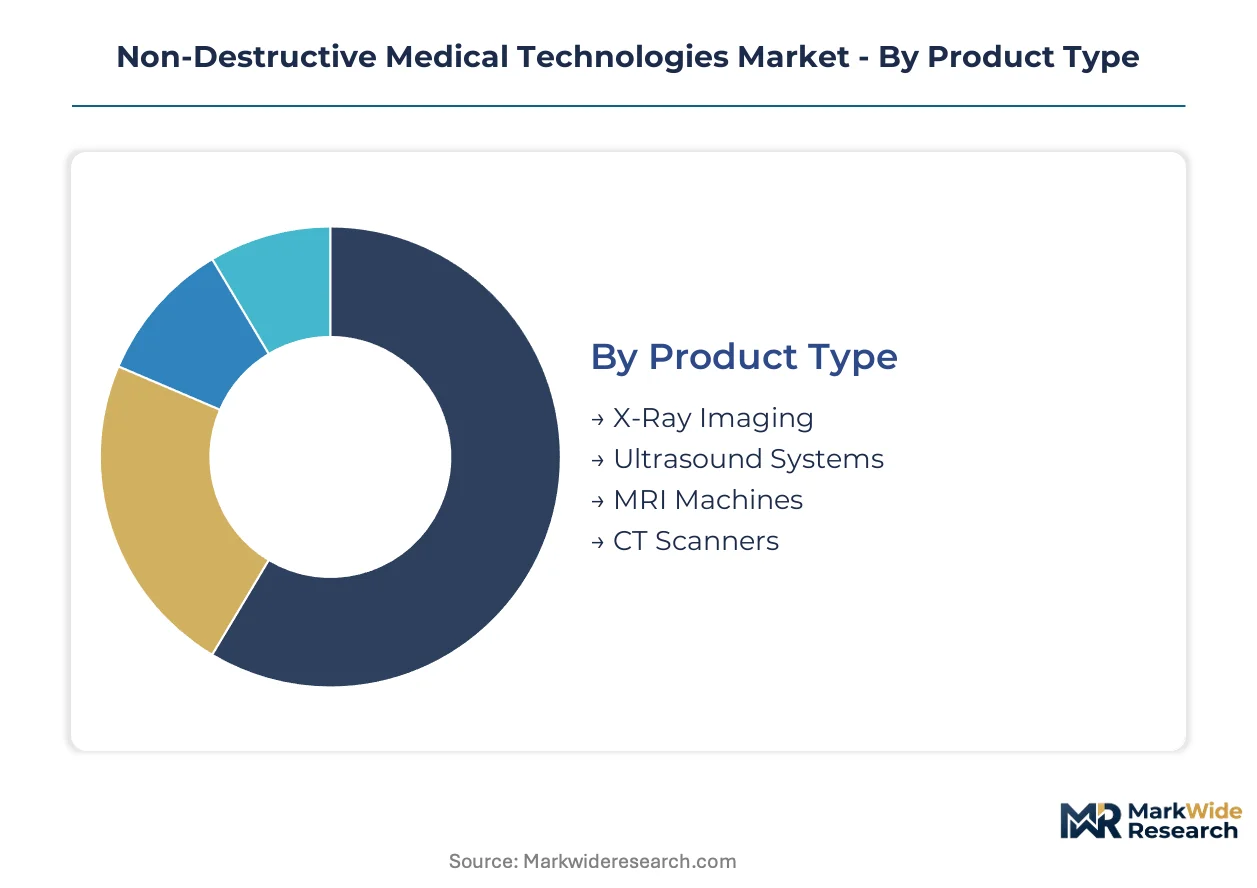
Segmentation in non-destructive medical technologies reveals divergent capital requirements, regulatory pathways, and geographic deployment patterns across imaging modalities. Procurement priorities differ sharply between hospital networks seeking high-field MRI platforms and outpatient operators optimizing for portable ultrasound economics.
Product Type:
Domestic manufacturing concentration varies sharply across product categories, with superconducting MRI and CT scanner assembly anchoring German and Japanese industrial clusters while ultrasound and digital X-ray production disperses across contract manufacturers in China and South Korea.
- MRI Machines:Superconducting systems utilizing niobium-titanium magnets operating at 1.5 to 7 Tesla field strengths. Demand concentrates in German and US academic medical centers pursuing neurology and oncology applications requiring high soft-tissue resolution, constrained by helium-3 supply volatility and cryogenic engineering talent scarcity.
- Ultrasound Systems:Piezoelectric transducer arrays operating across 2-18 MHz frequency ranges for real-time tissue imaging. Portable configurations penetrate Indian and Brazilian outpatient clinics where capital constraints favor lower-cost deployment, accelerated by AI-assisted image interpretation modules reducing radiologist dependency.
- X-Ray Imaging:Digital radiography detector panels replacing analog film cassettes in European and Asia-Pacific hospital retrofit programs.
- CT Scanners:Rotating gantry systems with photon-counting detector upgrades extending operational lifespans in mature US hospital installed bases.
MRI machines command the established base. The steepest expansion runs through ultrasound systems.
Technology:
Technology selection correlates directly with end-use application requirements, where magnetic field and electromagnetic radiation modalities serve high-acuity hospital settings while ultrasonic platforms dominate cost-sensitive ambulatory environments.
- Magnetic Field:Superconducting electromagnet assemblies generating homogeneous fields for nuclear magnetic resonance signal detection. Demand clusters in German university hospitals and Japanese specialty centers performing advanced spectroscopy, with procurement cycles extending due to EU MDR conformity documentation requirements.
- Ultrasonic:Piezoelectric crystal oscillation producing acoustic impedance maps without ionizing radiation exposure. Point-of-care adoption accelerates across Nigerian and Kenyan rural districts addressing radiologist scarcity through solar-powered, tablet-integrated portable units.
- Electromagnetic Radiation:X-ray photon detection across diagnostic energy spectra for skeletal and thoracic imaging protocols.
- Thermal Imaging:Infrared sensor arrays detecting surface temperature differentials for vascular and inflammatory assessment applications.
Magnetic field technology anchors high-value hospital procurement. Ultrasonic platforms are gaining share fastest across emerging market outpatient networks.
End User:
End-user segmentation tracks facility-level capital availability and reimbursement structure complexity, with hospital networks amortizing multi-million dollar MRI installations across high patient volumes while outpatient clinics prioritize mobile ultrasound with rapid payback periods.
- Hospitals:Integrated health systems operating centralized radiology departments with 24/7 diagnostic capacity. German, Japanese, and US hospital networks drive MRI and CT procurement, navigating FDA 510(k) and EU MDR parallel certification pathways for multi-territory equipment deployment.
- Outpatient Clinics:Ambulatory surgical centers and primary care practices performing same-day diagnostic protocols. Brazilian and Indian clinic chains expand portable ultrasound fleets, leveraging lower capital thresholds and streamlined staff training requirements.
- Research Laboratories:Preclinical imaging facilities supporting pharmaceutical development pipelines.
- Academic Institutions:Medical training programs requiring teaching-dedicated equipment with standardized protocols.
Hospitals retain the dominant installed base. Outpatient clinics show the steepest expansion trajectory across developing economy health systems.
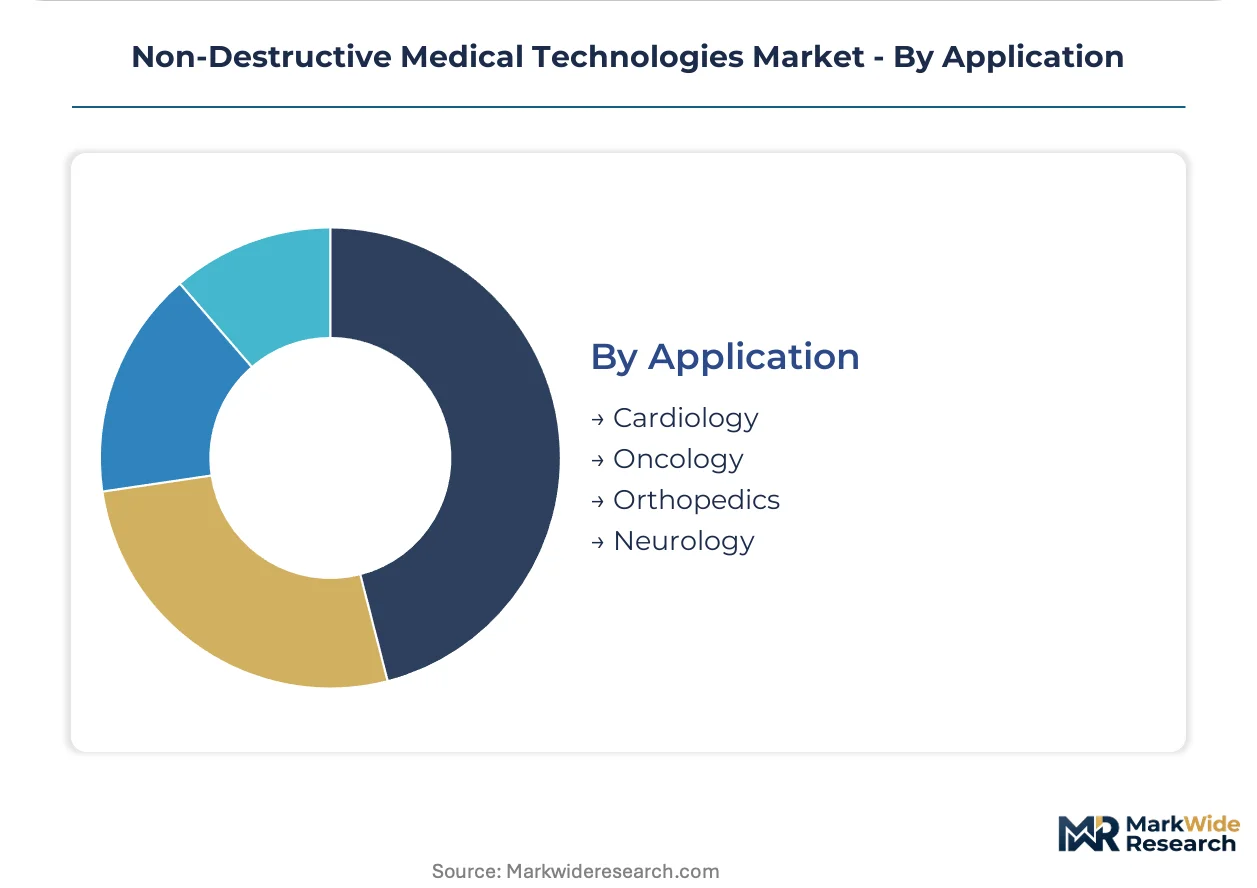
Application:
Application segmentation reflects disease prevalence patterns and reimbursement intensity, with oncology and neurology commanding premium imaging modalities due to diagnostic complexity and therapeutic monitoring requirements.
- Oncology:Tumor detection, staging, and treatment response monitoring across solid and hematologic malignancies. Demand concentrates in Massachusetts and German academic centers piloting photon-counting CT detectors under Japan PMDA fast-track designation pathways, with spectral imaging enabling reduced radiation dose protocols.
- Neurology:Brain parenchyma, vascular, and functional imaging for degenerative and acute cerebrovascular conditions. High-field MRI deployment targets US and German neurocritical care units, constrained by superconducting wire supply concentration in Japanese industrial clusters.
- Cardiology:Myocardial perfusion and structural assessment for ischemic and valvular disease.
- Orthopedics:Musculoskeletal trauma and degenerative joint disease evaluation.
Oncology applications anchor premium system deployment. Neurology is climbing the fastest as aging demographics expand cerebrovascular disease burden across developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German hospital networks absorb premium MRI pricing with minimal volume sensitivity, while Indian outpatient operators negotiate aggressively on portable ultrasound procurement. Japanese academic centers pursue cutting-edge photon-counting CT regardless of cost, whereas Brazilian clinic chains prioritize rapid payback periods on capital equipment.
United States
Massachusetts and Texas academic medical centers drive photon-counting CT pilot programs, with spectral imaging protocols reducing radiation exposure in oncology workflows. FDA's software pre-certification pilot permits continuous AI algorithm updates without redundant 510(k) submissions. The Greater Boston cluster anchors neurology-focused high-field MRI deployment, constrained by superconducting wire supply concentration risks.
Germany
University hospitals in Bavaria and Baden-Württemberg pursue advanced spectroscopy applications requiring homogeneous magnetic fields above 3 Tesla. EU MDR conformity documentation extends procurement cycles, yet streamlined CE marking pathways for Class IIa devices compress time-to-market for domestic manufacturers. The Erlangen industrial corridor concentrates superconducting magnet assembly and cryogenic engineering expertise.
Japan
Tokyo and Osaka specialty centers command priority allocation for photon-counting detector modules under PMDA fast-track designation pathways. METI industrial policy supports domestic superconductor foundry capacity expansion to reduce earthquake exposure in the niobium-titanium supply chain. The Kansai region maintains concentrated magnet manufacturing scale serving global OEM procurement contracts.
India
Maharashtra and Karnataka clinic chains expand portable ultrasound fleets across ambulatory surgical centers, leveraging AI-assisted image interpretation to offset radiologist scarcity. CDSCO medical device registration requirements are harmonizing with EU MDR technical documentation standards. Mumbai-based distributors negotiate volume pricing for solar-powered, tablet-integrated units targeting rural health districts.
Brazil
São Paulo and Rio de Janeiro outpatient networks prioritize rapid-depreciation ultrasound systems with streamlined staff training protocols. ANVISA regulatory alignment with FDA 510(k) evidentiary standards is accelerating product standardization for US- and European-origin equipment. The Southeast region concentrates procurement decision-making for clinic chain expansion into secondary cities.
Non-Destructive Medical Technologies Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in non-destructive medical imaging. Siemens Healthineers and GE Healthcare anchor the upper tier through captive magnet manufacturing and global service networks, while mid-scale specialists concentrate on single-modality excellence or geographic niche penetration. Three archetypes dominate: diversified conglomerates with cross-modal portfolios, pure-play imaging OEMs with vertical component control, and point-of-care disruptors leveraging AI software differentiation. Competitive moves center on backward integration into cryogenic wire production and unbundling of after-sales service contracts from hardware financing bundles.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers exemplify integrated leaders with manufacturing scale across MRI, CT, and ultrasound platforms. Fujifilm Holdings Corporation occupies a specialist position, with its geographic origin and corporate structure signaling concentrated expertise in digital X-ray detector technology. These three entities represent distinct competitive vectors: conglomerate breadth, component verticalization, and retrofit market specialization respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Hitachi Medical Corporation |
| Medtronic |
| Carestream Health |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) premarket notification and EU MDR conformity assessment protocols gate both supplier qualification and price differentiation simultaneously, separating OEMs with validated clinical data packages from contract manufacturers locked into commodity detector panel production. Hospital procurement committees in Germany and the United States exploit this certification hierarchy to negotiate tiered service bundles, while outpatient operators in India and Brazil bypass premium tiers entirely through direct sourcing from unbranded ultrasound assemblers.
Pricing Analysis
After-sales service revenue from coldhead refurbishment and magnet maintenance contracts drives lifetime value across superconducting MRI installed bases. Three-tier pricing structure across premium, standard, and economy levels segments buyers by field strength requirements and AI software integration depth. Cost compression in portable ultrasound hardware is intensifying because Chinese contract manufacturers are scaling piezoelectric transducer output for Indian clinic chains. Outpatient operators in emerging markets exhibit highest price sensitivity, while German university hospitals absorb premium MRI pricing with minimal negotiation leverage.
Supply Chain Analysis
Niobium-titanium filament production concentration in a single Japanese industrial cluster exposes imaging OEMs to earthquake and trade disruption risks. Superconducting magnet assembly draws from German cryogenic engineering expertise and Japanese superconductor foundry capacity. Helium-3 recovery infrastructure and cadmium zinc telluride detector materials rest on volatile noble gas supply chains and specialized semiconductor foundry access. Tariff exposure runs through US-China medical device component trade flows. Distribution runs through hospital procurement consortia and independent service organizations competing for mid-life system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among US hospital purchasing committees and French procurement consortia is shifting bargaining power toward buyers, compressing OEM margin pools and forcing unbundling of hardware from service contracts.
For Market Incumbents: Compound captive magnet manufacturing scale with backward integration into cryogenic wire production to defend against niobium-titanium supply chokepoint vulnerability. Secure long-term helium-3 recycling partnerships to extend MRI operational lifespans and lock out independent service organizations from mid-life maintenance revenue. Prioritize EU MDR documentation investment to accelerate CE marking pathways ahead of specialized competitors. For New Entrants and Emerging Players: AI-assisted image interpretation software layers represent the most penetrable service gap where Siemens Healthineers and GE Healthcare under-serve price-sensitive outpatient operators. Target Nigerian and Kenyan rural health districts with solar-powered, tablet-integrated ultrasound units addressing radiologist scarcity. Pursue CDSCO harmonization with EU MDR standards to unlock Maharashtra clinic chain procurement at lower regulatory compliance cost than US-bound competitors. For Investors and Strategic Acquirers: FDA's software pre-certification pilot reshapes the acquisition landscape by permitting continuous algorithmic updates without redundant submissions, elevating AI diagnostic module developers above hardware-dependent OEMs. Five-to-ten-year viability favors point-of-care specialists with cloud-native PACS architectures over capital-intensive magnet manufacturers. Target acquisition archetype: photon-counting CT detector material science firms with Japan PMDA fast-track designation. Watch signal: helium-3 spot price volatility as indicator of MRI installed-base maintenance contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Wire Production | Reduces dependency on Japanese niobium-titanium filament concentration for superconducting MRI supply security. |
| CE Marking Pathway Acceleration | Compresses time-to-market for Class IIa ultrasound devices targeting German hospital network procurement cycles. |
| Hospital System Partnership | Locks in multi-year MRI service contracts with Massachusetts academic centers pursuing photon-counting CT pilots. |
| Software Companion Development | Enables FDA pre-certification pilot participation for mammography triage tools in Texas radiology groups. |
| Reimbursement Strategy | Aligns portable ultrasound deployment with Brazilian ANVISA standards to accelerate clinic chain expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hospital purchasing committees, biomedical engineers, GPO contracts managers, and independent service organization technicians. Secondary validation incorporated FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up installed-base modeling and top-down healthcare capital expenditure forecasts were triangulated to reconcile volume estimates.
Across the analysis window, projections integrated product type segmentation by imaging modality, technology differentiation by field strength and frequency range, end-user facility economics, and application-specific reimbursement intensity. CAGRs were derived from weighted average replacement cycle analysis and penetration rate modeling for AI-enabled image interpretation modules. Forecast inputs included helium-3 supply volatility indices and PMDA fast-track designation approval velocity.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and Japan PMDA regimes; material policy shifts would require re-modeling clearance timelines and evidentiary standards. Practitioners should keep alternative scenarios live as AI diagnostic software classification protocols and superconducting wire supply diversification efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Cyberknife Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Global Medical Sensor Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
North America Ablation Devices Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Global Kidney Stone Retrieval Devices Market