
 Fat Free Yogurt Market | 2026-2036
Fat Free Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Yogurt Market Analysis
A shortage of dairy technologists skilled in fat-replacement formulation is redrawing competitive boundaries in developed markets. Danone leverages its European R&D network to sustain clean-label innovation pipelines. Chobani anchors North American production with in-house fermentation expertise. General Mills competes through broad retail distribution control across conventional grocery channels.
Fat free yogurt is a fermented dairy product manufactured from skim or nonfat milk through bacterial culture fermentation at controlled temperatures, yielding a protein-dense, low-calorie food with live active cultures. Greek fat free yogurt dominates margin pools due to its strained manufacturing process and premium positioning, while organic variants capture the fastest-growing consumer segment as clean-label preferences intensify. Distribution through supermarkets still occupies the largest volume channel, though online retail is accelerating as subscription models penetrate urban households.
The FDA governs live and active culture claims in the United States, while EFSA evaluates health claim substantiation across European markets, and China's SAMR enforces GB standards for dairy product composition and labeling. These frameworks shape reformulation priorities, dictate permissible marketing language, and determine market access timelines for new entrants. Stakeholders must monitor evolving sugar-reduction mandates and probiotic strain approval pathways to anticipate compliance costs and product portfolio adjustments.
Market Dynamics
Fat-replacement formulation complexity is redrawing competitive boundaries as manufacturers race to satisfy clean-label demands without sacrificing texture. The FDA's added-sugar labeling mandates and EFSA's health-claim substantiation requirements are forcing simultaneous reformulation across multiple regulatory jurisdictions.
Growth Catalysts
- Probiotic strain innovation:New bacterial cultures with enhanced stability profiles are extending shelf life without synthetic preservatives, unlocking clean-label positioning in premium segments.
- Urban subscription penetration:Direct-to-consumer delivery models are capturing household purchasing decisions in dense metropolitan zones, bypassing traditional retail gatekeepers.
- EFSA health claim pathways:Approved substantiation for digestive wellness claims is enabling functional positioning that commands price premiums across German and French retail channels.
Market Restraints
- Skim milk powder volatility:Input cost swings in dairy commodities compress margin predictability for contract manufacturers dependent on spot market sourcing.
- Fermentation capacity concentration:Commercial-scale culture production clusters in Denmark and the Netherlands, creating single-source vulnerability for North American brands.
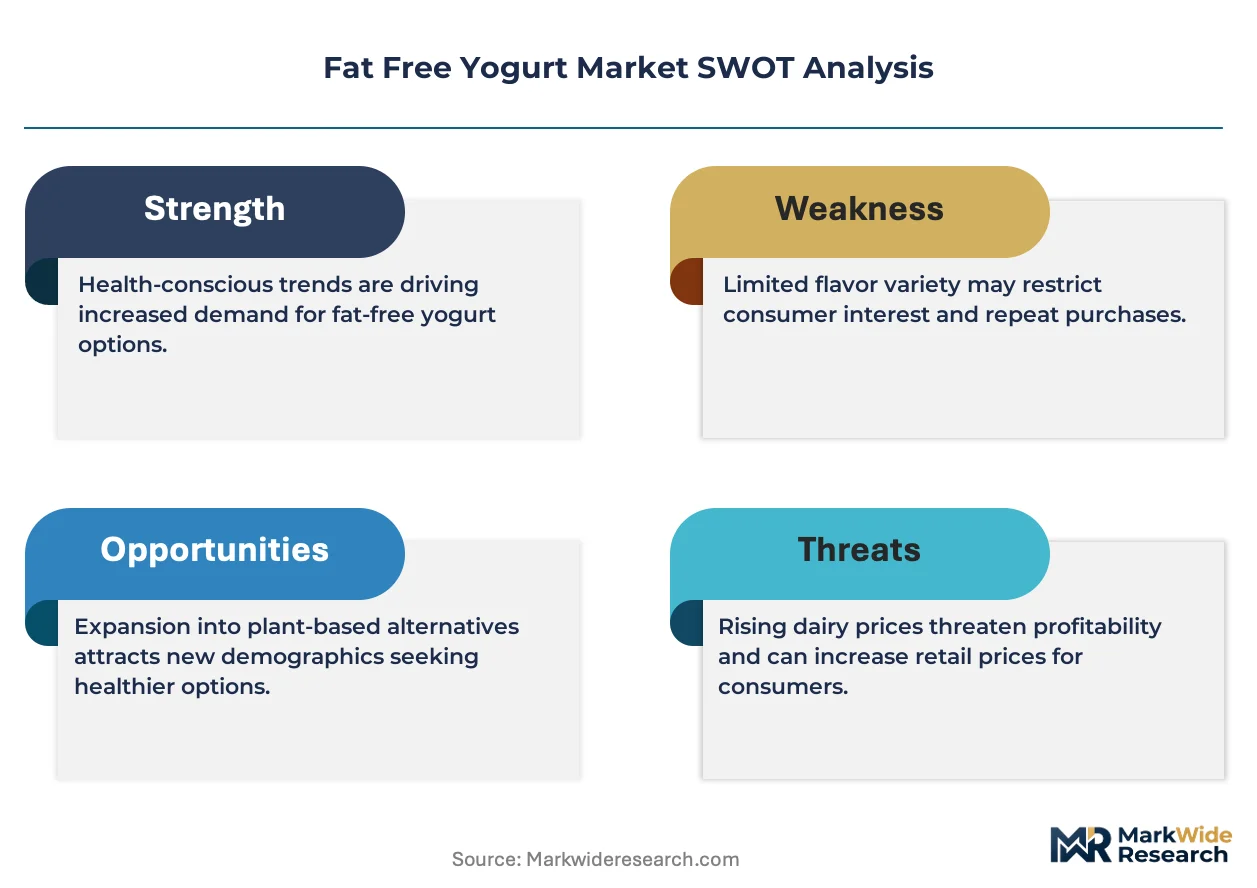
- Plant-based substitution acceleration:Oat and almond yogurt alternatives are capturing lactose-intolerant and flexitarian households previously loyal to dairy-based fat free options.
Strategic Opportunities
- SAMR pathway acceleration:China's streamlined dairy import registration for probiotic-containing products is opening access to tier-one urban markets in Shanghai and Beijing.
- Precision fermentation convergence:Integration of biomass fermentation with traditional dairy processing is enabling novel protein structures that replicate full-fat mouthfeel at zero fat content.
- Pharmaceutical channel expansion:Hospital and clinic nutrition programs are adopting medical-grade fat free yogurt for post-surgical and geriatric dietary protocols.
Industry Challenges
- Dairy technologist scarcity:Fat-replacement formulation expertise resides with a narrow cohort of European-trained specialists, constraining R&D velocity for new market entrants.
- Dual certification timelines:Simultaneous FDA and EFSA approval for novel probiotic strains stretches product development cycles and capital lock-up periods.
- Legacy ERP integration:Fermentation batch-tracking systems require costly middleware upgrades to comply with evolving traceability mandates across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Yogurt Market |
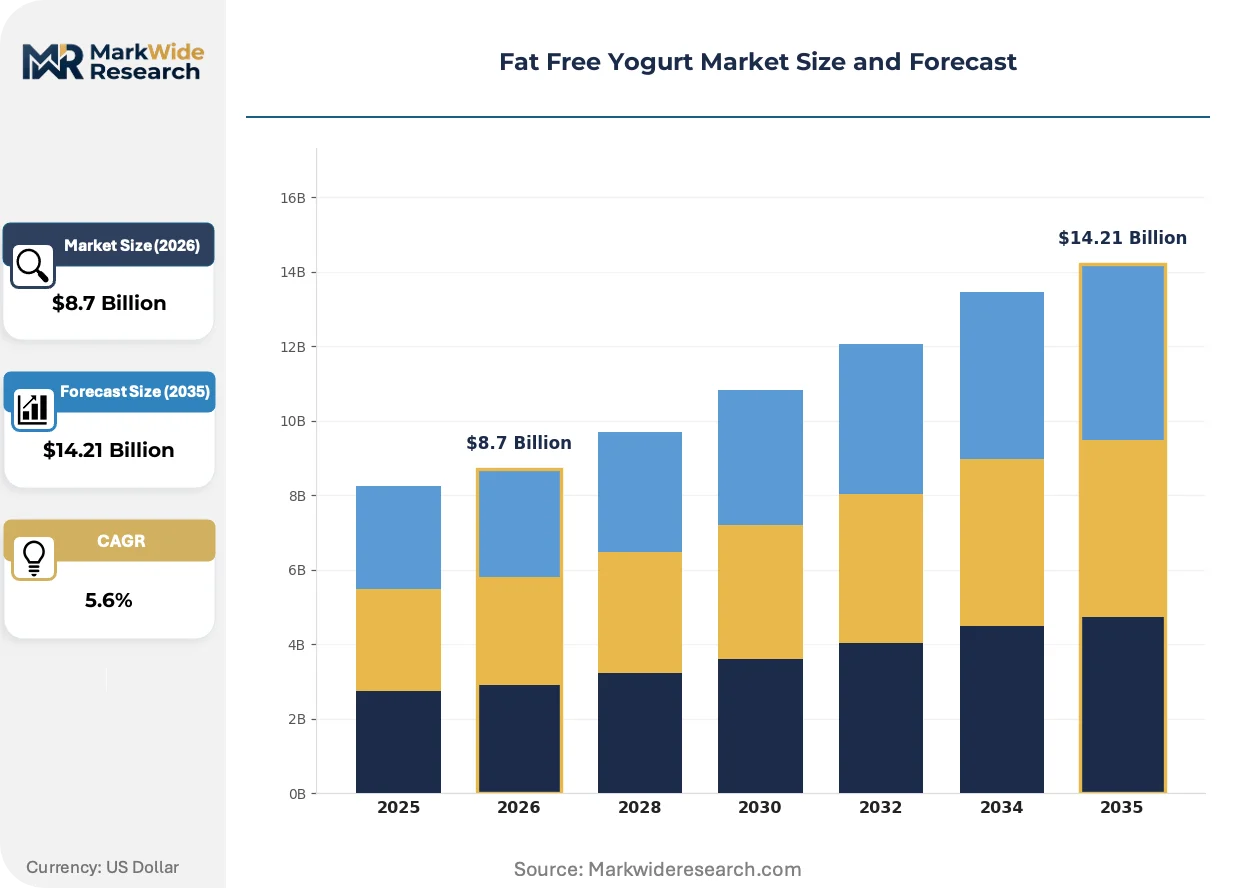
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek, Regular, Organic, Flavored Distribution Channel: Supermarkets, Health Stores, Online Retail, Convenience Stores End User: Fitness Enthusiasts, Health-Conscious Consumers, Families, Culinary Professionals Packaging Type: Cups, Bottles, Pouches, Bulk Bins |
| Companies Covered | Yili Group, Meiji Holdings, Danone, Fage International, Nestlé, Unternehmensgruppe Theo Müller, General Mills, Chobani, Mengniu Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Yogurt Market Emerging Trajectories
Clean-label fermentation science is supplanting conventional stabilizer systems as the primary axis of product differentiation. Texture replication without hydrocolloids has become the central technical battleground separating premium from commodity positioning.
Precision fermentation-derived whey proteins are supplanting traditional milk protein concentrates in fat free Greek yogurt manufacturing. European R&D facilities are scaling these biomass alternatives at commercial volume. The structural consequence is a compression of conventional dairy ingredient supplier margins as biotech-enabled inputs capture formulation decisions.
EFSA's updated guidance on gut microbiome health claims is tightening substantiation requirements for live culture marketing. Manufacturers must now demonstrate strain-specific efficacy through human intervention studies. German organic processors are responding by consolidating proprietary culture libraries and pursuing exclusivity agreements with research institutes.
Urban households are abandoning single-serve impulse purchases in favor of multi-unit subscription commitments through direct channels. This behavioral pivot is concentrating volume with platforms that control recurring revenue relationships. The shift is most visible in US coastal metropolitan markets where delivery density supports cold-chain economics.
Fat Free Yogurt Market Segmentation
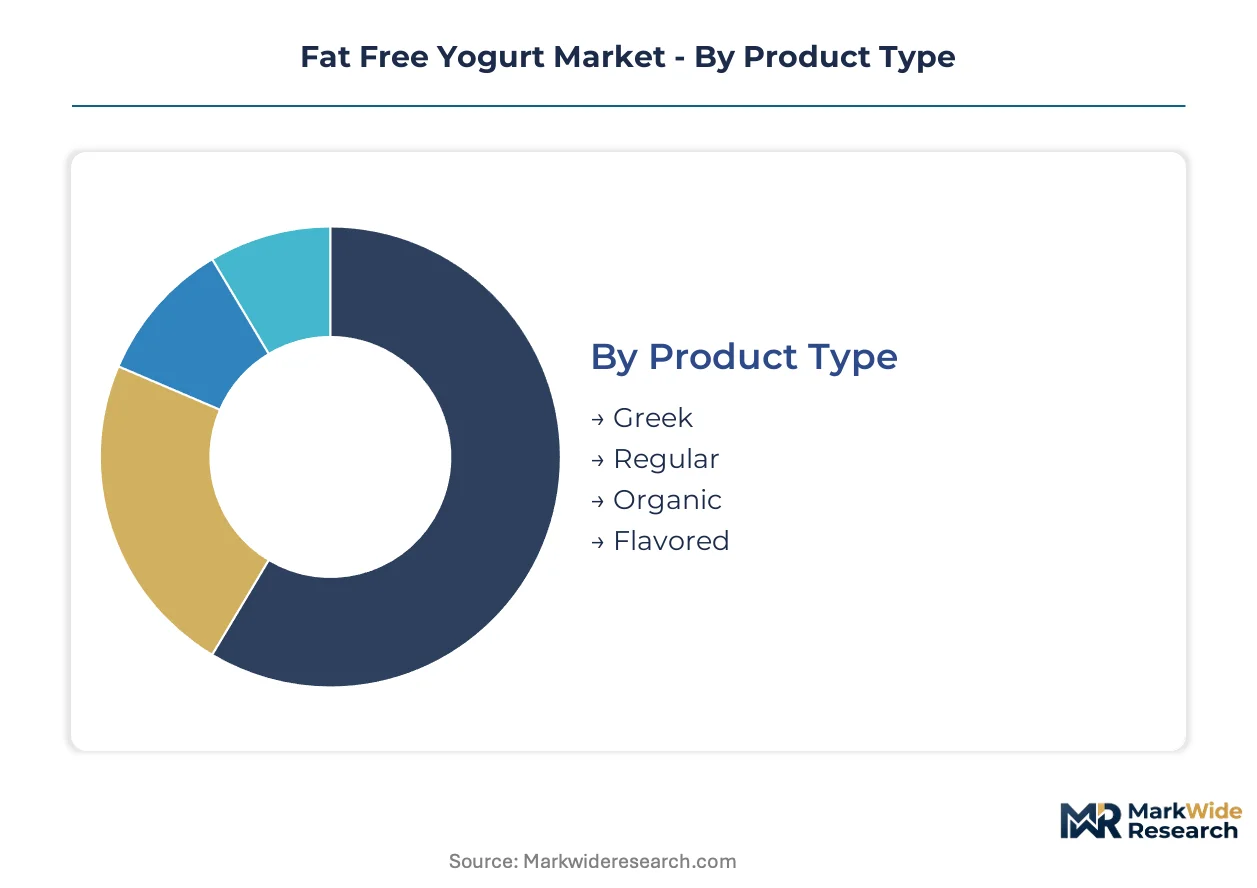
Fat free yogurt manufacturers deploy distinct formulation and positioning strategies across product architectures, channel structures, and user profiles. Segmentation discipline determines where R&D dollars flow and which distribution partnerships command premium terms.
Product Type:
Greek yogurt captures the deepest margin pools through its strained protein concentration and premium shelf positioning, while organic variants attract the steepest investment in fermentation science and clean-label certification.
- Greek:Manufactured through straining to remove whey and concentrate protein, delivering 15-20 grams protein per serving. Demand concentrates among US coastal metropolitan households seeking satiety management, with texture replication without fat driving formulation R&D spend.
- Organic:Sourced from certified organic milk with bacterial cultures meeting USDA organic standards, prohibiting synthetic additives. German and French retail channels show the tightest supply-demand imbalance as EFSA health claim substantiation requirements favor organic positioning for digestive wellness marketing.
- Regular:Standard stirred or set yogurt from skim milk without straining, occupying mid-tier price positioning across conventional grocery.
- Flavored:Incorporates fruit preparations, natural sweeteners, or vanilla extracts, facing reformulation pressure from FDA added-sugar labeling mandates.
Greek holds installed capacity. Organic is rotating up the share rankings.
Distribution Channel:
Channel selection dictates cold-chain investment intensity and margin structure, with direct-to-consumer platforms requiring fundamentally different logistics architecture than conventional retail.
- Supermarkets:Dominates volume throughput through refrigerated dairy case placement, with slotting fees and promotional calendars determining brand visibility. US conventional grocery chains anchor procurement scale.
- Online Retail:Subscription models penetrate dense urban zones, bypassing retail gatekeepers through recurring revenue relationships controlled by platform operators.
- Health Stores:Natural and specialty retailers command premium positioning for probiotic-forward and organic SKUs.
- Convenience Stores:Single-serve impulse formats target grab-and-go consumption occasions with limited cold-chain depth.
Supermarkets hold installed capacity. Online Retail is rotating up the share rankings.
End User:
User archetype determines protein concentration requirements, flavor complexity tolerance, and price elasticity, with fitness-oriented segments accepting the steepest premiums for functional positioning.
- Fitness Enthusiasts:Prioritizes protein density and macronutrient transparency, driving Greek yogurt adoption for post-workout recovery protocols.
- Health-Conscious Consumers:Evaluates live culture counts and clean-label credentials, concentrating demand in organic and probiotic-forward SKUs across German and French markets.
- Families:Multi-unit purchasers sensitive to per-ounce pricing, favoring larger format containers and kid-friendly flavor profiles.
- Culinary Professionals:Sources bulk formats for recipe applications requiring tang and texture without fat content.
Fitness Enthusiasts hold installed capacity. Health-Conscious Consumers is rotating up the share rankings.
Packaging Type:
Format selection shapes shelf life extension, portion control economics, and sustainability positioning, with single-serve formats commanding per-ounce premiums against bulk alternatives.
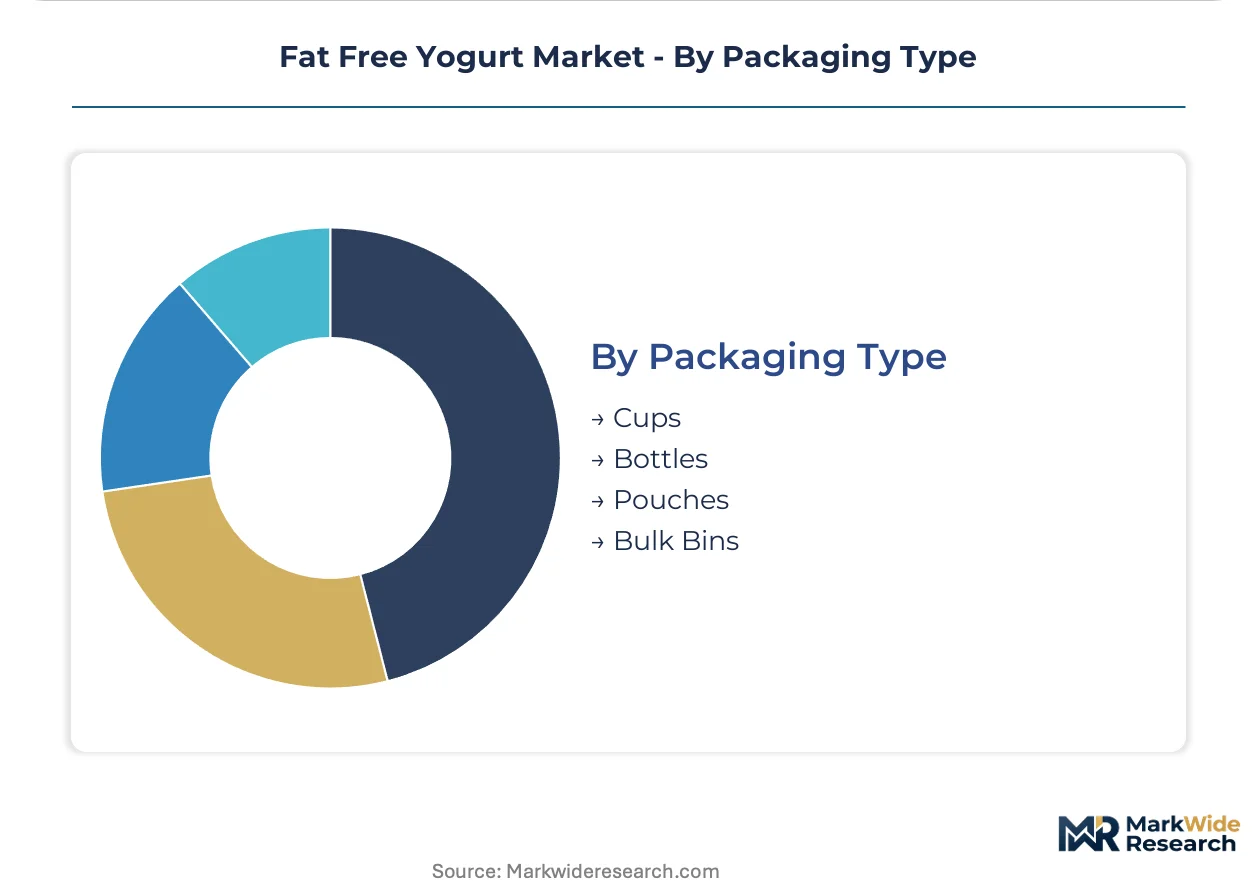
- Cups:Dominates single-serve consumption with portion-controlled 5.3-6 ounce formats, standard across US retail dairy cases.
- Bottles:Enables drinkable yogurt positioning for on-the-go occasions, requiring distinct viscosity formulation.
- Pouches:Targets children's lunchbox occasions with resealable convenience and reduced shipping weight.
- Bulk Bins:Foodservice and institutional formats minimizing per-serving packaging cost for culinary and healthcare applications.
Cups hold installed capacity. Bottles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: US households prioritize high-protein Greek formats for fitness routines, while German and French buyers gravitate toward organic certified products with EFSA-substantiated digestive claims. Asian markets emphasize drinkable and convenience formats for on-the-go urban consumption.
United States
Fitness-oriented consumers drive Greek yogurt adoption for post-workout protein delivery, with coastal metropolitan households commanding premium positioning. The FDA's updated nutrition labeling requirements for added sugars force reformulation across flavored SKUs. Cold-chain infrastructure concentrates in the Northeast corridor, where subscription delivery platforms bypass traditional retail gatekeepers.
Germany
Organic certification and EFSA-approved digestive wellness claims concentrate demand among health-conscious households in Bavaria and North Rhine-Westphalia. The country's national dairy regulator enforces strict live culture count verification for probiotic marketing. Berlin-Brandenburg anchors fermentation R&D clusters where precision fermentation startups partner with established dairy processors.
France
Traditional yogurt consumption habits persist alongside accelerating demand for fat-free organic variants in Île-de-France and Auvergne-Rhône-Alpes. EFSA health claim substantiation requirements favor strain-specific efficacy demonstrations for premium positioning. The Rhône-Alpes dairy basin hosts specialized culture production facilities serving organic processors across Western Europe.
China
Urban middle-class households in Shanghai and Beijing adopt drinkable yogurt formats through e-commerce subscription channels. SAMR's streamlined dairy import registration for probiotic-containing products accelerates market access timelines. The Yangtze River Delta concentrates domestic manufacturing capacity where local players compete with imported premium brands.
Japan
Functional food positioning dominates as consumers prioritize specific health outcomes from live culture consumption. The country's national pharmaceutical regulator evaluates probiotic strain efficacy claims under Foods with Function Claims frameworks. Tokyo-Osaka corridor retail channels feature dedicated fermented dairy sections with strain-specific labeling.
Fat Free Yogurt Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational dairy conglomerates controlling formulation IP and distribution infrastructure while regional challengers capture niche organic and functional segments. Two strategic archetypes dominate: scale-driven players leveraging global R&D networks for clean-label innovation, and heritage-rooted specialists commanding premium positioning through proprietary culture libraries. Competitive moves center on precision fermentation partnerships and direct-to-consumer platform acquisitions.
Among European-based multinationals, Danone and Nestlé occupy positions spanning conventional and organic segments across multiple regulatory jurisdictions. Greek heritage specialist Fage International exemplifies the premium-tier archetype through strained protein concentration expertise. Chinese scale players Yili Group and Mengniu Dairy represent the domestic market consolidation vector, leveraging distribution depth across tier-one urban centers.
| Leading Market Players |
|---|
| Yili Group |
| Meiji Holdings |
| Danone |
| Fage International |
| Nestlé |
| Unternehmensgruppe Theo Müller |
| General Mills |
| Chobani |
| Mengniu Dairy |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between North American yogurt brands and Danish culture suppliers lock in fermentation capacity access while insulating against spot-market skim milk powder volatility that otherwise erodes margin predictability for contract manufacturers.
Pricing Analysis
Subscription-based pricing models dominate direct-to-consumer channels, while conventional retail operates on promotional calendar cycles with slotting fee structures. Price differentiation rests on organic certification grade and Greek straining intensity, with EFSA-substantiated probiotic claims commanding premiums. Cost compression in flavored SKUs intensifies as FDA added-sugar labeling mandates force reformulation. Families purchasing multi-unit formats exhibit highest price sensitivity; fitness enthusiasts accepting steepest premiums for protein density transparency.
Supply Chain Analysis
Just-in-time cold-chain logistics dominate urban subscription fulfillment, while strategic stockpiling of freeze-dried cultures buffers against fermentation capacity concentration in Denmark and the Netherlands. Raw material flows draw from New Zealand skim milk powder, European bacterial culture libraries, and domestic US dairy processing. Single-source vulnerability in commercial-scale culture production creates supply risk. Distribution runs through supermarket refrigerated dairy cases anchoring volume, with direct-to-consumer platforms capturing recurring revenue relationships in dense metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate accelerating plant-based substitution as oat and almond yogurt alternatives capture lactose-intolerant and flexitarian households previously loyal to dairy-based fat free options.
For Market Incumbents: Fortify proprietary culture libraries through exclusivity agreements with European research institutes, securing strain-specific efficacy data for EFSA health claim substantiation. Deepen backward integration into precision fermentation-derived whey proteins to replicate full-fat mouthfeel without hydrocolloid stabilizers. Plant-based substitution acceleration demands rapid clean-label innovation pipelines. For New Entrants and Emerging Players: Lead with medical-grade fat free yogurt positioning for hospital and clinic nutrition programs, where post-surgical and geriatric dietary protocols create procurement entry points. White-space concentrates in pharmaceutical channel expansion and SAMR pathway acceleration for tier-one Chinese urban markets. Direct-to-consumer subscription platforms offer lowest retail gatekeeper friction. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation startups with commercial-scale biomass alternatives capability, as biotech-enabled inputs capture formulation decisions from conventional dairy ingredient suppliers. Long-term viability hinges on clean-label texture replication expertise. Watch for FDA novel probiotic strain approval timelines as inflection indicator for portfolio R&D velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biomass-derived proteins enable zero-fat mouthfeel replication without synthetic stabilizers. |
| Direct-to-Consumer Platform Acquisition | Recurring revenue relationships bypass supermarket slotting fee structures in dense urban zones. |
| EFSA Health Claim Substantiation Investment | Strain-specific efficacy demonstrations unlock premium pricing in German and French retail channels. |
| Proprietary Culture Library Consolidation | Exclusive research institute agreements secure competitive moats for digestive wellness marketing. |
| Medical-Grade Product Line Extension | Hospital nutrition program adoption opens institutional procurement pathways beyond retail. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA health claim submissions, and Nielsen retail audit data. Interviews with dairy processing executives, fermentation R&D directors, supermarket category buyers, and cold-chain logistics operators inform demand-side validation. SEC filings from publicly traded dairy conglomerates and customs records for skim milk powder trade flows provide supply-side triangulation. Bottom-up volume modeling and top-down value reconciliation ensure cross-verification.
Segmentation dimensions modeled span product architecture (Greek, organic, regular, flavored), distribution channel structure (supermarket, online retail, health stores, convenience), and end-user archetype (fitness enthusiasts, health-conscious consumers, families, culinary professionals). CAGR derivation integrates historical volume trajectories with regulatory mandate timelines and probiotic strain approval pathways. Precision fermentation capacity buildouts and SAMR dairy import registration velocity serve as industry-specific forecast inputs across the projection horizon.
Forecasts assume regulatory continuity in FDA live culture claim enforcement and EFSA health claim substantiation requirements; material policy shifts would require re-modeling. Skim milk powder commodity volatility and plant-based substitution acceleration represent primary revision triggers. Revision becomes warranted when precision fermentation-derived protein cost parity thresholds cross conventional dairy concentrate pricing bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
North America Non-Dairy Yogurt Market