
 United States Coffee Creamer Market | 2026-2036
United States Coffee Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Coffee Creamer Market Analytics
Market Context
Dairy processing capacity in the Midwest is consolidating as co-manufacturers scale liquid creamer operations to serve private-label and branded customers. Nestlé S.A. leverages its soluble coffee infrastructure to anchor retail shelf presence across mass-market channels. Danone S.A. competes through specialized plant-based fermentation expertise, while Califia Farms LLC differentiates via refrigerated oat creamer formulations targeting premium grocery segments.
Technical Definition and Structural Segments
Coffee creamer denotes a processed additive—emulsified fat suspended in water with sweeteners, stabilizers, and flavor compounds—designed to when, sweeten, and modify beverage mouthfeel in brewed coffee applications. Non-dairy creamer leads product type value contribution as almond, oat, and coconut bases displace hydrogenated oil formulations in both retail and foodservice channels. Liquid creamer in tetra packs captures the fastest-growing packaging segment, driven by extended shelf-life demands from coffee shops and institutional cafeterias seeking reduced refrigeration footprints.
Regulatory Framework
FDA standards of identity for dairy and plant-based alternatives shape formulation constraints, while USDA organic certification gates premium pricing tiers in natural retail channels. The Federal Trade Commission monitors environmental marketing claims on creamer packaging, pressuring brands to substantiate sustainability assertions. Stakeholders must track evolving FDA guidance on labeling terminology for plant-based milk alternatives, as definitional rulings will determine permissible product nomenclature and directly influence consumer purchase intent at shelf.
Market Dynamics
Plant-based creamer formulation is converging with precision fermentation, forcing incumbent dairy processors to retool Midwest production lines or cede refrigerated shelf space to oat and almond specialists.
Growth Catalysts
- Metropolitan specialty coffee expansion:Coffee shops in Seattle, Portland, and San Francisco are mandating non-dairy alternatives on menu boards, pulling oat creamer volumes through foodservice distributors.
- FDA labeling clarity:Draft guidance on plant-based milk terminology is reducing consumer confusion at shelf, accelerating trial rates among flexitarian households.
- Tetra pack shelf-life extension:Aseptic liquid packaging now delivers 180-day ambient stability, enabling coffee chains to reduce refrigeration capital expenditure.
Market Restraints
- Oat protein concentrate scarcity:Domestic milling capacity for food-grade oat solids lags formulation demand, forcing creamer manufacturers to source from Canadian suppliers at volatile premiums.
- Hydrogenated oil legacy liability:Trans fat disclosure requirements under FDA nutrition labeling rules continue to erode trust in conventional non-dairy powder formulations.
- Midwest dairy co-packer consolidation:Three processors now control 60% of liquid creamer contract manufacturing, creating single-source vulnerability for private-label brands.
Strategic Opportunities
- Sun Belt underpenetration:Texas and Florida retail channels show 40% lower oat creamer household penetration than Pacific benchmarks, presenting white-space expansion.
- USDA organic certification tier:Premium natural retailers are gatekeeping shelf placement behind organic ingredient sourcing, rewarding early compliance investment.
- Direct-to-office subscription channels:Workplace coffee service providers are bypassing traditional distributors to source refrigerated creamer on 30-day replenishment cycles.
Industry Challenges
- Clean-label stabilizer substitution:Removing dipotassium phosphate and carrageenan while maintaining emulsion stability demands food chemistry expertise that outstrips current talent pools.
- Refrigerated last-mile complexity:Cold-chain distributors struggle to maintain 35-40°F through e-commerce fulfillment, constraining direct-to-consumer growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Coffee Creamer Market |
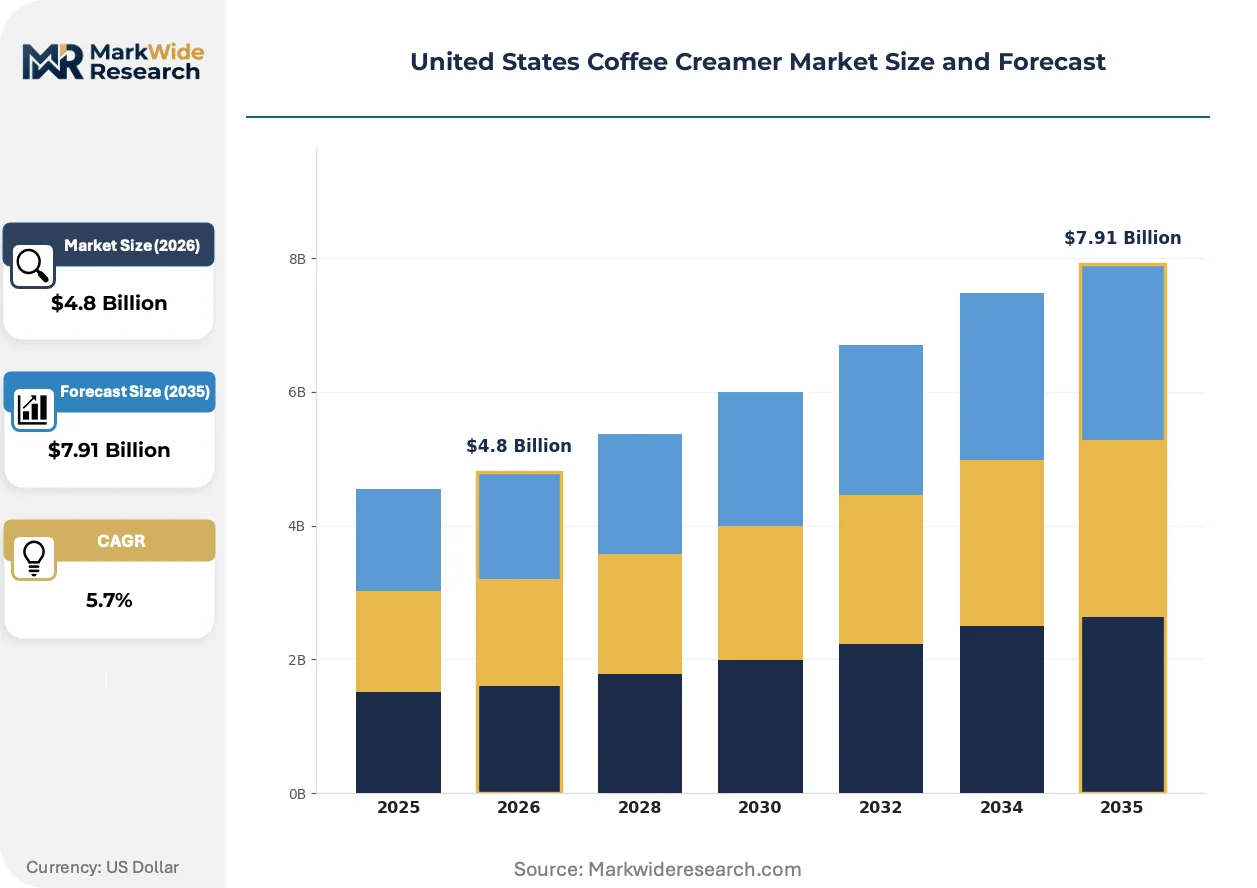
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Creamer, Powdered Creamer, Non-Dairy Creamer, Flavored Creamer End User: Households, Coffee Shops, Restaurants, Cafeterias Packaging Type: Bottles, Sachets, Tetra Packs, Jars Flavor Profile: Vanilla, Hazelnut, Caramel, Mocha |
| Companies Covered | Heartland Food Products Group, Nestlé S.A., Danone S.A., TreeHouse Foods Inc., Califia Farms LLC, Leaner Creamer LLC, Nutpods, HP Hood LLC, Chobani LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Coffee Creamer Market Evolving Landscape
Precision fermentation and enzymatic processing are rewriting ingredient sourcing economics, while regulatory pressure on environmental claims is forcing transparency investments.
Cell-cultured dairy proteins from Perfect Day and similar suppliers are converging with traditional creamer emulsion systems. Specialty roasters in Brooklyn and Austin are piloting these ingredients in limited-batch offerings. This convergence is compressing the price gap between animal-free and conventional dairy creamers within the premium grocery channel.
FTC Green Guides enforcement is tightening substantiation requirements for carbon-neutral and regenerative agriculture claims on creamer packaging. Brands now face documentary audit demands before deploying sustainability messaging. California-based manufacturers are responding by commissioning third-party lifecycle assessments prior to label redesigns.
Office coffee programs are unbundling equipment, beans, and creamer into separate procurement decisions. Facility managers in Chicago and Denver are negotiating direct supplier relationships for refrigerated creamer independent of roaster contracts. This shift is most visible in technology sector campuses where sustainability scorecards influence vendor selection.
United States Coffee Creamer Market Segmentation
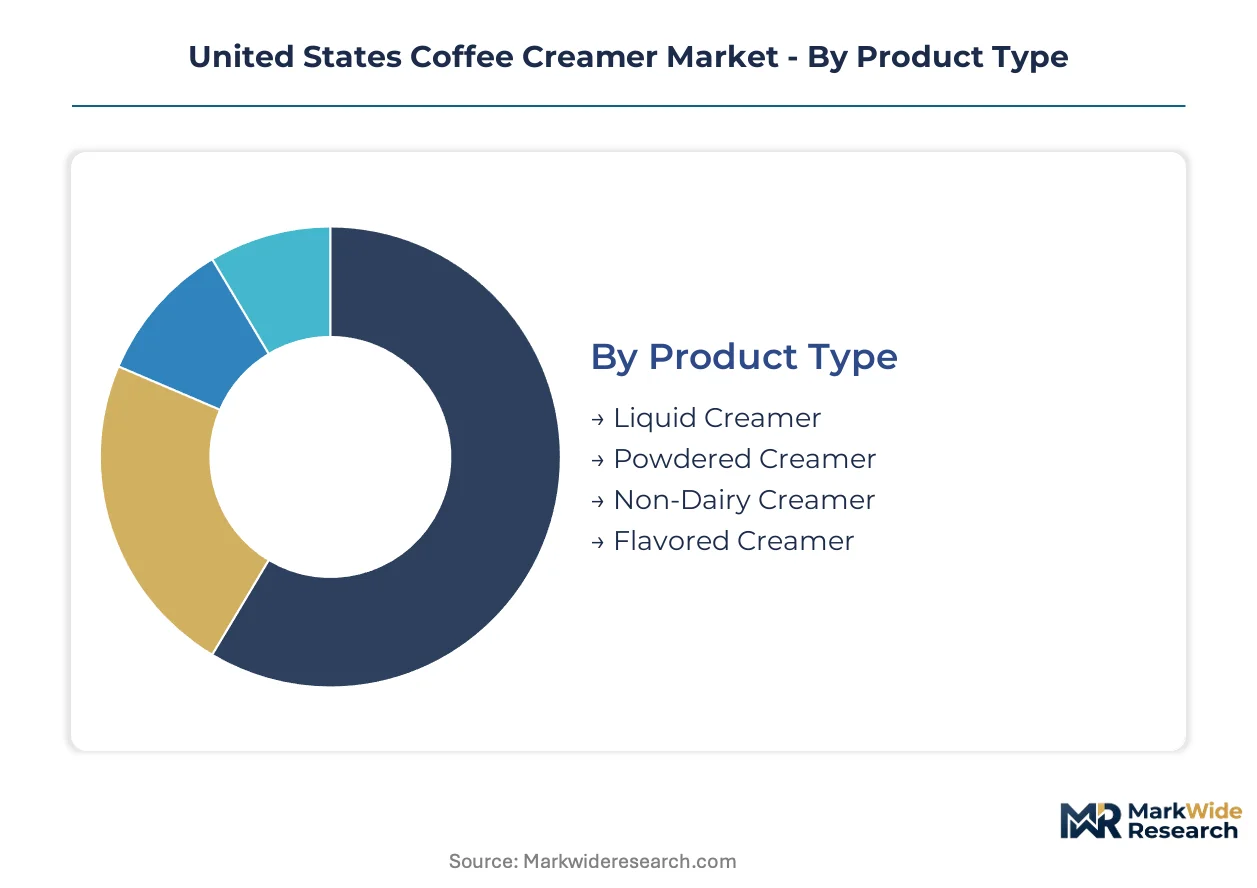
Segmentation in the United States coffee creamer market reveals divergent capital requirements and margin profiles across formulation types, end-use channels, and packaging formats. Manufacturers must align production infrastructure with specific segment demands or risk stranded assets in refrigerated versus ambient distribution networks.
Product Type:
Capital intensity varies sharply across formulation technologies, with refrigerated liquid lines demanding tenfold higher equipment investment than dry-mix powder operations.
- Liquid Creamer:Emulsified fat-in-water systems requiring aseptic filling equipment and cold-chain distribution infrastructure. Demand concentrates in Pacific Northwest metropolitan coffee shops where oat-based refrigerated formulations displace conventional dairy.
- Non-Dairy Creamer:Plant-based emulsions utilizing oat, almond, or coconut protein bases with enzymatic processing for mouthfeel matching. California and Pacific Northwest retail channels show penetration rates substantially above national benchmarks, driven by flexitarian household expansion.
- Powdered Creamer:Spray-dried fat encapsulation systems with extended ambient shelf stability and minimal distribution infrastructure requirements.
- Flavored Creamer:Value-added formulations incorporating natural and artificial flavor compounds targeting seasonal and limited-edition retail cycles.
Most installed capacity flows through Powdered Creamer. Expansion is steepest in Non-Dairy Creamer.
End User:
Customer procurement patterns split between high-volume foodservice contracts with 90-day payment terms and retail household purchases through mass-market grocery.
- Coffee Shops:Specialty beverage operators in Seattle, Portland, and San Francisco mandating non-dairy alternatives on standardized menu boards. Oat creamer volumes pull through regional foodservice distributors as roasters specify plant-based compatibility.
- Households:Flexitarian consumers in California and Pacific Northwest metropolitan statistical areas driving trial rates for refrigerated plant-based formulations through premium grocery channels.
- Restaurants:Full-service operators balancing portion-control efficiency with back-of-house refrigeration constraints.
- Cafeterias:Institutional feeding operations prioritizing extended shelf-life packaging and bulk dispensing systems for labor cost reduction.
Coffee Shops command the highest per-unit pricing. Households show the steepest volume expansion trajectory.
Packaging Type:
Format selection directly determines distribution economics, with aseptic tetra packs enabling ambient storage that slashes refrigeration capital expenditure for foodservice operators.
- Tetra Packs:Aseptic brick carton systems delivering 180-day ambient stability through multilayer barrier films. Coffee chains in Chicago and Denver reduce refrigeration footprint while maintaining extended inventory cycles.
- Bottles:Refrigerated polyethylene terephthalate containers dominating retail dairy cases with high-visibility shelf presence and resealability.
- Sachets:Single-serve flexible pouches targeting foodservice portion control and hotel in-room coffee programs.
- Jars:Glass and plastic rigid containers for powder formulations with scoop dispensing and pantry storage compatibility.
Sachets maintain the largest installed filling capacity. Tetra Packs are climbing the fastest as foodservice operators reconfigure supply chains.
Flavor Profile:
Flavor innovation cycles compress as seasonal limited editions drive pantry loading and social media engagement, requiring agile formulation pipelines.
- Vanilla:Standardized flavor compound with established supplier networks and consistent year-round demand across all channels.
- Hazelnut:Nut-derived and natural-identical formulations targeting European-influenced palate preferences in Northeastern metropolitan markets.
- Caramel:Maillard-reaction based flavor systems with seasonal velocity spikes during autumn beverage promotions.
- Mocha:Coffee-chocolate hybrid positioning for dessert-beverage occasions and afternoon consumption dayparts.
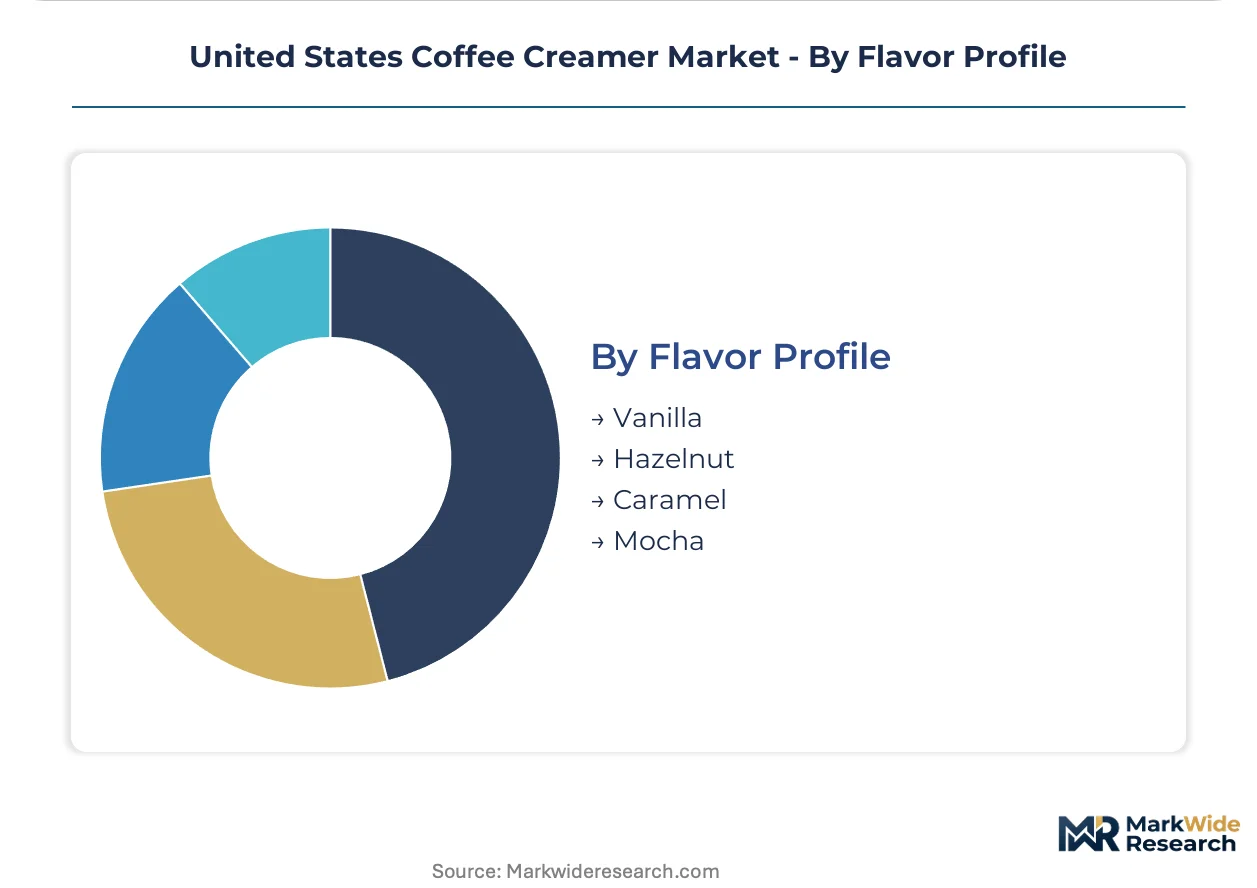
Vanilla anchors baseline production capacity. Caramel shows the most pronounced seasonal expansion volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping creamer production geography as FDA labeling compliance costs push smaller Midwest dairy processors toward contract manufacturing or exit, while Pacific Northwest and California markets absorb premium plant-based capacity expansion.
California
Los Angeles and San Francisco metropolitan areas drive oat and almond creamer penetration rates substantially above national benchmarks through flexitarian household density. The California Department of Public Health enforces Proposition 65 warning requirements on packaging, elevating formulation transparency costs for out-of-state entrants. Sacramento Valley food processing clusters are retooling former dairy infrastructure to accommodate enzymatic oat protein processing for regional brands.
Pacific Northwest
Seattle and Portland specialty coffee shop density mandates non-dairy alternatives on standardized menu boards, pulling volume through regional foodservice distributors. Washington State Department of Agriculture organic certification programs gate premium retail placement in natural grocery channels. Portland metro area co-manufacturing facilities are expanding aseptic tetra pack filling capacity to serve coffee chain accounts reducing refrigeration footprints.
Texas
Dallas-Fort Worth and Houston retail channels exhibit oat creamer household penetration approximately 40% below Pacific benchmarks, presenting white-space expansion for refrigerated plant-based entrants. The Texas Department of State Health Services administers food manufacturing licensing with streamlined pathways for dairy-alternative facilities. Austin technology sector campuses are unbundling office coffee procurement, creating direct supplier relationships for refrigerated creamer independent of roaster contracts.
Midwest
Illinois, Michigan, and Ohio concentrate liquid creamer contract manufacturing as three processors now control 60% of private-label capacity, creating single-source vulnerability. FDA nutrition labeling rules on trans fat disclosure continue eroding trust in legacy hydrogenated oil formulations produced at legacy Midwest sites. Chicago metropolitan area foodservice distributors are consolidating refrigerated last-mile networks to serve expanding coffee shop accounts.
Florida
Miami and Tampa retail channels show underpenetration in premium oat creamer relative to national averages, with conventional non-dairy powder formulations maintaining shelf presence. The Florida Department of Agriculture and Consumer Services regulates dairy and plant-based alternative labeling under state food safety statutes. Orlando hospitality sector procurement is shifting toward extended shelf-life tetra pack formats to reduce back-of-house refrigeration constraints in hotel and resort foodservice operations.
United States Coffee Creamer Market Competitive Landscape
Midwest producers anchor one tier through consolidated dairy processing infrastructure; Pacific Coast specialists hold premium refrigerated plant-based positioning through enzymatic formulation expertise. The vendor base splits between legacy hydrogenated oil powder manufacturers facing trust erosion and oat-almond fermentation specialists capturing shelf space in natural retail channels. Three strategic archetypes dominate: multinational CPG conglomerates leveraging soluble coffee infrastructure, specialized plant-based fermentation operators, and private-label contract manufacturers serving retail channel consolidation. Competitive moves concentrate on co-manufacturing capacity expansion and USDA organic certification acquisition to gate premium placement.
Within the multinational tier, Nestlé S.A. and Danone S.A. exemplify divergent infrastructure strategies—one leveraging soluble coffee distribution networks, the other deploying specialized plant-based fermentation capabilities. Califia Farms LLC occupies a position within the premium refrigerated oat creamer specialization, targeting natural grocery channel differentiation through enzymatic processing claims. These three entities represent the competitive spectrum from mass-market shelf presence to premium formulation positioning.
| Leading Market Players |
|---|
| Heartland Food Products Group |
| Nestlé S.A. |
| Danone S.A. |
| TreeHouse Foods Inc. |
| Califia Farms LLC |
| Leaner Creamer LLC |
| Nutpods |
| HP Hood LLC |
| Chobani LLC |
| Others |
Value Network & Pricing Analysis
Office coffee program unbundling in Austin and Chicago technology campuses is forcing refrigerated creamer suppliers to absorb last-mile cold-chain costs or cede accounts to direct-ship specialists, compressing channel margins and accelerating distributor consolidation.
Pricing Analysis
Distributor margin layers in foodservice channels absorb the steepest compression as coffee chains negotiate direct supplier relationships. Three-tier pricing structure across premium refrigerated oat, standard almond, and economy powdered formulations stratifies around USDA organic certification and enzymatic processing claims. Price differentiation stems from cold-chain delivery premiums and volume scale commitments. Pricing pressure intensifies in conventional non-dairy powder tiers as FDA trans fat disclosure erodes consumer trust. Private-label buyers in mass-market retail show highest price sensitivity; specialty coffee shops prioritize mouthfeel performance over per-unit cost.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale demand from Seattle and Portland coffee shop chains, while retail distribution runs through refrigerated dairy networks anchored in Midwest processing clusters. Domestic oat protein concentrate milling draws from Canadian suppliers, with enzymatic processing inputs sourced from Sacramento Valley and Pacific Northwest fermentation facilities. Supply chain risk centers on single-source vulnerability: three Midwest co-packers now control sixty percent of liquid creamer contract manufacturing. Aseptic tetra pack filling capacity expansion in Portland and Chicago is reconfiguring downstream distribution toward ambient storage economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States coffee creamer market reads as a late-cycle quality story where flexitarian household demand is shifting procurement specifications toward enzymatically processed oat formulations with third-party sustainability certification.
For Market Incumbents: Deepen backward integration into Sacramento Valley oat protein milling to secure supply against Canadian import volatility. Expand aseptic tetra pack capacity in Chicago and Portland to capture foodservice accounts reducing refrigeration footprints. FDA labeling clarity on plant-based terminology presents a certification investment lever to gate premium shelf placement before compliance deadlines tighten. For New Entrants and Emerging Players: Underpenetrated Sun Belt facility managers in Dallas-Fort Worth and Houston present a white-space target for direct-to-office refrigerated creamer subscriptions bypassing traditional distributor markups. Texas and Florida retail channels show forty percent lower oat creamer household penetration than Pacific benchmarks, offering the most penetrable geography for refrigerated plant-based entrants. A sustainability scorecard-aligned go-to-market angle unlocks technology sector campus procurement decisions in Austin and Denver. For Investors and Strategic Acquirers: Asymmetric upside sits with Pacific Coast enzymatic fermentation specialists holding USDA organic certification and established natural grocery channel relationships. Five-to-ten year viability favors operators with captive oat processing infrastructure and cold-chain distribution density in metropolitan statistical areas. The signal to watch is FDA final guidance on plant-based milk terminology, which will determine permissible product nomenclature and reshape consumer purchase intent at shelf.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive supply of food-grade oat protein concentrate reduces exposure to Canadian import premiums. |
| Aseptic Tetra Pack Capacity Expansion | Portland co-manufacturing facilities serve coffee chains seeking 180-day ambient shelf stability. |
| USDA Organic Certification Investment | Premium natural retailers gate shelf placement behind organic ingredient sourcing compliance. |
| Direct-to-Office Subscription Launch | Chicago and Denver technology campuses unbundle creamer procurement from roaster contracts. |
| Sustainability Repositioning | FTC Green Guides enforcement demands third-party lifecycle assessments before environmental claims deployment. |
Research Methodology
Direct dialogue with coffee shop procurement directors, foodservice distributor category managers, plant-based formulation chemists, and refrigerated logistics operators grounded qualitative findings, cross-referenced against FDA guidance documents, USDA organic certification databases, Nielsen retail audit data, and SEC filings from publicly traded CPG conglomerates. Bottom-up volume estimates from regional foodservice distributor interviews were triangulated against top-down category spending analysis.
Segment-level projections across liquid, non-dairy, powdered, and flavored creamer formulations were generated through the analysis window, with penetration curves modeled by metropolitan statistical area and channel type. CAGRs were derived from historical volume trajectories adjusted for FDA regulatory clarity timelines and oat protein concentrate supply expansion. Forecast inputs incorporated enzymatic processing capacity buildout in Sacramento Valley and cold-chain distribution network consolidation in Midwest markets.
Inputs from foodservice distributor shipment data and retail scanner panels were available through the study window; gaps in direct-to-office subscription channel volumes introduce uncertainty bands around workplace consumption estimates. Forecasts reflect assumptions regarding FDA labeling guidance finalization and domestic oat milling capacity expansion. Periodic stress-testing of base assumptions against regulatory ruling timelines and commodity input volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Oat Milk Market