
 PE Jumbo Bags Market | 2026-2036
PE Jumbo Bags Market Size, Share, and Industry Trends Forecast 2026-2036
PE Jumbo Bags Market Analytics
The capital-intensity divergence between integrated resin producers and regional converters is bifurcating competitive returns in PE jumbo bags. Berry Global Group leverages captive polyethylene supply chains to sustain margin compression in standard FIBC grades. Emmbi Industries anchors its position through dedicated woven-fabric manufacturing plants serving Indian agricultural exporters. Greif competes via its global industrial packaging footprint, extending reuse and recycling services alongside virgin bag sales.
PE jumbo bags are woven polypropylene or polyethylene flexible intermediate bulk containers, typically constructed from coated or uncoated tubular fabric with lifting loops rated for one-ton to two-ton payloads, designed for mechanized handling of free-flowing solids. FIBC variants dominate volume throughput in chemicals and construction end uses where UN-certified hazardous material containment governs procurement specifications. Baffle bags command premium positioning in agricultural logistics by maintaining cubic geometry during palletized transport, while conductive bags represent a specialized growth pocket serving electrostatic-sensitive chemical powders. The 1000 kg and 1500 kg capacity tiers capture the majority of food processing and fertilizer sector demand.
FDA food-contact regulations and EU REACH chemical compliance frameworks constrain resin additive formulations and fabric coating chemistries, elevating testing costs for suppliers serving cross-border food and pharmaceutical ingredient channels. ISO 21898 testing protocols for FIBC performance certification create non-tariff barriers that favor established laboratories and repeat-order incumbents over new market entrants. Stakeholders must monitor evolving extended producer responsibility mandates in Europe and state-level plastic packaging fees in the US, as these mechanisms will reshape total cost of ownership calculations and supplier selection criteria.
Market Dynamics
REACH compliance in Europe and evolving FDA food-contact material rules in the US are tightening woven polyethylene purity standards, forcing converters to requalify resin additive formulations and fabric coating chemistries for cross-border chemical and food ingredient shipments.
Growth Catalysts
- UN-certified hazardous material containment:Chemical processors in Germany and the Netherlands mandate FIBC variants with certified performance protocols for electrostatic-sensitive powders, pulling demand for conductive bag constructions.
- Brazilian agricultural commodity expansion:Soybean and coffee exporters in Mato Grosso and Minas Gerais are scaling bulk packaging procurement to match port throughput capacity at Santos and Paranaguá.
- China fertilizer distribution modernization:State-owned nutrient suppliers are replacing 50 kg sacks with 1000 kg and 1500 kg PE jumbo bags to reduce handling labor and palletization costs in inland provincial networks.
Market Restraints
- Polyethylene resin price volatility:Naphtha feedstock fluctuations and cracker operating rate adjustments in the US Gulf Coast and Middle East create margin compression for non-integrated regional converters.
- ISO 21898 testing protocol barriers:Certification costs and laboratory capacity constraints favor established suppliers with repeat-order histories, limiting new entrant penetration in EU and North American hazardous material channels.
- Woven polypropylene substitution:Lower-cost PP FIBCs retain volume share in non-food construction aggregates and mineral applications where electrostatic and food-contact compliance are non-mandatory.
Strategic Opportunities
- Extended producer responsibility mandates:EU Green Deal packaging regulations and emerging state-level plastic fees in California and New York create service revenue potential for closed-loop collection and mechanical recycling programs.
- India chemical processing corridor penetration:Gujarat and Maharashtra industrial zones lack sufficient domestic UN-certified FIBC capacity, opening procurement relationships with compliant foreign suppliers.
- Baffle bag agricultural logistics:Cubic geometry maintenance during palletized transport commands premium positioning in Southeast Asian palm oil and rubber supply chains where container cube optimization reduces freight costs.
Industry Challenges
- Multijurisdictional compliance synchronization:Suppliers serving simultaneous EU REACH, US FDA, and China GB standard markets face conflicting additive restrictions and coating chemistry prohibitions that fragment production runs.
- Woven fabric technical talent scarcity:Extrusion line operators and circular loom technicians with polyethylene-specific coating and lamination expertise concentrate in established manufacturing clusters, constraining greenfield plant staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Jumbo Bags Market |
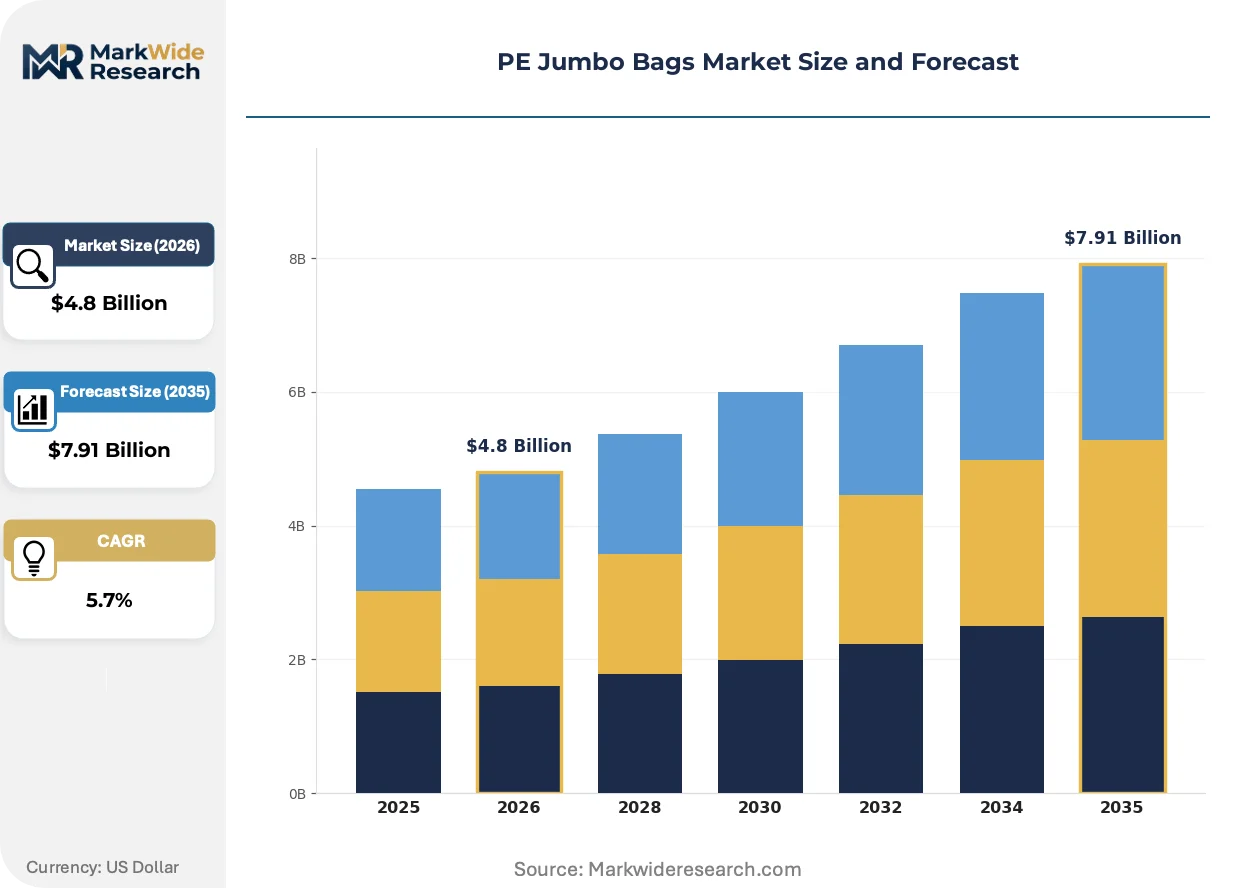
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FIBC, Baffle Bags, Ventilated Bags, Conductive Bags End User: Agriculture, Chemicals, Construction, Food Processing Capacity: 500 kg, 1000 kg, 1500 kg, 2000 kg Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Berry Global Group, Emmbi Industries, AmeriGlobe, Langston Companies Inc, LC Packaging International, Conitex Sonoco, Greif, Intertape Polymer Group, Al-Tawfiq Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Jumbo Bags Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing product development cycles while expanding the addressable application set beyond traditional chemical and agricultural bulk handling into pharmaceutical intermediates and specialized food ingredients.
Co-extruded multilayer polyethylene films with oxygen and moisture barrier properties are displacing laminated constructions in pharmaceutical active ingredient packaging. European API manufacturers in Switzerland and Ireland are qualifying these constructions for hygroscopic powder containment. This technology is miniaturizing the functional gap between rigid intermediate bulk containers and flexible alternatives, enabling PE jumbo bag penetration into moisture-sensitive applications previously reserved for steel or composite IBCs.
EU REACH Annex XVII restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of masterbatch colorants and UV stabilizers used in woven PE tapes. German chemical distributors now require full material disclosure documentation for FIBCs entering pharmaceutical ingredient supply chains. The compliance burden falls most heavily on small and mid-size converters lacking in-house regulatory affairs capacity, accelerating consolidation around vertically integrated suppliers with dedicated ECHA submission resources.
Consolidated procurement desks at multinational agrochemical and food ingredient corporations are unbundling bag supply from logistics services, issuing separate tenders for virgin FIBC purchase, collection, washing, and reconditioning. This purchasing model compression is displacing traditional full-service packaging distributors in the US Midwest and Brazilian Center-West. Bayer Crop Science and Nutrien procurement teams in São Paulo and Chicago exemplify the shift toward outcome-based vendor scorecards measuring total cost per ton moved rather than unit bag pricing.
PE Jumbo Bags Market Segmentation
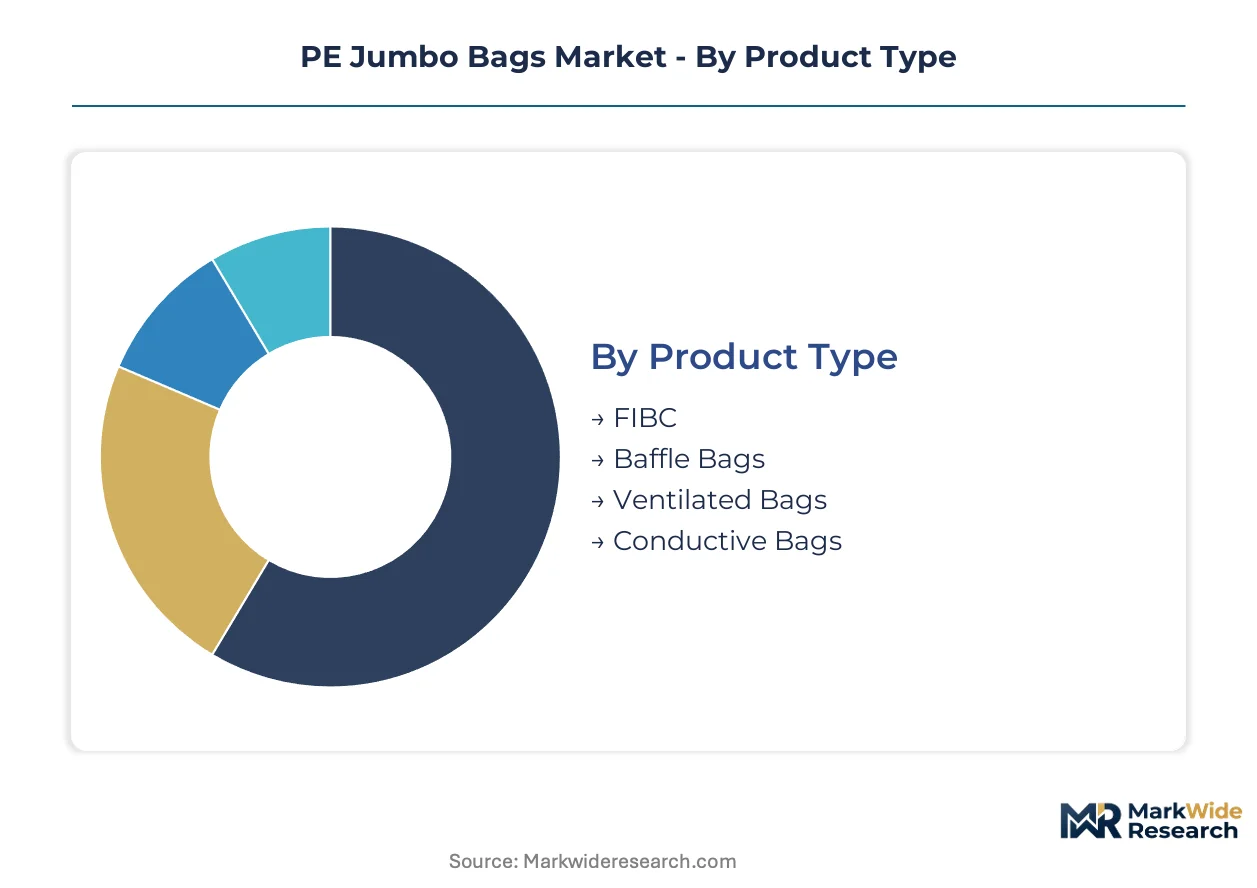
Segmentation in PE jumbo bags reveals how substitution pressures and compliance requirements fragment procurement patterns across end-use industries. Product type differentiation determines margin structure, while capacity tiers align with mechanized handling infrastructure in target geographies.
Product Type:
Woven polypropylene FIBCs exert the strongest substitution pressure on standard PE constructions in non-food construction aggregates where electrostatic and food-contact compliance remain non-mandatory.
- FIBC:Standard flexible intermediate bulk containers constructed from coated or uncoated tubular fabric with four-loop lifting configurations rated for mechanized handling. Chemical processors in Germany and the Netherlands mandate UN-certified variants with ISO 21898 performance protocols for hazardous material containment, pulling demand toward compliant suppliers with established laboratory relationships.
- Baffle Bags:Internal baffle constructions maintain cubic geometry during filling and palletized transport, optimizing container cube utilization in maritime shipping. Southeast Asian palm oil and rubber supply chains command premium positioning for these variants where freight cost reduction justifies higher unit pricing.
- Ventilated Bags:Mesh or perforated fabric constructions enable airflow for moisture-sensitive agricultural commodities. Coffee exporters in Minas Gerais and cocoa processors in West Africa deploy these for green bean storage where condensation control prevents mold degradation.
- Conductive Bags:Carbon-filament or metalized fabric constructions dissipate electrostatic charges for flammable powder handling. Swiss and Irish pharmaceutical API manufacturers qualify these for hygroscopic active ingredient containment under EU REACH material disclosure requirements.
FIBC anchors the volume base while conductive bags gain share at the steepest rate.
End User:
Cost tier stratification separates premium compliance-driven segments from economy-grade construction applications where woven polypropylene retains volume dominance.
- Agriculture:Soybean and coffee exporters in Brazil's Mato Grosso and Minas Gerais states scale bulk packaging procurement to match port throughput capacity at Santos and Paranaguá. State-owned nutrient suppliers in China's inland provinces replace 50 kg sacks with 1000 kg and 1500 kg configurations to reduce handling labor.
- Chemicals:UN-certified containment for electrostatic-sensitive powders drives specification complexity. German chemical distributors now require full material disclosure documentation for FIBCs entering pharmaceutical ingredient supply chains, favoring vertically integrated suppliers with dedicated ECHA submission resources.
- Construction:Mineral and aggregate handling tolerates lower-cost woven polypropylene alternatives where hazardous material certification is non-mandatory. Non-integrated regional converters face margin compression from resin price volatility in this price-sensitive segment.
- Food Processing:FDA food-contact regulations and evolving purity standards constrain resin additive formulations and fabric coating chemistries. EU REACH Annex XVII restrictions on phthalate plasticizers force reformulation of masterbatch colorants for cross-border shipments.
Chemicals commands the premium pricing tier while agriculture delivers the highest absolute volume throughput.
Capacity:
Application-specific handling infrastructure determines which capacity tiers achieve adoption in regional logistics networks.
- 500 kg:Compact configurations suit small-scale agricultural cooperatives and specialty chemical batch processing where forklift availability is limited.
- 1000 kg:The dominant tier for food processing and fertilizer sector demand, aligning with standard pallet dimensions and forklift rated capacities in Indian chemical processing corridors.
- 1500 kg:Preferred by China's state-owned nutrient suppliers for inland provincial distribution modernization, reducing palletization costs versus smaller sack alternatives.
- 2000 kg:Heavy-duty constructions for mineral aggregates and construction materials where equipment handling capacity permits bulkier single-unit loads.
1000 kg configurations anchor installed base volumes while 1500 kg tiers expand most quickly in Asian fertilizer networks.
Distribution Channel:
Customer type fragmentation separates integrated procurement desks from fragmented regional converter relationships.
- Direct Sales:Consolidated procurement desks at multinational agrochemical and food ingredient corporations issue separate tenders for virgin FIBC purchase, collection, washing, and reconditioning. Bayer Crop Science and Nutrien procurement teams exemplify outcome-based vendor scorecards measuring total cost per ton moved.
- Online Retail:Digital platforms serve small and mid-size converters lacking in-house regulatory affairs capacity, accelerating price transparency in standard grades.
- Distributors:Traditional full-service packaging distributors face displacement in the US Midwest and Brazilian Center-West as procurement unbundling separates bag supply from logistics services.
- Wholesalers:Regional inventory aggregation serves spot-market demand from construction and non-food mineral applications with lower compliance requirements.
Direct sales captures the premium compliance-driven volume while distributor relationships face compression from procurement desk consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across major agricultural and chemical corridors are redistributing PE jumbo bag procurement patterns. Brazil and Southeast Asian commodity exporters scale bulk packaging capacity to match port throughput, while European and North American chemical processors tighten compliance specifications for cross-border shipments.
United States
FDA food-contact material rules are tightening woven polyethylene purity standards for pharmaceutical ingredient channels. Midwestern agrochemical procurement desks at Nutrien and Bayer Crop Science unbundle bag supply from logistics services, issuing separate tenders for virgin FIBC purchase and reconditioning. Chicago anchors distributor displacement as outcome-based vendor scorecards measure total cost per ton moved.
Germany
UN-certified hazardous material containment mandates from chemical processors in the Rhine-Ruhr industrial zone pull demand for conductive bag constructions. ECHA REACH Annex XVII restrictions on phthalate plasticizers force reformulation of masterbatch colorants for pharmaceutical supply chains. Ludwigshafen and Leverkusen chemical clusters require full material disclosure documentation, favoring vertically integrated suppliers with dedicated regulatory submission resources.
China
State-owned nutrient suppliers in inland provinces replace 50 kg sacks with 1000 kg and 1500 kg configurations to reduce handling labor and palletization costs. GB standards compliance for woven polyethylene food-contact applications constrains resin additive formulations. Shandong and Jiangsu fertilizer distribution networks modernize mechanized handling infrastructure to accommodate heavier single-unit loads.
Brazil
Soybean and coffee exporters in Mato Grosso and Minas Gerais scale bulk packaging procurement to match port throughput capacity at Santos and Paranaguá. ANVISA pharmaceutical packaging regulations intersect with EU REACH compliance for export-bound active ingredients. The Center-West agricultural belt drives baffle bag adoption for cubic geometry optimization during containerized maritime shipping.
India
Gujarat and Maharashtra chemical processing corridors lack sufficient domestic UN-certified FIBC capacity, opening procurement relationships with compliant foreign suppliers. BIS standards for hazardous material containment create non-tariff barriers favoring established laboratory relationships. Mundra and Hazira industrial zones anchor woven-fabric manufacturing expansion serving agricultural export channels.
PE Jumbo Bags Market Competitive Landscape
Concentration sits with integrated resin producers and regional converters whose captive polyethylene supply chains sustain margin compression in standard FIBC grades. The market structure bifurcates between capital-intensive integrated players and specialized regional fabricators. Three archetypes dominate: multinational industrial packaging conglomerates with global footprints, dedicated woven-fabric specialists serving agricultural export corridors, and resin-backed converters leveraging upstream supply control. Competitive moves center on backward integration into resin production and geographic expansion into underpenetrated chemical processing zones.
Among North American industrial packaging conglomerates, Berry Global Group and Greif exemplify scale-driven positioning through global footprints and reuse service extension. Emmbi Industries represents the dedicated woven-fabric specialist archetype, anchoring regional procurement relationships in South Asian agricultural export channels. These three companies illustrate how competitive positioning fragments across integrated supply chain control, geographic specialization, and service bundling strategies.
| Leading Market Players |
|---|
| Berry Global Group |
| Emmbi Industries |
| AmeriGlobe |
| Langston Companies Inc |
| LC Packaging International |
| Conitex Sonoco |
| Greif |
| Intertape Polymer Group |
| Al-Tawfiq Company |
| Others |
Value Network & Pricing Analysis
ISO 21898 certification protocols gate both supplier qualification and price differentiation in PE jumbo bags, creating a bifurcated market where UN-certified constructions command substantial premiums over standard grades while non-integrated converters face persistent margin compression.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tier captures UN-certified conductive bags for pharmaceutical API channels where ECHA REACH disclosure requirements elevate testing costs. Standard grades serve agricultural exporters with baffle bag configurations optimizing container cube utilization. Economy tier faces price erosion from woven polypropylene substitution in construction aggregates where electrostatic compliance is non-mandatory. Cost compression in standard FIBC grades intensifies because naphtha feedstock volatility and cracker operating rate adjustments in the US Gulf Coast transmit directly to non-integrated regional converters.
Supply Chain Analysis
China and India anchor woven polyethylene fabric production, with Shandong and Jiangsu provinces hosting extrusion and circular loom clusters serving domestic fertilizer distribution networks. Gujarat and Maharashtra chemical corridors draw from imported UN-certified capacity where domestic laboratory relationships remain underdeveloped. Raw material dependencies center on naphtha-derived polyethylene resin from US Gulf Coast and Middle Eastern crackers, plus carbon-filament yarns for conductive bag constructions. Single-source vulnerability concentrates in specialized coating chemistries where EU REACH Annex XVII restrictions on phthalate plasticizers have eliminated qualified Asian suppliers. Distribution runs through direct sales channels for multinational agrochemical procurement desks, with traditional wholesalers serving spot-market construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement desks at multinational agrochemical and food ingredient corporations, fragmenting vendor relationships and unbundling bag supply from logistics services.
For Market Incumbents: Shield margin position by deepening backward integration into captive polyethylene resin production and accelerating certification investment for EU REACH Annex XVII compliance. Woven polypropylene substitution in construction aggregates threatens volume share in price-sensitive tiers. Channel control through closed-loop collection and mechanical recycling programs captures service revenue as extended producer responsibility mandates expand. For New Entrants and Emerging Players: Lead with UN-certified FIBC capacity targeting Gujarat and Maharashtra chemical processing corridors where domestic laboratory relationships create supply gaps. India's pharmaceutical ingredient export channels offer the most penetrable white-space, with BIS standards compliance serving as the critical go-to-market credential. Technical talent scarcity in extrusion line operators and circular loom technicians constrains rapid scaling. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational industrial packaging conglomerates seeking to divest non-core regional converter assets. Long-term viability hinges on regulatory compliance automation and geographic positioning in underpenetrated chemical processing zones. Watch ECHA REACH enforcement intensity as the inflection indicator for consolidation acceleration around vertically integrated suppliers with dedicated submission resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyethylene supply insulates Berry Global Group from naphtha volatility in standard grades. |
| UN Certification Investment | ISO 21898 laboratory relationships unlock German chemical processor procurement at Rhine-Ruhr clusters. |
| Closed-Loop Recycling Programs | EU Green Deal packaging regulations transform collection services into recurring revenue streams. |
| Baffle Bag Capacity Expansion | Cubic geometry optimization commands premium positioning in Southeast Asian palm oil supply chains. |
| Geographic Expansion into India | Gujarat and Maharashtra chemical corridors lack sufficient domestic UN-certified FIBC capacity. |
Research Methodology
Operator-level perspectives from plant managers at woven fabric facilities, procurement leads at agrochemical distributors, technical R&D directors for coating formulations, and channel partners in agricultural export corridors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, chemical industry association reports, SEC 10-K filings, and FDA food-contact material guidance documents. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested volume and value outputs against resin price volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions modeled include product type tier, end-use industry, capacity configuration, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements, with specific inputs for fertilizer distribution modernization rates in China and Brazilian agricultural commodity export growth.
Forecasts assume regulatory continuity in EU REACH, US FDA, and China GB standard regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding naphtha feedstock pricing stability and laboratory certification capacity expansion. Recalibration cycles align with material shifts in extended producer responsibility mandate implementation and cracker operating rate adjustments in major supply regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Octabin Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Pasted Valve Bags Market