
 Europe Bulk Bags Market | 2026-2036
Europe Bulk Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bulk Bags Market Analysis
CE marking under the EU's Packaging and Packaging Waste Directive is collapsing the supplier base to firms with certified testing infrastructure. Greif, Inc. leverages its integrated woven polypropylene operations across multiple European plants to sustain volume leadership. Berry Global Group anchors its position through advanced extrusion capabilities that meet food-contact migration limits. Mondi Group differentiates via lightweighting R&D that reduces material intensity without sacrificing load ratings.
Bulk bags are large-volume flexible intermediate bulk containers, typically constructed from woven polypropylene fabric with four lifting loops and a safe working load of 500–2,000 kg, designed for the storage and transport of dry flowable materials. The FIBC segment dominates value generation due to its ubiquity in chemical and mineral handling, while conductive bags represent the fastest-expanding niche as electrostatic-sensitive industries tighten material safety protocols. Polypropylene sustains overwhelming material share because of its tensile strength, chemical resistance, and recyclability under EU circular-economy frameworks.
REACH registration requirements and the EU Green Deal's packaging sustainability targets are forcing reformulation of virgin resin content and accelerating post-industrial recycling adoption. ECHA substance restrictions and national extended producer responsibility schemes in Germany, France, and Italy shape competitive access by penalizing non-compliant imports. Stakeholders must monitor upcoming revisions to the PPWR and the CSRD's supply-chain disclosure rules to anticipate compliance cost shifts and qualification timeline extensions.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's packaging sustainability targets are forcing immediate reformulation of virgin resin specifications, collapsing the qualified supplier base to firms with certified testing infrastructure and documented post-industrial recycling streams.
Growth Catalysts
- Chemical sector expansion:German and French chemical manufacturers are scaling FIBC orders for mineral and powder handling, driven by capacity additions in specialty chemicals and agrochemicals.
- REACH material registration:Compliance requirements for woven polypropylene additives are locking in established suppliers with ECHA-registered formulations and documented safety data sheets.
- Conductive bag adoption:Electrostatic-sensitive industries including pharmaceuticals and electronics are mandating Type C and Type D FIBCs for solvent and powder handling.
Market Restraints
- Polypropylene price volatility:Naphtha feedstock costs tied to European natural gas pricing are compressing margins for converters without long-term resin contracts.
- Testing infrastructure concentration:CE marking and UN certification capabilities cluster in Germany, Netherlands, and Italy, creating qualification bottlenecks for peripheral suppliers.
- Flexible intermediate bulk container substitution:Rigid intermediate bulk containers are capturing share in closed-loop pharmaceutical and food applications requiring repeated sterilization.
Strategic Opportunities
- Central and Eastern Europe penetration:Poland, Czech Republic, and Hungary offer underdeveloped FIBC specification standards with accelerating chemical and agricultural investment.
- Post-industrial recycling integration:The EU Green Deal's 2030 packaging recyclability targets create first-mover advantage for converters with validated closed-loop polypropylene recovery systems.
- Food-contact migration compliance:EFSA-compliant extrusion and lamination capabilities open premium dairy, grain, and ingredient handling segments with higher certification barriers.
Industry Challenges
- Multilayer coextrusion expertise scarcity:Food-contact barrier FIBCs require specialized extrusion technicians and polymer scientists concentrated in Germany and Benelux.
- CSRD supply-chain disclosure complexity:The Corporate Sustainability Reporting Directive mandates granular Scope 3 emissions documentation that many mid-tier converters cannot yet provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bulk Bags Market |
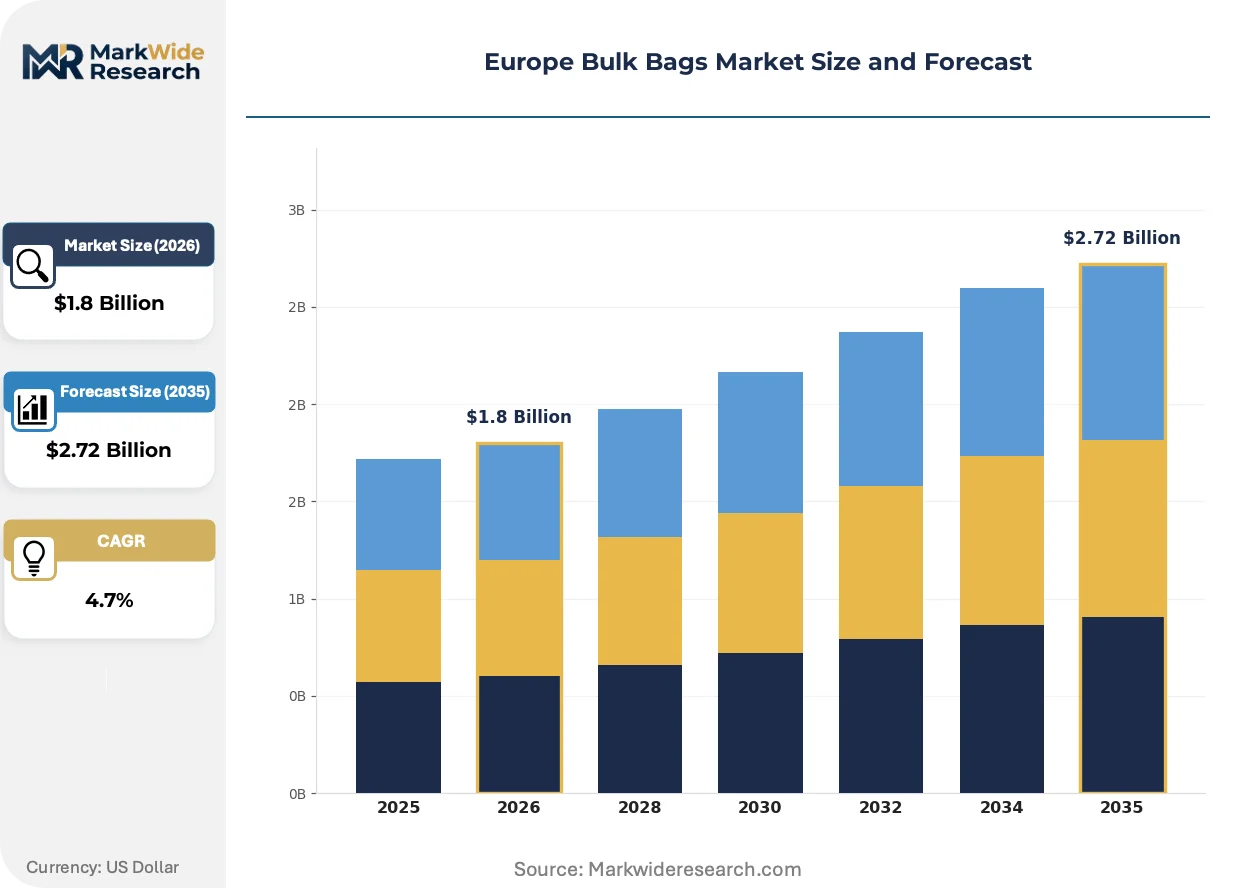
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, FIBC, Tarp Bags, Conductive Bags Material: Polypropylene, Polyester, Cotton, Jute End User: Agriculture, Chemicals, Food, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Greif, Inc., Berry Global Group, Inc., Intertape Polymer Group, Conitex Sonoco, LC Packaging International BV, BAG Corp, Sackmaker J&HM Dickson Ltd, Mondi Group, Rudolph Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bulk Bags Market Emerging Trajectories
Lightweighting R&D and conductive fabric engineering are compressing material intensity while expanding addressable end-uses, as regulatory pressure on virgin resin content accelerates substitution trials.
Multilayer coextruded barrier films are decomposing the traditional single-layer woven polypropylene standard for moisture-sensitive and oxygen-critical applications. Pharmaceutical ingredient handlers and specialty chemical distributors are specifying these structures for hygroscopic powders. The technology is decomposing volume-based pricing models by shifting procurement criteria toward certified performance metrics and documented shelf-life extension.
The EU Packaging and Packaging Waste Regulation revision is mandating minimum recycled content thresholds and extended producer responsibility fee modulation based on recyclability scores. Converters with validated mechanical recycling streams gain cost advantages over import-dependent competitors. Food-contact and pharmaceutical FIBC segments face the steepest compliance cost escalations and are consolidating supplier qualification lists to pre-certified domestic manufacturers.
Consolidated chemical and agribuyer procurement is compressing supplier margins through multi-year framework agreements with performance guarantees and total cost of ownership clauses. Distributors and trading houses are losing share to direct mill relationships as buyers seek traceability documentation for CSRD compliance. This pattern is most pronounced in Germany's Rhine-Ruhr industrial corridor and northern France's chemical cluster, where procurement functions have centralized sustainability verification responsibilities.
Europe Bulk Bags Market Segmentation
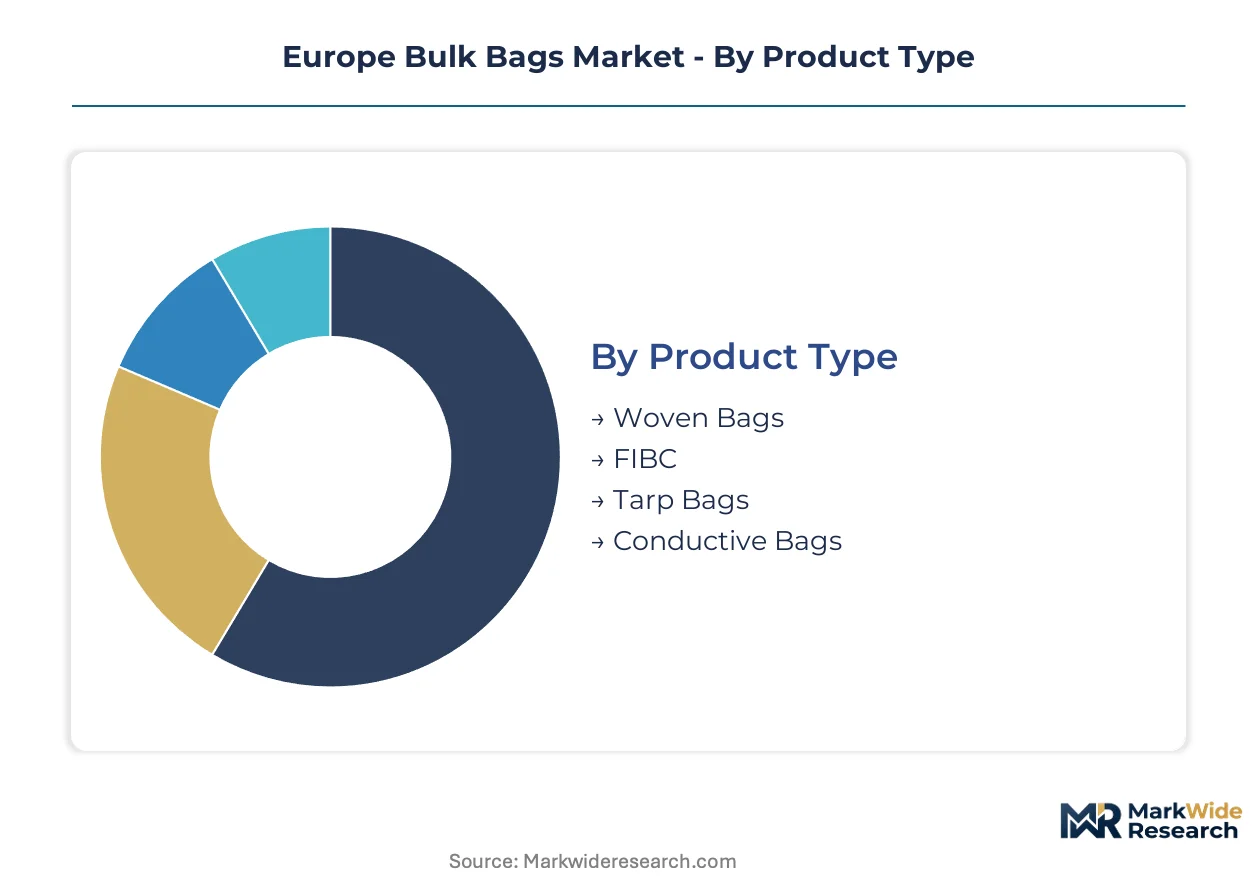
Segmentation in the Europe Bulk Bags Market reveals how regulatory frameworks fragment competitive access across product tiers. REACH registration and CE marking requirements create divergent qualification costs that reshape supplier positioning in each category.
Product Type:
REACH substance registration and UN certification standards separate qualified suppliers from commodity competitors across product categories.
- FIBC:Flexible intermediate bulk containers constructed from woven polypropylene fabric with four lifting loops and 500–2,000 kg safe working loads dominate chemical and mineral handling throughout Germany's Rhine-Ruhr corridor. ECHA-registered additive formulations and documented safety data sheets lock in established suppliers against import competition.
- Conductive Bags:Type C and Type D FIBCs engineered with conductive yarns or dissipative fabrics prevent electrostatic discharge in solvent and powder handling. Pharmaceutical manufacturers across France's chemical cluster and electronics assemblers in the Netherlands mandate these specifications for flammable material transport.
- Woven Bags:Standard woven polypropylene sacks serve agricultural grain and feed applications with lower certification barriers.
- Tarp Bags:Heavy-duty laminated covers protect bulk materials during outdoor storage and transport.
FIBC handles the majority of throughput; Conductive Bags are gaining share fastest on electrostatic safety mandates.
Material:
Cost tiers align with recyclability validation under EU Green Deal packaging targets.
- Polypropylene:Virgin and recycled polypropylene resins provide tensile strength, chemical resistance, and mechanical recyclability under extended producer responsibility schemes. German converters with validated post-industrial recovery systems capture margin advantages over naphtha-dependent competitors facing natural gas price volatility.
- Polyester:PET-based woven fabrics offer superior UV resistance and dimensional stability for extended outdoor duty cycles. Italian agricultural cooperatives specify polyester for seasonal grain storage with multi-year reuse requirements.
- Cotton:Natural fiber woven bags serve organic certification holders requiring biodegradable packaging.
- Jute:Traditional bast fiber construction persists in specialty coffee and cocoa export niches.
Polypropylene commands volume leadership; Polyester climbs fastest on durability premiums in agricultural contracting.
End User:
Application-specific migration limits and sterilization protocols create divergent certification pathways.
- Chemicals:Specialty chemical and agrochemical manufacturers in Germany, France, and Belgium drive specification-grade FIBC demand with UN-certified dangerous goods requirements. REACH compliance documentation and batch traceability systems qualify a narrowing supplier base for hazardous material handling.
- Food:EFSA-compliant extrusion and lamination capabilities open dairy, grain, and ingredient handling segments with stringent food-contact migration limits. Multilayer coextrusion expertise concentrates in German and Benelux converters.
- Agriculture:Grain cooperatives and feed compounders across Poland, Hungary, and Romania source standard woven bags with lower barrier specifications.
- Construction:Cement and mineral wool distributors specify heavy-duty FIBCs with abrasion-resistant coatings.
Chemicals anchors volume demand; Food is expanding most quickly on compliance-driven supplier consolidation.
Distribution Channel:
Customer type and order scale determine channel economics and traceability documentation requirements.
- Direct Sales:Mill-direct relationships dominate consolidated chemical and agribuyer procurement with multi-year framework agreements. Centralized sustainability verification responsibilities in German and French procurement functions demand granular Scope 3 emissions documentation that distributors cannot provide.
- Distributors:Stocking intermediaries serve fragmented agricultural and construction customers with smaller lot sizes and spot purchasing patterns.
- Wholesalers:Volume aggregators supply peripheral European markets with standardized specifications.
- Online Retail:Digital channels capture spot demand from small-scale agricultural and construction buyers.
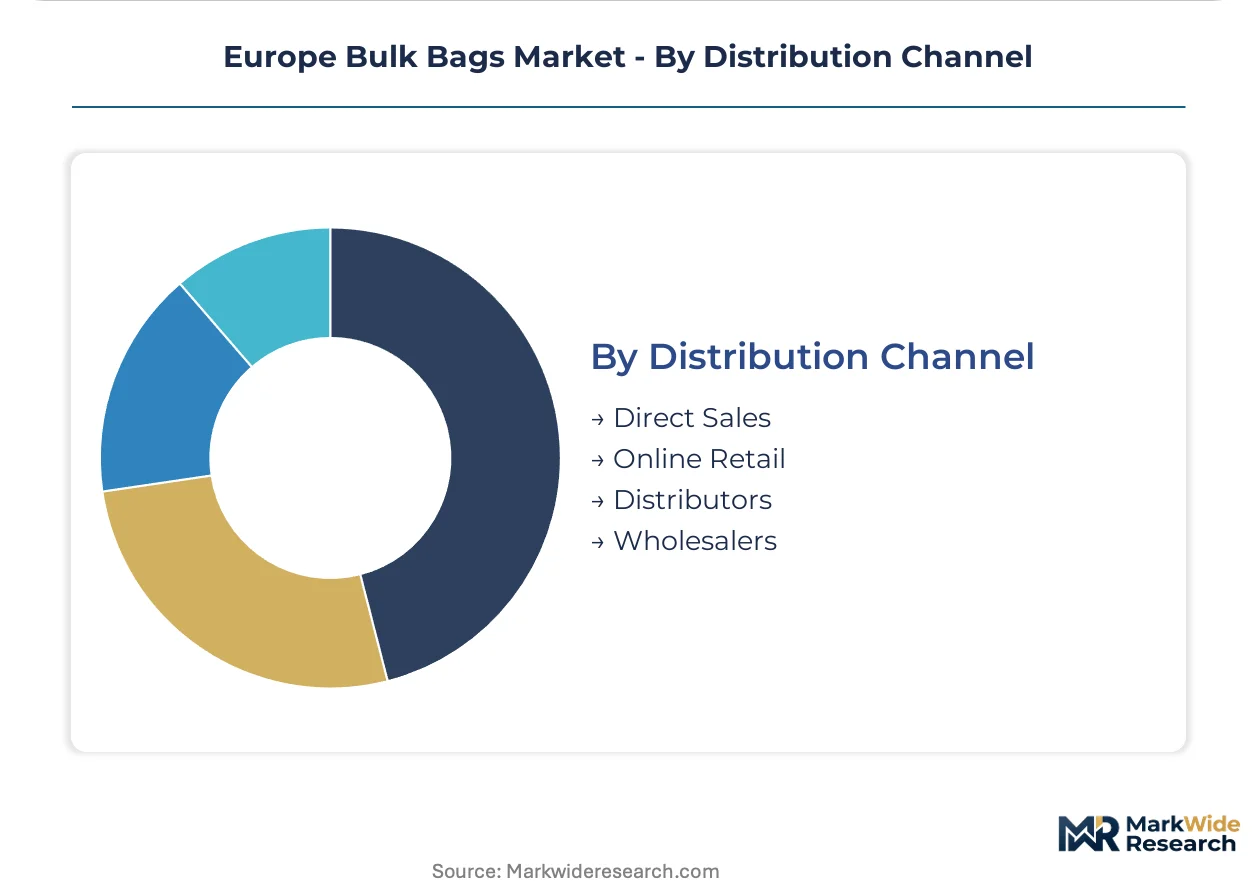
Direct Sales transacts the largest volume; Distributors retain share in geographically dispersed agricultural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration deadlines and the EU Green Deal's packaging sustainability targets are redirecting investment toward countries with established testing infrastructure and documented recycling streams. Chemical sector expansion and centralized procurement functions are concentrating demand in industrial corridors with verified compliance capabilities.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr corridor are scaling FIBC orders for mineral and powder handling. ECHA-registered additive formulations and documented safety data sheets lock in established suppliers against import competition. Berlin-based procurement functions have centralized sustainability verification responsibilities, demanding granular Scope 3 emissions documentation.
France
Pharmaceutical manufacturers across the chemical cluster are mandating Type C and Type D FIBCs for solvent and flammable material transport. CE marking requirements under the EU Packaging and Packaging Waste Directive collapse the qualified supplier base to firms with certified testing infrastructure. Lyon and Paris procurement hubs prioritize direct mill relationships over distributors for traceability documentation.
Netherlands
Electronics assemblers and chemical distributors specify conductive bags for electrostatic-sensitive material handling. UN certification capabilities cluster in Dutch testing facilities, creating qualification advantages for regional converters. Rotterdam's logistics hub anchors distribution networks serving Benelux chemical and agricultural buyers.
Italy
Agricultural cooperatives specify polyester-based woven bags for seasonal grain storage with multi-year reuse requirements. National extended producer responsibility schemes penalize non-compliant imports, shaping competitive access. Northern Italian converters with validated mechanical recycling streams capture margin advantages over naphtha-dependent competitors.
Poland
Chemical and agricultural investment is accelerating in underdeveloped FIBC specification standards. The EU Green Deal's 2030 packaging recyclability targets create first-mover advantage for converters establishing closed-loop polypropylene recovery systems. Warsaw and Kraków procurement functions are consolidating supplier qualification lists to pre-certified domestic manufacturers.
Europe Bulk Bags Market Vendor Landscape
Player mix skews toward integrated packaging conglomerates with captive woven polypropylene operations and specialized regional converters with certified food-contact capabilities. The supplier base concentrates around firms with ECHA-registered formulations, CE marking infrastructure, and documented post-industrial recycling streams. Strategic archetypes include integrated multinational packaging groups, mid-tier regional specialists with barrier film expertise, and niche conductive fabric engineers. Competitive moves center on backward integration into resin compounding and geographic expansion into Central and Eastern European markets.
Among integrated packaging groups, Greif, Inc. and Berry Global Group, Inc. occupy positions representing scale-driven volume leadership with multi-plant European woven polypropylene networks. Mondi Group exemplifies the lightweighting and sustainability-focused archetype through differentiated R&D positioning. Regional specialists including LC Packaging International BV and Sackmaker J&HM Dickson Ltd anchor mid-tier competitive positioning with certified testing infrastructure and food-contact migration compliance capabilities.
| Leading Market Players |
|---|
| Greif, Inc. |
| Berry Global Group, Inc. |
| Intertape Polymer Group |
| Conitex Sonoco |
| LC Packaging International BV |
| BAG Corp |
| Sackmaker J&HM Dickson Ltd |
| Mondi Group |
| Rudolph Logistics |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with naphtha-indexed resin clauses lock in supply access for German and French chemical buyers while capping price volatility exposure across the analysis window. These structures tether converter margins to European natural gas benchmarks and REACH compliance cost pass-through mechanisms.
Pricing Analysis
Cost-plus contracts with monthly naphtha indexation dominate polypropylene feedstock pricing for European converters. Three-tier pricing structure across REACH-certified premium, CE-marked standard, and uncertified economy levels separates qualified suppliers from import competitors. Pricing pressure stems from centralized procurement functions demanding granular Scope 3 documentation without premium tolerance. Agricultural cooperatives in Poland and Hungary exhibit highest price sensitivity; pharmaceutical manufacturers in France's chemical cluster accept certification premiums without volume negotiation.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German chemical manufacturers with integrated ERP systems linking FIBC consumption to production schedules. Virgin resin compounding concentrates in Germany, Netherlands, and Belgium; woven fabric conversion clusters in Poland and Czech Republic. Raw material dependencies center on naphtha-derived polypropylene, conductive yarn additives, and multilayer coextrusion films. Single-source vulnerability runs through ECHA-registered additive suppliers with limited formulation alternatives. Distribution runs through Rotterdam's logistics hub serving Benelux chemical corridors and direct mill relationships displacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-industrial recycling validation services and CSRD compliance documentation represent faster-expanding revenue layers than base FIBC hardware across the European market. These recurring-revenue attachments transform transactional converter relationships into multi-year service partnerships.
For Market Incumbents: Consolidate testing infrastructure advantages by acquiring CE marking capabilities in Poland and Czech Republic before qualification bottlenecks harden. Lock in backward integration into resin compounding to defend margin position against naphtha volatility. Prioritize EFSA-compliant extrusion capacity expansion as food-contact migration limits displace commodity competitors from premium segments.
For New Entrants and Emerging Players: REACH registration fast-track through authorized representative partnerships in Germany offers qualification acceleration without full ECHA submission timelines. Target Poland's underdeveloped FIBC specification standards with conductive bag specialization for electronics assemblers. Pursue direct sales relationships with Warsaw-based procurement functions consolidating supplier lists to pre-certified domestic manufacturers.
For Investors and Strategic Acquirers: Regional specialists with validated mechanical recycling streams and food-contact barrier film expertise represent the optimal acquisition target archetype for sustainability-driven consolidation. Long-term viability hinges on EU Green Deal packaging recyclability target compliance rather than volume scale alone. Watch for ECHA substance restriction announcements on polypropylene additives as inflection indicators for qualified supplier base contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from naphtha volatility and secures REACH-registered formulation control. |
| CE Marking Infrastructure Expansion | Unlocks qualification advantages in Central and Eastern European chemical corridors. |
| Post-Industrial Recycling Validation | Generates EU Green Deal compliance premiums and EPR fee reductions. |
| EFSA-Compliant Extrusion Capacity | Opens food-contact dairy and grain handling segments with certification barriers. |
| Conductive Fabric Engineering Partnership | Addresses Type C and Type D FIBC mandates from pharmaceutical and electronics buyers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration databases, Cefic industry reports, and SEC filings from integrated packaging groups. Interviews with FIBC procurement leads at German chemical manufacturers, plant managers at Polish converter facilities, distribution channel partners in Benelux, and technical R&D directors specializing in barrier film extrusion informed demand-side and supply-side assessments. Bottom-up volume modeling triangulates against top-down macroeconomic indicators across the European region.
Segmentation dimensions modeled include product type tier, material grade, end-use industry vertical, distribution channel structure, and country-level regulatory cluster. CAGRs derive from regression analysis of historical shipment data and elasticity-adjusted forward projections. Forecast inputs incorporate REACH compliance timeline acceleration, EU Packaging and Packaging Waste Regulation revision impacts, and naphtha price correlation coefficients with European natural gas benchmarks.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement and EU Green Deal packaging target adherence; material deviation would warrant model refresh. Specific risk factors include ECHA additive restriction expansions, natural gas price dislocations affecting resin economics, and CSRD disclosure requirement scope creep. Revision becomes warranted when centralized procurement consolidation crosses thresholds that eliminate distributor channel viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Flat Bottom Bags Market