
 Slider Bags Market | 2026-2036
Slider Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Slider Bags Market Intelligence
North American polyethylene resin suppliers are decoupling from traditional virgin feedstock contracts as recycled-content mandates tighten. Berry Global leverages vertical integration across blown film extrusion to sustain margin control in food-grade slider applications. SC Johnson anchors brand equity through Ziploc's retail shelf presence, while Reynolds Consumer Products competes on value-tier positioning in club-store channels.
Slider bags are flexible packaging enclosures featuring an interlocking plastic track mechanism bonded to film sidewalls, typically manufactured through coextrusion or adhesive lamination of low-density polyethylene or linear low-density polyethylene layers with thicknesses ranging from 1.5 to 4 mil. Their primary commercial purpose centers on repeatable access to contents while maintaining barrier integrity against moisture and oxygen ingress. Reclosable slider bags lead volume due to universal kitchen and pantry adoption, whereas child-resistant slider bags command premium positioning driven by pharmaceutical storage compliance requirements. Multi-layer films represent the fastest-growing material category as brands pursue oxygen-scavenging and moisture-barrier performance without metalized components.
FDA food-contact substance regulations govern resin approvals and migration limits for domestic U.S. slider bag production, while EU REACH restrictions on phthalate plasticizers constrain additive formulations exported to European markets. State-level extended producer responsibility frameworks in California and Oregon are forcing reformulation timelines for virgin plastic thresholds. Stakeholders must monitor polymer recycling infrastructure buildouts and sortation technology advances to validate recycled-content claims before procurement specifications harden.
Market Dynamics
Recycled-content mandates across multiple jurisdictions are forcing resin procurement restructuring and accelerating capital deployment into mechanical recycling infrastructure for food-grade film applications.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates recycled content thresholds that pull converters toward certified post-consumer resin streams, expanding addressable supply for compliant slider bag production.
- Meal-prep subscription services:Portion-control packaging specifications from direct-to-consumer food platforms are standardizing reclosable formats across warehouse club and grocery channels.
- Multi-layer coextrusion:Oxygen-scavenging film architectures are displacing metalized laminates in barrier-sensitive applications while maintaining microwave compatibility.
Market Restraints
- LLDPE resin price volatility:Ethane feedstock exposure ties margin stability to Gulf Coast petrochemical capacity utilization and hurricane disruption patterns.
- Mechanical recycling contamination thresholds:Sortation technology limitations cap post-consumer resin availability for food-contact applications below procurement mandate timelines.
- Paper-based flexible packaging:Fiber alternatives are capturing shelf-stable dry goods segments where moisture barrier requirements permit substrate substitution.
Strategic Opportunities
- Pharmaceutical compliance storage:Child-resistant slider mechanisms face underpenetration in European and Asian prescription dispensing formats governed by USP 671 and comparable national standards.
- Chemical recycling scale-up:Pyrolysis-derived resin offers pathway to food-contact approval bypassing mechanical recycling contamination constraints.
- Extended producer responsibility frameworks:California and Oregon EPR laws create first-mover advantage for producers with verified recycled-content supply chains.
Industry Challenges
- Migration testing protocols:FDA food-contact notification timelines for novel resin additives extend 18-24 months, compressing product development windows against mandate deadlines.
- Film thickness standardization:Retailer private-label specifications fragment across 1.5 mil to 4 mil ranges, preventing scale economies in masterbatch formulation.
- Legacy extrusion asset retrofitting:Coextrusion line upgrades for seven-layer barrier structures demand capital allocation competing with greenfield recycling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slider Bags Market |
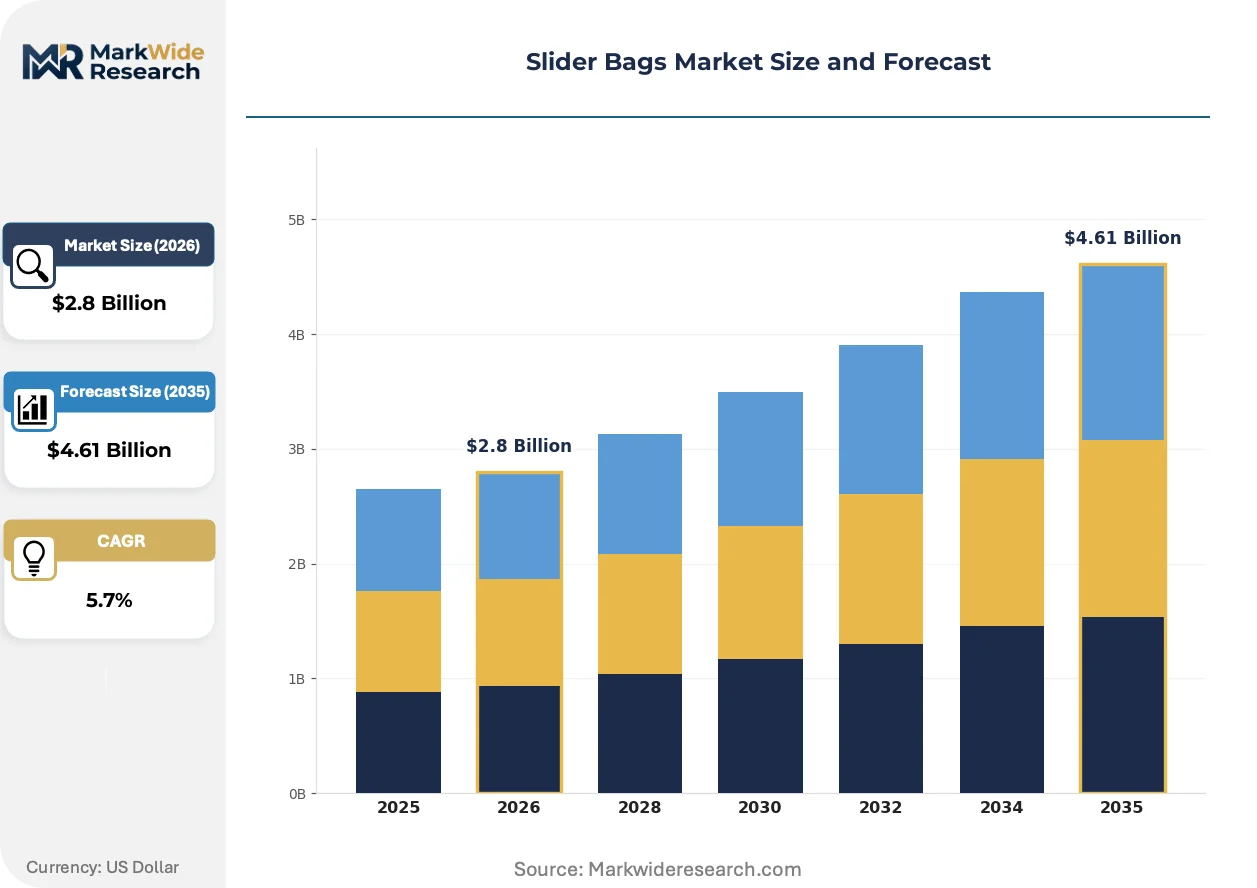
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Slider Bags, Reclosable Slider Bags, Stand-Up Slider Bags, Child-Resistant Slider Bags, Slider Freezer Bags Material: Low-Density Polyethylene, Linear Low-Density Polyethylene, Polypropylene, Biodegradable Plastic, Multi-Layer Films Application: Food Packaging, Pharmaceutical Storage, Personal Care Products, Stationery Organization, Hardware Component Storage End User: Consumer Goods Manufacturers, Healthcare Providers, Educational Institutions, Electronics Assembler, Food Service Providers |
| Companies Covered | SC Johnson (Ziploc), Reynolds Consumer Products, Inteplast Group, Berry Global, C-P Flexible Packaging, International Plastics Inc., Glad Products Company, Minigrip, Glenroy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slider Bags Market Strategic Shifts & Innovations
Material science advances and regulatory compliance architectures are converging to redefine competitive positioning in barrier film applications.
Mono-material polyethylene constructions are overtaking multi-substrate laminates in recycling-stream compatibility. Retailers with corporate sustainability commitments are specifying these formats for private-label adoption. The shift is compressing demand for adhesive lamination capacity while expanding blown film extrusion requirements.
REACH restrictions on phthalate plasticizers are constraining additive portfolios for European export production. Formulators are migrating to bio-based plasticizers and non-phthalate alternatives with comparable low-temperature flexibility profiles. Food-service slider bag lines face reformulation timelines ahead of 2025 substance restriction enforcement.
Direct sourcing from resin producers is consolidating procurement decision-making among large-format retailers. Club-store volume concentration enables specification of custom melt-index ranges and additive packages. The pattern is most visible in United States warehouse channels where bagged produce and bulk meat programs drive standardized sizing requirements.
Slider Bags Market Segmentation
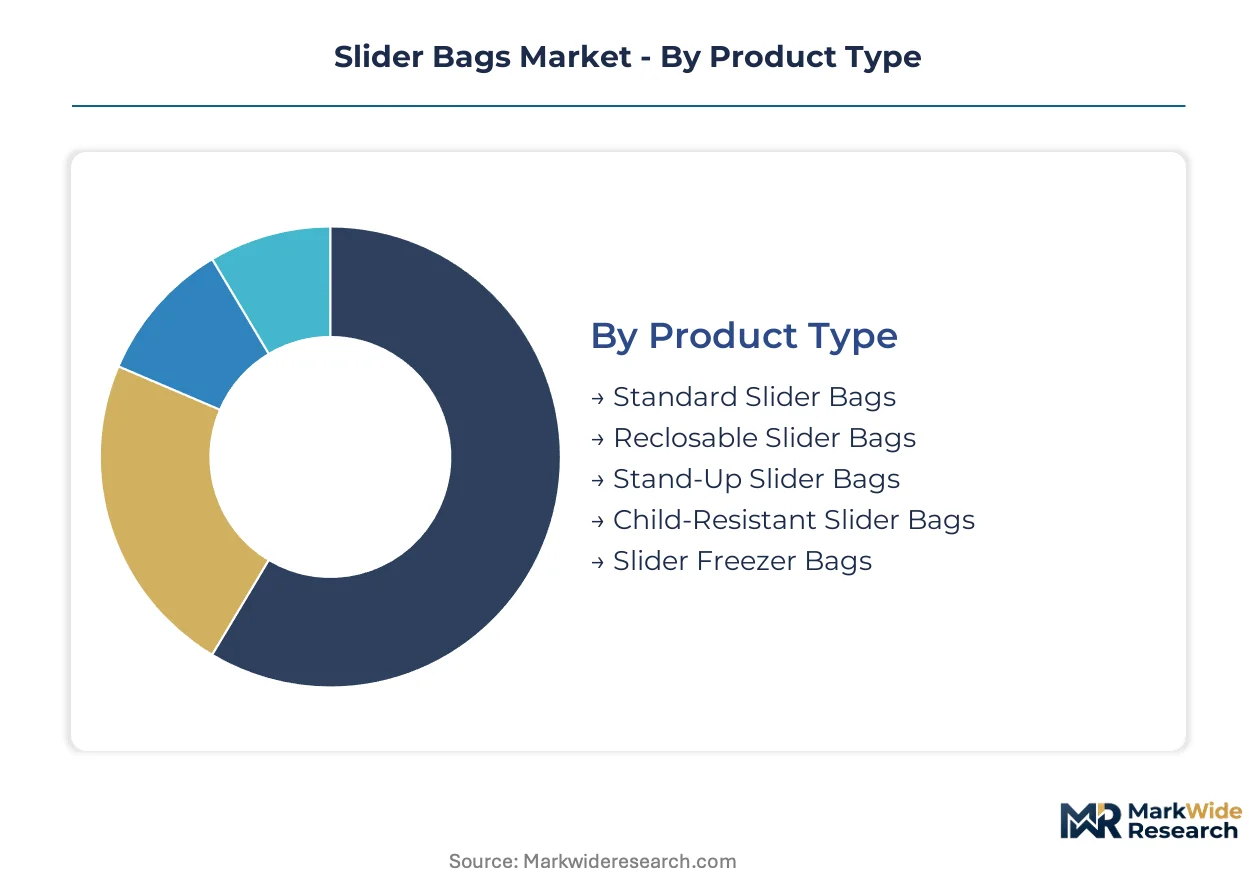
Slider bag segmentation reveals divergent margin profiles across product architectures and material specifications. Procurement patterns cluster around food-contact compliance tiers, while emerging pharmaceutical and sustainable formats command premium positioning.
Product Type:
Volume concentration favors universal kitchen formats, while premium mechanics target regulated storage applications.
- Reclosable Slider Bags:Interlocking track mechanisms bonded to LDPE or LLDPE sidewalls enable repeatable access without compromising moisture barrier integrity. Household pantry and meal-prep subscription services in the United States drive standardization of 1.5-3 mil thickness ranges across warehouse club channels.
- Child-Resistant Slider Bags:Specialized track geometries requiring dual-action or sequential force to open, engineered to USP 671 and comparable European pharmaceutical storage standards. Underpenetration in European prescription dispensing formats creates expansion opportunity as compliance mandates tighten.
- Standard Slider Bags:Basic single-track configurations for general-purpose storage with minimal barrier specifications.
- Stand-Up Slider Bags:Gusseted bottom structures with integrated slider closures for retail shelf presentation of bulk dry goods.
- Slider Freezer Bags:Thicker gauge constructions, typically 3-4 mil, with enhanced low-temperature flexibility additives for extended frozen storage.
Mature deployment sits with Reclosable Slider Bags. Newer deployment is concentrated in Child-Resistant Slider Bags.
Material:
Recycling-stream compatibility is displacing performance-optimized multi-substrate constructions.
- Multi-Layer Films:Coextruded oxygen-scavenging and moisture-barrier architectures, typically five to seven layers, achieving metalized laminate performance without microwave incompatibility. Food service providers across North American retail channels are specifying these formats for protein and produce applications.
- Biodegradable Plastic:Starch-based or PLA formulations engineered for industrial composting streams, constrained by moisture barrier limitations and FDA food-contact notification timelines. California and New York state-level mandates are accelerating procurement trials in institutional food service.
- Low-Density Polyethylene:Virgin and mechanically recycled grades for general-purpose slider applications with moderate barrier requirements.
- Linear Low-Density Polyethylene:Higher tensile strength resin for downgauged constructions maintaining puncture resistance.
- Polypropylene:Higher temperature tolerance for hot-fill or microwaveable applications with distinct sealing parameters.
Volume leadership remains with Low-Density Polyethylene. Steepest expansion trajectory belongs to Multi-Layer Films.
Application:
Food-contact specifications dominate procurement volumes, while pharmaceutical compliance creates specification premiums.
- Food Packaging:Primary driver of slider bag consumption spanning fresh produce, bulk meat, and prepared meal segments. United States warehouse club formats and direct-to-consumer meal platforms standardize reclosable specifications across 1.5-4 mil thickness ranges.
- Pharmaceutical Storage:Child-resistant and barrier-optimized formats governed by USP 671 moisture vapor transmission and oxygen ingress limits. European and Asian prescription dispensing channels show underpenetration relative to United States compliance storage adoption.
- Personal Care Products:Travel-size and sample formats for cosmetics and toiletries with moderate barrier requirements.
- Stationery Organization:Light-duty storage for office and craft supplies with minimal specification constraints.
- Hardware Component Storage:Puncture-resistant constructions for small parts and tool organization in retail and industrial channels.
Established penetration centers on Food Packaging. Emerging specification intensity concentrates in Pharmaceutical Storage.
End User:
Direct sourcing consolidation among large-format retailers is compressing converter margins while enabling custom specification.
- Food Service Providers:Institutional and commercial kitchens driving bulk-format procurement with standardized sizing requirements. Club-store volume concentration in the United States enables specification of custom melt-index ranges and additive packages.
- Healthcare Providers:Hospital systems and pharmacy chains requiring child-resistant and compliance-labeled storage formats. REACH restrictions on phthalate plasticizers are constraining additive portfolios for European export production.
- Consumer Goods Manufacturers:Private-label and branded product companies sourcing retail-ready packaging configurations.
- Educational Institutions:Institutional procurement of organizational and storage products for classroom and laboratory use.
- Electronics Assembler:Anti-static and moisture-barrier specifications for component protection in manufacturing environments.
Procurement scale concentrates with Food Service Providers. Regulatory specification complexity is expanding fastest among Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast ethane crackers supply the polyethylene feedstock that anchors North American slider bag production, while mechanical recycling infrastructure buildouts in Germany and California reshape procurement geography.
United States
Warehouse club formats and meal-prep subscription services drive bulk-format consumption across Texas and the Midwest. California's extended producer responsibility framework forces reformulation timelines for virgin plastic thresholds. Berry Global maintains blown film extrusion capacity in the Southeast to sustain margin control in food-grade applications.
Germany
REACH restrictions on phthalate plasticizers constrain additive portfolios for European export production. The EU Single-Use Plastics Directive mandates recycled content thresholds that pull converters toward certified post-consumer resin streams. Industrial clusters in North Rhine-Westphalia host coextrusion lines upgraded for seven-layer barrier structures.
China
Domestic demand for organizational and storage products expands through e-commerce distribution channels. The country's national standards body governs food-contact substance approvals with migration limits comparable to FDA frameworks. Manufacturing concentration in the Yangtze River Delta supplies cost-optimized formats for export markets.
Japan
Pharmaceutical storage compliance requirements drive premium positioning for child-resistant slider mechanisms. METI oversees industrial standards for flexible packaging applications with emphasis on microwave compatibility. The Kanto region around Tokyo anchors demand for high-barrier multi-layer films in prepared meal segments.
India
Institutional food service procurement expands through quick-service restaurant chains and centralized kitchen formats. FSSAI regulations govern food-contact approvals with notification timelines compressing product development windows. Manufacturing activity concentrates in Maharashtra and Gujarat for domestic supply and regional export.
Slider Bags Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biodegradable material certifications and pharmaceutical compliance niches. The market structures around three tiers: multinational resin-integrated converters, regional flexible packaging specialists, and private-label contract manufacturers. Two strategic archetypes dominate competitive positioning: backward-integrated players controlling blown film extrusion capacity, and brand-anchored competitors leveraging retail shelf presence. M&A activity concentrates on mechanical recycling assets, while capacity expansion targets seven-layer coextrusion lines for barrier-optimized formats.
Among North American resin-integrated converters, Berry Global exemplifies backward integration across blown film extrusion, while SC Johnson anchors brand equity through retail shelf presence in household channels. Reynolds Consumer Products occupies a position within value-tier positioning for club-store volume concentration. These three represent the dominant competitive archetypes: captive supply control, brand-driven premium positioning, and scale-optimized value tiering.
| Leading Market Players |
|---|
| SC Johnson (Ziploc) |
| Reynolds Consumer Products |
| Inteplast Group |
| Berry Global |
| C-P Flexible Packaging |
| International Plastics Inc. |
| Glad Products Company |
| Minigrip |
| Glenroy, Inc. |
| Others |
Cost & Logistics Intelligence
California's extended producer responsibility framework mandates virgin plastic thresholds that force converters toward certified post-consumer resin streams, compressing margin structures and elevating procurement costs for compliant slider bag production.
Pricing Analysis
Service bundling separates food-contact certification packages from basic resin supply, with FDA notification support and migration testing documentation commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, recycled-content verification, and barrier performance specifications. Cost compression in value-tier club-store channels is intensifying because direct sourcing consolidation among large-format retailers eliminates distributor markups. Food service providers exhibit highest price sensitivity due to standardized sizing requirements, while pharmaceutical compliance storage buyers prioritize certification assurance over unit economics.
Supply Chain Analysis
Gulf Coast freight corridors anchor polyethylene resin movement from Texas crackers to Southeast blown film extrusion facilities, with hurricane disruption patterns injecting volatility into feedstock delivery schedules. Raw material flows draw from ethane feedstock, LLDPE resin grades, and post-consumer recycled flake streams. Single-source vulnerability concentrates in mechanical recycling infrastructure for food-contact applications, where contamination thresholds cap compliant resin availability. Distribution runs through warehouse club formats, direct-to-consumer meal platforms, and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical recycling capacity scarcity for food-contact resin grades props pricing premiums, creating supply-constrained conditions that favor producers with verified post-consumer supply chains.
For Market Incumbents: Hedge resin price exposure through backward integration into Gulf Coast ethane feedstock or long-term offtake agreements with certified mechanical recyclers. Prioritize coextrusion line upgrades for seven-layer barrier structures to defend against oxygen-scavenging film displacement of metalized laminates. Channel control through direct retailer relationships protects specification lock-in against private-label contract manufacturers. For New Entrants and Emerging Players: E-commerce distribution channels enable bypass of club-store volume concentration that favors incumbent scale. Target pharmaceutical compliance storage in European prescription dispensing formats, where USP 671 and comparable national standards create specification premiums. Pursue biodegradable material certifications for institutional food service procurement trials accelerated by California and New York state-level mandates. For Investors and Strategic Acquirers: The window for entry favors mechanical recycling asset owners with food-contact approval pathways. Long-term viability hinges on pyrolysis-derived resin scale-up that bypasses mechanical contamination constraints. Monitor chemical recycling project announcements as inflection indicator for recycled-content supply chain validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive LLDPE supply insulates Berry Global from Gulf Coast ethane volatility. |
| Seven-Layer Coextrusion Capacity Expansion | Multi-layer film architectures displace metalized laminates in barrier-sensitive protein applications. |
| Pharmaceutical Compliance Certification | USP 671 validation opens underpenetrated European prescription dispensing channels. |
| Mechanical Recycling Asset Acquisition | Post-consumer resin streams satisfy California EPR recycled-content thresholds. |
| Direct-to-Consumer Platform Partnership | Meal-prep subscription services standardize reclosable formats across warehouse channels. |
Research Approach
Document review covered FDA food-contact substance regulations, EU REACH restriction filings, and state-level extended producer responsibility frameworks, complemented by interviews with blown film extrusion plant managers, procurement leads at food service providers, distribution channel partners, and technical R&D directors specializing in barrier film architectures. Secondary validation drew from customs and trade data, SEC 10-K filings of resin-integrated converters, and American Chemistry Council industry reports. Bottom-up volume modeling triangulated against top-down value estimates derived from retailer private-label specification databases.
Segment-level outputs across product type, material specification, application, and end-user channels were generated through the projection horizon. CAGRs were derived from regression analysis against historical resin price indices and regulatory mandate implementation timelines. Forecast inputs incorporated mechanical recycling infrastructure buildout schedules and sortation technology advancement curves.
The model holds under stable regulatory enforcement timelines and mechanical recycling contamination thresholds; deviation in pyrolysis-derived resin food-contact approval pathways or hurricane disruption frequency would shift supply elasticity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Freezing Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market