
 Alkaptonuria Drugs Market | 2026-2036
Alkaptonuria Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Alkaptonuria Drugs Market Outlook
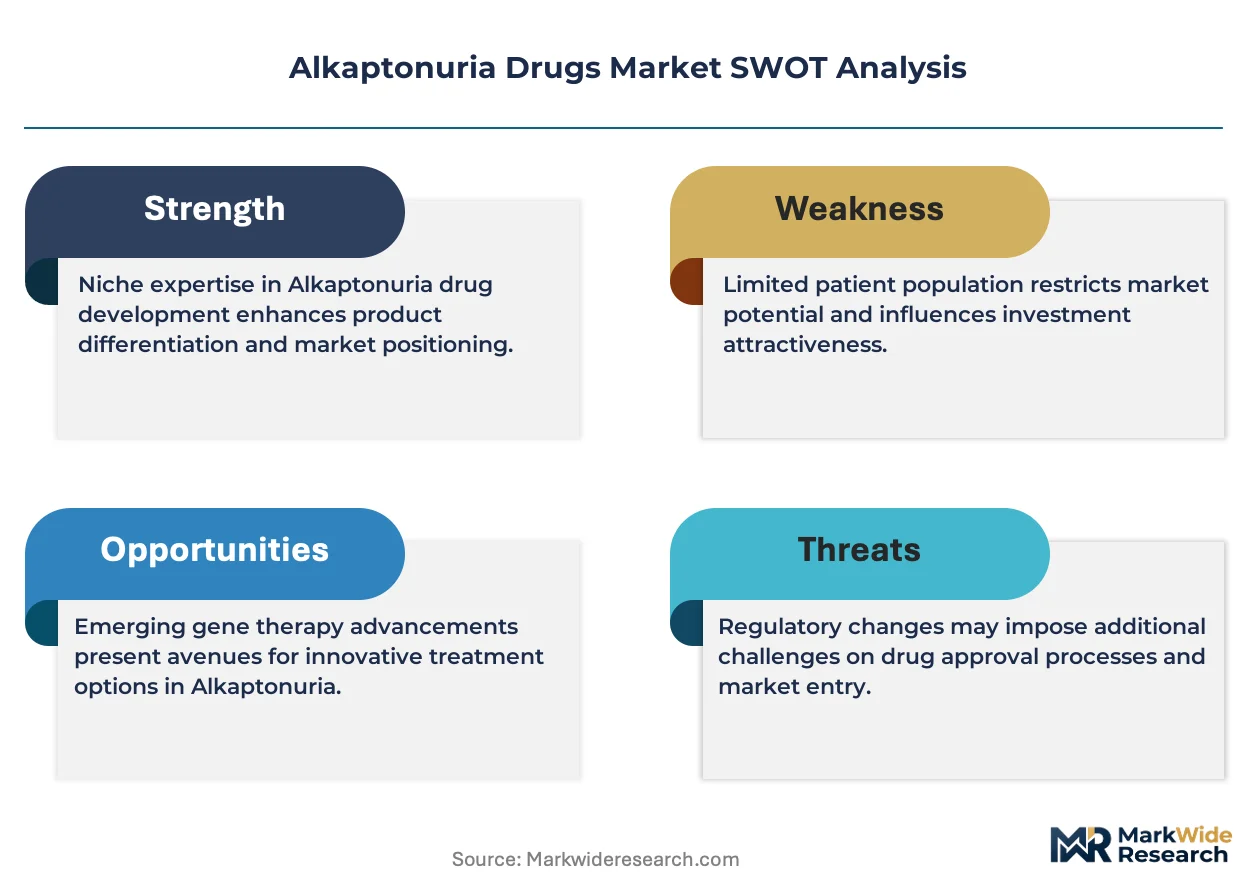
Nitisinone is realigning treatment economics as the standard-of-care substrate reduction therapy displaces older symptomatic management approaches in alkaptonuria protocols. Swedish Orphan Biovitrum AB leverages its rare disease commercial infrastructure to sustain European market presence. Alexion Pharmaceuticals Inc. anchors its portfolio through specialized metabolic disorder expertise. CYCLE Pharmaceuticals differentiates via focused formulation development for ultra-rare indications.
Alkaptonuria drugs comprise pharmaceutical agents targeting homogentisic acid oxidase deficiency, specifically nitisinone formulations that inhibit 4-hydroxyphenylpyruvate dioxygenase to reduce toxic metabolite accumulation and slow connective tissue ochronosis. The oral route of administration dominates current prescribing patterns due to patient convenience and outpatient management requirements. HGA-1 formulations occupy the leading position among drug types as first-line nitisinone therapy, while subcutaneous delivery systems represent the fastest-growing segment through innovations in sustained-release depot formulations. Genetic disorders classification within therapeutic area segmentation captures the majority of development investment given alkaptonuria's Mendelian inheritance pattern.
The FDA's Orphan Drug Designation framework and the EMA's Committee for Orphan Medicinal Products jointly shape clinical development incentives, with accelerated review pathways reducing time-to-market for qualifying therapies. Reimbursement authorities in Germany through the G-BA and Japan's MHLW determine national pricing and access conditions for ultra-rare disease treatments. Stakeholders must monitor evolving health technology assessment methodologies as payer scrutiny intensifies for high-cost chronic therapies in small patient populations.
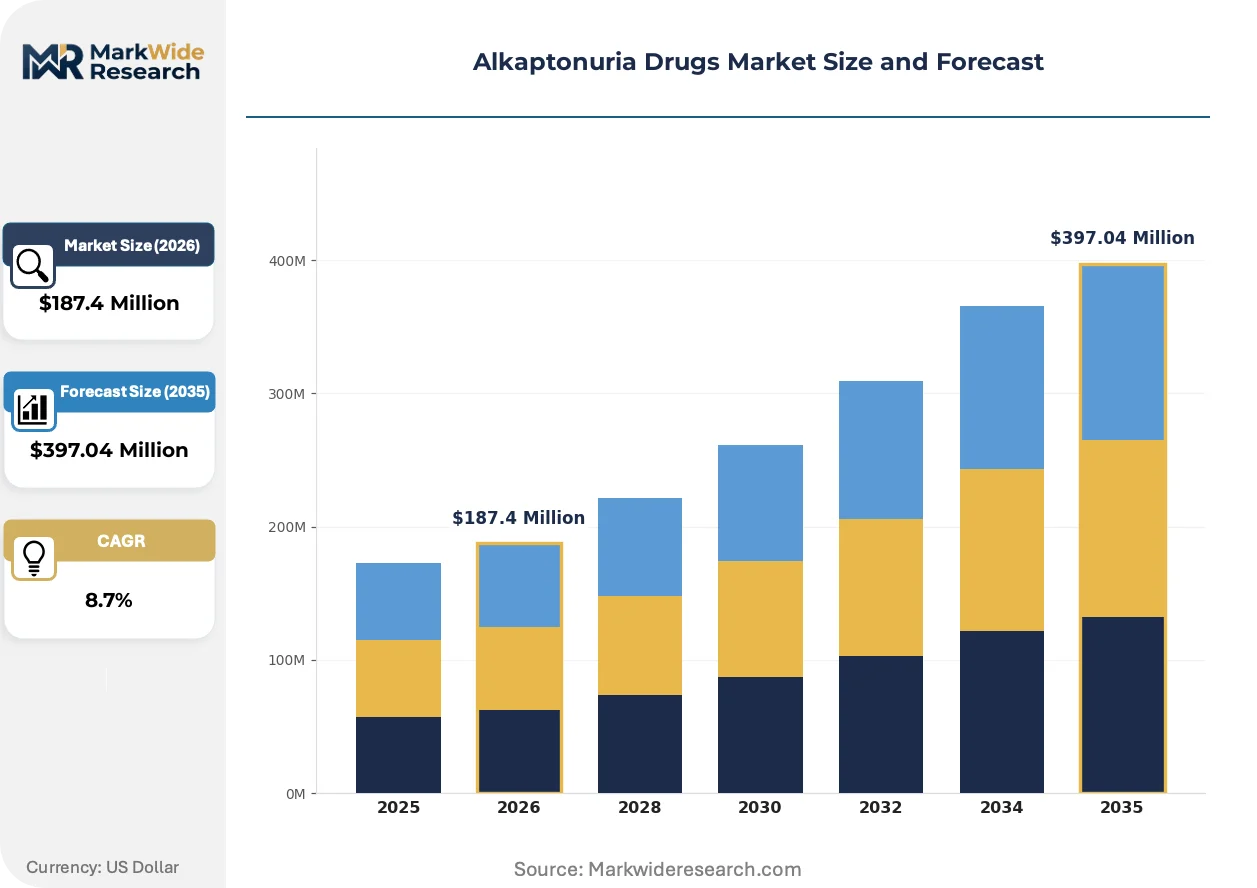
Market Dynamics
The FDA's Orphan Drug Designation framework is compressing clinical trial timelines and redirecting capital toward ultra-rare metabolic disorder therapeutics, fundamentally altering how developers prioritize alkaptonuria pipeline assets against larger indication opportunities.
Growth Catalysts
- EMA's Committee for Orphan Medicinal Products:Accelerated review pathways reduce regulatory burden for sponsors pursuing nitisinone formulations across European markets.
- Subcutaneous depot delivery systems:Sustained-release innovations extend dosing intervals and improve outpatient compliance for chronic homogentisic acid management.
- Japan's MHLW rare disease reimbursement protocols:National pricing guarantees for designated intractable diseases secure predictable revenue streams for enzyme replacement therapies.
Market Restraints
- Active pharmaceutical ingredient concentration:Single-source supply of 4-hydroxyphenylpyruvate dioxygenase inhibitors creates vulnerability for formulation sponsors.
- G-BA benefit assessment timelines:Germany's health technology appraisal process extends market access negotiations for ultra-rare therapies beyond standard pharmaceutical timelines.
- Diagnostic latency:Mean 10-year delay from symptom onset to alkaptonuria confirmation compresses addressable patient populations despite genetic screening availability.
Strategic Opportunities
- Pediatric formulation gaps:Liquid nitisinone preparations for juvenile patients remain undeveloped across major markets despite orphan drug incentives.
- Biomarker-guided dosing protocols:Homogentisic acid monitoring integration with therapeutic drug management creates service-layer revenue potential for specialty pharmacies.
- IRAs Medicare price negotiation exclusions:Orphan-designated small-molecule drugs maintain pricing autonomy under current US federal health program rules.
Industry Challenges
- Patient registry interoperability:Fragmented natural history data across national alkaptonuria databases complicates payer evidence generation for novel therapeutics.
- Specialized metabolic clinical trial infrastructure:Limited sites with ochronosis assessment expertise constrain enrollment velocity for pivotal studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkaptonuria Drugs Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: HGA-1, HGA-2, HGA-3, Others Route of Administration: Oral, Intravenous, Subcutaneous, Others Therapeutic Area: Metabolic Disorders, Genetic Disorders, Enzyme Deficiencies, Others Patient Type: Pediatric, Adult, Geriatric, Other |
| Companies Covered | Swedish Orphan Biovitrum AB, CYCLE Pharmaceuticals, Alexion Pharmaceuticals Inc., Pfizer Inc., GSK plc, Sanofi, Johnson & Johnson Services, Inc., Eton Pharmaceuticals, Mallinckrodt Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkaptonuria Drugs Market Strategic Shifts
Nitisinone therapy protocols are fragmenting across administration modalities and monitoring intensities as stakeholders seek differentiation in a concentrated competitive set. Three distinct vectors are reshaping development priorities and commercial positioning.
Depot formulation technology is modularizing chronic disease management for alkaptonuria patients. Subcutaneous implant systems now under clinical evaluation extend dosing intervals from daily oral administration to quarterly or semi-annual interventions. Specialty metabolic clinics in Germany and Japan are piloting these sustained-release platforms to reduce patient burden and improve therapeutic adherence in dispersed rare disease populations.
REACH chemical safety registrations are constraining excipient selection for oral nitisinone formulations. The European Chemicals Agency's authorization requirements for novel pharmaceutical ingredients are extending formulation development timelines by 18-24 months for sponsors seeking EU market entry. Manufacturers are responding by reverting to established excipient libraries or pursuing centralized procedure exemptions for ultra-rare disease indications.
Centralized specialty pharmacy distribution is displacing traditional hospital procurement for chronic alkaptonuria therapies. Hub-and-spoke models with integrated patient support services now capture majority volume in the United States as payers seek outcomes documentation and adherence guarantees. This channel consolidation is most pronounced in Medicare Part D and commercial managed care plans with rare disease carve-out arrangements.
Alkaptonuria Drugs Market Segmentation
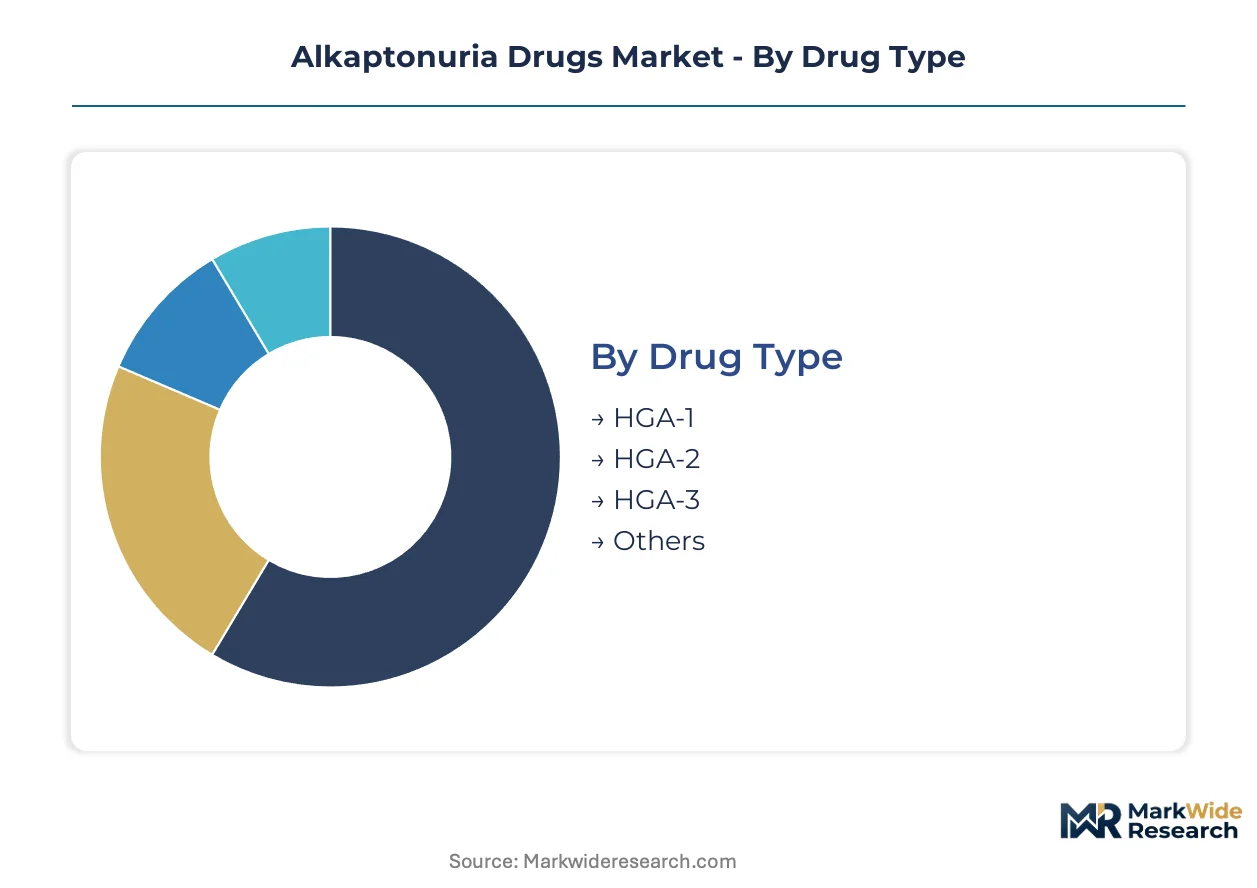
Alkaptonuria drug segmentation reveals how formulation specifications and patient characteristics determine prescribing economics. Each axis—molecular type, delivery mechanism, therapeutic classification, and age cohort—carries distinct reimbursement and development implications for sponsors targeting this ultra-rare metabolic disorder.
Drug Type:
Formulation chemistry distinguishes nitisinone variants by homogentisic acid suppression efficiency and regulatory approval status across FDA and EMA jurisdictions.
- HGA-1:First-generation nitisinone formulation with established bioavailability profiles. Demand concentrates in United States hospital systems where FDA orphan drug exclusivity supports premium reimbursement for substrate reduction therapy in confirmed alkaptonuria cases.
- HGA-2:Modified-release nitisinone with optimized pharmacokinetic parameters. German metabolic centers and Japan's designated intractable disease institutions are expanding procurement of this refined chemistry to reduce dosing frequency and improve ochronosis management adherence.
- HGA-3:Investigational formulation targeting pediatric populations with liquid suspension capabilities.
- Others:Emerging nitisinone analogs and combination therapies in preclinical development for homogentisic acid oxidase deficiency.
HGA-1 leads on scale; HGA-2 leads on momentum.
Route of Administration:
Delivery modality selection hinges on patient compliance requirements and the chronicity of alkaptonuria management across dispersed rare disease populations.
- Oral:Standard tablet and capsule formulations dominating current prescribing. Adult patients in Medicare Part D plans and European national health systems prefer this route for outpatient chronic therapy, though daily adherence remains problematic in progressive ochronosis cases.
- Subcutaneous:Depot injection systems and implantable sustained-release platforms. Specialty metabolic clinics in Germany and Japan are piloting quarterly dosing protocols to reduce patient burden in geographically dispersed populations with limited access to tertiary centers.
- Intravenous:Hospital-administered nitisinone for acute metabolic decompensation scenarios.
- Others:Transdermal patches and inhalation formulations in early feasibility studies for alkaptonuria drug delivery.
Oral formulations command current volume; subcutaneous delivery is gaining share fastest.
Therapeutic Area:
Clinical classification determines payer recognition and the availability of orphan drug incentives across national rare disease frameworks.
- Genetic Disorders:Mendelian inheritance classification capturing majority of development investment. United States and European sponsors prioritize this segment for FDA Orphan Drug Designation and EMA Committee for Orphan Medicinal Products accelerated review pathways.
- Metabolic Disorders:Biochemical pathway-focused positioning emphasizing homogentisic acid accumulation mechanisms. German G-BA benefit assessments and Japan's MHLW reimbursement protocols favor this classification for chronic disease management funding.
- Enzyme Deficiencies:Homogentisic acid oxidase deficiency framing for enzyme replacement therapy parallels.
- Others:Connective tissue disease and rheumatologic positioning for ochronosis symptom management.
Genetic Disorders classification anchors R&D spending; Metabolic Disorders drives reimbursement access.
Patient Type:
Age-stratified development addresses distinct compliance capabilities, disease progression stages, and dosing formulation requirements across the alkaptonuria patient journey.
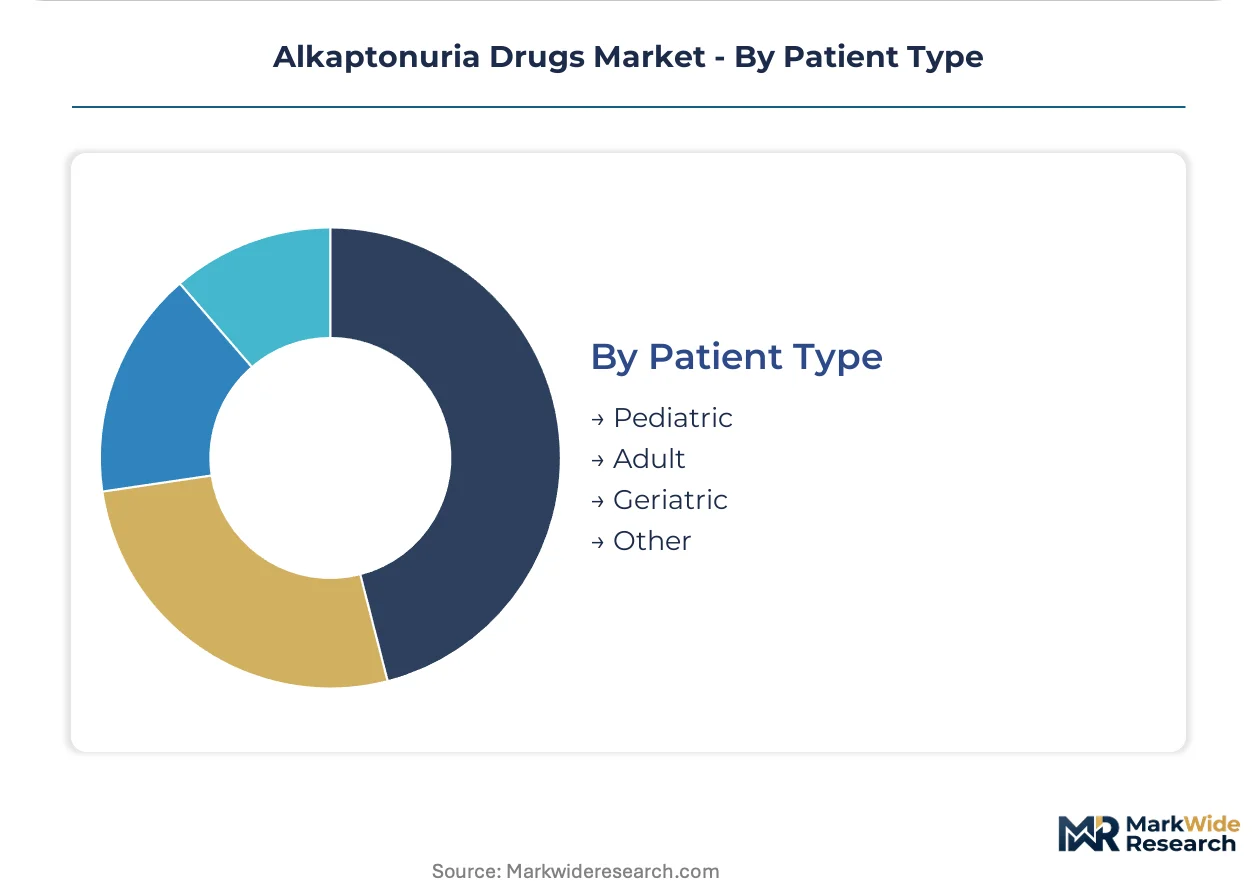
- Adult:Confirmed alkaptonuria patients with established ochronosis receiving chronic nitisinone therapy. United States specialty pharmacies and German metabolic centers concentrate procurement in this segment where diagnostic confirmation rates are highest and reimbursement pathways are clearest.
- Pediatric:Juvenile patients requiring liquid formulations and weight-based dosing protocols. Unmet need persists across all major markets despite orphan drug incentives, creating formulation development opportunities for sponsors addressing diagnostic latency in early-onset cases.
- Geriatric:Advanced ochronosis patients with multi-morbidity requiring dose-adjusted nitisinone.
- Other:Prenatal and neonatal screening-identified patients in preventive therapy protocols.
Adult patients dominate current treatment volume; Pediatric represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare disease treatment centers in Boston and the Research Triangle anchor pharmaceutical procurement for alkaptonuria therapeutics. National rare disease strategies in developed markets direct reimbursement toward enzyme replacement protocols. Diagnostic infrastructure and regulatory incentives determine patient access across major pharmaceutical markets.
United States
Medicare Part D carve-outs and commercial rare disease plans sustain nitisinone prescribing through specialty pharmacy networks. The FDA's Orphan Drug Designation program accelerates clinical trial timelines and secures pricing autonomy under IRA exclusions for designated small-molecule therapies. Boston's concentration of academic medical centers and metabolic disease specialists generates concentrated demand for substrate reduction therapies.
Germany
Metabolic centers in Munich and Heidelberg expand procurement of modified-release nitisinone formulations to reduce patient dosing burden. The G-BA conducts benefit assessments for ultra-rare disease therapies under Germany's national rare disease framework, though negotiation timelines extend beyond standard pharmaceutical market access windows. Bavaria's university hospital network pilots subcutaneous depot delivery systems for geographically dispersed patient populations.
Japan
Designated intractable disease status under MHLW protocols guarantees national pricing for chronic alkaptonuria management. Tokyo's National Center of Neurology and Psychiatry and Osaka's metabolic disease institutes concentrate pediatric and adult patient volumes. The country's genetic screening infrastructure reduces diagnostic latency compared to Western markets, expanding addressable patient pools for early intervention protocols.
United Kingdom
NHS England's specialized commissioning framework routes alkaptonuria patients through designated metabolic centers in London, Manchester, and Birmingham. NICE technology appraisals evaluate nitisinone cost-effectiveness against symptomatic management standards, with Scottish Medicines Consortium parallel assessments for NHS Scotland coverage. The country's patient registry infrastructure supports natural history data collection for payer evidence generation.
Switzerland
Swissmedic's accelerated review pathways for orphan-designated therapies align with the country's high per-capita spending on rare disease treatments. Basel's pharmaceutical cluster and Zurich's university hospital network concentrate metabolic disorder expertise and clinical trial participation. Cantonal reimbursement guarantees for ultra-rare conditions secure predictable access to chronic nitisinone therapy.
Alkaptonuria Drugs Market Competitive Environment
Global majors compete with regional champions across rare disease commercial infrastructure and metabolic disorder expertise. The market structure concentrates around established orphan drug developers with existing regulatory relationships and payer access pathways. Three archetypes dominate: large-cap diversified pharmaceutics with rare disease divisions, mid-cap metabolic specialists with focused portfolios, and emerging sponsors pursuing formulation differentiation. Competitive moves center on M&A to acquire orphan drug designations and strategic partnerships to access patient registries.
Within the metabolic specialist tier, Swedish Orphan Biovitrum AB exemplifies European rare disease commercial infrastructure, while Alexion Pharmaceuticals Inc. occupies a position among large-cap players with dedicated metabolic disorder expertise. CYCLE Pharmaceuticals represents the formulation-focused archetype targeting ultra-rare indications with specialized development capabilities.
| Leading Market Players |
|---|
| Swedish Orphan Biovitrum AB |
| CYCLE Pharmaceuticals |
| Alexion Pharmaceuticals Inc. |
| Pfizer Inc. |
| GSK plc |
| Sanofi |
| Johnson & Johnson Services, Inc. |
| Eton Pharmaceuticals |
| Mallinckrodt Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Specialty pharmacy consolidation in the United States is forcing formulation sponsors to absorb hub-and-spoke distribution costs while maintaining orphan drug premium positioning, compressing net margins and accelerating backward integration into active pharmaceutical ingredient sourcing.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through dominates nitisinone economics as single-source 4-hydroxyphenylpyruvate dioxygenase inhibitor supply constrains formulation sponsors. Three-tier pricing structure across premium orphan-designated, standard authorized generic, and economy investigational tiers reflects FDA exclusivity status and G-BA benefit assessment outcomes. Pricing pressure stems from Medicare Part D rebate obligations and European health technology appraisal reference pricing. Pediatric liquid formulations show highest price sensitivity due to uncompensated development costs; adult oral tablets in Japanese designated intractable disease protocols demonstrate lowest sensitivity with guaranteed national pricing.
Supply Chain Analysis
Specialized metabolic biochemist scarcity in Basel, Boston, and Tokyo constrains quality control capacity for nitisinone synthesis and release testing. Active pharmaceutical ingredient manufacturing concentrates in Switzerland, the United States, and Japan; excipient sourcing draws from established European and North American chemical libraries to circumvent REACH authorization delays. Single-source dependency for homogentisic acid reference standards creates vulnerability for batch release protocols. Distribution runs through centralized specialty pharmacy hubs with integrated patient support services rather than traditional hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkaptonuria drug economics favor margin expansion through subcutaneous depot formulation premiums and pediatric indication extensions that command orphan drug pricing autonomy under IRA exclusions.
For Market Incumbents: Acquire pediatric formulation development capabilities to preempt liquid nitisinone gaps before diagnostic latency reductions expand addressable juvenile populations. Secure exclusive supply agreements for 4-hydroxyphenylpyruvate dioxygenase inhibitor active pharmaceutical ingredients to defend against single-source disruption threats. Invest in biomarker-guided dosing protocol infrastructure to create service-layer revenue streams that offset pricing pressure from Medicare Part D rebate obligations. For New Entrants and Emerging Players: Specialty metabolic clinic partnerships in Germany and Japan offer the most penetrable access point for depot delivery system pilots in geographically dispersed rare disease populations. Target adult patients with established ochronosis in Bavaria's university hospital network where G-BA benefit assessments have already validated substrate reduction therapy reimbursement. Pursue liquid formulation development for juvenile patients as a differentiated go-to-market angle against incumbent oral tablet dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with formulation-focused sponsors possessing REACH-compliant excipient libraries and subcutaneous sustained-release platform expertise. Five-to-ten year viability hinges on successful pediatric indication expansion and diagnostic latency reduction through newborn screening program adoption. Watch for homogentisic acid monitoring integration with therapeutic drug management services as the inflection signal for specialty pharmacy value capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | Liquid nitisinone suspensions address unmet need in juvenile alkaptonuria patients across FDA and EMA jurisdictions. |
| Subcutaneous Depot Scale-Up | Quarterly dosing platforms reduce patient burden in German and Japanese dispersed rare disease populations. |
| Biomarker-Guided Dosing Integration | Homogentisic acid monitoring creates service-layer revenue for specialty pharmacy hub-and-spoke networks. |
| REACH Excipient Compliance | Established chemical libraries circumvent ECHA authorization delays extending EU market entry timelines. |
| Orphan Drug Designation Maintenance | IRA small-molecule exclusions preserve pricing autonomy for designated therapies in Medicare Part D plans. |
Study Parameters
Bottom-up patient population modeling reconciled against top-down nitisinone procurement tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists informed demand-side assumptions. Secondary validation drew from FDA orphan drug designations, EMA Committee for Orphan Medicinal Products submissions, ClinicalTrials.gov protocols, and national alkaptonuria patient registries. Triangulation across these sources established baseline prevalence estimates and treatment penetration rates.
Historical trendline analysis of nitisinone approval pathways and reimbursement decisions anchored the forecast framework. Segmentation dimensions modeled encompass drug type, route of administration, therapeutic classification, and patient age cohort across regional regulatory clusters. CAGRs were derived from elasticity-adjusted pricing trajectories and patient pool expansion assumptions. Forecast inputs incorporated G-BA benefit assessment timelines, MHLW designated intractable disease pricing guarantees, and specialty pharmacy channel migration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to diagnostic latency reduction through newborn screening adoption and REACH chemical authorization timeline shifts. Material deviation in FDA orphan drug exclusivity interpretations or IRA small-molecule negotiation rule changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Mycoses Treatment Market