
 Bisphosphonates Market | 2026-2036
Bisphosphonates Market Size, Share, and Industry Trends Forecast 2026-2036
Bisphosphonates Market Analysis
Osteoporosis therapy is pivoting toward outpatient and homecare administration as payers push for reduced hospitalization costs. Merck & Co Inc leverages its long-standing alendronate franchise to sustain volume leadership in oral segments. Novartis AG anchors its position through zoledronic acid infusion networks in oncology-linked bone metastasis care. Teva Pharmaceutical Industries Ltd competes aggressively in the generic alendronate space, squeezing price points across mature markets.
Bisphosphonates constitute a class of synthetic pyrophosphate analogs that bind hydroxyapatite crystals in bone mineral matrix, inhibiting osteoclast-mediated resorption through farnesyl diphosphate synthase enzyme suppression; they primarily serve to reduce fracture risk in metabolic bone disorders and skeletal-related events in malignant disease. Oral alendronate and risedronate still occupy the largest revenue share due to decades of clinical familiarity and payer preference for self-administered chronic therapy. Intravenous zoledronic acid generates the fastest growth in oncology-integrated care settings where infusion compliance can be monitored. The homecare end-user channel is expanding fastest structurally, though hospital procurement retains the deepest margin pools through bundled oncology contracts.
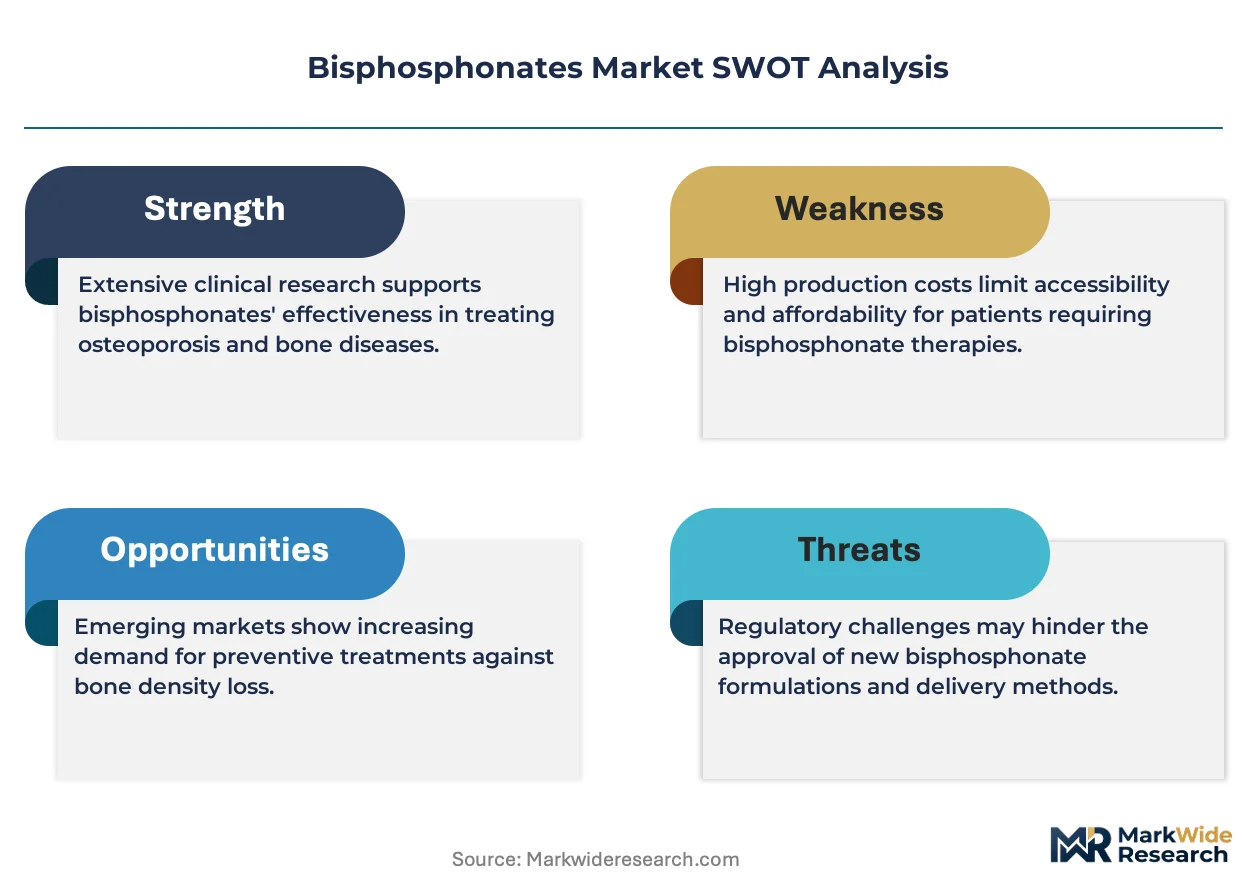
The FDA oversees New Drug Application pathways and post-market surveillance for bisphosphonate-related osteonecrosis of the jaw, while the EMA's Pharmacovigilance Risk Assessment Committee mandates periodic safety update reporting across European markets. These frameworks elevate manufacturing documentation burdens and lengthen approval cycles for reformulated delivery systems. Stakeholders must monitor evolving pharmacovigilance signal detection requirements that could trigger class-label restrictions or demand additional clinical outcomes data.
Market Dynamics
The FDA's post-market surveillance mandates for osteonecrosis of the jaw have lengthened approval cycles for reformulated bisphosphonate delivery systems, compressing development timelines and elevating pharmacovigilance documentation burdens across all manufacturers.
Growth Catalysts
- Medicare preventive skeletal care coverage:The United States reimbursement framework favors bone-density screening and chronic osteoporosis therapy, expanding prescription volumes for oral formulations in geriatric populations.
- Oncology-integrated infusion networks:Hospital outpatient departments are building dedicated zoledronic acid administration protocols for skeletal-related event prevention in metastatic cancer patients.
- Homecare administration protocols:Payer pressure to reduce hospitalization costs is accelerating training programs for self-injection and oral regimen compliance monitoring outside clinical settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of nitrogen-containing bisphosphonates depends on a limited supplier base in India and China, creating vulnerability to geopolitical trade disruptions.
- Denosumab substitution pressure:The RANK ligand inhibitor offers comparable fracture risk reduction with different administration schedules, capturing therapy-naive patients in rheumatology practices.
- EMA Pharmacovigilance Risk Assessment Committee mandates:Periodic safety update reporting requirements across European markets impose recurring compliance costs that disproportionately burden mid-scale generic manufacturers.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Diagnostic infrastructure gaps have suppressed osteoporosis recognition, creating first-mover advantage for portable bone mineral density screening paired with oral therapy education.
- Biologic-bisphosphonate combination protocols:Convergence of monoclonal antibody therapy with antiresorptive agents is opening oncology trial design for simultaneous skeletal protection and tumor suppression.
- Specialty pharmacy distribution channels:Direct-to-patient shipment models with embedded adherence monitoring are capturing margin pools previously held by hospital outpatient departments.
Industry Challenges
- Pharmacovigilance signal detection expertise:Rare event monitoring for atypical femoral fracture requires specialized biostatistical capabilities that smaller manufacturers struggle to staff.
- Legacy manufacturing line retrofitting:Containment upgrades for highly potent bisphosphonate powder handling demand capital deployment that strains depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bisphosphonates Market |
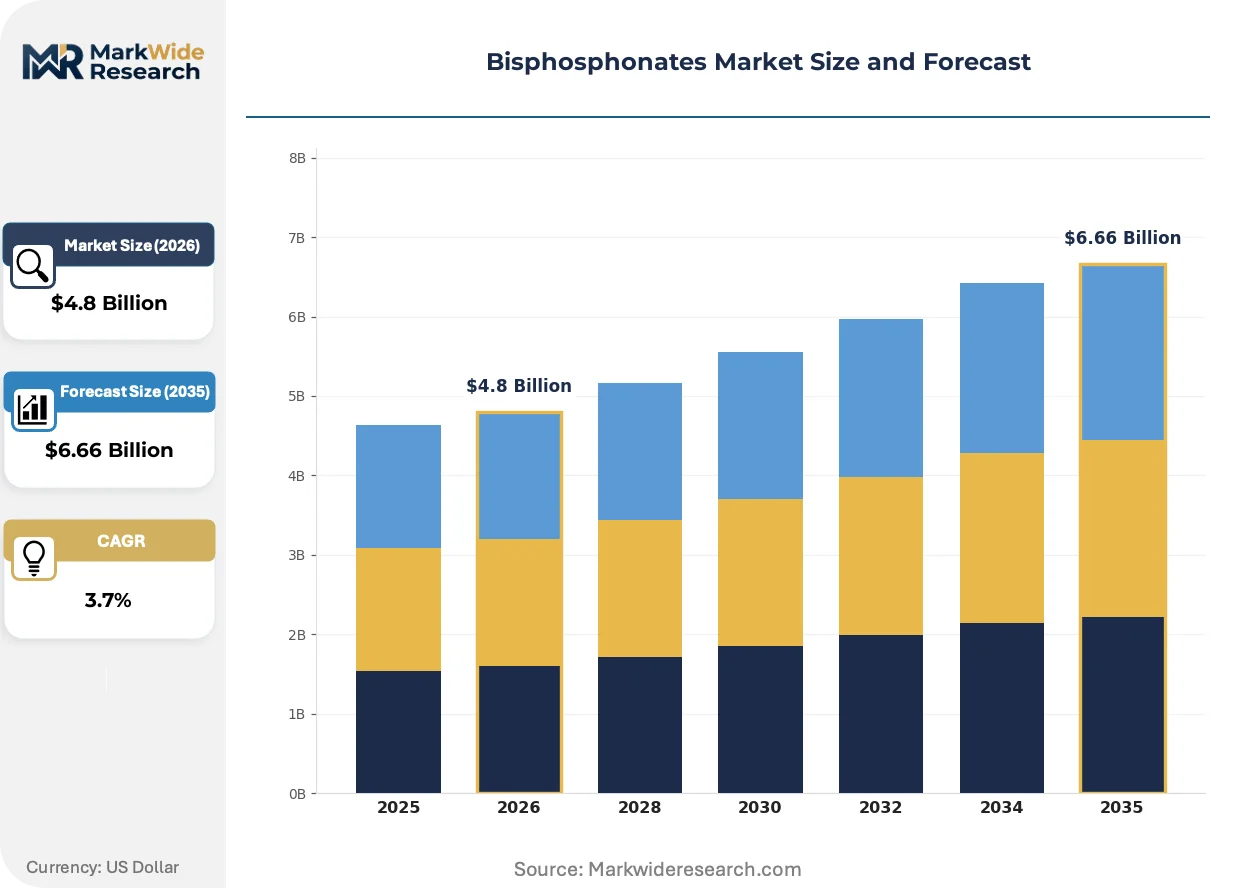
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alendronate, Risedronate, Ibandronate, Zoledronic Acid Therapy Area: Osteoporosis, Paget's Disease, Bone Metastasis, Hypercalcemia Administration Route: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Merck & Co Inc, Novartis AG, Amgen Inc, Pfizer Inc, Teva Pharmaceutical Industries Ltd, F. Hoffmann-La Roche Ltd, Sanofi, UCB Pharma, Aspen Pharmacare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bisphosphonates Market Emerging Trajectories
Formulation science and administration convenience are converging to reshape competitive positioning, with manufacturers racing to reduce dosing frequency while maintaining bioequivalence standards.
Extended-release injectable depot formulations are unifying sustained drug release kinetics with reduced clinic visit requirements. Oncology networks in Germany and Japan are piloting quarterly administration protocols. This technology is unifying patient convenience demands with bundled payment structures that penalize frequent infusion center utilization.
The EMA's tightened requirements for generic bisphosphonate bioequivalence studies now mandate additional pharmacokinetic sampling windows. European manufacturers have responded by consolidating contract research organization relationships to streamline study execution. Smaller generic entrants face exclusion from the region's tender processes due to documentation gaps.
Hospital procurement committees are consolidating vendor lists to capture volume discounts on intravenous formulations. Specialty distributors with cold-chain capabilities are displacing traditional wholesale relationships in oncology-integrated care settings. This concentration is most visible in United States Medicare Advantage networks where pharmacy benefit managers enforce preferred product tiers.
Bisphosphonates Market Segmentation
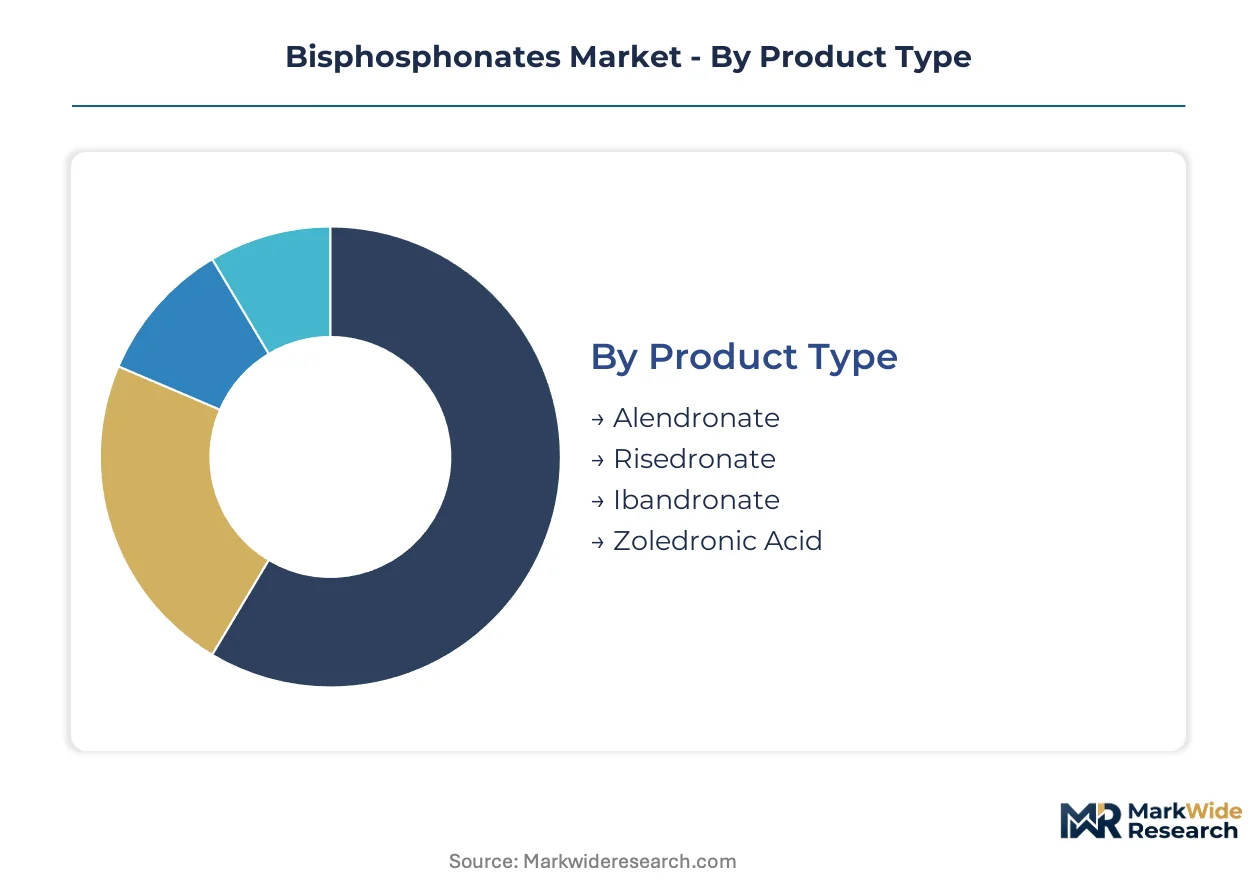
Bisphosphonate therapy selection hinges on bone metabolism kinetics, patient compliance capacity, and reimbursement pathway design. Each segmentation dimension carries distinct margin profiles and regulatory documentation burdens that reshape competitive positioning across therapeutic contexts.
Product Type:
Standardization dominates nitrogen-containing bisphosphonates, while potency variations and infusion requirements create customization tiers for hospital formularies.
- Alendronate:The first-generation amino-bisphosphonate offers weekly oral dosing with established bioequivalence pathways for generic substitution. Demand concentrates in United States Medicare Advantage networks where prior authorization protocols favor self-administered chronic osteoporosis therapy over infusion alternatives.
- Zoledronic Acid:This third-generation nitrogen-bisphosphonate delivers the highest potency with annual infusion schedules, binding hydroxyapatite with exceptional affinity. Oncology-integrated care settings in Germany and Japan favor quarterly administration protocols for skeletal-related event prevention in metastatic breast and prostate cancer patients.
- Risedronate:Monthly oral and annual intravenous formulations bridge convenience and efficacy for patients with esophageal intolerance to alendronate.
- Ibandronate:Monthly oral and quarterly intravenous options target postmenopausal osteoporosis with flexible administration pathways.
Most installed capacity flows through alendronate. Expansion is steepest in zoledronic acid infusion networks.
Therapy Area:
Volume scales inversely with reimbursement complexity across this category, with preventive metabolic bone disorders outpacing acute oncologic indications in prescription frequency.
- Osteoporosis:Primary prevention of fragility fractures in postmenopausal women and elderly men constitutes the largest addressable population. United States bone health guidelines from the National Osteoporosis Foundation drive screening rates and first-line bisphosphonate initiation in primary care settings.
- Bone Metastasis:Skeletal-related event prevention in solid tumor malignancies commands premium pricing through bundled oncology contracts. Hospital outpatient departments in the United Kingdom and France capture deep margin pools through zoledronic acid procurement tied to chemotherapy administration protocols.
- Paget's Disease:Deformed bone remodeling in older adults requires intermittent high-dose bisphosphonate courses with radiographic monitoring.
- Hypercalcemia:Acute malignancy-associated calcium elevation demands rapid-acting intravenous intervention in inpatient settings.
Prescription volume concentrates in osteoporosis. Revenue intensity peaks in bone metastasis care.
Administration Route:
Patient autonomy preferences and payer cost-containment pressures are redistributing volume from infusion centers toward self-administered alternatives.
- Oral:First-pass hepatic metabolism and strict fasting requirements constrain bioavailability, yet decades of clinical familiarity sustain dominance in chronic osteoporosis management. Medicare reimbursement policies in the United States favor oral alendronate as the default first-line therapy for treatment-naive geriatric patients.
- Intravenous:Direct vascular delivery bypasses gastrointestinal tolerability issues while enabling precise dosing in oncology contexts. Infusion networks in Japan and Australia are piloting extended-release depot formulations to reduce clinic visit frequency under bundled payment structures.
- Subcutaneous:Emerging auto-injector platforms target homecare administration with reduced nursing supervision requirements.
- Transdermal:Novel permeation-enhanced patches remain investigational, seeking to overcome bisphosphonate hydrophilicity barriers for dermal absorption.
Oral formulations retain the deepest prescription volume. Intravenous routes are gaining share fastest in oncology-integrated settings.
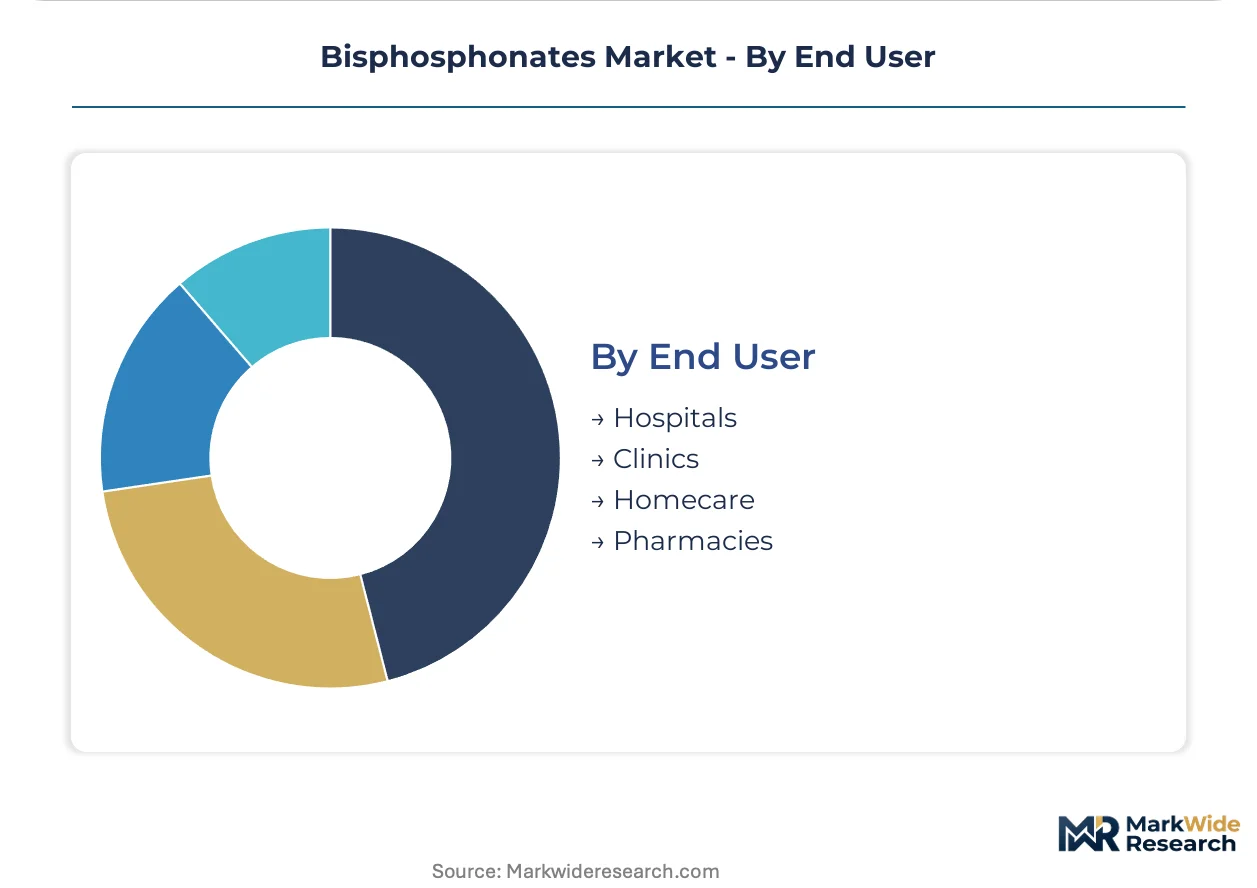
End User:
Procurement authority and margin capture diverge sharply between institutional purchasers and direct-to-patient channels.
- Hospitals:Bundled oncology contracts and 340B drug pricing programs concentrate purchasing power for intravenous formulations. United States health systems with captive specialty pharmacies are integrating zoledronic acid procurement with chemotherapy benefit management.
- Homecare:Payer pressure to reduce hospitalization costs is accelerating training programs for self-injection and oral regimen compliance monitoring outside clinical settings. Remote adherence tracking platforms in the Netherlands and Sweden are embedding bisphosphonate therapy within digital chronic disease management workflows.
- Clinics:Rheumatology and endocrinology practices serve as gatekeepers for therapy initiation and monitoring.
- Pharmacies:Retail and specialty dispensing channels capture oral formulation distribution with embedded prior authorization support.
Hospital procurement retains the highest revenue per patient encounter. Homecare channels are expanding most quickly structurally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting active pharmaceutical ingredient production toward jurisdictions with streamlined environmental permitting and lower pharmacovigilance compliance costs. Manufacturers are relocating nitrogen-bisphosphonate synthesis operations to exploit these cost-of-compliance gaps while maintaining EMA and FDA market access through qualified importer arrangements.
United States
Medicare Advantage networks drive oral alendronate volumes through prior authorization protocols favoring self-administered osteoporosis therapy. The FDA's post-market surveillance mandates for osteonecrosis of the jaw lengthen approval cycles for reformulated delivery systems. Hospital procurement committees in Texas and Florida health systems are consolidating vendor lists to capture volume discounts on intravenous zoledronic acid.
Germany
Oncology-integrated care settings favor quarterly zoledronic acid administration protocols for skeletal-related event prevention in metastatic cancer patients. The EMA's Pharmacovigilance Risk Assessment Committee mandates periodic safety update reporting that elevates documentation burdens for generic manufacturers. The Rhine-Ruhr pharmaceutical cluster hosts specialized containment facilities for highly potent bisphosphonate powder handling.
Japan
Aging demographics expand the addressable population for fracture prevention therapies in postmenopausal women and elderly men. PMDA guidelines on generic bioequivalence studies for bisphosphonates require additional pharmacokinetic sampling windows. The Kanto region around Tokyo anchors infusion network pilot programs for extended-release depot formulations reducing clinic visit frequency.
India
Domestic API synthesis capabilities for nitrogen-containing bisphosphonates concentrate in Gujarat and Maharashtra contract manufacturing facilities. CDSCO streamlined approval pathways for reformulated oral generics are accelerating product registration timelines. Hyderabad-based research organizations are developing pharmacovigilance signal detection capabilities to support export market compliance.
China
Hospital outpatient departments are building dedicated zoledronic acid administration protocols as oncology infrastructure expands in tier-one cities. NMPA tightened requirements for generic bioequivalence documentation are consolidating contract research organization relationships. The Yangtze River Delta pharmaceutical manufacturing corridor is retrofitting legacy lines for containment upgrades handling highly potent bisphosphonate compounds.
Bisphosphonates Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to share pharmacovigilance infrastructure and API synthesis capabilities. The vendor base clusters around three tiers: originators with established infusion networks, mid-scale generic houses with regional tender expertise, and contract manufacturers supplying active pharmaceutical ingredients. Two strategic archetypes prevail—vertically integrated pharmaceutical conglomerates controlling API-to-finished-dose supply chains, and specialty distributors with cold-chain capabilities displacing traditional wholesale relationships. Portfolio diversification into extended-release formulations and geographic expansion through qualified importer arrangements represent the dominant competitive moves.
Within the originator tier, Merck & Co Inc and Novartis AG exemplify divergent strategic positions—one leveraging decades of oral formulation familiarity, the other anchoring oncology-integrated infusion networks. Teva Pharmaceutical Industries Ltd occupies a position within the aggressive generic substitution segment, squeezing price points across mature markets where bioequivalence pathways are well-established. These three entities represent the spectrum from patented franchise defense to commoditized volume capture.
| Leading Market Players |
|---|
| Merck & Co Inc |
| Novartis AG |
| Amgen Inc |
| Pfizer Inc |
| Teva Pharmaceutical Industries Ltd |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| UCB Pharma |
| Aspen Pharmacare |
| Others |
Supply Flow & Price Mechanics
EMA containment facility certification gates qualified supply for nitrogen-bisphosphonate API synthesis, separating premium-tier manufacturers with validated containment infrastructure from economy-tier competitors facing exclusion from European tender processes. This environmental-safety mandate directly determines pricing power, as certified facilities command 15-20% contract premiums while uncertified producers absorb steep compliance retrofit costs or exit the market entirely.
Pricing Analysis
Distributor margin compression in oral alendronate channels is intensifying as Teva Pharmaceutical Industries Ltd and mid-scale generic houses squeeze price points through direct-to-pharmacy arrangements. Three-tier pricing structure across premium infusion networks, standard hospital procurement, and economy oral generics reflects FDA bioequivalence tiering and cold-chain capability differentiation. Pricing pressure stems from denosumab substitution in rheumatology practices, with Medicare Advantage networks showing highest price sensitivity due to prior authorization protocols favoring self-administered alternatives.
Supply Chain Analysis
Regional distribution centers in Gujarat and Maharashtra anchor hub-and-spoke patterns for nitrogen-containing bisphosphonate API movement to formulation facilities in Germany, Japan, and the United States. Active pharmaceutical ingredient synthesis draws from phosphorus trichloride and phosphorous acid feedstocks concentrated in Chinese and Indian chemical corridors. Single-source vulnerability characterizes zoledronic acid precursor supply, with geopolitical trade disruptions threatening oncology infusion network continuity. Distribution runs through specialty pharmaceutical wholesalers with cold-chain credentials, displacing traditional wholesale relationships in Medicare Advantage and bundled oncology contract segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bisphosphonate therapy rests on homecare channel penetration and extended-release formulation premiums, with cost-down drivers from API synthesis automation and pharmacovigilance infrastructure sharing offsetting EMA documentation burdens.
For Market Incumbents: Anticipate denosumab biosimilar entry by reinforcing zoledronic acid infusion network lock-in through bundled oncology contracts with hospital outpatient departments. Prioritize backward integration into nitrogen-bisphosphonate API synthesis through Gujarat and Maharashtra facility partnerships, securing qualified supply status under tightening EMA containment mandates while generic competitors face capital-strained retrofit timelines.
For New Entrants and Emerging Players: The mid-tier pricing gap between Novartis AG's premium infusion networks and Teva Pharmaceutical Industries Ltd's commoditized oral generics offers white-space entry through sub-Saharan Africa diagnostic infrastructure partnerships and portable bone mineral density screening platforms. Target South Africa and Nigeria osteoporosis recognition gaps with oral alendronate education programs, leveraging CDSCO streamlined approval pathways for reformulated generics to compress registration timelines versus FDA and EMA routes.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale generic houses with EMA bioequivalence study capabilities because consolidation concentrates pharmacovigilance infrastructure costs across portfolios while preserving regional tender access. Long-term viability favors targets with validated containment facilities and existing hospital procurement relationships, with inflection signal tied to FDA osteonecrosis of the jaw signal detection outcomes that could trigger class-label restrictions reshaping competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Depot Formulation Development | Quarterly administration protocols in Germany and Japan reduce clinic visit frequency under bundled payment structures. |
| EMA Containment Facility Certification | Validated infrastructure separates premium-tier manufacturers from economy competitors facing European tender exclusion. |
| Sub-Saharan Africa Diagnostic Partnership | Portable bone mineral density screening in South Africa and Nigeria creates first-mover advantage in underpenetrated markets. |
| Specialty Pharmacy Distribution Channel Expansion | Direct-to-patient shipment models with embedded adherence monitoring capture margin pools from hospital outpatient departments. |
| Pharmacovigilance Infrastructure Sharing | Mid-scale generic houses consolidate rare event monitoring capabilities to satisfy FDA and EMA signal detection mandates. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market's regulatory and commercial stakeholders. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative grounding through structured interviews. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Rate-of-change decomposition structured the analytical framework, with CAGRs derived from therapy line evolution, dosage form shifts, administration route migration, patient population aging dynamics, and regional regulatory cluster differentiation across the projection horizon. Segmentation dimensions modeled included product type potency tier, therapy area reimbursement complexity, end-user channel margin capture, and geographic API synthesis concentration. Oncology-integrated infusion network expansion rates and homecare protocol adoption curves served as industry-specific forecast inputs.
Caveats apply where FDA osteonecrosis of the jaw signal detection outcomes, EMA Pharmacovigilance Risk Assessment Committee mandate expansions, or India-China API trade disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Europe Laxative Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Global Psychotropic Drugs Market