
 High-Purity Nitrogen Market | 2026-2036
High-Purity Nitrogen Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Nitrogen Market Analytics
Buyer concentration among semiconductor foundries is restructuring procurement patterns across the high-purity nitrogen value chain. Linde plc leverages its on-site generation infrastructure to anchor long-term supply agreements with leading chipmakers. Air Liquide sustains competitive positioning through cryogenic technology leadership and regional production density in Asian manufacturing hubs. Air Products and Chemicals, Inc. specializes in ultra-high-purity gas purification systems that meet sub-part-per-billion contamination thresholds for advanced lithography processes.
High-purity nitrogen denotes gaseous or liquid nitrogen refined to contaminant levels below one part per million, typically produced via cryogenic air separation or pressure swing adsorption followed by catalytic deoxygenation and molecular sieve drying. Its primary industrial purpose is to create oxygen-free environments for oxidation-sensitive processes in electronics manufacturing, pharmaceutical packaging, and chemical synthesis. Gaseous nitrogen dominates volume consumption in semiconductor fabrication, where continuous inerting of deposition and etch chambers commands premium pricing and technical service bundling. Liquid nitrogen retains structural importance in healthcare cryopreservation and food freezing tunnels, though growth rates in these segments trail electronics applications. The distribution channel dimension reveals wholesale and direct sales networks capturing the bulk of value, with distributor relationships concentrated in regions lacking integrated gas company infrastructure.
FDA regulations governing pharmaceutical aseptic processing and EPA emissions standards for chemical manufacturing shape product purity certifications and handling protocols in the United States. ECHA REACH requirements and EU F-Gas Regulation compliance in Europe mandate detailed traceability for gas supply chains and restrict certain fluorinated alternatives that nitrogen displaces. Stakeholders must monitor evolving semiconductor node transitions and corresponding purity specification escalations to align capacity investments with buyer technical roadmaps.
Market Dynamics
Semiconductor node transitions below 3nm are tightening contamination thresholds and forcing gas suppliers to recalibrate purification infrastructure ahead of buyer roadmaps. This technical escalation concentrates procurement power among foundries with captive on-site generation, restructuring contract terms and service bundling across the value chain.
Growth Catalysts
- Advanced Lithography Expansion:Sub-5nm chip production in Taiwan and South Korea requires continuous high-volume nitrogen inerting for EUV scanner environments, pulling demand from merchant supply toward integrated on-site systems.
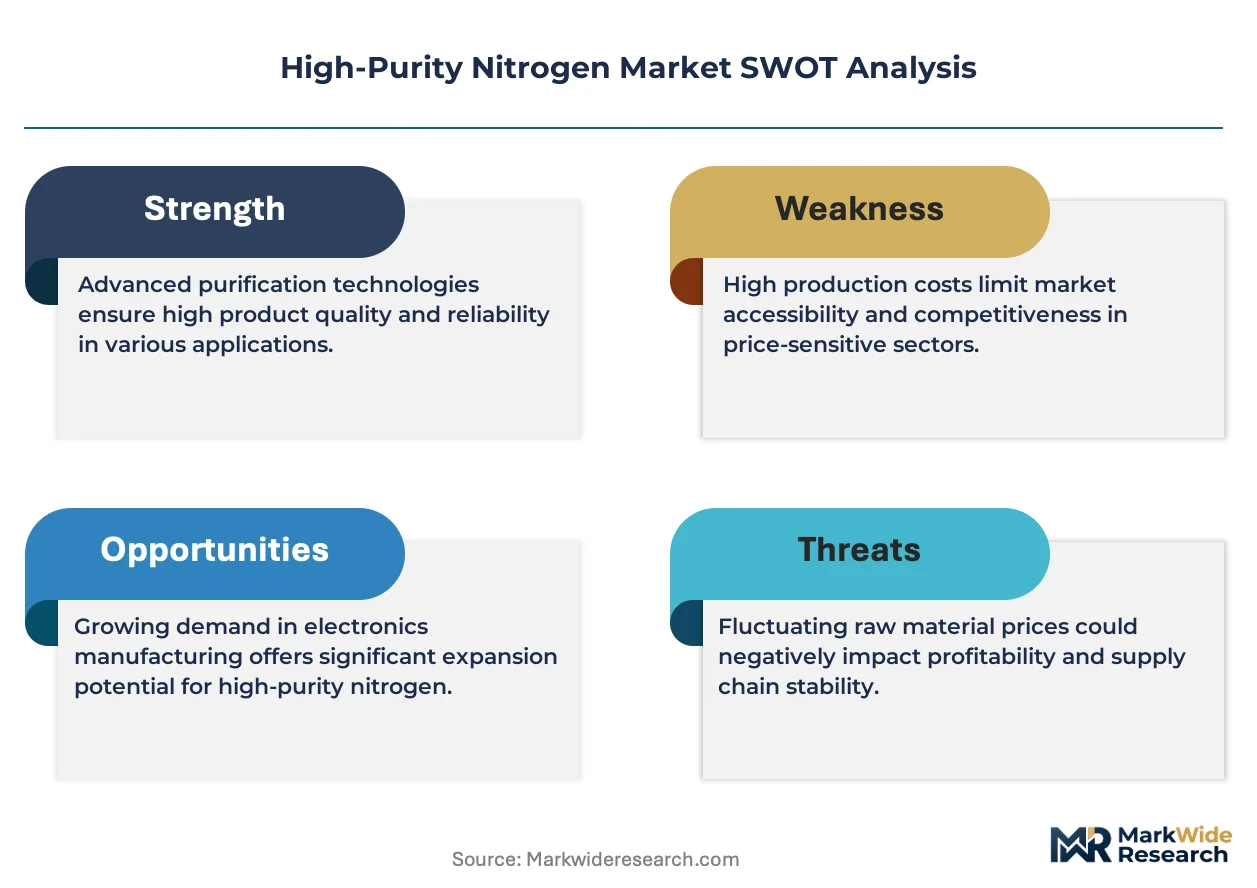
- EU F-Gas Regulation:The European framework restricts hydrofluorocarbon use in electronics cooling, redirecting manufacturers toward nitrogen-based thermal management for etch chamber temperature control.
- Cryogenic Air Separation:Energy efficiency improvements in large-scale ASU plants are lowering unit production costs for ultra-high-purity grades, expanding addressable demand in pharmaceutical aseptic processing.
Market Restraints
- Electricity Cost Volatility:Cryogenic nitrogen production is electricity-intensive; grid price spikes in Germany and Japan directly compress margins for merchant gas suppliers without long-term power purchase agreements.
- Captive Supply Concentration:Taiwan Semiconductor Manufacturing and Samsung Electronics operate self-owned generation assets, locking volume away from independent industrial gas merchants in East Asian manufacturing corridors.
- Pressure Swing Adsorption Limits:PSA systems cannot achieve sub-ppb purity levels required for advanced node production, restricting technology choice and capital flexibility for new market entrants.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO aseptic processing mandates and expanding biosimilar production in Hyderabad and Bengaluru create demand for certified nitrogen supply without established captive infrastructure.
- Green Hydrogen Electrolysis:Nitrogen purging for PEM electrolyzer stack assembly represents an emerging application as European and Australian hydrogen hubs scale manufacturing capacity.
- Remote Monitoring Integration:IoT-enabled purity sensors and predictive maintenance platforms allow gas suppliers to unbundle technical service contracts and capture recurring software revenue from distributed pharmaceutical clients.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized expertise in ASU design and cold box maintenance is concentrated among retiring specialists in Germany and the United States, constraining capacity expansion timelines.
- Multi-Year Certification Cycles:Semiconductor fabs require 18-24 month qualification protocols for new nitrogen supply sources, freezing out alternative suppliers even when technical specifications are met.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Nitrogen Market |
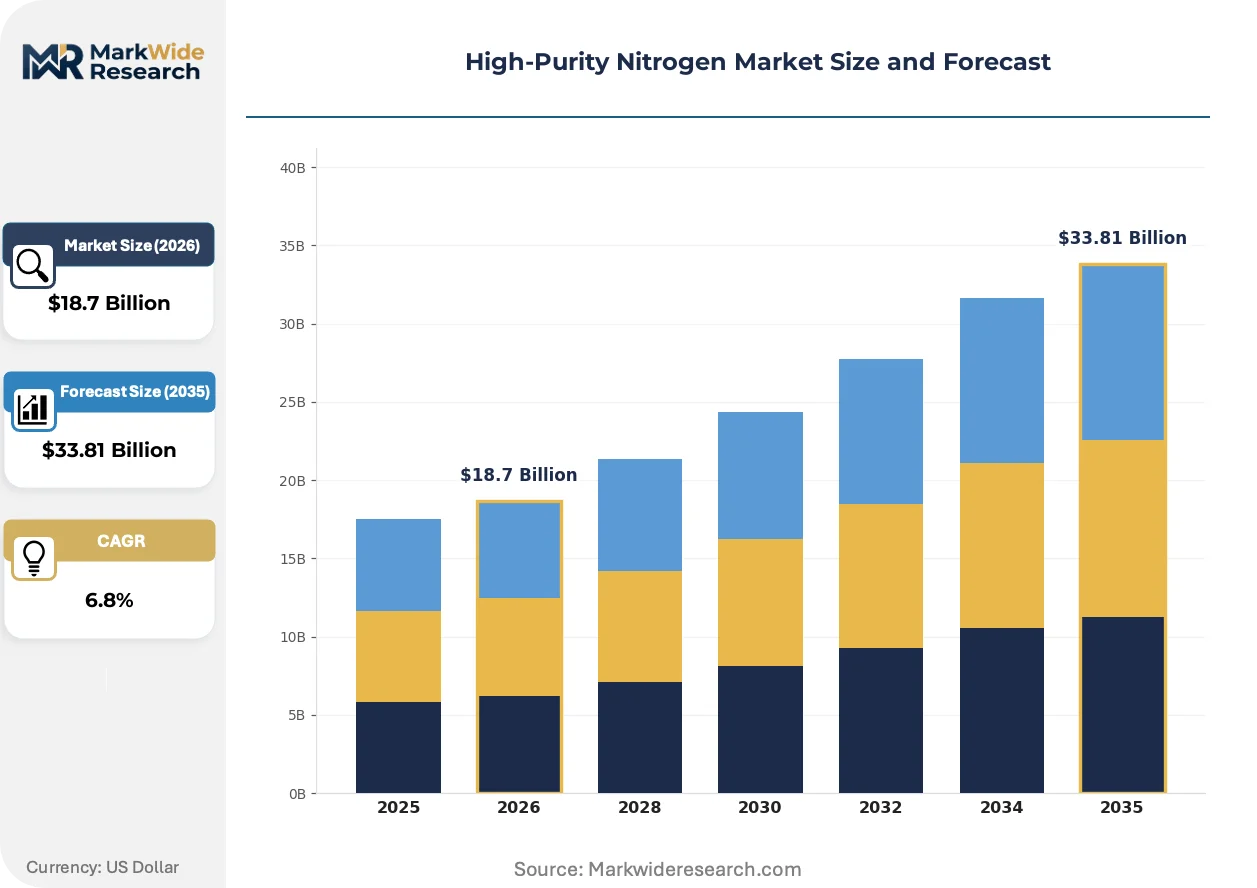
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nitrogen, Gaseous Nitrogen, High-Purity Gas, Nitrogen Cylinder Application: Semiconductors, Healthcare, Food Preservation, Chemical Processing End User: Manufacturing, Pharmaceuticals, Electronics, Research Laboratories Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer SE & Co. KGaA, Parker Hannifin Corp, Atlas Copco Group, Ingersoll Rand, Hitachi Industrial Equipment Systems Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Nitrogen Market Evolving Landscape
Membrane separation technology is advancing rapidly, threatening to compress the addressable market for traditional cryogenic systems in mid-purity applications. These developments are forcing incumbent suppliers to defend position through service integration and purity tier differentiation.
Membrane nitrogen generation is absorbing demand from food packaging and electronics assembly applications where 99.9% purity suffices. Pharmaceutical contract manufacturers in India and Southeast Asia are adopting these systems for primary packaging lines. The technology is absorbing volume that previously flowed to delivered liquid nitrogen, pressuring regional distributor networks.
The EU F-Gas Regulation is tightening phase-down schedules for hydrofluorocarbons used in semiconductor etch processes. Electronics manufacturers in Germany and the Netherlands are retrofitting thermal management systems to accept nitrogen-based cooling loops. Memory chip fabrication in Dresden and Eindhoven is most affected, with facility engineers redesigning chamber architectures around nitrogen compatibility.
Foundries are consolidating supplier relationships around single-source on-site generation partnerships with decade-long terms. Merchant liquid and bulk gas distributors are losing position in East Asian manufacturing clusters as TSMC and Samsung expand captive ASU capacity. This concentration is most visible in Hsinchu and Pyeongtaek, where new fab construction embeds nitrogen infrastructure into facility design from groundbreaking.
High-Purity Nitrogen Market Segmentation
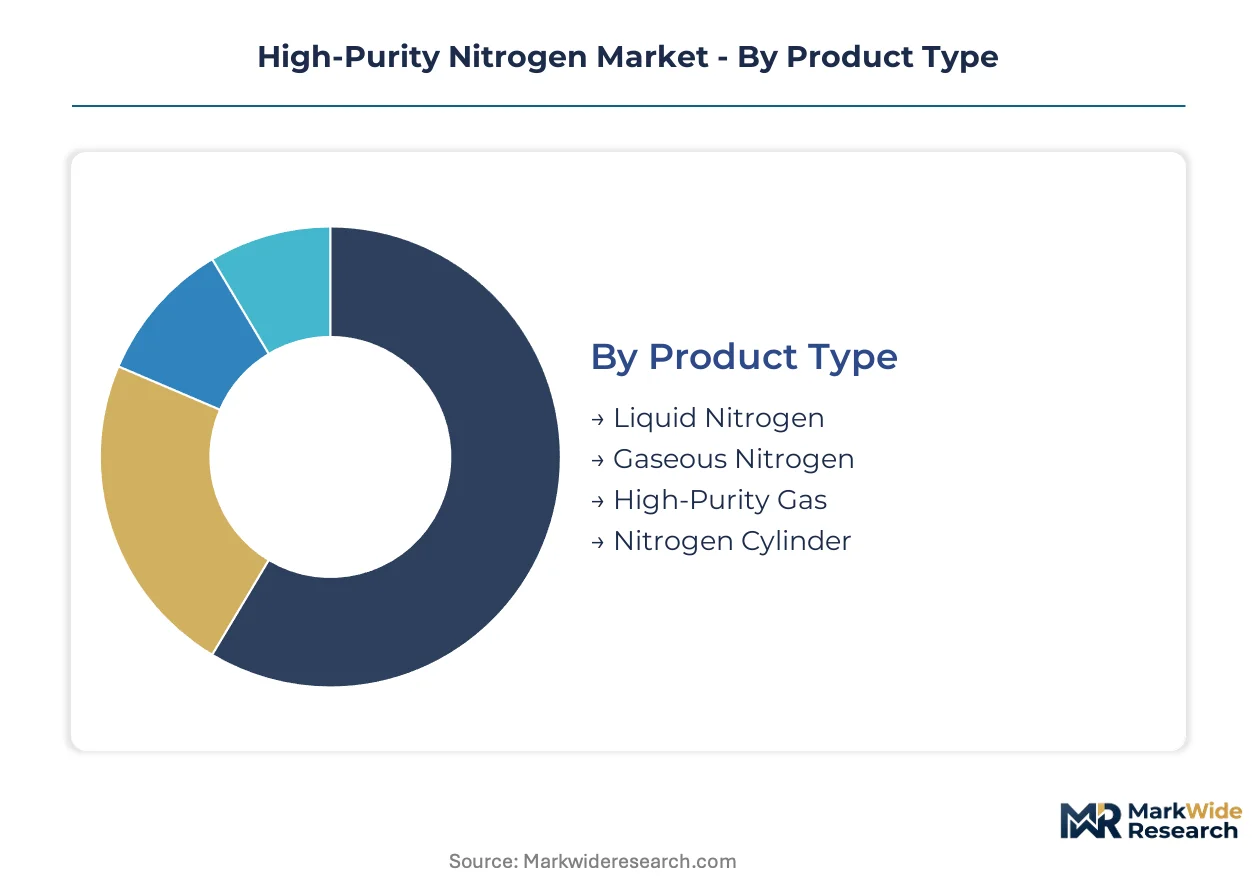
Segmentation in high-purity nitrogen markets reveals how capital deployment and technical specifications diverge across supply modes and customer requirements. Procurement patterns vary sharply between semiconductor fabs requiring sub-ppb purity and pharmaceutical operations tolerating higher contamination thresholds.
Product Type:
Cryogenic air separation units demand the heaviest capital commitments, with single-train ASU installations exceeding $100 million for ultra-high-purity output.
- Gaseous Nitrogen:Continuous-flow production via cryogenic distillation achieves 99.9999% purity with oxygen and moisture content below 1 ppb. Semiconductor fabrication in Taiwan and South Korea consumes the majority of fab-grade gaseous output, driven by EUV lithography chamber inerting requirements that tolerate zero contamination events.
- Liquid Nitrogen:Cryogenic liquefaction at -196°C enables bulk storage and transport for distributed applications. Healthcare cryopreservation in the United States and Germany anchors demand, though food freezing tunnels in Southeast Asia are expanding offtake for modified atmosphere packaging lines.
- High-Purity Gas:Catalytic deoxygenation and molecular sieve polishing refine standard nitrogen to electronic-grade specifications. Specialty chemical synthesis in the Netherlands and Switzerland requires these certified streams for oxidation-sensitive reactions.
- Nitrogen Cylinder:Pressurized containment in steel or aluminum cylinders serves remote research facilities and small-scale pharmaceutical packaging operations. India's CDSCO-registered contract manufacturers in Hyderabad represent emerging demand clusters without pipeline infrastructure.
Gaseous nitrogen absorbs the bulk of installed capacity; liquid nitrogen is expanding most quickly in food and healthcare applications.
Application:
Process sensitivity determines purity premiums, with semiconductor lithography commanding the steepest specification escalations and pricing tiers.
- Semiconductors:Deposition and etch chamber inerting requires continuous nitrogen blanketing at contamination thresholds below 0.1 ppb for advanced node production. Samsung Electronics and TSMC operate captive ASU assets in Pyeongtaek and Hsinchu, locking volume away from merchant suppliers.
- Healthcare:Cryopreservation of biological specimens and cryosurgical applications utilize liquid nitrogen for rapid temperature reduction. German university medical centers and US biobanks drive specification standards for traceable chain-of-custody documentation.
- Food Preservation:Modified atmosphere packaging and freezing tunnels employ nitrogen to displace oxygen and inhibit microbial growth. Southeast Asian seafood processing facilities in Thailand and Vietnam are retrofitting blast freezers with nitrogen injection systems.
- Chemical Processing:Inerting of reaction vessels and catalyst regeneration cycles consumes bulk gaseous nitrogen. BASF's Ludwigshafen complex and Dow's Texas operations anchor European and North American demand for pipeline-delivered supply.
Semiconductors dominate value concentration; healthcare applications are climbing the fastest as biobank infrastructure expands.
End User:
Volume scale and technical service requirements fragment procurement relationships across customer categories.
- Electronics:Foundry and memory chip manufacturers specify on-site generation with decade-long take-or-pay contracts. South Korean and Taiwanese fabs embed nitrogen infrastructure into greenfield construction timelines, freezing out merchant competition.
- Pharmaceuticals:Aseptic filling lines and API synthesis require certified nitrogen with documented batch purity. Indian CDSCO mandates and EMA requirements in Europe drive qualification protocols that extend 18-24 months for new supply sources.
- Manufacturing:Heat treatment, metal cutting, and electronics assembly consume mid-purity nitrogen via bulk liquid or cylinder delivery. German automotive suppliers and Japanese precision manufacturers represent fragmented demand with price-sensitive procurement.
- Research Laboratories:Universities and government research institutes require small-volume ultra-high-purity supply for analytical instrumentation. CERN in Switzerland and national labs in the United States specify traceable contamination documentation for grant compliance.
Electronics captures the deepest supplier relationships; pharmaceuticals is gaining share fastest as biosimilar production scales.
Distribution Channel:
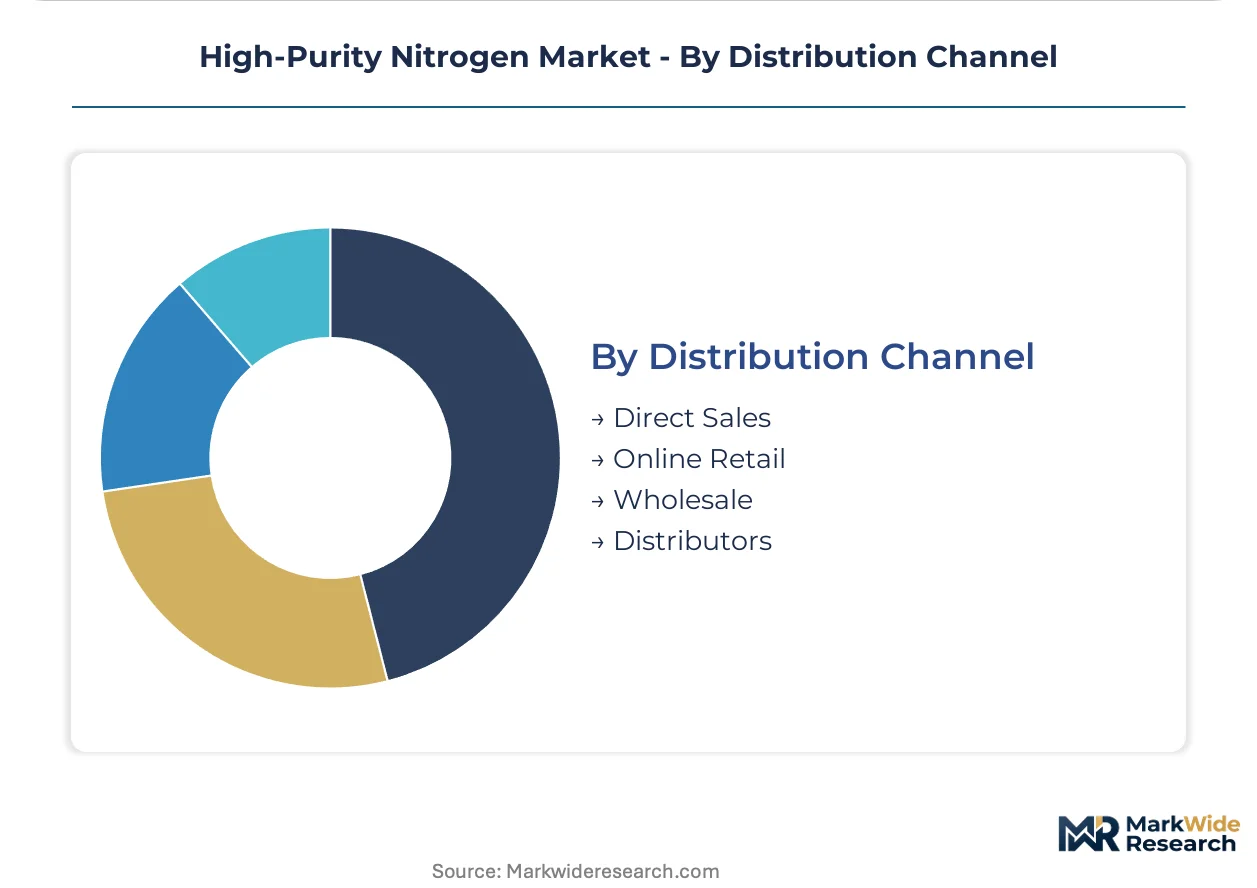
Customer scale and geographic concentration determine channel economics, with direct sales capturing premium service bundles.
- Direct Sales:Linde plc and Air Liquide negotiate long-term on-site generation contracts with semiconductor foundries. These agreements bundle cryogenic engineering, predictive maintenance, and purity monitoring into integrated service packages.
- Wholesale:Bulk liquid nitrogen moves via cryogenic tanker to industrial clusters with sufficient volume density. The Rhine-Ruhr corridor in Germany and the US Gulf Coast petrochemical complex anchor wholesale network economics.
- Distributors:Regional gas distributors serve pharmaceutical and food processing accounts lacking pipeline access. India's fragmented distributor landscape in Bengaluru and Mumbai lacks integrated gas company coverage.
- Online Retail:Cylinder and small-bulk orders for research and small manufacturing customers migrate to digital procurement platforms. Japanese and German industrial gas suppliers are piloting e-commerce portals for standardized purity grades.
Direct sales commands the highest contract values; wholesale channels are expanding most quickly in industrial corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries in Taiwan and South Korea absorb the majority of fab-grade nitrogen consumption, while pharmaceutical and chemical clusters in Germany and the United States sustain merchant supply demand. Captive on-site generation systems now dominate volume in East Asian manufacturing corridors, restructuring procurement relationships away from traditional bulk delivery.
Taiwan
TSMC's advanced node expansion in Hsinchu and Tainan Science Parks drives continuous nitrogen inerting demand for EUV lithography chambers. The National Development Council's semiconductor initiative accelerates greenfield fab construction with embedded ASU infrastructure. Kaohsiung's emerging 2nm cluster locks volume into decade-long supply agreements, freezing merchant competition from the island's southern manufacturing belt.
South Korea
Samsung Electronics and SK Hynix operate self-owned generation assets in Pyeongtaek and Yongin for memory and logic chip production. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes on-site gas infrastructure for foundry expansion. Sejong City's emerging compound semiconductor cluster attracts nitrogen engineering specialists from retiring German cryogenic experts.
United States
Intel's Ohio and Arizona fabs drive merchant nitrogen demand where captive infrastructure remains under construction. EPA emissions standards for chemical manufacturing shape purity certification protocols in Texas and Louisiana petrochemical corridors. Phoenix's emerging semiconductor cluster attracts Air Products and Linde engineering teams for long-term on-site partnerships.
Germany
BASF's Ludwigshafen complex and Merck KGaA's Darmstadt operations anchor pharmaceutical-grade nitrogen demand for aseptic processing. ECHA REACH requirements mandate detailed supply chain traceability for gas certification. Dresden's silicon photonics cluster retrofits thermal management for EU F-Gas Regulation compliance, redirecting etch chamber cooling toward nitrogen-based systems.
India
CDSCO-registered contract manufacturers in Hyderabad and Bengaluru expand biosimilar production without established captive gas infrastructure. The Production Linked Incentive scheme for pharmaceuticals incentivizes aseptic processing capacity that requires certified nitrogen supply. Mumbai's fragmented distributor landscape lacks integrated gas company coverage, creating wholesale opportunity for bulk liquid delivery.
High-Purity Nitrogen Market Competitive Landscape
European producers anchor one tier through cryogenic technology leadership and regional production density; East Asian specialists hold position through foundry-integrated service bundling and decade-long contract structures. The vendor base stratifies between integrated industrial gas majors with on-site generation capabilities and equipment-focused specialists supplying purification hardware. Three archetypes dominate: captive infrastructure operators, merchant bulk suppliers, and point-of-use system fabricators. Consolidation through ASU asset acquisitions and strategic partnerships for remote monitoring integration represent the primary competitive vectors reshaping positioning.
Within the integrated industrial gas tier, Linde plc, Air Liquide, and Air Products and Chemicals, Inc. exemplify divergent strategic postures. Linde occupies a position emphasizing on-site generation infrastructure and long-term foundry anchoring. Air Liquide represents cryogenic technology density and European regulatory compliance specialization. Air Products sits within ultra-high-purity purification system supply, serving contamination thresholds below sub-part-per-billion specifications for advanced lithography.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Taiyo Nippon Sanso Corporation |
| Messer SE & Co. KGaA |
| Parker Hannifin Corp |
| Atlas Copco Group |
| Ingersoll Rand |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry concentration in Taiwan and South Korea anchors contract-based long-term offtake pricing with decade-long take-or-pay structures. Merchant suppliers face margin compression where captive on-site generation locks volume away from bulk liquid markets.
Pricing Analysis
High-volume fab contracts sacrifice margin for guaranteed offtake while spot pharmaceutical and food-grade deliveries capture premium pricing. Three-tier pricing structure across fab-grade, pharmaceutical-certified, and industrial-standard levels differentiates by contamination threshold and certification documentation. Pricing pressure stems from electricity cost volatility in Germany and Japan directly compressing cryogenic production margins. Pharmaceutical contract manufacturers in India exhibit highest price sensitivity due to fragmented distributor competition, while semiconductor foundries prioritize technical service bundling over unit cost.
Supply Chain Analysis
Cryogenic tanker logistics from centralized air separation units to distributed pharmaceutical and food processing accounts consumes 15-25% of delivered product cost in regions lacking pipeline infrastructure. Production concentrates in Taiwan, South Korea, and Germany where foundry-integrated ASU assets and chemical corridor pipeline networks anchor supply. The supply chain draws from electricity feedstock, specialized cryogenic engineering talent, and molecular sieve catalysts. Single-source vulnerability in East Asian manufacturing corridors threatens supply security where TSMC and Samsung operate self-owned generation without merchant backup. Distribution runs through direct on-site partnerships for electronics, wholesale bulk liquid for chemical processing, and regional distributors for pharmaceutical and research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where electricity cost volatility and captive supply concentration force merchant gas suppliers without on-site generation capabilities toward acquisition or exit.
For Market Incumbents: Cement foundry relationships through embedded ASU infrastructure investments in Hsinchu and Pyeongtaek before greenfield fab completion locks in decade-long competitors. Acquire membrane separation specialists in India and Southeast Asia to defend position against point-of-use systems displacing delivered liquid in mid-purity pharmaceutical packaging. Cryogenic engineering talent scarcity in Germany and the United States threatens expansion timelines; secure retiring specialist expertise through targeted retention and knowledge transfer programs. For New Entrants and Emerging Players: Regional gas distributors in India's Hyderabad and Bengaluru clusters offer the most penetrable entry path where integrated gas company coverage remains fragmented. Target CDSCO-registered pharmaceutical contract manufacturers requiring certified nitrogen supply without established captive infrastructure. A go-to-market angle emphasizing IoT-enabled purity monitoring and predictive maintenance unbundles technical service contracts from commodity gas delivery, capturing recurring software revenue. For Investors and Strategic Acquirers: The window for entry favors equipment-focused purification system fabricators with ultra-high-purity capabilities below sub-ppb thresholds. Long-term viability hinges on semiconductor node transitions below 3nm tightening contamination specifications and extending qualification protocol timelines that freeze out alternative suppliers. Watch for foundry announcements of advanced node expansion in Sejong City and Kaohsiung as inflection indicators for nitrogen infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ASU Assets | Captive production in Taiwan and South Korea locks foundry volume away from merchant competition. |
| Membrane Technology Acquisition | Point-of-use systems in India and Southeast Asia displace delivered liquid in mid-purity applications. |
| IoT Purity Monitoring Platform Launch | Remote sensors allow unbundling of technical service contracts from commodity gas delivery. |
| Long-term Supply Agreement with Foundry | Decade-long take-or-pay structures in Hsinchu and Pyeongtaek anchor revenue visibility. |
| Cryogenic Engineering Talent Retention Program | Specialized expertise concentration among retiring German and US specialists constrains expansion. |
Research Methodology
Trade databases, customs records, and SEC filings from industrial gas majors formed the secondary backbone for supply chain mapping and capacity tracking. Primary interviews with cryogenic plant managers, semiconductor fab procurement leads, pharmaceutical quality assurance directors, and regional gas distributor operators validated production cost structures and contract term evolution. Bottom-up and top-down triangulation cross-checked volume estimates against electricity consumption data and foundry expansion announcements.
Bottom-up modeling of individual air separation unit capacity, utilization rates, and purity tier output combined with top-down semiconductor capital expenditure analysis across the projection horizon. Segmentation dimensions included supply mode (on-site, bulk liquid, cylinder), purity grade (electronic, pharmaceutical, industrial), end-use application (semiconductor, healthcare, food, chemicals), and geographic production cluster. CAGRs were derived from node transition timelines and corresponding contamination threshold escalations, with EU F-Gas Regulation phase-down schedules and Indian PLI scheme implementation as industry-specific forecast inputs.
Caveats apply where electricity price volatility, foundry construction delays, or regulatory enforcement shifts could materially shift the outlook. Forecasts reflect documented assumptions around semiconductor node transition pace and captive generation adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Ultra-High Purity Materials Market