
 Nitro Tea Market | 2026-2036
Nitro Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Nitro Tea Market Insights
Specialty beverage production clusters in the Pacific Northwest is recalibrating nitrogen-infusion capacity to serve expanding ready-to-drink distribution. Starbucks Corporation leverages its cafe network to anchor nitro tea availability across thousands of North American locations. Rise Brewing Co. competes through dedicated cold-brew nitrogenation infrastructure that sustains consistent product texture. East Forged specializes in Asian-inspired flavor profiles that differentiate its portfolio from conventional offerings.
Nitro tea infuses brewed tea with nitrogen gas under high pressure, creating a cascading pour with creamy mouthfeel and reduced acidity compared to standard iced tea; the nitrogenation process typically operates at 30-40 psi and requires flash-chilled liquid bases to preserve volatile aromatic compounds. Black Nitro Tea occupies the largest volume share due to established consumer familiarity and broader distribution through Quick Service Restaurants. Flavored Nitro Tea registers the fastest trajectory as botanical and fruit-adjacent formulations attract younger demographics through Convenience Stores and Fitness Centers.
The FDA oversees nitrogen gas purity standards and cold-chain labeling requirements for retail nitro tea packaging, while the USDA's organic certification program shapes premium positioning for botanical ingredient sourcing. Japan's FSSAI equivalent, the Ministry of Health, Labour and Welfare, enforces additive thresholds and novel food assessments that constrain formulation flexibility for entrants. Stakeholders must monitor evolving nitrogen gas supplier qualification protocols and regional cold-chain infrastructure gaps as distribution expands beyond established metropolitan cores.
Market Dynamics
Nitrogen-infusion equipment manufacturers face capacity constraints as specialty cafes and ready-to-drink bottlers simultaneously expand dispensing infrastructure. Cold-chain logistics providers scramble to retrofit distribution networks for flash-chilled liquid bases requiring sub-40°F integrity.
Growth Catalysts
- FDA Cold-Chain Labeling Mandates:The FDA's expanded disclosure requirements for nitrogenated beverages create compliance-driven demand for certified dispensing systems and packaging equipment upgrades across US retail channels.
- Fitness Center Channel Expansion:Post-workout recovery positioning drives nitro tea placement in high-traffic gym chains, replacing traditional sports drink fountains with nitrogenated alternatives.
- Tokyo Metropolitan Cluster Density:Japan's Ministry of Health, Labour and Welfare streamlined novel food assessments for botanical additives, accelerating flavored formulation approvals in the capital's specialty beverage corridor.
Market Restraints
- Liquid Nitrogen Supply Concentration:Industrial gas production clusters in the Gulf Coast and Texas Panhandle create geographic vulnerability for coastal dispensing networks dependent on refrigerated transport.
- 30-40 PSI Infrastructure Cost:Cafe operators face $15,000-$40,000 per-location capital requirements for nitrogen generation systems, compressing independent operator entry.
- Cold-Brew Acidity Substitution:Flash-chilled coffee systems achieve comparable mouthfeel without nitrogenation, diverting equipment investment in hybrid beverage operations.
Strategic Opportunities
- India Convenience Store Penetration:FSSAI's evolving ready-to-drink beverage standards create first-mover positioning for nitrogenated formats in organized retail expansion across Tier-2 cities.
- Botanical-Functional Convergence:Adaptogenic ingredient integration with nitrogenation technology targets wellness-focused demographics through pharmacy and natural food channels.
- Direct-to-Consumer Subscription Models:Canned nitro tea delivery bypasses dispensing infrastructure limitations, capturing home consumption occasions previously unreachable by on-premise formats.
Industry Challenges
- Nitrogen System Technician Scarcity:Specialized maintenance expertise for high-pressure dispensing equipment concentrates in major metropolitan service hubs, extending downtime for remote locations.
- USDA Organic Certification Timelines:Botanical ingredient sourcing documentation requirements delay premium product launches by 8-14 months, compressing seasonal flavor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitro Tea Market |
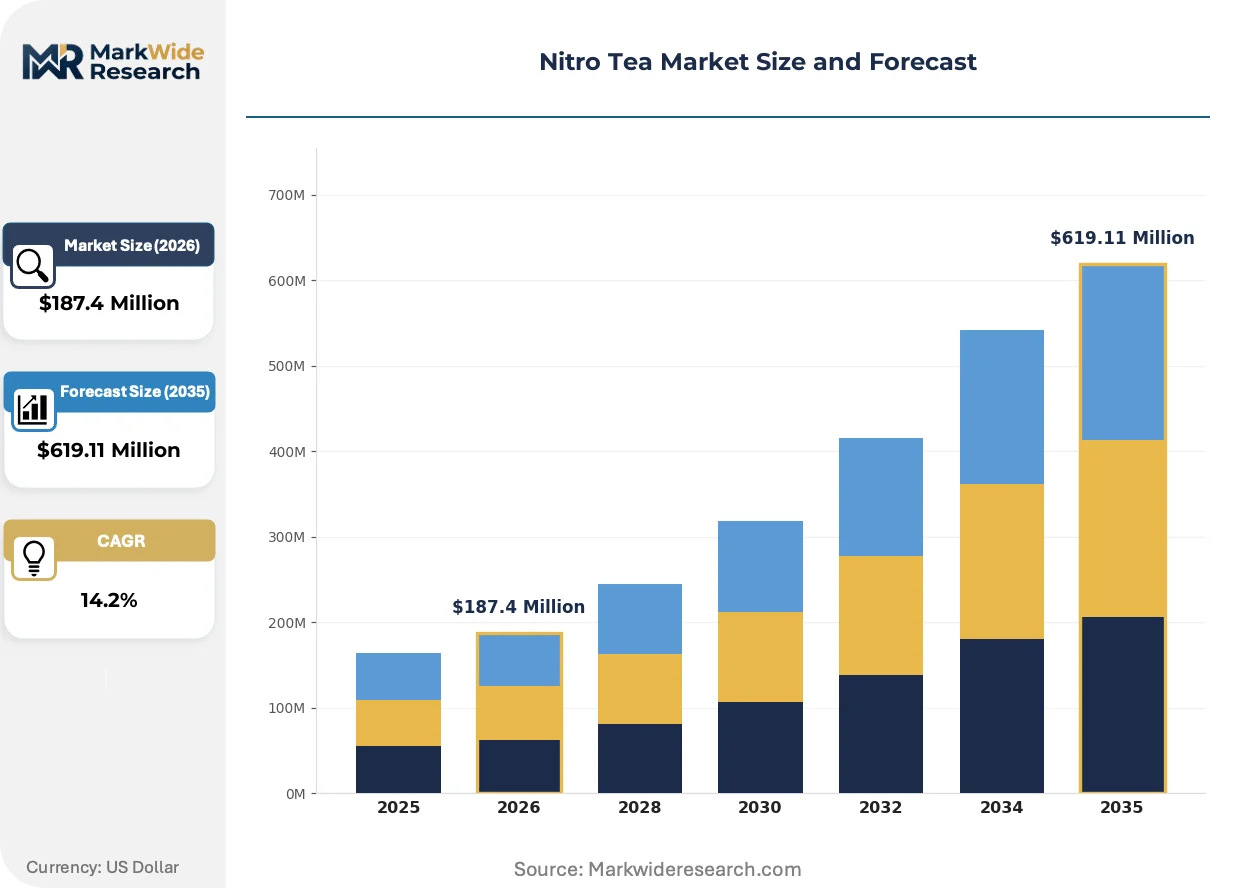
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Nitro Tea, Green Nitro Tea, Herbal Nitro Tea, Flavored Nitro Tea, Specialty Nitro Tea Application: Cafes, Quick Service Restaurants, Office Beverage Services, Fitness Centers, Convenience Stores Packaging Type: cans, Bottles, Kegs, Cartons, Sachets End User: Hospitality, Corporate Offices, Fitness Studios, Educational Institutions, Event Venues |
| Companies Covered | Starbucks Corporation, Rise Brewing Co., Bona Fide Nitro Coffee and Tea, Chameleon Coffee, East Forged, Quivr, Minor Figures, Portal Tea, Novus Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitro Tea Market Trends and Innovations
Flash-chilling technology is absorbing capital allocation as manufacturers prioritize aromatic compound preservation over traditional cold-brew steeping methods. Equipment suppliers race to integrate nitrogenation directly into bottling lines.
Modular nitrogen generators are absorbing mid-capacity production demand from regional bottlers seeking to bypass industrial gas supply contracts. These plug-and-play systems enable 500-2,000 liter daily throughput without centralized infrastructure. California and New York craft beverage producers are absorbing this technology fastest, compressing the traditional equipment supplier hierarchy.
Japan's Ministry of Health, Labour and Welfare tightened additive threshold assessments for novel botanical extracts in nitrogenated formats. The regulatory friction forces reformulation of elderberry and ashwagandha variants previously approved in US markets. Tokyo-based specialty cafes are absorbing compliance costs through simplified ingredient statements, narrowing the flavor portfolio gap with American competitors.
Convenience store buyers now specify nitrogenated beverages with 90-day ambient shelf stability, displacing traditional cold-chain dependent distribution. This specification compresses manufacturer margins but expands addressable retail footprint. California and Texas petroleum retail chains are absorbing this shift earliest, replacing fountain equipment with ambient-ready canned formats.
Nitro Tea Market Segmentation
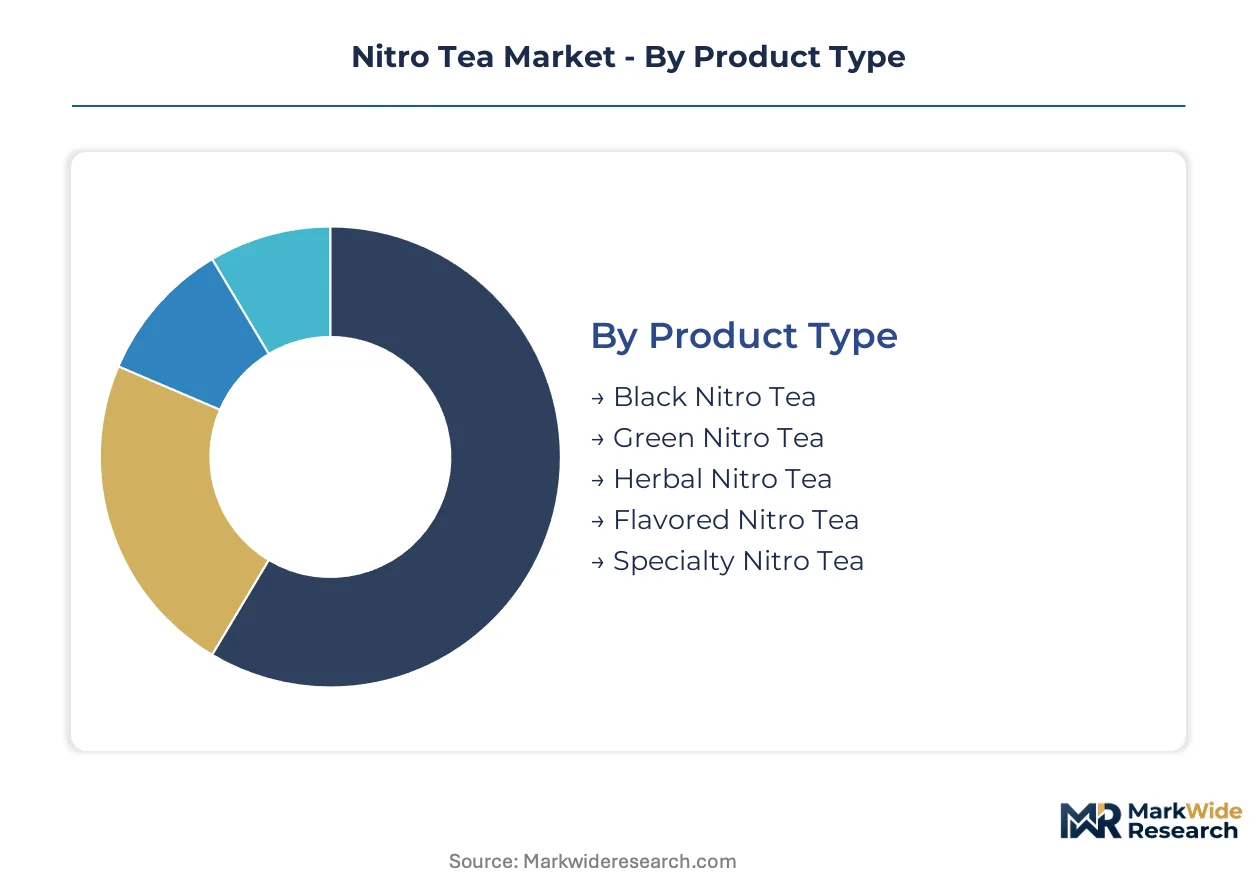
Nitrogenation equipment specifications and cold-chain requirements vary sharply across product formulations and dispensing environments. Segmentation reveals where FDA cold-chain mandates, USDA organic certification timelines, and Japan's Ministry of Health, Labour and Welfare additive thresholds create divergent compliance burdens.
Product Type:
USDA organic certification and FDA nitrogen gas purity standards impose tiered documentation requirements across botanical ingredient portfolios. Japan's Ministry of Health, Labour and Welfare enforces additive thresholds that constrain formulation flexibility for entrants.
- Black Nitro Tea:Established consumer familiarity drives volume concentration through Quick Service Restaurant fountain systems. Coastal metropolitan clusters in California and New York absorb the largest dispensing infrastructure investments.
- Flavored Nitro Tea:Botanical and fruit-adjacent formulations attract younger demographics through Convenience Store and Fitness Center channels. Japan's streamlined novel food assessments for botanical additives accelerate approval timelines in Tokyo's specialty beverage corridor.
- Green Nitro Tea:Antioxidant positioning targets wellness-focused consumers in pharmacy and natural food retail formats.
- Herbal Nitro Tea:Adaptogenic ingredient integration requires extended USDA organic certification timelines.
- Specialty Nitro Tea:Limited-batch production concentrates in Pacific Northwest craft beverage clusters.
Leading the category by volume: Black Nitro Tea. Expanding most quickly: Flavored Nitro Tea.
Application:
Capital requirements for 30-40 PSI nitrogen generation systems stratify entry barriers across dispensing environments. Independent operators face $15,000-$40,000 per-location infrastructure costs.
- Cafes:Specialty beverage producers anchor nitrogen-infusion capacity to serve expanding ready-to-drink distribution. Starbucks Corporation leverages thousands of North American locations to standardize nitro tea availability.
- Quick Service Restaurants:Fountain equipment standardization enables rapid format adoption across high-traffic locations. Black tea variants dominate volume throughput in this channel.
- Office Beverage Services:Corporate procurement specifications prioritize ambient-stable canned formats over keg-dependent dispensing.
- Fitness Centers:Post-workout recovery positioning displaces traditional sports drink fountains with nitrogenated alternatives.
- Convenience Stores:Buyers now specify 90-day ambient shelf stability, compressing manufacturer margins while expanding retail footprint.
Highest infrastructure investment: Cafes. Fastest channel expansion: Fitness Centers.
Packaging Type:
Cold-chain integrity requirements and shelf stability specifications determine format viability across retail channels. California and Texas petroleum retail chains absorb ambient-ready canned formats earliest.
- Kegs:Flash-chilled liquid bases requiring sub-40°F integrity concentrate in on-premise dispensing networks. Specialty cafes in Tokyo and New York maintain the densest keg infrastructure.
- Cans:Direct-to-consumer subscription models bypass dispensing infrastructure limitations, capturing home consumption occasions. Rise Brewing Co. competes through dedicated cold-brew nitrogenation infrastructure sustaining consistent product texture.
- Bottles:Premium positioning in natural food channels requires extended USDA organic certification documentation.
- Cartons:Bulk institutional formats target educational and corporate office procurement specifications.
- Sachets:Single-serve powder formats remain underdeveloped for nitrogenated applications.
Dominant format by volume: Kegs. Steepest expansion trajectory: Cans.
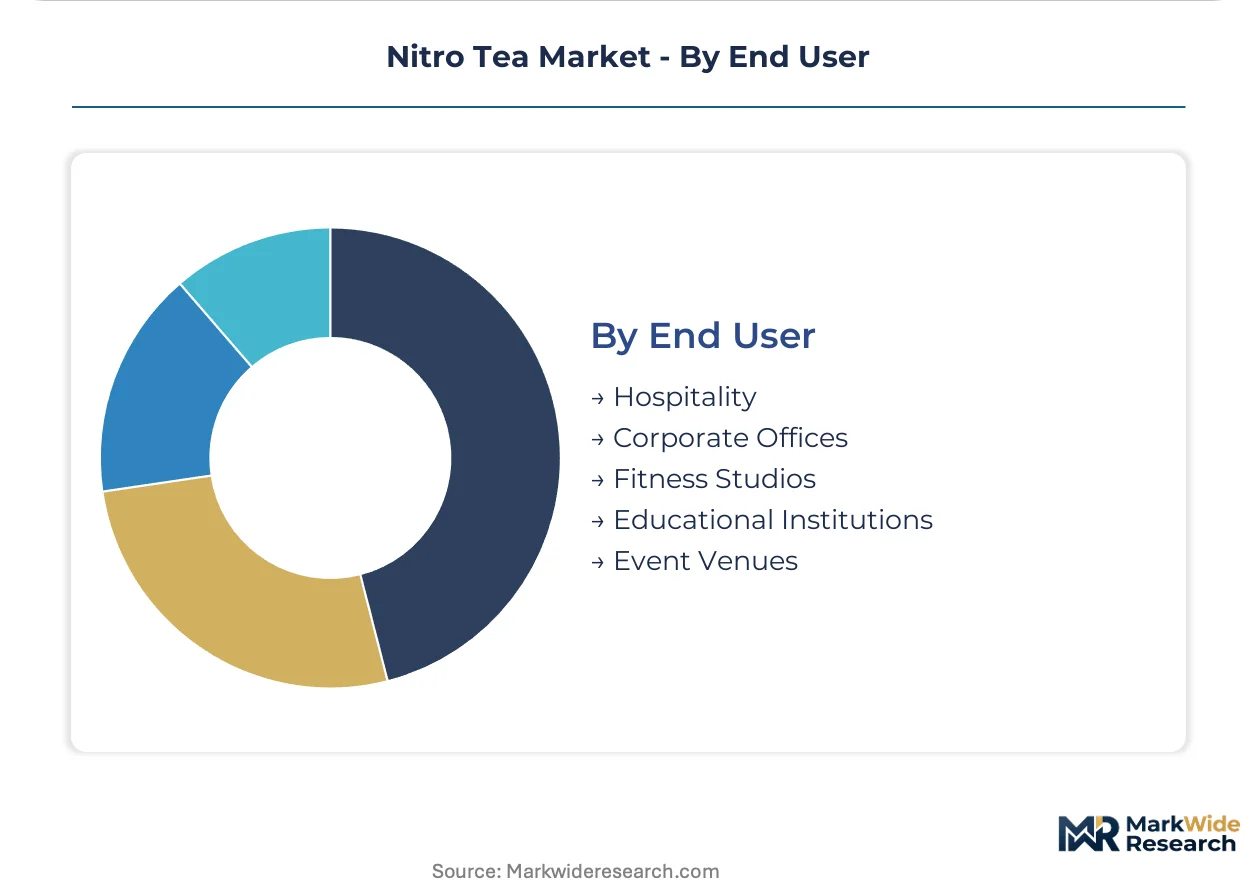
End User:
Procurement specifications and consumption occasion patterns fragment demand across institutional and commercial environments. East Forged specializes in Asian-inspired flavor profiles differentiating its portfolio for hospitality applications.
- Hospitality:Premium positioning in hotels and restaurants requires consistent nitrogenation texture for guest experience standards.
- Corporate Offices:Office Beverage Services procurement prioritizes ambient-stable formats reducing cold-chain dependency.
- Fitness Studios:Post-workout recovery demand concentrates in high-traffic gym chains replacing traditional beverage fountains.
- Educational Institutions:Bulk procurement specifications favor cartons and bottles over keg-dependent dispensing.
- Event Venues:Temporary dispensing requirements favor mobile nitrogen generation systems over fixed infrastructure.
Largest procurement volume: Hospitality. Fastest specification evolution: Fitness Studios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial nitrogen production clusters in the Texas Panhandle and Gulf Coast supply coastal dispensing networks across multiple continents, creating geographic interdependencies that shape regional market development.
United States
FDA cold-chain labeling mandates for nitrogenated beverages drive compliance investment across California and New York metropolitan corridors. The USDA's organic certification program extends botanical ingredient sourcing timelines for premium formulations. Specialty cafes in Los Angeles and Brooklyn absorb the densest nitrogen generation infrastructure deployments.
Japan
Tokyo's specialty beverage corridor concentrates demand for Asian-inspired flavor profiles through high-traffic cafe networks. The Ministry of Health, Labour and Welfare streamlined novel food assessments for botanical additives, accelerating flavored formulation approvals. Kanto region bottlers retrofit flash-chilling capacity to serve expanding convenience store distribution.
India
FSSAI's evolving ready-to-drink beverage standards create first-mover positioning for nitrogenated formats in organized retail expansion. Tier-2 cities absorb ambient-stable canned formats as petroleum retail chains replace fountain equipment. Maharashtra and Karnataka beverage producers pilot modular nitrogen generators to bypass industrial gas supply contracts.
Germany
EMA-aligned food additive assessments constrain botanical extract formulations for nitrogenated beverages entering European markets. Bavaria and North Rhine-Westphalia craft beverage clusters absorb flash-chilling technology for aromatic compound preservation. Berlin specialty cafes anchor nitrogen-infusion capacity for premium hospitality channels.
Australia
TGA-equivalent food standards enforcement shapes import requirements for nitrogenated ready-to-drink products. New South Wales and Victoria fitness center chains displace traditional sports drink fountains with nitrogenated alternatives. Sydney and Melbourne metropolitan areas concentrate dispensing infrastructure investment for post-workout recovery positioning.
Nitro Tea Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional botanical differentiation and direct-to-consumer subscription models. The vendor base stratifies across three tiers: multinational cafe networks with captive dispensing infrastructure, dedicated cold-brew nitrogenation specialists, and regional craft producers with Asian-inspired flavor portfolios. Consolidation pressure concentrates among equipment-dependent operators facing $15,000-$40,000 per-location capital requirements. Strategic moves cluster around M&A for nitrogen generation technology and partnerships with cold-chain logistics providers.
Within the dedicated nitrogenation tier, Rise Brewing Co. and East Forged occupy positions exemplifying divergent specialization strategies. Rise Brewing Co. anchors the consistent texture segment through purpose-built cold-brew infrastructure. East Forged represents the Asian-inspired flavor archetype, differentiating through botanical formulations targeting younger demographics. Starbucks Corporation sits at the scale-driven end, leveraging thousands of North American locations to standardize nitro tea availability across Quick Service Restaurant and cafe channels.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Rise Brewing Co. |
| Bona Fide Nitro Coffee and Tea |
| Chameleon Coffee |
| East Forged |
| Quivr |
| Minor Figures |
| Portal Tea |
| Novus Tea |
| Others |
Pricing and Supply Chain Analysis
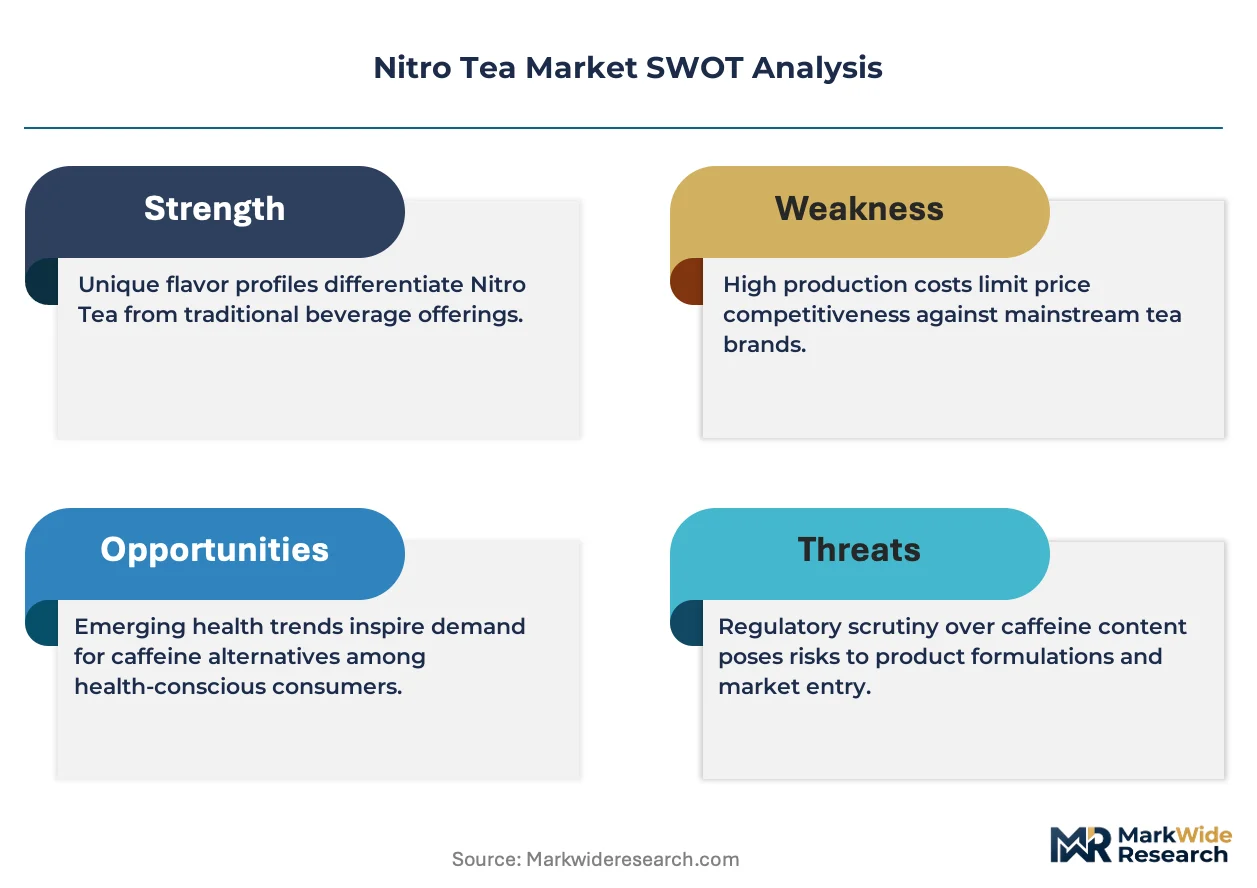
Liquid nitrogen feedstock costs cascade from Gulf Coast industrial gas clusters through refrigerated transport networks into three distinct pricing tiers for coastal dispensing infrastructure. FDA cold-chain labeling mandates compress margins for non-compliant operators while USDA organic certification premiums sustain elevated price floors for botanical-forward formulations.
Pricing Analysis
Service-bundling separates equipment warranty coverage from bare-metal nitrogen generation system sales, with independent cafe operators absorbing unbundled maintenance risk. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and cold-chain integrity specifications. Pricing pressure stems from modular generator entrants undercutting industrial gas contract dependencies. Quick Service Restaurant procurement teams exhibit highest price sensitivity; specialty cafes in Tokyo and Brooklyn sustain premium tolerance for consistent texture delivery.
Supply Chain Analysis
Refrigerated freight costs from Texas Panhandle and Louisiana industrial gas production centers amplify landed nitrogen expenses for California and New York metropolitan dispensing networks. Supply draws from concentrated US Gulf Coast production, Japanese industrial gas imports, and emerging Indian modular generator manufacturing. Single-source vulnerability concentrates in liquid nitrogen transport logistics for coastal keg-dependent operations. Distribution runs through flash-chilled liquid base suppliers, equipment manufacturers, and cold-chain logistics providers into on-premise dispensing and ambient-stable canned retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance cost escalation under FDA cold-chain labeling mandates and Japan's Ministry of Health, Labour and Welfare additive thresholds erect durable barrier-to-entry moats for certified incumbents while squeezing marginal operators.
For Market Incumbents: Extend nitrogen generation technology ownership through backward integration into modular equipment manufacturing, insulating against industrial gas supply concentration. Anchor capacity expansion in Pacific Northwest specialty beverage clusters where flash-chilling technology absorption runs fastest. Counter cold-brew acidity substitution threats by embedding nitrogenation texture as non-negotiable quality standard in Quick Service Restaurant fountain specifications. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models bypassing fifteen-to-forty-thousand-dollar per-location dispensing infrastructure barriers. Target India Tier-2 convenience store penetration where FSSAI ready-to-drink standards create first-mover white space. Exploit ambient-stable canned format specifications displacing cold-chain dependent keg distribution in petroleum retail chains. For Investors and Strategic Acquirers: FDA warning letter issuance for cold-chain labeling violations is the leading indicator that consolidation pressure is intensifying among equipment-dependent regional operators. Five-to-ten-year viability favors nitrogen generation technology specialists with captive dispensing network relationships over pure-play formulation brands. Monitor modular generator patent filings as inflection signal for supply-side technology disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Nitrogen Generator Deployment | Regional bottlers bypass industrial gas contracts through 500-2,000 liter daily throughput systems. |
| Flash-Chilling Technology Integration | Equipment suppliers embed nitrogenation directly into bottling lines for aromatic preservation. |
| Ambient-Stable Canned Format Expansion | California and Texas petroleum retail chains replace fountain equipment with 90-day shelf-stable alternatives. |
| Botanical-Functional Convergence R&D | Adaptogenic ingredient integration targets wellness demographics through pharmacy channel placement. |
| Cold-Chain Logistics Partnership | Flash-chilled liquid base suppliers secure sub-40°F integrity guarantees for keg distribution networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nitro tea market assessment. Primary interviews with specialty cafe operators, nitrogen generation equipment manufacturers, cold-chain logistics providers, and botanical ingredient suppliers combined with FDA enforcement action databases, USDA organic certification registries, and Japan Ministry of Health, Labour and Welfare additive approval records. Bottom-up volume modeling triangulated against top-down category spending estimates.
Granularity-level modeling deployed product type, application channel, packaging format, and end-user specifications across the projection horizon. CAGRs derived from segment-level volume trajectories and price realization trends. Forecast inputs incorporated nitrogen generation equipment deployment rates, convenience store ambient-stability specification adoption curves, and fitness center channel penetration benchmarks.
Regulatory enforcement intensity shifts, industrial gas supply disruption events, and cold-brew coffee substitution acceleration are the dominant revision risks for trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Pu-Erh Tea Market
Tea
High Protein Tea Market
Tea
Instant Tea Premixes Market
Tea
White Tea Extract Market
Tea
US Ready to Drink Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Organic Tea Market
Tea
Detox Tea Market
Tea
APAC RTD Tea Market
Tea
New Style Tea Drink Market
Tea
Black Tea Base Bubble Tea Market
Tea
Matcha Market
Tea
Instant Tea Premix Consumption Market
Tea
Green Tea Leaves Market
Tea
Floral Tea Market
Tea
Butterfly Pea Flower Tea Market