
 Detox Tea Market | 2026-2036
Detox Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Detox Tea Market Analysis
Corporate wellness programs is recalibrating the buyer base for detox tea, shifting volume from retail shelves to employer-subsidized health stipends. Yogi Products leverages its certified organic supply chain to anchor premium positioning in this channel. Traditional Medicinals sustains botanical sourcing transparency as a competitive differentiator against commodity blends. Pukka Herbs Limited specializes in Ayurvedic-inspired formulations that occupy a distinct niche in European health food retail.
Detox tea comprises blended botanical infusions formulated with diuretic, antioxidant, or hepatoprotective compounds—typically caffeine-free or low-caffeine—manufactured through controlled drying, cutting, and temperature-monitored steeping processes to preserve volatile oil integrity. The product category serves consumers seeking perceived metabolic support, hydration rituals, and sugar-free alternatives to conventional beverages. Herbal detox tea leads volume contribution due to its caffeine-free positioning and broader evening consumption occasion, while green tea variants capture faster growth through antioxidant marketing tied to EGCG catechin content. Sachet packaging dominates convenience-oriented channels, though canister formats retain stronger margins in specialty and gift segments where perceived value correlates with reusable storage utility.
EFSA health claims regulation constrains permissible marketing language for digestive and metabolic benefits, forcing reformulation toward substantiated ingredient dossiers. FDA Good Manufacturing Practices and USDA Organic certification shape import eligibility and shelf placement in United States retail, while ECHA botanical safety assessments affect European ingredient approvals. Stakeholders must monitor evolving caffeine disclosure thresholds and emerging state-level extended producer responsibility rules for flexible packaging waste.
Market Dynamics
Corporate wellness programs are restructuring detox tea distribution, redirecting procurement through employer-subsidized health stipends rather than conventional retail channels. This shift compels manufacturers to reformulate for bulk institutional contracts while maintaining clean-label credentials demanded by benefits administrators.
Growth Catalysts
- EFSA Health Claims Regulation:Stricter substantiation requirements for digestive benefits are forcing reformulation toward clinically documented botanical dossiers, elevating barrier to entry for commodity competitors.
- Employer Wellness Stipends:Human resources departments in the United States and Germany are expanding beverage allowances to include functional teas, creating predictable recurring revenue streams distinct from seasonal retail cycles.
- Low-Temperature Drying Technology:Controlled dehydration preserving volatile oil integrity enables premium positioning through verifiable phytochemical retention claims on packaging.
Market Restraints
- Botanical Raw Material Concentration:Organic certified chamomile and milk thistle supply concentrates in Egyptian and Bulgarian growing regions, exposing processors to climate-driven harvest volatility.
- USDA Organic Certification Cost Structure:Three-year transition requirements for conventional farmland impose capital lockup that excludes smaller cooperatives from United States import eligibility.
- Decaffeinated Coffee Substitution:Improved Swiss Water Process availability at mass-market price points captures evening consumption occasions previously reserved for herbal detox formulations.
Strategic Opportunities
- Direct-to-Subscription Channel Innovation:Personalized blend algorithms based on consumer-reported sleep and digestion metrics enable recurring revenue models with higher lifetime value than retail.
- China Functional Beverage Professionalization:Tier-one cities including Shanghai and Beijing exhibit accelerating demand for hepatoprotective positioning among white-collar workers facing intensive work cultures.
- EU Green Deal Packaging Mandates:Extended producer responsibility rules for flexible film waste incentivize investment in compostable sachet materials ahead of regulatory deadlines.
Industry Challenges
- Botanical Identification Skill Gap:Quality control laboratories face acute shortage of taxonomists capable of authenticating dried herb morphology against adulterant substitutes.
- Dual Certification Timeline Compression:Simultaneous pursuit of USDA Organic and Fair Trade certification creates documentation bottlenecks extending new product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detox Tea Market |
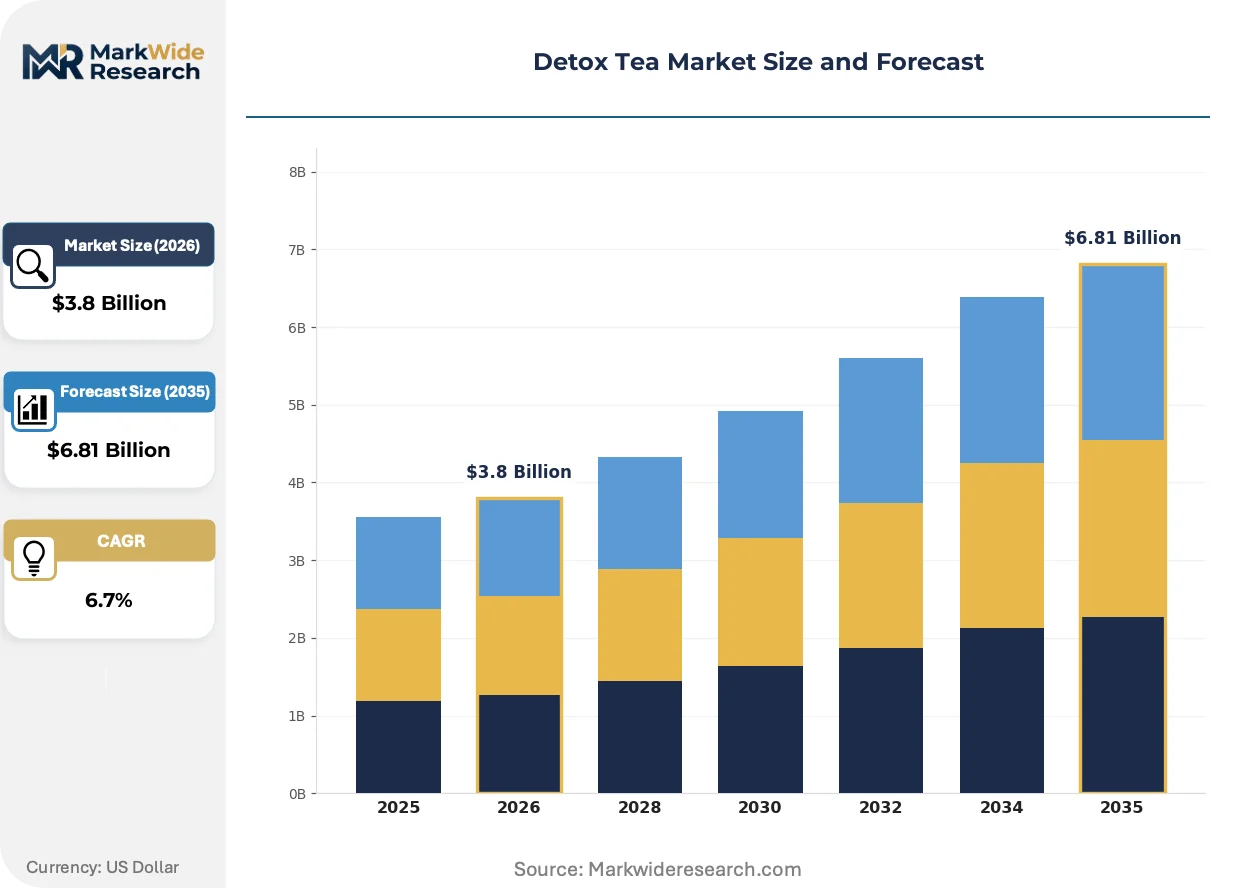
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Green, Black, White Ingredient: Ginger, Turmeric, Mint, Lemongrass Packaging Type: Pouch, Bottle, Canister, Sachet Distribution Channel: Online, Supermarket, Health Food Store, Specialty Store |
| Companies Covered | Yogi Products, Lipton, Pukka Herbs Limited, Choice Organic Teas, Teatulia Tea, R. Twinings, Traditional Medicinals, Tazo Tea Company, Celestial Seasonings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detox Tea Market Emerging Trajectories
Clean-label verification technologies and consumption ritual digitization are converging to reshape how detox tea manufacturers demonstrate value beyond commodity botanical blending. These developments compress the distance between harvest traceability and consumer trust.
Nitrogen-flush packaging with embedded QR-linked batch records is integrating blockchain-verified supply chain data directly into consumer-facing interfaces. Premium wellness brands in Germany are adopting this capability fastest, enabling real-time farm-to-cup transparency that justifies price premiums over unverified competitors. The technology is integrating quality assurance documentation into marketing touchpoints previously reserved for brand storytelling.
EFSA's 2023 guidance on botanical safety assessments is tightening allowable liver health messaging across European retail channels. Manufacturers must now submit full toxicological dossiers for novel ingredients, extending formulation timelines but creating competitive moats for established players with existing approvals. Herbal detox SKUs targeting metabolic support face the steepest compliance burden, accelerating consolidation toward firms with dedicated regulatory affairs capacity.
Subscription personalization based on biomarker feedback loops is displacing static product assortment in direct channels. Consumers in the United States increasingly expect algorithmic blend adjustments tied to self-reported digestion, sleep quality, and energy metrics. This behavior concentrates highest among millennial purchasers in coastal metropolitan markets, where wellness app integration drives retention rates exceeding conventional auto-replenishment models.
Detox Tea Market Segmentation
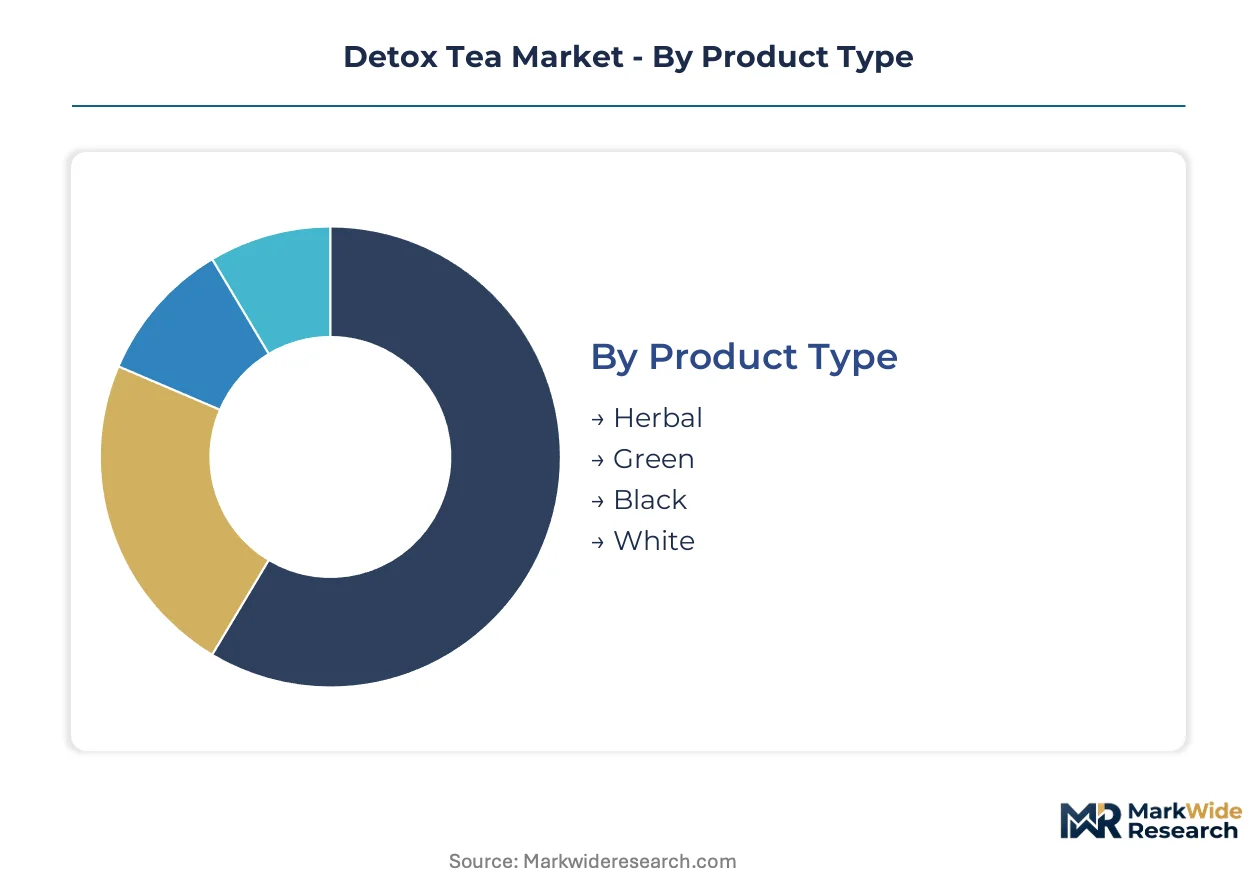
Detox tea manufacturers configure product portfolios across four intersecting dimensions that determine margin structure and channel access. Specification choices in product type and ingredient sourcing create tiered positioning, while packaging and distribution decisions lock in recurring purchase mechanics or gift-market premiums.
Product Type:
Caffeine content and botanical composition define consumption occasion and regulatory classification across manufacturing specifications.
- Herbal:Caffeine-free infusions rely on dried flowers, roots, and leaves without Camellia sinensis. Evening consumption rituals in Germany and the United States concentrate demand here, though EFSA health claims scrutiny constrains liver-support messaging.
- Green:Unoxidized leaves retain EGCG catechin content marketed for antioxidant positioning. White-collar workers in Shanghai and Beijing drive procurement through employer wellness stipends tied to hepatoprotective benefits.
- Black:Fully oxidized leaves deliver higher caffeine suitable for morning consumption occasions. Orthodox processing requirements limit supply to Sri Lankan and Indian growing regions with established orthodox certification.
- White:Minimal processing preserves delicate polyphenol profiles commanding premium pricing. Bud-and-leaf harvesting constraints restrict volume to Fujian province and select Kenyan highland estates.
Herbal leads on scale; green leads on momentum.
Ingredient:
Botanical sourcing geography and phytochemical standardization separate commodity blends from clinically positioned formulations.
- Ginger:Rhizome drying and volatile oil retention specifications vary by end-use. Nigerian and Indian supply chains dominate, with organic certification from Uttar Pradesh commanding price premiums in United States health food retail.
- Turmeric:Curcuminoid standardization to 95% content enables supplement-adjacent positioning. Climate volatility in Andhra Pradesh and Tamil Nadu growing regions exposes processors to harvest-driven cost spikes.
- Mint:Mentha piperita and Mentha spicata varieties serve distinct flavor profiles and digestive positioning. Pacific Northwest cultivation in the United States supplies domestic organic demand, reducing import dependency.
- Lemongrass:Cymbopogon citratus sourcing concentrates in Kerala and Thailand. Lower processing complexity enables competitive entry, compressing margins for undifferentiated bulk supply.
Ginger anchors volume contribution; turmeric expands most quickly through wellness-channel premiumization.
Packaging Type:
Format selection determines shelf-life engineering, portion control economics, and waste-stream compliance obligations.
- Sachet:Individual portion packaging dominates convenience-oriented channels and hospitality procurement. Nitrogen-flush technology with QR-linked batch records enables German premium positioning through traceability claims.
- Canister:Reusable storage formats retain stronger margins in gift segments and specialty retail where perceived value correlates with kitchen-counter visibility. Bulk contents require consumer education on proper storage to preserve volatile oil integrity.
- Pouch:Flexible film formats optimize shipping cube efficiency for direct-to-subscription channels. EU Green Deal extended producer responsibility rules incentivize compostable material investment ahead of regulatory deadlines.
- Bottle:Ready-to-drink liquid formulations capture on-premise consumption and convenience retail. Cold-chain requirements constrain distribution radius and elevate working capital intensity versus dried formats.
Sachet commands unit volume; canister captures value concentration.
Distribution Channel:
Channel selection determines customer acquisition cost structure and data capture depth for personalization algorithms.
- Online:Direct-to-subscription platforms enable algorithmic blend personalization based on self-reported sleep and digestion metrics. Millennial purchasers in coastal United States metropolitan markets drive retention rates exceeding conventional auto-replenishment.
- Supermarket:Mass retail placement requires slotting fee investment and velocity guarantees that exclude smaller organic cooperatives. Clean-label certification from USDA Organic shapes shelf placement eligibility.
- Health Food Store:Curated assortment environments reward botanical sourcing transparency and Fair Trade certification. Traditional Medicinals and Yogi Products anchor premium positioning through supply chain documentation.
- Specialty Store:Tea-specific retail and apothecary formats enable education-intensive purchasing decisions. Ayurvedic-inspired formulations from Pukka Herbs Limited occupy distinct niche positioning in European health food retail.
Online gains share fastest; supermarket retains absolute volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States employer wellness ecosystem is reshaping detox tea procurement patterns, with corporate stipends redirecting volume from conventional retail into institutional channels. Germany's clean-label regulatory environment and China's functional beverage professionalization complete the tripartite demand concentration.
United States
Corporate wellness stipends from human resources departments in San Francisco and New York Metro are creating predictable recurring revenue streams distinct from seasonal retail cycles. FDA Good Manufacturing Practices and USDA Organic certification shape import eligibility and shelf placement across mass retail channels. Pacific Northwest cultivation of organic mint supplies domestic demand, reducing import dependency for key botanical inputs.
Germany
Nitrogen-flush packaging with QR-linked batch records is integrating blockchain-verified supply chain data into consumer-facing interfaces fastest here. EFSA health claims regulation constrains permissible marketing language for digestive benefits, forcing reformulation toward substantiated ingredient dossiers. Berlin and Hamburg anchor premium wellness brand adoption where real-time farm-to-cup transparency justifies price premiums.
China
Tier-one cities including Shanghai and Beijing exhibit accelerating demand for hepatoprotective positioning among white-collar workers facing intensive work cultures. SAMR oversight of functional food claims requires careful navigation of permitted health messaging. Yangtze River Delta manufacturing clusters are scaling low-temperature drying technology to preserve volatile oil integrity for export markets.
United Kingdom
Ayurvedic-inspired formulations occupy distinct niche positioning in London health food retail and apothecary formats. EU Green Deal extended producer responsibility rules for flexible film waste incentivize compostable sachet material investment ahead of regulatory deadlines. Traditional Medicinals and Pukka Herbs Limited anchor supply chain transparency as competitive differentiation.
India
Organic ginger certification from Uttar Pradesh commands price premiums in United States health food retail, with FSSAI standards governing domestic quality benchmarks. Kerala and Tamil Nadu turmeric cultivation faces climate volatility exposing processors to harvest-driven cost spikes. Mumbai and Bangalore processing hubs are consolidating botanical identification capabilities to address quality control skill gaps.
Detox Tea Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance institutional contract requirements against clean-label credentials demanded by benefits administrators. The vendor base organizes across three tiers: certified organic specialists, mass-market commodity blenders, and direct-to-subscription algorithmic platforms. Consolidation pressure is accelerating toward firms with dedicated regulatory affairs capacity. Competitive moves center on M&A for botanical sourcing security and strategic partnerships for biomarker-feedback subscription technology.
Within the certified organic tier, Yogi Products and Traditional Medicinals exemplify supply chain transparency positioning, while Pukka Herbs Limited occupies a distinct Ayurvedic-inspired niche in European health food retail. These entities represent the premium-channel archetype where botanical sourcing documentation commands shelf placement and consumer loyalty. Mass-market volume concentrates with Lipton and Twinings, entities whose scale advantages enable slotting fee investment across supermarket channels. The algorithmic subscription vector remains contested, with Teatulia Tea and Choice Organic Teas representing early movers in personalized blend configurations.
| Leading Market Players |
|---|
| Yogi Products |
| Lipton |
| Pukka Herbs Limited |
| Choice Organic Teas |
| Teatulia Tea |
| R. Twinings |
| Traditional Medicinals |
| Tazo Tea Company |
| Celestial Seasonings |
| Others |
Supply Flow & Price Mechanics
Taxonomist labor scarcity in Mumbai and Bangalore quality control laboratories widens pricing spreads between certified organic premium tiers and undifferentiated commodity blends, as authentication skill premiums compound with USDA Organic certification costs.
Pricing Analysis
Input-cost pass-through from Egyptian and Bulgarian chamomile harvest volatility drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on organic certification grade and botanical sourcing transparency, with EFSA-substantiated liver health claims commanding substantial premiums. Cost compression in economy tiers intensifies because of decaffeinated coffee substitution at mass-market price points. Employer wellness stipend buyers exhibit lowest price sensitivity, while supermarket mass retail shoppers drive hard on unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian organic chamomile and Bulgarian milk thistle, as climate-driven harvest volatility exposes processors to margin squeezes. Geographic supply concentration centers on Nigeria and India for ginger, Andhra Pradesh and Tamil Nadu for turmeric, and Kerala and Thailand for lemongrass. Raw material dependencies hinge on volatile oil retention specifications, curcuminoid standardization, and nitrogen-flush packaging materials. Tariff exposure on flexible film imports from Asia threatens sachet cost structures. Distribution runs through direct-to-subscription platforms for algorithmic personalization, health food retail for transparency premiums, and supermarket mass channels for volume turnover.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detox tea procurement arbitrage between United States employer wellness stipends and European clean-label regulatory premiums rewards players who bridge FDA and EFSA compliance capabilities within unified supply chains.
For Market Incumbents: Acquire dormant organic farmland in Uttar Pradesh to secure ginger supply against climate volatility. Dual certification capacity for USDA Organic and Fair Trade creates defensive moats against commodity blenders. Consolidate taxonomist training programs in Mumbai processing hubs to close botanical identification skill gaps threatening quality control. For New Entrants and Emerging Players: Employer wellness administrators in Germany's Mittelstand sector represent an underserved buyer archetype with predictable recurring revenue potential. White-space concentration sits in algorithmic subscription personalization for white-collar hepatoprotective positioning in China's tier-one cities. Launch through direct-to-subscription channels with biomarker-feedback integration rather than fighting for supermarket shelf space. For Investors and Strategic Acquirers: Beverage conglomerates with existing functional drink portfolios are the most active acquirer in this space, seeking clean-label credibility through certified organic specialists. Long-term viability favors firms with dedicated regulatory affairs capacity spanning FDA, EFSA, and SAMR jurisdictions. Acquisition target archetype: mid-tier organic processors with existing dual certification and underutilized low-temperature drying capacity. Watch for EFSA botanical safety assessment guidance tightening as inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farmland | Uttar Pradesh ginger certification secures supply against Nigerian climate volatility and Indian harvest fluctuations. |
| Dual Certification Investment | Simultaneous USDA Organic and Fair Trade pursuit extends launch timelines but locks in premium-channel shelf placement. |
| Algorithmic Subscription Platform Launch | Biomarker-feedback personalization retains millennial coastal purchasers at rates exceeding conventional auto-replenishment mechanics. |
| Compostable Sachet Material Transition | EU Green Deal extended producer responsibility rules incentivize packaging investment ahead of regulatory deadlines in Germany. |
| Taxonomist Training Program Expansion | Mumbai and Bangalore laboratory capabilities address acute botanical authentication shortages threatening quality control integrity. |
Methodological Framework
Coverage spans the United States, Germany, China, the United Kingdom, and India, with primary inputs from each market combined with secondary validation. Primary interviews engaged brand managers at certified organic specialists, category buyers at health food retail chains, supply planners at mass-market blenders, and regulatory affairs leads navigating EFSA and FDA substantiation requirements. Secondary sources included FDA Good Manufacturing Practice filings, EFSA botanical safety assessment guidance, SAMR functional food claim databases, USDA Organic certification records, and customs trade data on dried herb imports. Bottom-up volume modeling triangulated against top-down value estimates across channel and packaging configurations.
Granularity-level modeling deployed separate forecasts for herbal, green, black, and white tea variants by caffeine content and botanical composition. Projections incorporated employer wellness stipend penetration rates, nitrogen-flush packaging adoption curves, and EFSA health claims compliance timelines as industry-specific inputs. CAGRs were derived from weighted average growth across consumption occasion segments, with evening ritual demand for caffeine-free formulations modeled separately from hepatoprotective green tea positioning among white-collar workers.
Underlying measurement precision varies by segment; direct-to-subscription channels with algorithmic personalization carry tighter precision than fragmented supermarket mass retail. Forecasts reflect assumptions on corporate wellness program expansion, clean-label certification cost trajectories, and climate volatility in Egyptian and Bulgarian growing regions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Africa Tea Market
Tea
Tea Polyphenols Market
Tea
Tea Pitchers Market
Tea
Black Tea Base Bubble Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Global Tea Bag Market
Tea
Fermented Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Green Tea Market
Tea
Instant Tea Premixes Market
Tea
Tea Packaging Market
Tea
North America Ready-To-Drink Tea Market
Tea
White Tea Extract Market
Tea
Green Tea Leaves Market
Tea
Global Tea Extract Market
Tea
Nitro Tea Market