
 Global Ready-To-Drink Green Tea Market | 2026-2036
Global Ready-To-Drink Green Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ready-To-Drink Green Tea Market Outlook
Single-serve bottle downsizing is rebalancing buyer choice toward trial-friendly formats that reduce purchase risk. Ito En, Ltd. leverages its captive Japanese distribution network to sustain shelf dominance in convenience channels. PepsiCo Inc. competes through mass-market pricing that anchors volume in North American grocery retail. Nestlé S.A. differentiates via functional positioning that extends its nutrition credentials into ready-to-drink tea.
Ready-to-drink green tea comprises brewed Camellia sinensis leaf extract, preserved through hot-fill or aseptic processing, and packaged for ambient consumption without reconstitution. The beverage typically contains 20-50 mg of caffeine per 240 ml serving alongside catechins, with pH stabilization ensuring shelf stability for 6-12 months. Bottled formats dominate value capture due to premium positioning in supermarkets and health shops, while aluminum cans represent the fastest-growing packaging type as beverage makers seek recyclability advantages under EU Green Deal requirements. Tetra Pak occupies a stable niche in Asian markets where aseptic carton logistics reduce distribution costs.
Japan's Ministry of Economy, Trade and Industry (METI) enforces labeling standards that shape functional claims on ready-to-drink green tea products, while FDA oversight in the United States governs health claim substantiation and caffeine disclosure. EFSA in Europe evaluates catechin-related health assertions, creating divergence in permissible marketing language across jurisdictions. Stakeholders must monitor evolving packaging regulations and caffeine threshold debates to anticipate reformulation requirements and label redesign cycles.
Market Dynamics
EU Green Deal packaging mandates are forcing beverage manufacturers to abandon multilayer plastic bottles in favor of aluminum and aseptic carton formats, reshaping capital allocation across the ready-to-drink green tea supply base.
Growth Catalysts
- Functional positioning:Health-conscious millennials in Tokyo, Shanghai, and New York seek beverages with verified catechin content and clean-label credentials, pulling premium SKUs into mainstream distribution.
- METI labeling standards:Japan's Ministry of Economy, Trade and Industry permits specific antioxidant claims that differentiate ready-to-drink green tea from commodity soft drinks, anchoring domestic premiumization.
- Hot-fill processing:This preservation technology extends ambient shelf life without artificial preservatives, enabling clean-label formulations that command price premiums in European health channels.
Market Restraints
- Camellia sinensis leaf cost volatility:Weather-driven harvest fluctuations in China's Fujian and Zhejiang provinces create input price instability that compresses blender margins during poor growing seasons.
- Aseptic line capital intensity:Retrofitting existing hot-fill facilities to handle aluminum cans requires $15-25 million per plant, concentrating investment capacity among multinational beverage conglomerates.
- Caffeine threshold debates:Pending EFSA evaluations of high-catechin beverage safety may trigger reformulation mandates that invalidate existing inventory and label inventories across European markets.
Strategic Opportunities
- Vietnamese market penetration:Underdeveloped ready-to-drink tea infrastructure in Ho Chi Minh City and Hanoi offers first-mover positioning before local supply chains mature.
- EU Green Deal recyclability mandates:Packaging regulations favoring aluminum and aseptic cartons create structural advantages for producers with existing canning capabilities or Tetra Pak partnerships.
- Convenience channel digitization:Smart vending networks in Japanese urban centers enable dynamic pricing and consumption-data capture that traditional retail cannot replicate.
Industry Challenges
- Aseptic engineering talent scarcity:Specialized technicians capable of maintaining sterile processing environments command premium wages that inflate operating costs in emerging production facilities.
- Multi-jurisdiction label compliance:Divergent FDA, EFSA, and METI standards for health claims force parallel packaging runs that fragment production economies and complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ready-To-Drink Green Tea Market |
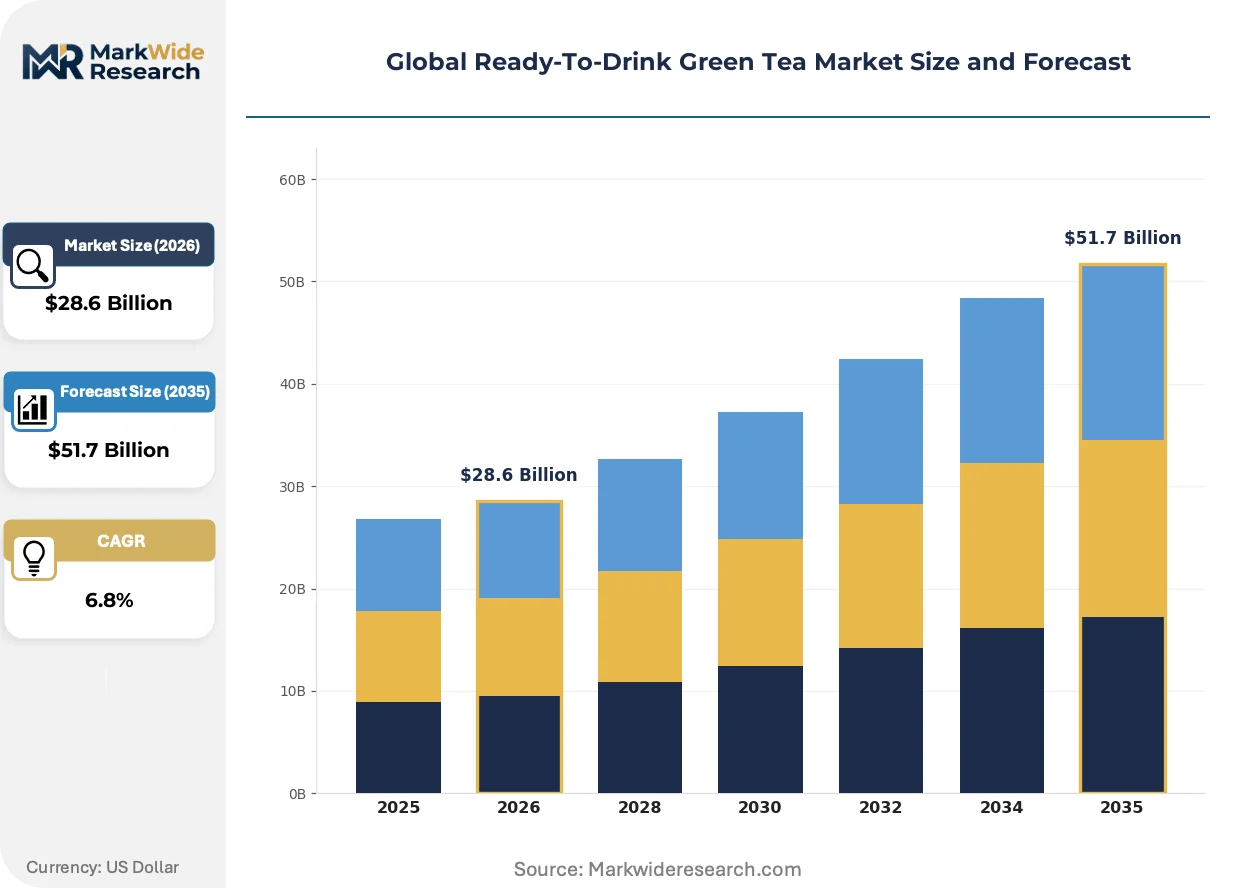
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottled, Canned, Powdered, Concentrate Flavor: Original, Lemon, Mint, Jasmine Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Shops Packaging Type: Glass, Plastic, Tetra Pak, Aluminum |
| Companies Covered | Ito En, Ltd., Suntory Holdings Limited, The Coca-Cola Company, PepsiCo Inc., Nestlé S.A., Unilever PLC, Keurig Dr Pepper Inc., Tata Consumer Products Limited, Asahi Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ready-To-Drink Green Tea Market Strategic Shifts
Processing technology and packaging material selection are converging to redefine shelf-stable beverage economics, with sustainability mandates now dictating equipment investment priorities ahead of pure efficiency metrics.
Aluminum can formats are consolidating market share from multilayer PET bottles as beverage manufacturers respond to EU Green Deal recyclability requirements and consumer backlash against plastic waste. Japanese and South Korean convenience chains are accelerating can adoption for single-serve green tea, compressing the premium positioning gap that historically separated bottled and canned offerings. This format shift is consolidating supply relationships around metal packaging specialists with established aseptic canning capabilities.
EFSA catechin safety evaluations are tightening permissible health claims on ready-to-drink green tea products marketed across European Union member states. Manufacturers must now substantiate antioxidant assertions through clinical dossiers that previously relied on general botanical references, extending product development timelines by 12-18 months. German and French health food retailers are responding by demanding third-party certification that preempts regulatory challenge, filtering smaller suppliers from premium shelf placement.
Urban millennial buyers are rotating consumption toward trial-sized formats that reduce purchase commitment in saturated convenience channels. Japanese metropolitan consumers increasingly favor 200-280ml bottles and slim cans over traditional 500ml servings, forcing distributors to reconfigure planogram space and reorder economics. This behavioral pivot is most visible in Tokyo and Osaka convenience stores, where single-serve SKUs now occupy prime cold-vault positioning previously reserved for volume-tier products.
Global Ready-To-Drink Green Tea Market Segmentation
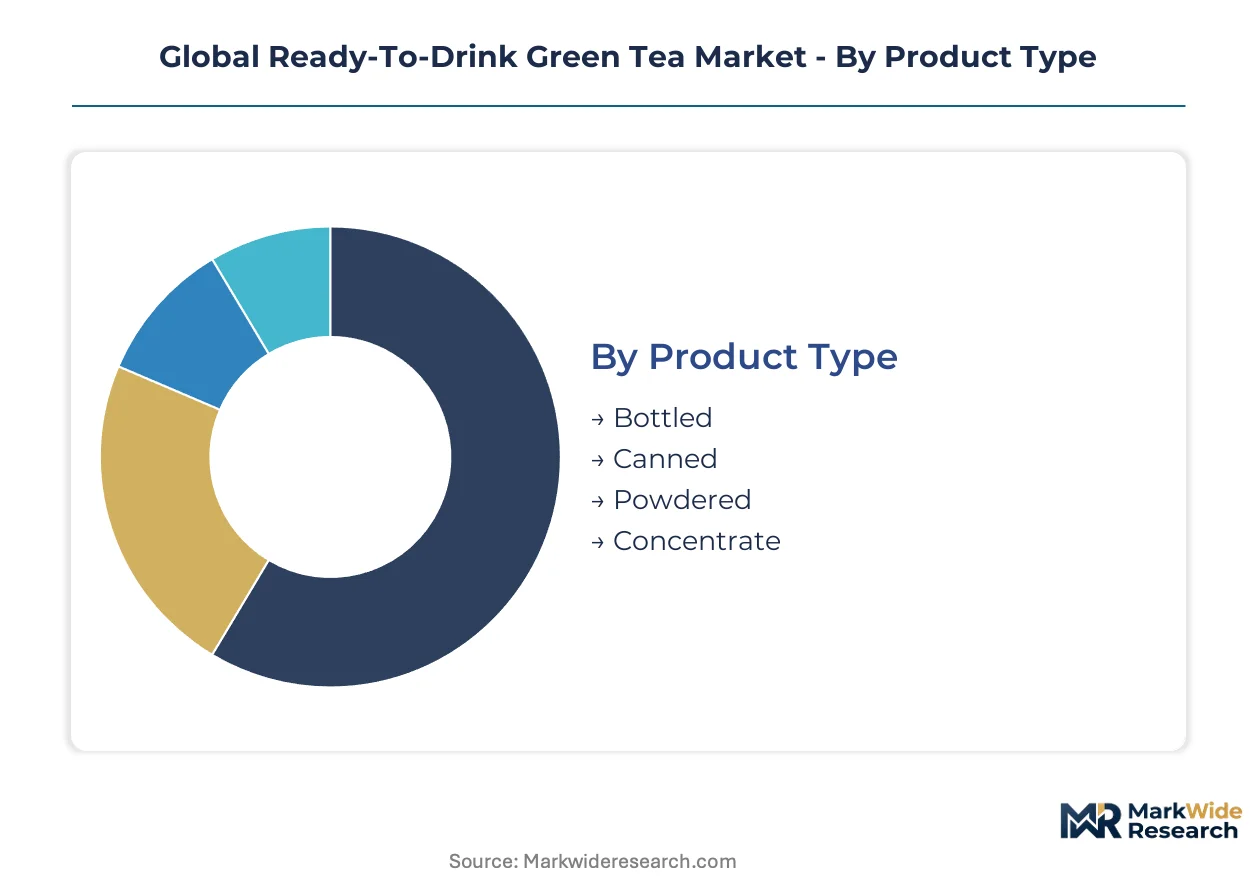
Segmentation in ready-to-drink green tea reveals how processing technology, packaging material science, and channel economics fragment competitive arenas. Manufacturers align capital allocation with specific technical requirements and margin profiles rather than pursuing universal positioning.
Product Type:
Hot-fill and aseptic processing technologies create distinct equipment requirements and shelf-life capabilities across formats.
- Bottled:Multilayer PET and glass containers dominate premium supermarket placement. Japanese convenience chains favor 280ml formats that command chilled-section positioning in Tokyo and Osaka.
- Canned:Aluminum formats enable rapid thermal processing and align with EU Green Deal recyclability mandates. South Korean convenience stores are accelerating adoption as beverage makers abandon multilayer plastic.
- Powdered:Freeze-dried extract formulations target foodservice and at-home reconstitution. Hotel chains in Southeast Asia deploy single-serve sachets for in-room beverage programs.
- Concentrate:Liquid extract concentrates serve industrial blending and fountain applications. Bubble tea chains in Taiwan source bulk concentrate for menu standardization.
Bottled formats lead on scale; canned formats lead on momentum.
Flavor:
Botanical infusions and citrus additions alter extraction protocols and stability requirements during formulation.
- Original:Unflavored Camellia sinensis extract maintains the highest catechin integrity. German health food retailers demand third-party certification for antioxidant content claims.
- Lemon:Citric acid integration requires pH buffering to prevent catechin degradation. French supermarkets position lemon variants as gateway SKUs for soft drink converts.
- Mint:Menthol compounds interact with bitterness perception, enabling reduced-sugar positioning. UAE hospitality channels favor mint formulations for regional palate alignment.
- Jasmine:Scented variants demand controlled aroma infusion during processing. Shanghai consumers demonstrate strong preference for jasmine-scented offerings in traditional tea shops.
Original formulations anchor volume; jasmine variants climb fastest in Asian urban centers.
Distribution Channel:
Channel selection determines packaging format, pricing architecture, and promotional investment intensity.
- Supermarkets:Multi-pack configurations and promotional stacking dominate volume. US grocery retailers anchor pricing through mass-market private label placement.
- Convenience Stores:Single-serve cold-vault positioning commands impulse purchase behavior. Japanese smart vending networks enable dynamic pricing unavailable in traditional retail.
- Online Retailers:Subscription models and variety packs reduce customer acquisition costs. Direct-to-consumer channels in Vietnam bypass underdeveloped traditional distribution infrastructure.
- Health Shops:Functional positioning and clean-label credentials justify premium pricing. EFSA-compliant antioxidant claims filter smaller suppliers from premium shelf placement.
Supermarkets capture absolute volume; online channels expand most quickly in emerging markets.
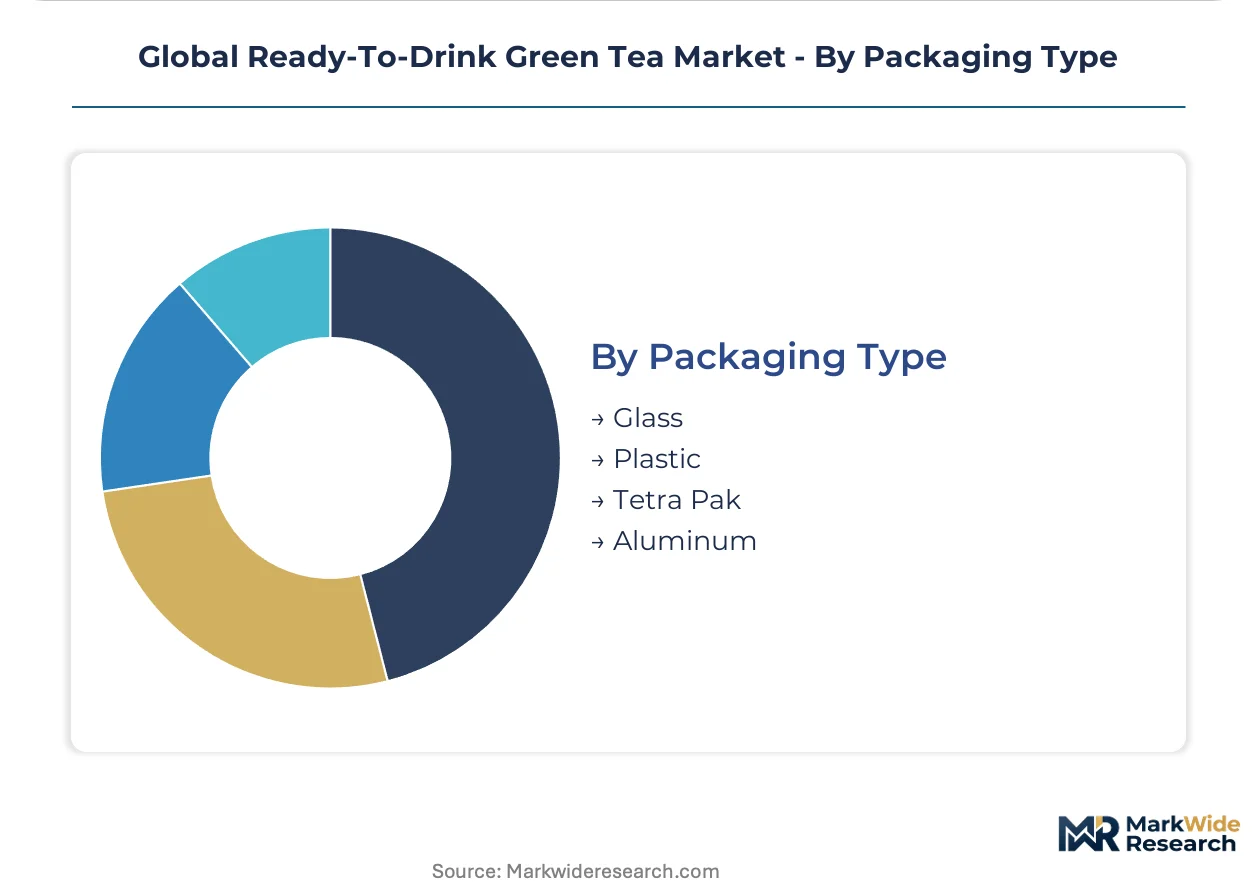
Packaging Type:
Material selection now reflects regulatory compliance and circular economy requirements ahead of pure cost optimization.
- Glass:Inert barrier properties preserve flavor integrity across extended shelf life. Premium health shops in France and Germany favor glass for perceived quality signaling.
- Plastic:Multilayer PET faces abandonment under EU Green Deal mandates. Existing hot-fill lines require retrofit investment to transition toward alternative formats.
- Tetra Pak:Aseptic carton logistics reduce distribution costs in Asian markets. Tetra Pak partnerships create structural advantages for producers seeking Asian market penetration.
- Aluminum:Infinite recyclability aligns with EU Green Deal requirements and consumer backlash against plastic. Japanese and South Korean convenience chains compress the premium gap between canned and bottled offerings.
Plastic retains installed base dominance; aluminum gains share fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial ready-to-drink green tea bottling in the 1980s, establishing the processing standards and distribution infrastructure that later diffused to China, South Korea, and Western markets. This historical foundation created persistent competitive advantages in formulation expertise and captive retail networks that shape contemporary market dynamics.
Japan
Tokyo and Osaka convenience stores anchor single-serve consumption patterns that favor 200-280ml formats with functional catechin claims. METI labeling standards permit specific antioxidant assertions unavailable in other jurisdictions, reinforcing domestic premiumization. Chubu-Nagoya industrial corridors concentrate aseptic processing equipment manufacturing that supplies regional bottling facilities.
China
Shanghai and Beijing urban millennials drive demand for jasmine-scented and original formulations in modern trade channels. The country's national food safety regulator enforces progressively stricter additive disclosure requirements that accelerate clean-label adoption. Fujian and Zhejiang provinces supply Camellia sinensis leaf extract that feeds domestic blending operations and export-oriented processing.
United States
FDA oversight of health claim substantiation and caffeine disclosure shapes permissible marketing language for functional positioning. Mass-market grocery retail in California and New York Metro anchors volume through promotional stacking and private label placement. Pacific Northwest beverage innovation clusters experiment with cold-brew extraction methods for premium channel distribution.
Germany
EFSA catechin safety evaluations tighten permissible antioxidant claims, forcing clinical dossier preparation that extends product development timelines. Health food retailers in Bavaria and North Rhine-Westphalia demand third-party certification that filters smaller suppliers from premium shelf placement. Berlin-Brandenburg logistics hubs coordinate aluminum can distribution compliant with EU Green Deal recyclability mandates.
Vietnam
Ho Chi Minh City and Hanoi present underdeveloped ready-to-drink tea infrastructure where first-mover positioning precedes local supply chain maturation. Direct-to-consumer online channels bypass fragmented traditional distribution networks in emerging urban centers. Central Highlands tea-growing regions provide raw material proximity that reduces extraction logistics costs for prospective entrants.
Global Ready-To-Drink Green Tea Market Competitive Environment
Premium-margin players sit above commodity-margin players across functional positioning and distribution channel depth, with Japanese beverage conglomerates commanding convenience network access that multinational soft drink giants replicate through grocery retail scale. The vendor base concentrates around three strategic archetypes: captive distribution network operators, mass-market price anchors, and functional nutrition credential extenders. Dominant competitive moves include aluminum can format transitions compliant with EU packaging mandates and aseptic line retrofit investments that concentrate capacity among capital-rich participants.
Within the captive distribution tier, Ito En, Ltd. and Suntory Holdings Limited exemplify Japanese market architecture where metropolitan convenience channel penetration creates defensive positioning. PepsiCo Inc. anchors the mass-market vector through grocery retail pricing power that sustains volume capture in North American markets. Nestlé S.A. occupies the functional nutrition extension position, leveraging existing health credential infrastructure into ready-to-drink tea categories. These three corporate structures collectively illustrate how geographic origin and legacy business model shape competitive approach without requiring identical strategic execution.
| Leading Market Players |
|---|
| Ito En, Ltd. |
| Suntory Holdings Limited |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Nestlé S.A. |
| Unilever PLC |
| Keurig Dr Pepper Inc. |
| Tata Consumer Products Limited |
| Asahi Group Holdings, Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recyclability mandates gate both qualified supply and premium-tier pricing access, concentrating procurement relationships around aluminum canning specialists and Tetra Pak partners while excluding multilayer PET-dependent blenders from European health channel placement. This regulatory filter compresses margin structures for non-compliant producers while rewarding capital-rich participants with retrofit capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant antioxidant-certified offerings from mass-market grocery placements and private-label commodity tiers. Price differentiation rests on catechin verification protocols and clean-label credentials rather than brand heritage alone. Pricing pressure stems from aseptic line capital intensity that concentrates volume leverage among multinational conglomerates. Convenience channel buyers in Japanese urban centers demonstrate lowest price sensitivity, while US grocery retail anchors exhibit highest elasticity to promotional stacking.
Supply Chain Analysis
EFSA catechin certification and METI labeling compliance gate supplier qualification, filtering smaller blenders from premium European and Japanese shelf placement. Geographic supply concentration centers on China's Fujian and Zhejiang provinces for Camellia sinensis leaf extract, Japan's Chubu-Nagoya corridor for aseptic processing equipment, and South Korea for aluminum canning infrastructure. Raw material dependencies include weather-sensitive tea leaf harvests, pH stabilization compounds, and aroma infusion agents. Supply chain risk manifests in single-source vulnerability to Fujian province harvest fluctuations. Distribution runs through Japanese captive convenience networks, North American grocery retail, and emerging direct-to-consumer channels in Vietnamese urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by health-conscious millennial consumption patterns that sustain premium-tier pricing power across economic cycles.
For Market Incumbents: Extend functional positioning into verified catechin claims that preempt EFSA regulatory tightening, while retrofitting hot-fill lines toward aluminum canning capabilities before EU Green Deal enforcement hardens. Aluminum format transition represents the critical capacity lever. Consolidate supply relationships with Fujian province extract processors to hedge harvest volatility exposure.
For New Entrants and Emerging Players: EU Green Deal packaging mandates in Europe open a window for aluminum-can-native producers to capture premium health channel placement before incumbent retrofit cycles complete. Vietnamese direct-to-consumer online channels present the most penetrable white-space, bypassing fragmented traditional distribution. Target Ho Chi Minh City and Hanoi with subscription-based trial formats that reduce customer acquisition costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extract processors with captive Fujian province supply relationships but lacking downstream brand infrastructure. Long-term viability frames around 5-10 year horizon consolidation toward vertically integrated beverage conglomerates. Watch EFSA catechin safety evaluation outcomes as the inflection signal that triggers reformulation capex cycles and inventory write-downs.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Can Format Transition | EU Green Deal compliance secures premium European health channel access against PET-dependent competitors. |
| Aseptic Line Retrofit Investment | Hot-fill to aluminum canning conversion concentrates capacity among capital-rich multinational beverage conglomerates. |
| EFSA-Compliant Antioxidant Certification | Clinical dossier preparation extends product development timelines but filters smaller suppliers from premium placement. |
| Vietnamese Direct-to-Consumer Launch | Online subscription models bypass underdeveloped traditional distribution infrastructure in Ho Chi Minh City. |
| Fujian Province Supply Integration | Backward integration into Camellia sinensis leaf extraction hedges weather-driven harvest cost volatility. |
Study Parameters
Direct dialogue with beverage R&D directors, Japanese convenience chain category managers, European health food retail buyers, and Tetra Pak packaging engineers grounded qualitative assessment, cross-referenced with METI regulatory filings, EFSA safety evaluation dossiers, EU Green Deal implementation texts, and customs trade data for extract imports. Secondary validation drew from SEC 10-K disclosures of multinational beverage conglomerates and Nielsen retail audit data for channel volume estimation. Bottom-up SKU-level modeling and top-down category sizing triangulated market dimensions.
Bottom-up volume builds aggregated individual SKU velocity across convenience, grocery, online, and health shop channels, while top-down macro constraints anchored aggregate category ceiling. Segmentation modeling spanned processing technology, packaging material, flavor variant, and distribution channel dimensions across the projection horizon. CAGRs derived from trend extrapolation of per-capita consumption intensity, urban millennial population growth, and regulatory enforcement timelines. Forecast inputs incorporated aseptic line capacity expansion announcements and EU packaging mandate phase-in schedules.
Revisions become necessary when EFSA catechin safety evaluations trigger reformulation mandates, Fujian province harvest failures disrupt extract supply, or EU Green Deal enforcement accelerates beyond modeled timelines. A model refresh is warranted upon material change in Japanese convenience channel digitization adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Probiotic Tea Market
Tea
Nitro Tea Market
Tea
South America Tea Market
Tea
Black Tea Extracts Market
Tea
High Protein Tea Market
Tea
Kombucha Tea Market
Tea
Detox Tea Market
Tea
Green Tea Bag Market
Tea
Out of Home Tea Market
Tea
Tea Subscription Market
Tea
Asia-Pacific Organic Tea Market
Tea
Asia-Pacific Tea Market
Tea
Instant Tea Market
Tea
North America Tea Market
Tea
Europe Tea Market
Tea
Fermented Tea Market