
 Pu-Erh Tea Market | 2026-2036
Pu-Erh Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Pu-Erh Tea Market Analysis
China's Geographical Indication (GI) certification for Yunnan-origin pu-erh is redrawing competitive boundaries among producers. Menghai Tea Factory leverages its state-issued GI license and decades-old fermentation cellars to command premium positioning in aged ripe pu-erh. Dayi Tea Group anchors the mass-market tier through standardized factory production and nationwide distribution depth. Xiaguan Tea Factory specializes in compressed tuo cha formats that dominate transit and gift channels across southwestern China.
Pu-erh tea comprises Camellia sinensis var. assamica leaves harvested in Yunnan province, with microbial post-fermentation driving chemical transformation of polyphenols and theaflavins over months to decades of controlled aging. Raw pu-erh retains enzymatic activity for natural oxidation, while ripe pu-erh undergoes accelerated wo dui piling to simulate extended aging within weeks. Compressed formats—cakes, bricks, and tuo cha—dominate value pools due to collector premiums and storage efficiency, though loose leaf is gaining traction in specialty tea shops seeking brewing convenience. Organic grades command outsized margins despite smaller volume, reflecting pesticide-conscious buyers in tier-one cities.
China's SAMR enforces GB standards for maximum residue limits and geographical origin labeling, while the General Administration of Customs regulates cross-border e-commerce exports through bonded warehouse requirements. These frameworks compel smaller workshops to invest in laboratory testing or exit formal channels entirely. Stakeholders must monitor how GI enforcement evolves and whether aging-claim verification systems emerge as a new gate for market access.
Market Dynamics
China's tightening geographical indication enforcement for Yunnan-origin pu-erh is restructuring competitive access, forcing non-compliant producers toward informal channels or costly facility upgrades.
Growth Catalysts
- GB Standards Harmonization:SAMR's unified residue limit protocols reduce testing fragmentation across provincial borders, streamlining formal channel entry for mid-sized workshops.
- Collector Capital Rotation:Guangdong's tea trading houses are expanding aged inventory warehousing as alternative asset allocation deepens among Shenzhen and Guangzhou investors.
- Compressed Format Premiums:Cake and brick formats command sustained collector premiums due to storage efficiency and provenance verification advantages over loose leaf alternatives.
Market Restraints
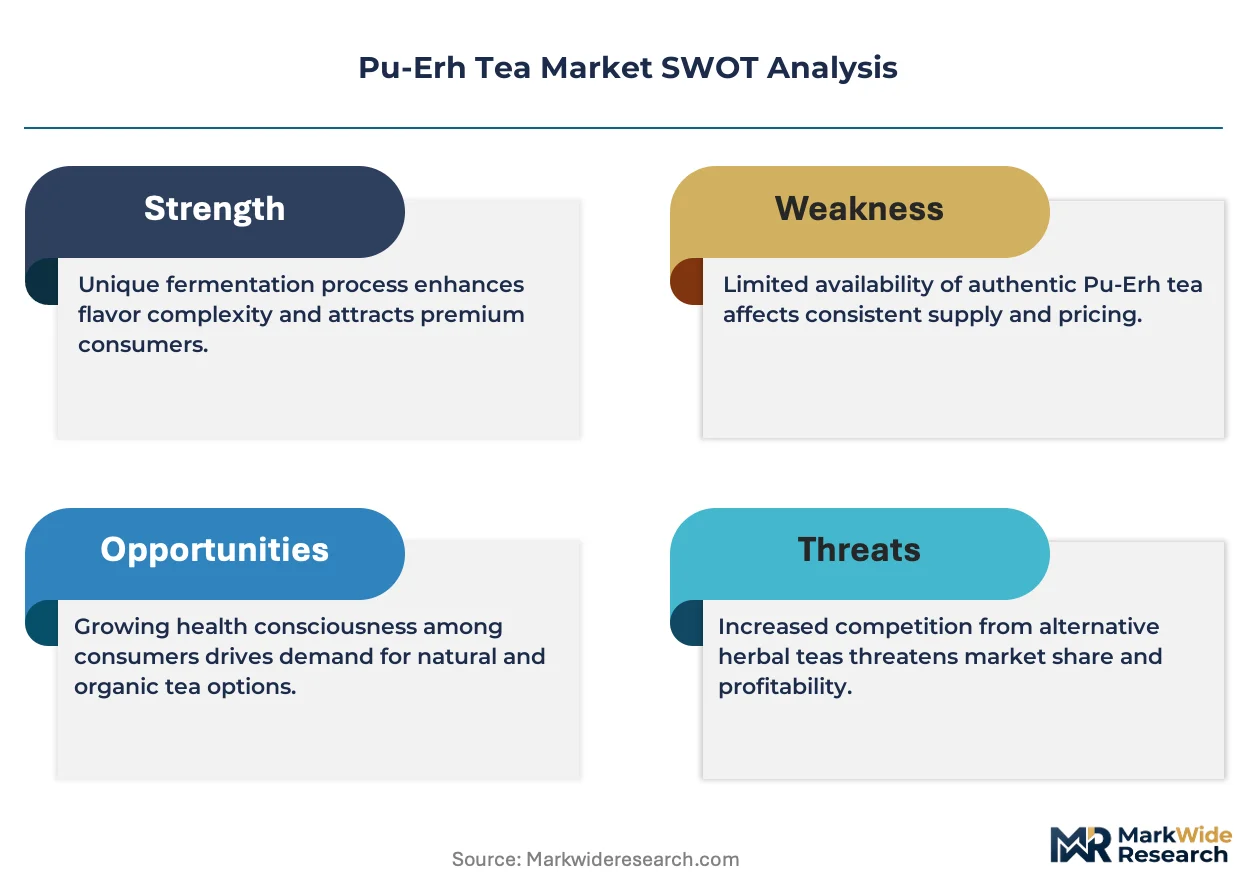
- Input Cost Volatility:Old-growth arbor tree leaf prices fluctuate with Yunnan's harvest yields, compressing margins for raw pu-erh specialists dependent on ancient tree material.
- Supply Concentration Risk:Menghai County's fermentation cellar infrastructure dominates ripe pu-erh production, creating single-point vulnerability for accelerated aging capacity.
- Substitution Threat:Aged white tea from Fujian attracts overlapping collector capital seeking lower entry price points with comparable aging narratives.
Strategic Opportunities
- Cross-Border E-Commerce Channels:Bonded warehouse requirements under China's General Administration of Customs enable direct-to-consumer export models bypassing traditional wholesale layers.
- Organic Grade Penetration:Pesticide-conscious buyers in tier-one cities create margin expansion potential for certified organic production despite smaller absolute volumes.
- Wo Dui Process Innovation:Convergence of controlled humidity systems with traditional piling techniques offers quality consistency improvements for ripe pu-erh acceleration.
Industry Challenges
- Master Blender Scarcity:The craft of recipe formulation for consistent aged flavor profiles lacks formal training pipelines, constraining quality scale-up.
- Aging-Claim Verification:Absence of standardized vintage authentication systems invites mislabeling disputes that erode collector trust and transaction liquidity.
- Legacy Storage Integration:Traditional dry-storage facilities in Kunming face retrofit costs to meet modern humidity monitoring requirements for export-grade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pu-Erh Tea Market |
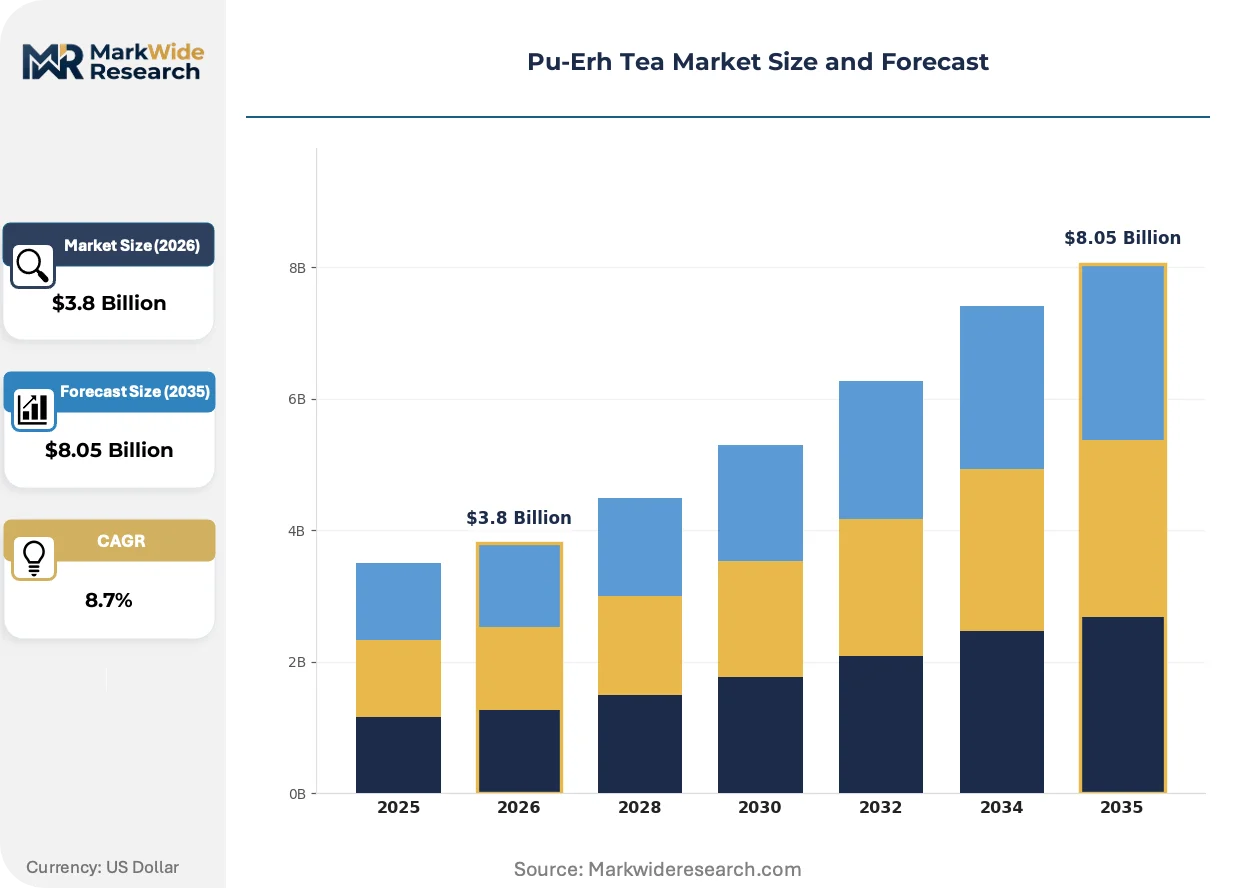
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Pu-Erh, Ripe Pu-Erh, Loose Leaf, Compressed End User: Households, Specialty Tea Shops, Restaurants, Cafes Quality Grade: High Grade, Medium Grade, Low Grade, Organic Packaging Type: Tea Bags, Bulk Packs, Gift Sets, Loose Packs |
| Companies Covered | Menghai Tea Factory, Xiaguan Tea Factory, Dayi Tea Group, Liming Tea Factory, Zhongcha Tea Factory, Haiwan Tea Factory, Lancang Ancient Tea Company, Longrun Tea Group, Chenshenghao, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pu-Erh Tea Market Emerging Trajectories
Digital provenance tracking and fermentation process control are converging to reshape how aged pu-erh authenticity and quality are guaranteed across collector and retail channels.
Blockchain-based origin verification is decomposing the information asymmetry that previously advantaged established trading houses with direct Yunnan supplier relationships. Collector buyers in Guangdong and Beijing are piloting these systems for high-value vintage transactions. The technology is compressing due diligence timelines and enabling fractional ownership models previously impractical without trusted third-party authentication.
China's SAMR is intensifying GB standards enforcement for geographical indication labeling, compelling producers outside Yunnan to rebrand or relocate processing facilities. The regulation creates compliance cost tiers that favor scaled operators with in-house testing laboratories. Smaller workshops in Guangxi and Sichuan are exiting formal distribution channels rather than absorbing certification investments.
Specialty tea shops in tier-one cities are unbundling traditional wholesale relationships to source directly from designated Yunnan production zones. This channel disintermediation replaces multi-layer distributor markups with transparent origin premiums paid to specific mountain villages. The pattern concentrates in Shanghai and Hangzhou where consumer education levels support single-origin storytelling at retail.
Pu-Erh Tea Market Segmentation
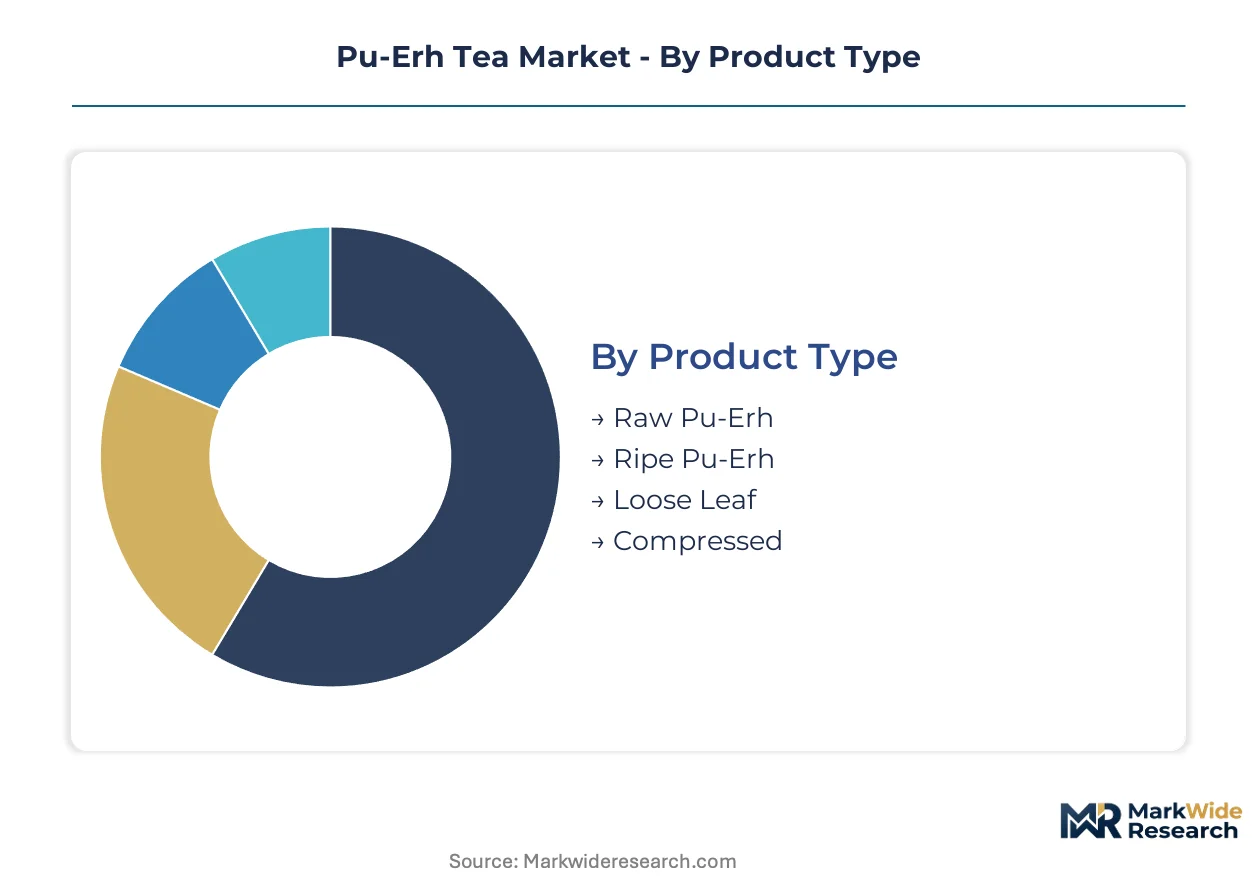
Pu-erh's value architecture fragments across fermentation states, compression formats, and aging grades. Each segment carries distinct margin profiles and collector liquidity characteristics that shape producer investment priorities.
Product Type:
Compressed formats and aged raw pu-erh capture the deepest margin pools, driven by provenance verification premiums and warehousing economics that reward patient capital.
- Raw Pu-Erh:Sun-dried maocha retains enzymatic activity for decades-long oxidation, with ancient tree material from Yunnan's Bulang and Yiwu mountains commanding collector premiums. Guangdong trading houses rotate capital into vintage raw cakes as alternative assets.
- Ripe Pu-Erh:Wo dui piling accelerates fermentation through controlled humidity and microbial inoculation, compressing aging from decades to weeks. Menghai County's cellar infrastructure dominates production capacity for this segment.
- Loose Leaf:Brewing convenience drives specialty tea shop procurement in Shanghai and Hangzhou, though storage efficiency disadvantages limit collector premiums.
- Compressed:Cake, brick, and tuo cha formats dominate value pools through provenance verification advantages and space-efficient warehousing for long-term aging.
Compressed formats hold installed capacity. Ripe pu-erh is rotating up the share rankings.
End User:
Collector-facing channels concentrate margin capture, while foodservice volumes anchor baseline production scale for factory operators.
- Households:Direct-to-consumer e-commerce channels bypass wholesale markups for educated buyers in tier-one cities, with bonded warehouse exports expanding cross-border access.
- Specialty Tea Shops:Single-origin sourcing from designated Yunnan villages replaces traditional distributor relationships, with transparent mountain premiums replacing opaque multi-layer markups.
- Restaurants:Standardized ripe pu-erh dominates banquet service in Guangdong, where digestive properties anchor post-meal service rituals.
- Cafes:Younger consumers in Beijing and Shenzhen experiment with pu-erh lattes and cold-brew formats, though volumes remain marginal to traditional consumption.
Specialty tea shops hold installed capacity. Household direct channels are rotating up the share rankings.
Quality Grade:
Organic certification and ancient tree provenance define the steepest price gradients, with pesticide-conscious buyers in coastal cities absorbing substantial premiums.
- High Grade:Ancient arbor tree material from restricted harvest zones carries documented village provenance, with Menghai and Lancang county origins commanding auction premiums.
- Medium Grade:Plantation-grown assamica from certified Yunnan zones balances quality consistency with accessible price points for regular consumption.
- Low Grade:Blended material from multiple harvest zones serves mass-market brick production and foodservice bulk requirements.
- Organic:Certified pesticide-free production from designated ecological zones targets health-conscious buyers in Shanghai and Hangzhou despite smaller absolute volumes.
High grade holds installed capacity. Organic certification is rotating up the share rankings.
Packaging Type:
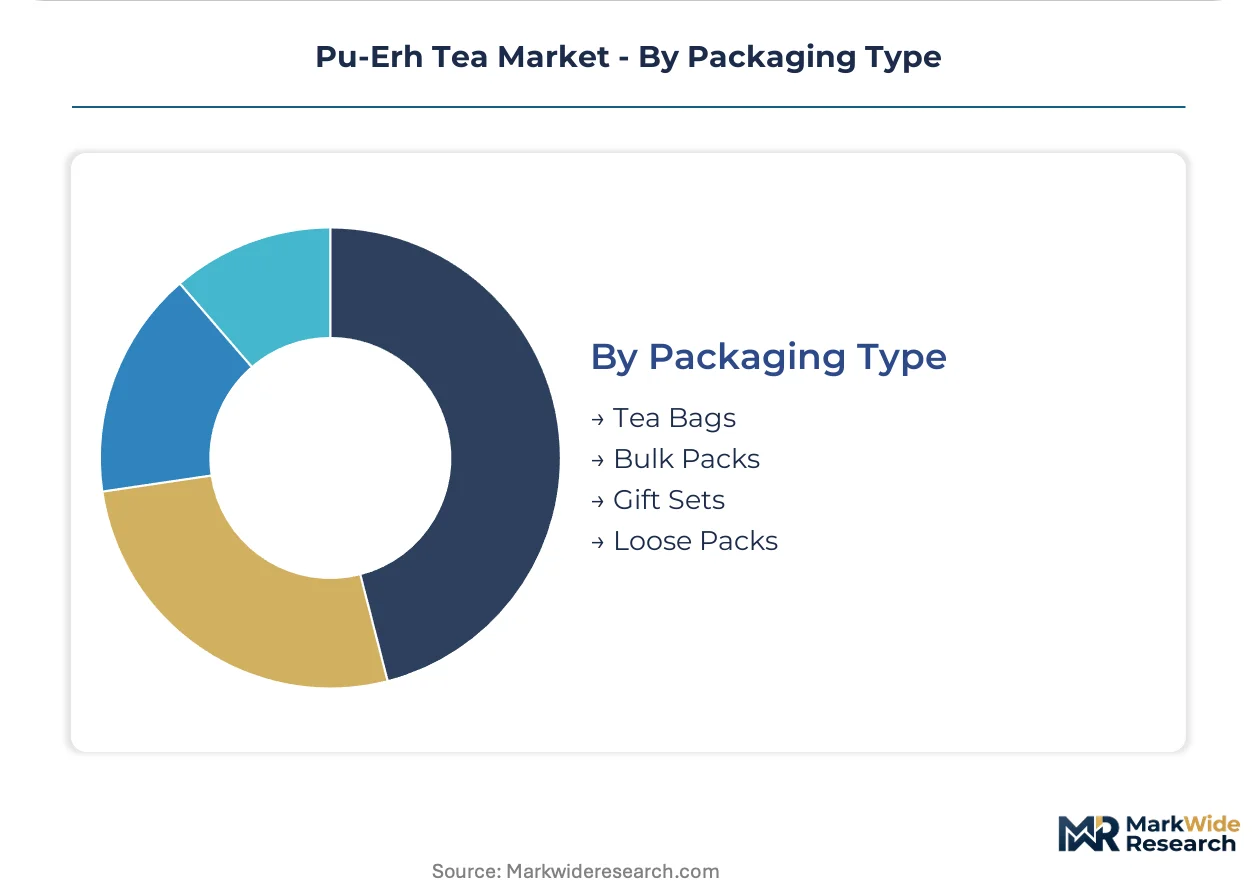
Gift-oriented formats and bulk warehousing configurations split the value architecture between ceremonial occasion purchasing and collector-scale inventory accumulation.
- Tea Bags:Convenience formats target office consumption and travel use, though purist buyers reject paper flavor contamination and restricted leaf expansion.
- Bulk Packs:Kilogram-scale loose leaf or cake quantities serve collector warehousing and restaurant service volumes with per-gram cost efficiency.
- Gift Sets:Ceremonial packaging with origin documentation and vintage certificates dominates Lunar New Year and business relationship gifting in Guangdong.
- Loose Packs:Simple sealed pouches of loose leaf target trial purchases and brewing convenience for specialty shop retail shelves.
Gift sets hold installed capacity. Bulk packs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tightening geographical indication enforcement for Yunnan-origin pu-erh is restructuring competitive access across major consuming markets, with regulatory frameworks in producer and buyer countries reshaping trade flows and investment patterns.
China
Guangdong province concentrates demand through established trading hubs in Guangzhou and Shenzhen where collector capital rotates into aged inventory as alternative asset allocation. SAMR enforces GB standards for residue limits and origin labeling that compel facility upgrades among Yunnan producers. Menghai County's fermentation cellar infrastructure dominates ripe pu-erh production capacity.
United States
Specialty tea shops in California and New York Metro drive direct-to-consumer procurement of certified Yunnan-origin cakes through cross-border e-commerce channels. FDA regulates imported tea under the Food Safety Modernization Act with foreign supplier verification requirements. Los Angeles and San Francisco anchor West Coast distribution networks for aged pu-erh collector circles.
Japan
Connoisseur demand in Tokyo and Osaka supports premium pricing for documented vintage raw cakes from specific Yunnan mountain villages. METI oversees food import standards and pesticide residue testing protocols for tea products. Kansai region's traditional tea houses maintain dedicated storage facilities for long-term aging of compressed formats.
United Kingdom
London's specialty retailers and auction houses facilitate collector-grade transactions with provenance documentation requirements. Food Standards Agency enforces EU-originated maximum residue limits and labeling regulations for imported tea. Southeast England's warehousing clusters serve European distribution for bonded inventory holdings.
South Korea
Seoul Capital Area's tea culture revival drives demand for high-grade raw pu-erh among younger consumers seeking wellness positioning. MFDS regulates food imports with strict pesticide testing and geographical origin verification. Busan-Ulsan corridor's logistics infrastructure supports re-export trade to other Northeast Asian markets.
Pu-Erh Tea Market Vendor Landscape
Player mix skews toward state-affiliated heritage manufacturers with decades-old fermentation infrastructure and emerging private-label specialists targeting direct-to-consumer channels. Market structure concentrates around Yunnan-based producers holding SAMR-issued geographical indication licenses, with tiered competition separating vintage inventory holders from mass-market processors. Strategic archetypes include heritage state factories with legacy cellar assets, mountain-village cooperatives with ancient tree access, and cross-border e-commerce brands bypassing traditional wholesale layers. Dominant competitive moves center on GI certification acquisition and bonded warehouse capacity expansion for export-grade production.
Among Yunnan-based heritage producers, Menghai Tea Factory and Dayi Tea Group occupy positions representing the licensed manufacturer archetype with state-issued geographical indication credentials and established fermentation infrastructure. Xiaguan Tea Factory exemplifies the format-specialist segment through its concentration on compressed tuo cha configurations. These entities anchor competitive positioning across premium and mass-market tiers without specific product or financial claims attaching to individual operations.
| Leading Market Players |
|---|
| Menghai Tea Factory |
| Xiaguan Tea Factory |
| Dayi Tea Group |
| Liming Tea Factory |
| Zhongcha Tea Factory |
| Haiwan Tea Factory |
| Lancang Ancient Tea Company |
| Longrun Tea Group |
| Chenshenghao |
| Others |
Supply Flow & Price Mechanics
Old-growth arbor leaf substitution for plantation-grade material simultaneously concentrates supply geography around Yunnan's Bulang and Yiwu mountain zones while steepening price gradients for documented village provenance. This input replacement dynamic compresses margins for mass-market processors while amplifying collector premiums for heritage inventory holders.
Pricing Analysis
Geographical indication certification level creates the primary spread between formal channel and gray-market pricing tiers. Three-tier pricing structure across premium, standard, and economy levels segments raw pu-erh by harvest zone documentation and fermentation cellar credentials. Pricing pressure stems from old-growth material scarcity as Guangdong trading houses rotate capital into aged inventory. Household direct-to-consumer buyers exhibit highest price sensitivity, while collector-facing channels absorb substantial premiums for verified vintage documentation.
Supply Chain Analysis
Yunnan province anchors raw material cultivation and fermentation infrastructure, with Guangdong province dominating warehousing and distribution for aged inventory. The supply chain draws from ancient arbor tree zones, plantation-grade assamica fields, and Menghai County's wo dui piling cellars. Single-source vulnerability concentrates in Menghai's accelerated aging capacity for ripe pu-erh production. Distribution runs through Guangzhou and Shenzhen trading houses for wholesale allocation, with bonded warehouse channels expanding direct-to-consumer export reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where SAMR's geographical indication enforcement creates switching costs that entrench licensed Yunnan producers against non-compliant competitors.
For Market Incumbents: Fortify cellar infrastructure in Menghai County against supply concentration risk while acquiring blockchain provenance capabilities to preempt mislabeling disputes. Backward integration into designated mountain village harvest zones secures raw material access as SAMR tightens origin verification requirements. Channel control through direct-to-consumer e-commerce platforms bypasses wholesale margin compression. For New Entrants and Emerging Players: Organic certification fast-track through designated ecological zones opens penetrable white space in tier-one cities where pesticide-conscious buyers absorb outsized premiums. Specialty tea shop direct sourcing in Shanghai and Hangzhou replaces opaque distributor relationships with transparent mountain premiums. Cross-border e-commerce bonded warehouse models bypass entrenched Guangdong trading house layers for export market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-label specialists holding cross-border e-commerce capabilities and GI-compliant processing infrastructure. Long-term viability centers on regulatory entrenchment through SAMR licensing and vintage inventory warehousing economics. The signal to watch is emergence of standardized aging-claim verification systems that would reshape collector trust and transaction liquidity.| Strategic Initiative | Industry Significance |
|---|---|
| GI Certification Acquisition | SAMR licensing creates formal channel access barriers against non-compliant competitors. |
| Bonded Warehouse Expansion | General Administration of Customs frameworks enable direct-to-consumer export bypassing wholesale layers. |
| Blockchain Provenance Deployment | Digital verification compresses due diligence timelines for high-value vintage transactions. |
| Organic Grade Scale-Up | Certified production targets pesticide-conscious buyers in Shanghai and Hangzhou premium segments. |
| Mountain Village Integration | Direct sourcing from designated Yunnan zones replaces opaque multi-layer distributor markups. |
Methodological Framework
Initial hypotheses were tested against primary input from tea factory production managers, Guangdong trading house procurement directors, SAMR regulatory affairs specialists, and specialty tea shop buyers in tier-one cities and refined through secondary validation. Data synthesis combined customs export records, GB standards documentation, bonded warehouse filings, and collector auction transaction databases. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Variance decomposition across fermentation state, compression format, quality grade, and regional consumption patterns anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating inventory aging economics, collector capital rotation patterns, and regulatory enforcement intensity. Industry-specific inputs included wo dui piling capacity utilization rates and GI license issuance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained SAMR enforcement intensity and stable Guangdong collector capital allocation; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in geographical indication regulation and cross-border e-commerce policy frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
High Protein Tea Market
Tea
Kombucha Tea Market
Tea
Oolong Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Europe Green Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Africa Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Tea Infuser Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Tea Packaging Market
Tea
Instant Tea Premix Consumption Market
Tea
Pyramid Tea Bags Market
Tea
Green Tea Extract Market
Tea
Smart Tea Maker Market
Tea
Light-Fermented Tea Market