
 High Protein Tea Market | 2026-2036
High Protein Tea Market Size, Share, and Industry Trends Forecast 2026-2036
High Protein Tea Market Foresight
China is reshaping supply dynamics through expanded ready-to-drink manufacturing capacity and protein extraction infrastructure. PepsiCo leverages its beverage distribution network to secure shelf placement across mass retail channels. Nestlé anchors its position through dairy-protein tea formulations that draw on existing nutrition science capabilities. Glanbia specializes in whey and plant-protein ingredient supply, extending its reach into finished beverage partnerships.
High protein tea combines brewed tea extracts with protein isolates or concentrates, typically delivering 10-20 grams of protein per serving through cold microfiltration or enzymatic blending processes designed to preserve tea polyphenol stability. The product serves consumers seeking hydration with muscle recovery or satiety benefits in formats that replace traditional sports drinks or meal replacements. Ready-to-drink formulations capture the largest margin pool due to convenience premiums and brand loyalty, while instant powder competes on cost per serving and portability for gym-centric consumption. Fitness enthusiasts and health conscious consumers represent the fastest-growing end-user clusters as protein fortification expands beyond traditional sports nutrition into daily wellness routines.
The FDA governs protein content claims and GRAS status for novel protein sources in the United States, while the EFSA evaluates health claim substantiation across European markets. BIS standards in India and GB standards in China add compliance layers for brands seeking multi-country distribution. Stakeholders must monitor evolving protein-source regulations and clean-label certification requirements as consumer scrutiny of ingredient provenance intensifies.
Market Dynamics
Protein extraction infrastructure expansion in China is compressing ingredient costs while cold microfiltration technology advances enable polyphenol stability at higher protein loads, reshaping formulation economics across ready-to-drink and powder formats.
Growth Catalysts
- Fitness Enthusiast Demand:Muscle recovery and satiety benefits drive adoption beyond traditional sports nutrition into daily wellness routines, expanding addressable consumer base.
- Novel Food Regulation Pathways:The EU's structured ingredient approval framework accelerates protein-fortified beverage commercialization across member states.
- Enzymatic Blending Processes:Cold-process enzyme technologies preserve tea bioactive compounds while integrating dairy and plant protein isolates without heat degradation.
Market Restraints
- Whey Protein Price Volatility:Dairy commodity fluctuations create margin pressure for formulations dependent on whey isolates as primary protein source.
- GRAS Status Uncertainty:The FDA's evolving evaluation timelines for novel plant protein sources delay product launches in the United States.
- Ready-to-Drink Shelf Stability:Protein precipitation and tea tannin interactions limit ambient distribution reach for liquid formats.
Strategic Opportunities
- India Functional Beverage Entry:BIS standards alignment and urban gym culture expansion create first-mover potential in underdeveloped protein tea categories.
- Clean-Label Certification Premiums:Organic and non-GMO verification protocols command pricing power in United States mass retail channels.
- Direct-to-Consumer Subscription Models:Powder formats bypass traditional retail slotting fees through personalized nutrition platforms targeting health-conscious households.
Industry Challenges
- Flavor Masking Expertise Gap:Protein off-notes in tea matrices require specialized food science talent scarce outside established dairy-protein regions.
- Multi-Jurisdiction Labeling Complexity:Divergent protein content claim thresholds between FDA, EFSA, and GB standards fragment packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Protein Tea Market |
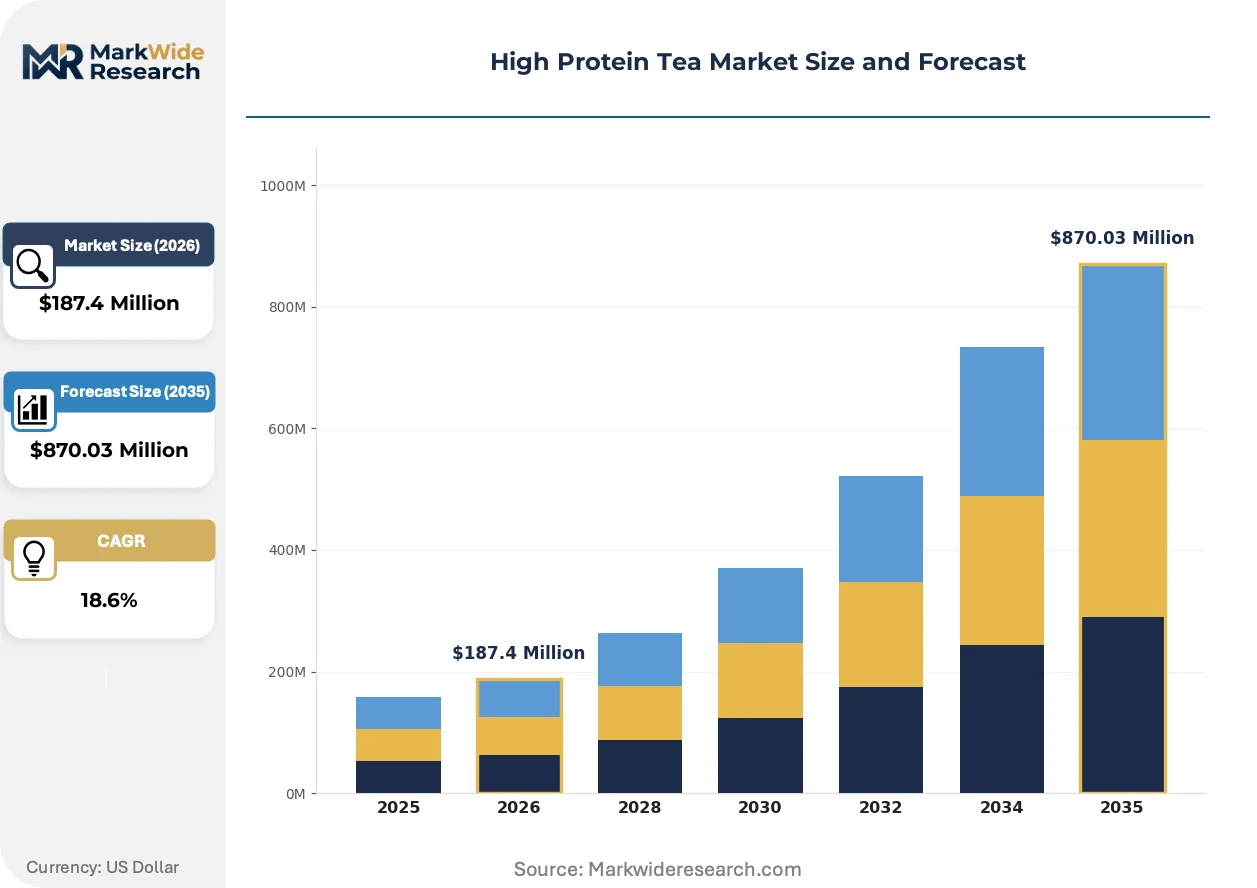
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Ready-to-Drink, Instant Powder Form: Cold Brew, Hot Brew, Concentrate, Extract End User: Fitness Enthusiasts, Health Conscious Consumers, Athletes, Weight Management Seekers Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops |
| Companies Covered | PepsiCo, Nestlé, Unilever, The Coca-Cola Company, Herbalife Nutrition, Danone, Glanbia, Abbott Nutrition, Monster Beverage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Protein Tea Market Shifts & Advancements
Cold-process manufacturing and regulatory clarity are converging to unlock shelf-stable formats previously constrained by protein-tea chemical incompatibility, while distribution models fragment across premium convenience and value-oriented bulk channels.
Microencapsulation technology for protein isolates is collapsing the stability gap between ready-to-drink and freshly prepared high-protein beverages. Fitness enthusiasts and meal-replacement seekers are adopting these formats at accelerating velocity. The technology is collapsing spoilage risk premiums that previously constrained ambient distribution.
EFSA health claim substantiation requirements are tightening evidentiary standards for muscle recovery and satiety messaging on European protein-fortified teas. Manufacturers must invest in clinical validation or reformulate positioning around general wellness. Sports nutrition brands targeting EU expansion are responding with revised label architectures and reduced specific performance claims.
Gym-centric consumption patterns are fragmenting procurement between single-serve ready-to-drink purchases and bulk powder subscriptions. Traditional sports nutrition retail channels face disintermediation from direct brand relationships and automated replenishment platforms. This behavioral shift is most visible in United States metropolitan markets with dense boutique fitness studio networks.
High Protein Tea Market Segmentation
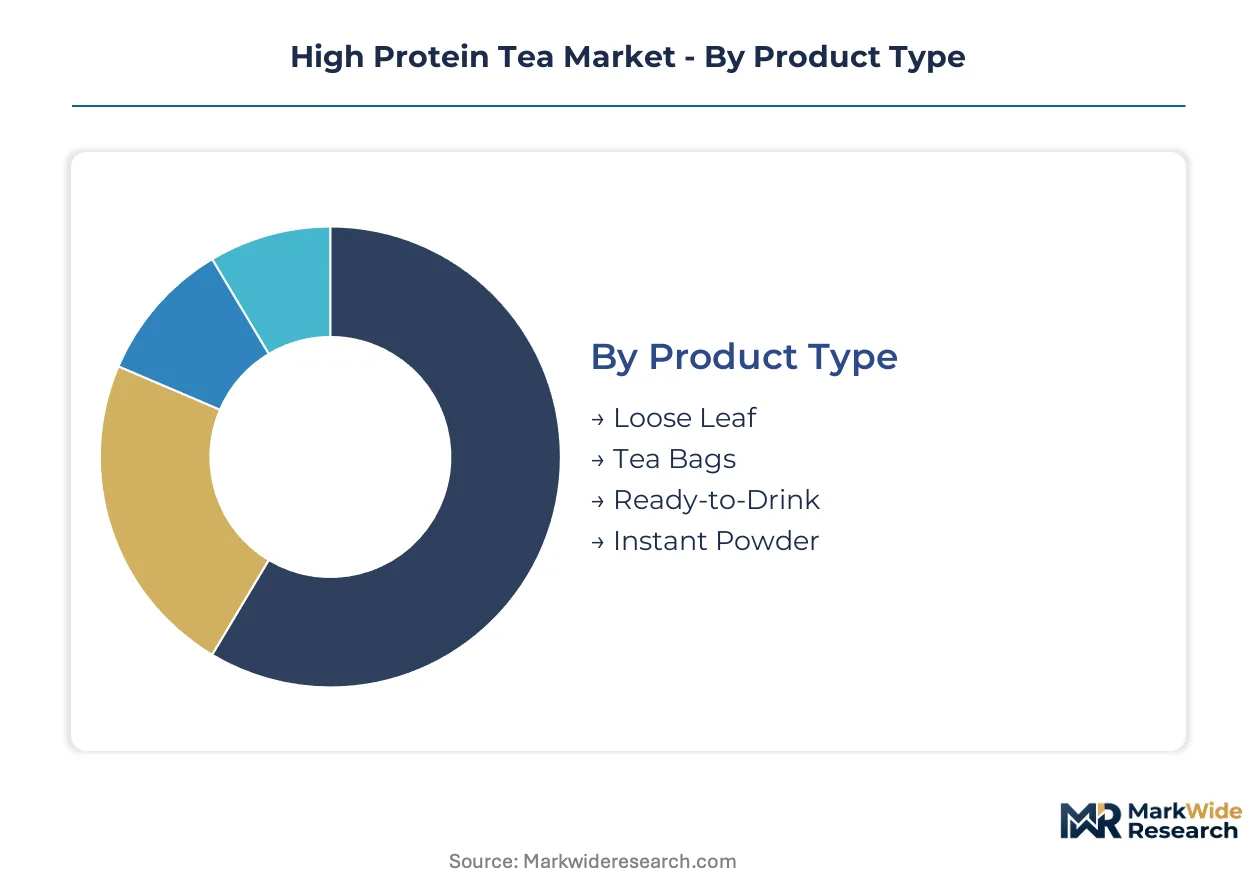
Segmentation in high protein tea reveals divergent margin structures and purchase frequencies across formats, with ready-to-drink commanding convenience premiums while powder formats compete on cost efficiency. Understanding these trade-offs exposes where formulation investment and channel strategy should concentrate.
Product Type:
Ready-to-drink formats turn inventory fastest through impulse purchases at fitness centers and convenience retail, while loose leaf moves slowest through specialty channels with educated staff.
- Ready-to-Drink:Cold microfiltration delivers 10-20 grams protein per 330-500ml serving with preserved tea polyphenol stability. United States metropolitan markets with dense boutique fitness studio networks drive velocity through grab-and-go consumption at gym exits and urban convenience chains.
- Instant Powder:Enzymatic blending creates shelf-stable concentrates requiring only water addition, with cost per serving 40-60% below liquid equivalents. Gym-centric consumers in China and India bulk-purchase through direct-to-consumer subscription platforms bypassing traditional retail slotting fees.
- Loose Leaf:Protein-fortified whole leaf teas target premium wellness consumers through specialty tea merchants with brewing ritual emphasis.
- Tea Bags:Single-serve sachets with protein coating bridge convenience and preparation control for office and travel consumption.
Ready-to-drink dominates installed base. Instant powder is where expansion concentrates.
Form:
Cost tier separation runs steep between concentrate formats optimized for foodservice bulk and cold brew positioned at retail premium.
- Cold Brew:Extended steeping at refrigerated temperatures extracts tea compounds without heat degradation, then protein isolates integrate through low-temperature enzymatic processes. United States health food stores and premium supermarkets command price multiples over hot-brew equivalents for perceived bioactive preservation.
- Concentrate:Reduced water content slashes shipping weight for foodservice and industrial blending applications, with dilution ratios customizable by end-user. China's expanded protein extraction infrastructure compresses ingredient costs for concentrate manufacturers serving ready-to-drink co-packers.
- Hot Brew:Traditional extraction followed by spray-dried protein integration targets cost-sensitive markets accepting some polyphenol degradation.
- Extract:Standardized tea polyphenol bases with precise protein dosing serve functional beverage manufacturers requiring formulation consistency.
Cold brew captures margin leadership. Concentrate is gaining share fastest in foodservice supply chains.
End User:
Application intensity varies dramatically between daily ritual consumers and episodic athletic use cases with distinct replenishment triggers.
- Fitness Enthusiasts:Muscle recovery and satiety benefits drive adoption beyond traditional sports nutrition into daily wellness routines, with procurement fragmenting between single-serve ready-to-drink purchases and bulk powder subscriptions. Automated replenishment platforms in United States metropolitan markets disintermediate traditional sports nutrition retail channels.
- Health Conscious Consumers:Protein fortification replaces conventional sugary beverages in hydration rituals, with clean-label certification protocols commanding pricing power in mass retail channels. EFSA health claim substantiation requirements in Europe tighten evidentiary standards, forcing reformulation toward general wellness positioning.
- Athletes:Competitive and recreational competitors demand precise macronutrient timing with batch-tested formulations.
- Weight Management Seekers:Meal replacement applications prioritize satiety signaling through protein load with minimal caloric density.
Fitness enthusiasts dominate installed base. Health conscious consumers are where expansion concentrates.
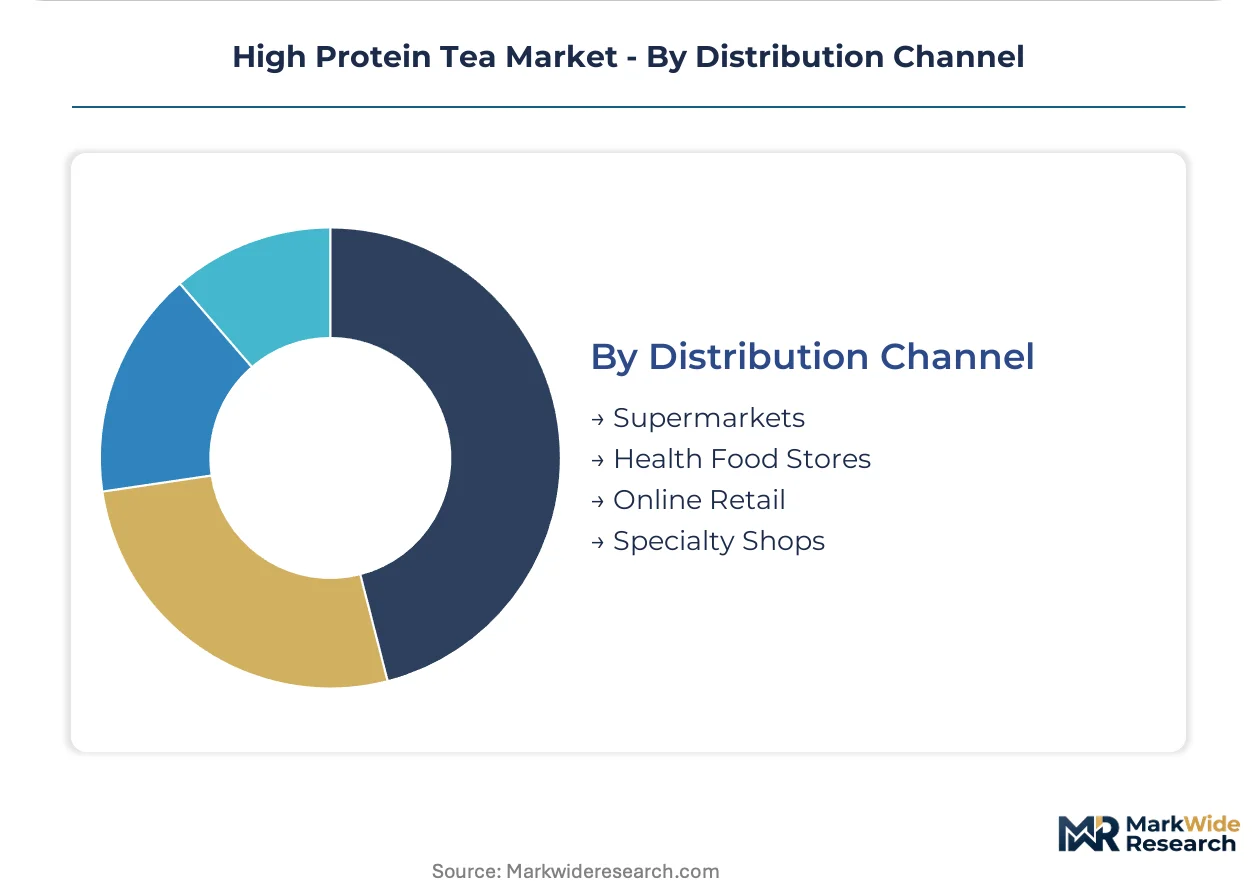
Distribution Channel:
Volume concentration sits with mass retail while margin extraction concentrates in specialized channels with educated staff.
- Online Retail:Direct-to-consumer subscription models bypass traditional retail slotting fees through personalized nutrition platforms targeting health-conscious households, with powder formats particularly suited to automated replenishment algorithms. PepsiCo leverages its beverage distribution network to secure shelf placement across mass retail channels, while niche brands build defensible positions through digital-native customer relationships.
- Health Food Stores:Staff expertise enables premium positioning for cold brew and microencapsulated formats with technical differentiation, with organic and non-GMO verification protocols commanding pricing power. EFSA evaluations shape health claim substantiation for European market entry.
- Supermarkets:Mass retail placement demands price competitiveness and familiar flavor profiles for mainstream adoption.
- Specialty Shops:Curated tea merchants with brewing education support loose leaf and ceremonial-grade protein-fortified offerings.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA protein content claims and GRAS status evaluations anchor the United States as the dominant geography, while EFSA health claim substantiation shapes European commercialization timelines. China's expanded protein extraction infrastructure compresses ingredient costs across Asia-Pacific supply chains.
United States
Fitness enthusiasts and health-conscious households drive ready-to-drink velocity through boutique fitness studio networks in metropolitan markets. FDA GRAS status uncertainty for novel plant proteins delays some product launches despite strong consumer pull. Cold brew protein tea formulations command price multiples in health food stores across California and New York Metro clusters.
China
Urban gym culture expansion and direct-to-consumer subscription platforms accelerate powder format adoption among fitness enthusiasts. GB standards compliance requirements add regulatory layers for multi-country distribution strategies. Yangtze River Delta manufacturing hubs concentrate ready-to-drink production capacity with integrated protein extraction infrastructure.
Germany
EFSA health claim substantiation requirements tighten evidentiary standards for muscle recovery messaging on protein-fortified teas. EU Novel Food Regulation pathways accelerate ingredient approval across member states. Bavaria-based dairy-protein specialists leverage existing nutrition science capabilities for beverage formulation partnerships.
India
BIS standards alignment and urban gym culture expansion create first-mover potential in underdeveloped protein tea categories. FSSAI regulations govern protein fortification claims for functional beverages entering the market. Maharashtra and Karnataka metropolitan clusters concentrate early distribution trials for ready-to-drink formats.
Japan
Health-conscious consumers seeking hydration with satiety benefits drive adoption of protein-fortified green tea variants. METI industrial policies support functional food innovation through targeted R&D incentives. Kanto region beverage manufacturers integrate cold microfiltration technology for polyphenol-stable formulations.
High Protein Tea Market Competitive Landscape
Capability concentration sits with dairy-protein nutrition specialists; scale advantage sits with mass-market beverage conglomerates. The market structure organizes around three tiers: global FMCG giants with refrigerated distribution networks, sports nutrition specialists with clinical validation expertise, and ingredient suppliers extending into finished goods partnerships. Dominant competitive moves include enzymatic blending technology licensing and direct-to-consumer platform acquisitions that bypass traditional retail slotting fees.
Within the mass-market tier, PepsiCo and Nestlé occupy positions that exemplify scale-driven shelf placement strategies across United States metropolitan convenience chains. Glanbia represents the ingredient-to-finished-goods archetype, anchoring supply relationships that leverage whey and plant-protein extraction capabilities. These three entities collectively illustrate how protein tea commercialization spans beverage distribution networks, dairy science portfolios, and upstream ingredient control.
| Leading Market Players |
|---|
| PepsiCo |
| Nestlé |
| Unilever |
| The Coca-Cola Company |
| Herbalife Nutrition |
| Danone |
| Glanbia |
| Abbott Nutrition |
| Monster Beverage |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta protein extraction infrastructure is compressing whey and plant-protein input costs while forcing suppliers toward longer-term offtake contracts to defend margin structures across ready-to-drink and powder formats.
Pricing Analysis
Price spreads between United States metropolitan convenience chains and Indian urban gym-centric subscription platforms exceed factor ranges due to cold microfiltration technology premiums and GRAS certification compliance costs. Three-tier pricing structure across premium cold brew, standard ready-to-drink, and economy instant powder segments anchors the market. Pricing pressure stems from whey protein commodity volatility and China's expanded manufacturing capacity. Fitness enthusiasts in premium health food stores show least price sensitivity; cost-conscious bulk purchasers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes on enzymatic blending equipment from Germany and Japan limit technology transfer to emerging market co-packers, constraining local cold-process manufacturing scale-up. Supply concentrates in China for protein extraction, the United States for cold microfiltration formulation, and India for enzymatic powder processing. Raw material dependencies span whey isolates, tea polyphenol extracts, and microencapsulation substrates. Single-source vulnerability sits with German enzymatic technology licensors. Distribution runs through PepsiCo and Nestlé refrigerated networks in developed markets, direct-to-consumer platforms in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
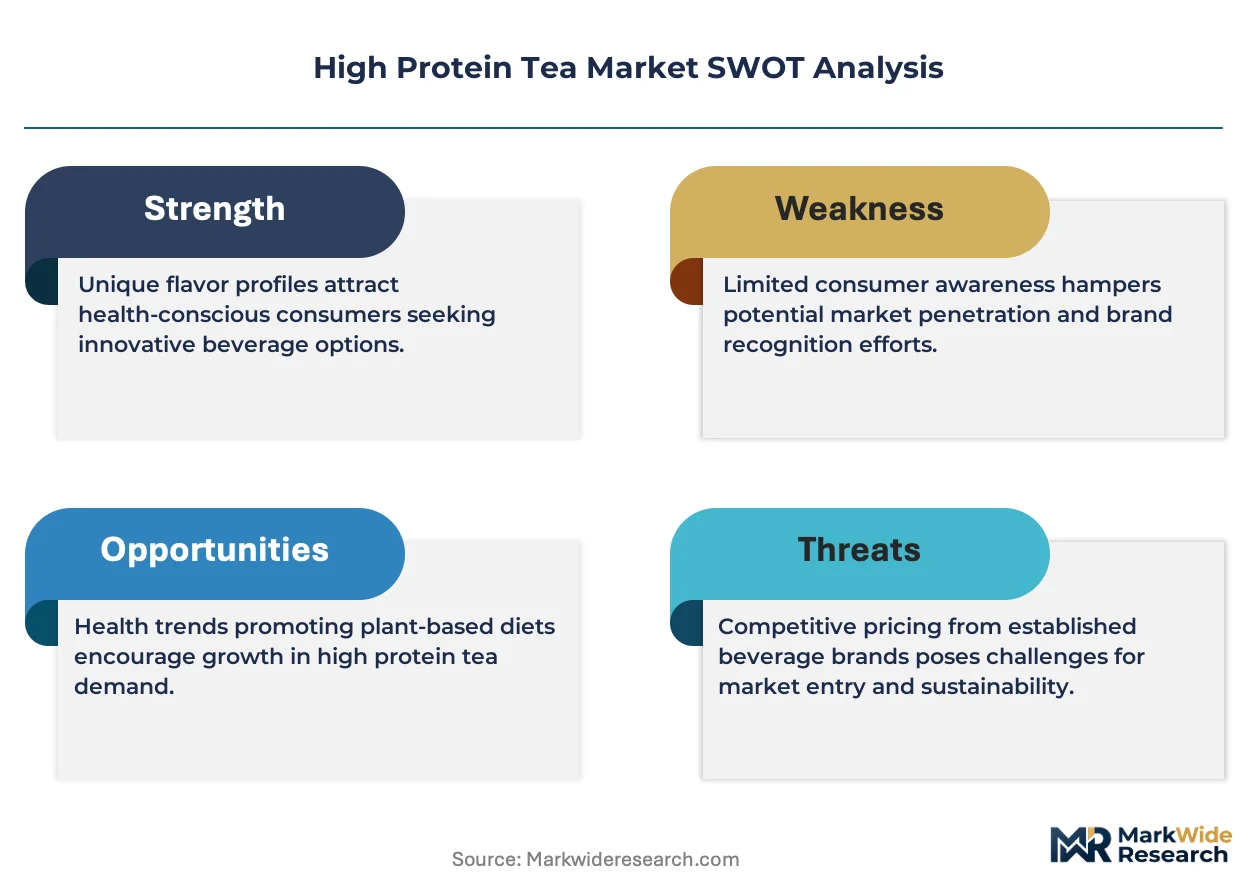
The high protein tea market is recovering from whey price cyclicality as China's protein extraction infrastructure matures and cold-process manufacturing achieves scale economics.
For Market Incumbents: Build formulation IP moats through proprietary enzymatic blending patents that lock in polyphenol stability at elevated protein loads. Nestlé and Glanbia should deepen backward integration into dairy-protein supply to offset whey commodity volatility. PepsiCo must secure exclusive refrigerated shelf space contracts before emerging brands achieve velocity in metropolitan fitness studio networks. For New Entrants and Emerging Players: India's underpenetrated protein tea category offers first-mover potential as BIS standards align with FSSAI functional beverage frameworks. Maharashtra and Karnataka metropolitan clusters concentrate gym culture expansion with minimal incumbent presence. Direct-to-consumer subscription platforms bypass traditional retail slotting fees and enable automated replenishment algorithms for powder formats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across instant powder manufacturing as China's equipment costs compress. Long-term viability favors ingredient suppliers with captive protein extraction and finished-goods partnerships. Acquisition targets include enzymatic blending technology licensors and direct-to-consumer platform operators. Watch EFSA health claim substantiation rulings as inflection signals for European market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Blending Technology Licensing | German and Japanese licensors capture value from polyphenol stability patents across global co-packer networks. |
| Direct-to-Consumer Platform Acquisition | Automated replenishment algorithms in United States metropolitan markets disintermediate traditional sports nutrition retail channels. |
| Cold Microfiltration Capacity Expansion | United States health food stores command price multiples for bioactive-preservation positioning in California and New York clusters. |
| Clean-Label Certification Investment | Organic and non-GMO verification protocols unlock pricing power in mass retail channels across developed markets. |
| India Distribution Channel Buildout | BIS standards alignment and urban gym culture expansion create defensible early positions in underdeveloped categories. |
Research Methodology
The analysis maps ready-to-drink, instant powder, loose leaf, and tea bag sub-sectors, each validated through beverage formulation scientists, sports nutrition brand managers, health food store category buyers, and protein ingredient procurement leads. Primary interviews triangulate with secondary sources including FDA GRAS filings, EFSA health claim substantiation records, GB standards documentation, and Nielsen retail audit data across United States, China, and European markets. Bottom-up volume builds and top-down macroeconomic checks anchor the analytical framework.
Assumptions held fixed include regulatory approval timelines for novel protein sources and cold microfiltration technology diffusion rates; variables include whey protein commodity price trajectories and gym culture penetration rates across emerging markets. Segmentation dimensions span product type, form, end user archetype, and distribution channel, with geographic regulatory clusters modeled separately. CAGRs derive from installed base growth and replacement cycle analysis. Forecast inputs incorporate protein extraction capacity utilization and enzymatic blending equipment deployment schedules.
Practitioners should monitor FDA GRAS status rulings for novel plant proteins and EFSA evidentiary requirement tightening for early signals of market access friction. Forecasts reflect assumptions about regulatory stability and protein commodity price normalization. Material shifts in EU Novel Food Regulation enforcement or China GB standards alignment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Asia-Pacific Tea Market
Tea
Smart Tea Maker Market
Tea
Black Tea Market
Tea
Slimming Tea Market
Tea
Floral Tea Market
Tea
Tea Pitchers Market
Tea
Moringa Tea Market
Tea
Europe Tea Market
Tea
Tea Infuser Market
Tea
China Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Global Tea Market
Tea
Nitro Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Kombucha Tea Market
Tea
North America Ready-To-Drink Tea Market