
 MS Polymer Hybrid Adhesives and Sealants Market | 2026-2036
MS Polymer Hybrid Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
MS Polymer Hybrid Adhesives and Sealants Market Foresight
Silicone is broadening its displacement of polyurethane in construction and automotive bonding as MS polymer hybrids close the performance gap at lower material cost. Sika AG dominates European infrastructure specifications with deep specification engineering relationships. Henkel AG anchors automotive OEM supply chains through captive resin development and tier-one qualification protocols. Arkema (Bostik) leverages its acrylic technology base to compete in flexible adhesive segments where UV resistance differentiates performance tiers.
MS polymer hybrid adhesives and sealants combine silane-terminated polyurethane or silane-modified polyether backbones with moisture-cure chemistry, delivering elastic bonding without isocyanate content or solvent emission. The formulation achieves 300-600% elongation at break while maintaining tensile strengths of 2-5 MPa, serving structural glazing, elastic flooring, and vehicle panel attachment where dynamic joint movement occurs. Hybrid sealants command the largest value pool in construction applications where movement accommodation and paint compatibility overlap. Automotive assembly represents the fastest-growing application segment as OEMs substitute mechanical fasteners with bonded joints to reduce vehicle mass. Direct sales channels control the premium specification tier where OEMs and major contractors negotiate multi-year supply agreements with technical service捆绑.
REACH in Europe and EPA VOC regulations in the United States restrict solvent content and mandate isocyanate labeling, pushing formulators toward silane-cure platforms that bypass both hazard classes. ECHA substance evaluations and state-level CARB standards in California create overlapping compliance layers that favor pre-qualified suppliers with established regulatory dossiers. Stakeholders must monitor evolving MEE standards in China and potential EU Green Deal extensions into embodied carbon calculations for construction materials.
Market Dynamics
Automotive OEMs are systematically eliminating mechanical fasteners from vehicle architectures, substituting bonded joints that reduce mass while accommodating thermal expansion mismatches between aluminum panels and composite substrates.
Growth Catalysts
- REACH Phase-Out of Isocyanates:ECHA restrictions on diisocyanate content in consumer and professional applications are accelerating silane-cure platform adoption across European construction and transport manufacturing.
- Lightweighting Mandates in Transport:CAFE standards in the United States and parallel CO2 fleet targets in Germany and Japan are compelling automakers to replace rivets and welds with structural adhesives in body-in-white assembly.
- Hybrid Chemistry Performance Maturation:Silane-modified polyether backbones now achieve paint compatibility and UV stability thresholds that previously required pure silicone formulations, opening specification access in premium facade applications.
Market Restraints
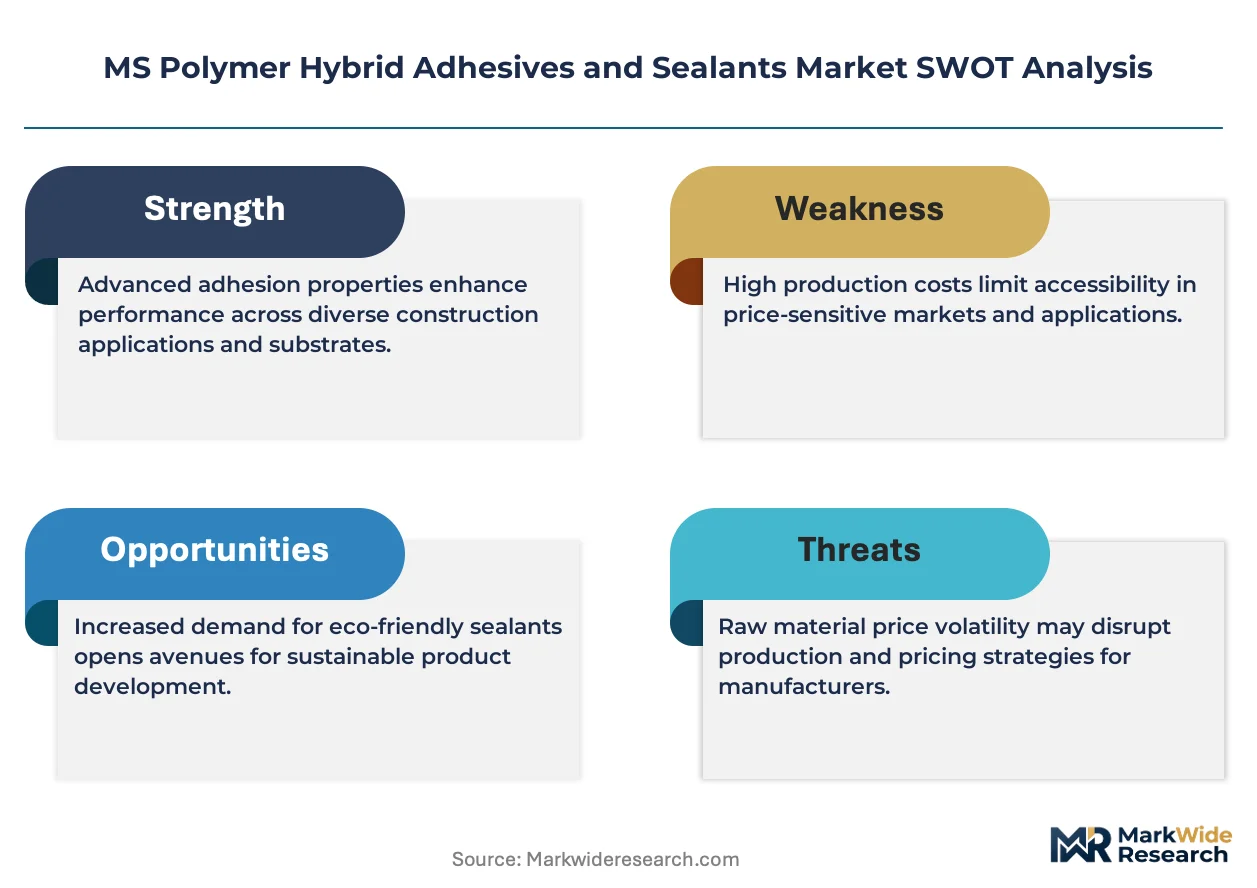
- Silane Monomer Supply Concentration:Production of specialty silane coupling agents concentrates among a limited set of German and Chinese chemical manufacturers, creating input vulnerability for formulators.
- Cure Kinetics Limitation:Moisture-cure chemistry requires 24-72 hours for full property development, restricting application in high-throughput assembly lines where instant handling strength remains mandatory.
- Polyurethane Cost Competition:Established two-component polyurethane systems maintain price advantages in non-regulated construction segments where VOC exposure limits remain unenforced.
Strategic Opportunities
- Electric Vehicle Battery Enclosure Bonding:Thermal management module attachment in EV platforms demands flame-retardant elastic adhesives with dielectric properties that hybrid formulations are uniquely positioned to address.
- India Building Code Evolution:BIS adoption of ISO 11600 sealant classification standards is creating first-mover advantage windows for compliant hybrid products in commercial high-rise construction.
- Wind Turbine Blade Repair:Leading-edge erosion protection and structural crack injection applications favor low-viscosity MS polymer grades that bond dissimilar substrates under field cure conditions.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Silane-terminated polymer synthesis and moisture-cure catalyst optimization require specialized knowledge concentrated among senior chemists approaching retirement in European and Japanese technical centers.
- OEM Qualification Timeline Compression:Tier-one automotive suppliers face 18-36 month validation cycles for new adhesive platforms, misaligned with vehicle platform refresh schedules that now compress to 24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MS Polymer Hybrid Adhesives and Sealants Market |
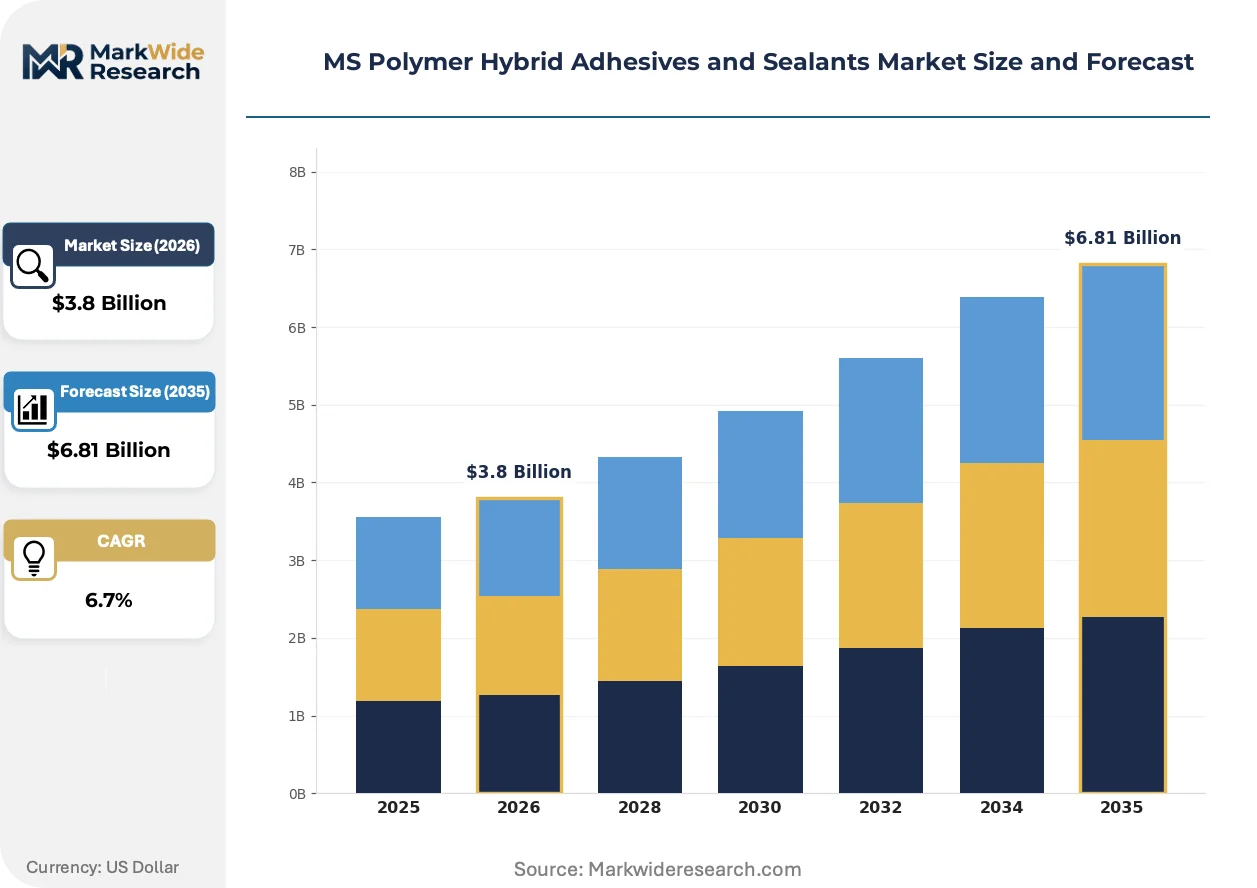
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Adhesives, Rigid Sealants, Hybrid Sealants, Structural Adhesives Application: Automotive Assembly, Construction, Industrial Manufacturing, Marine Applications End User: OEMs, Contractors, Distributors, Repair Shops Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Arkema (Bostik), Sika AG, H.B. Fuller, Henkel AG, 3M Company, Wacker Chemie AG, Tremco Illbruck, Soudal Group, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MS Polymer Hybrid Adhesives and Sealants Market Shifts & Advancements
Formulation chemistry is converging with digital specification tools that automate joint design and cure scheduling, compressing the engineering validation cycle for bonded assemblies in both construction and transport applications.
Silane-modified polyether technology is integrating nano-silica reinforcement to achieve simultaneous improvements in tensile strength and elongation without sacrificing the low-modulus characteristics required for movement accommodation. Automotive glazing contractors in Germany and Japan are specifying these enhanced grades for panoramic roof installations where dynamic loading and thermal cycling coincide. The structural consequence is that hybrid sealants are integrating load-bearing functions previously reserved for mechanical fasteners, compressing the bill-of-materials count in vehicle superstructures.
EPA VOC regulations under the National Ambient Air Quality Standards are tightening permissible solvent content in architectural coatings and sealants, with California CARB standards extending these thresholds to consumer products. Industrial consequence includes reformulation of conventional solvent-borne sealants toward 100% solids hybrid platforms that eliminate emission control equipment requirements. Construction contractors in the United States are responding by pre-qualifying suppliers with established low-VOC product dossiers, shifting specification authority toward formulators with regulatory documentation depth.
Building envelope contractors are consolidating procurement around single-source adhesive-sealant systems that reduce substrate compatibility testing and warranty fragmentation. Distributors are displacing fragmented local supply relationships with integrated logistics platforms that bundle technical service, inventory management, and specification support. This concentration is most visible in German commercial construction markets where general contractors face liquidated damages clauses for envelope performance failures, creating preference for suppliers with documented project track records and captive application training capabilities.
MS Polymer Hybrid Adhesives and Sealants Market Segmentation
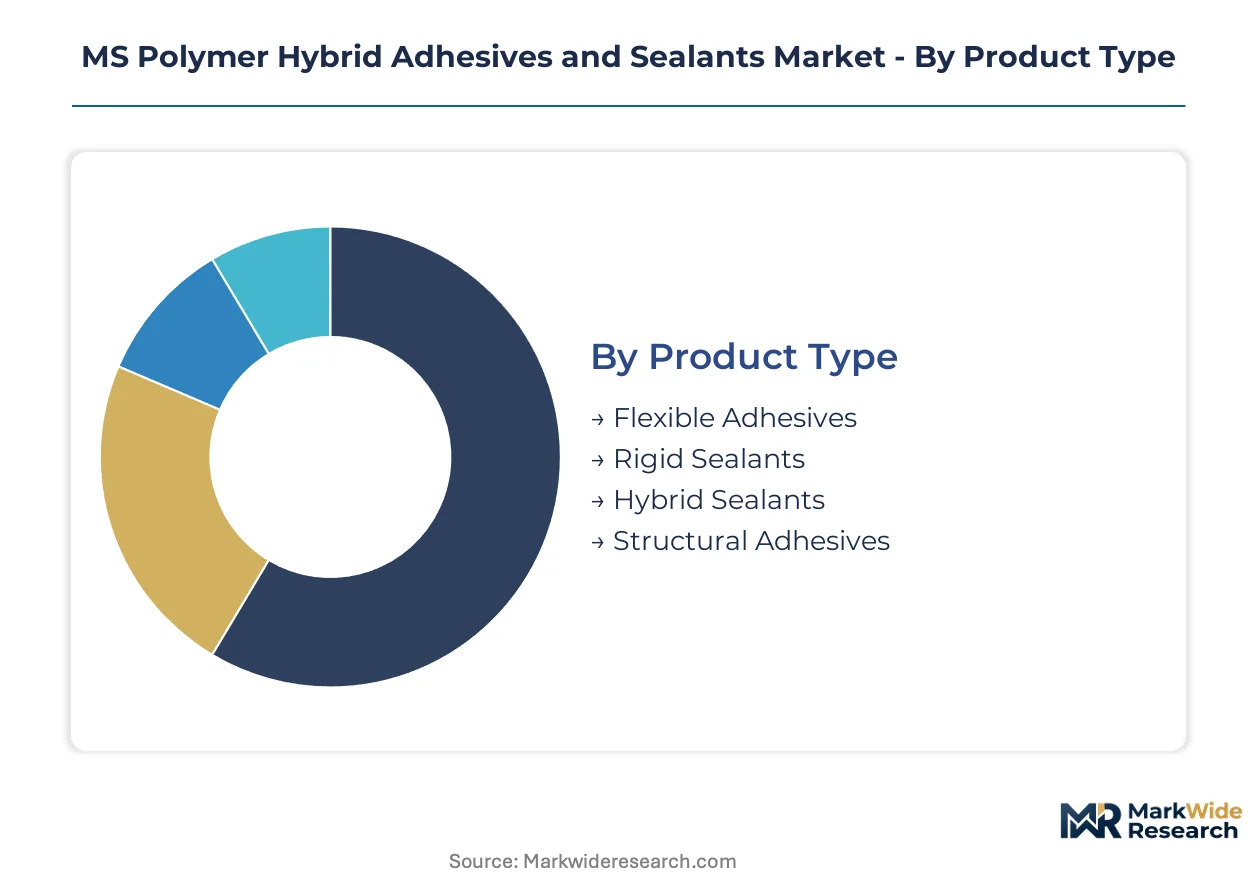
Segmentation in the MS polymer hybrid adhesives and sealants market reveals how formulation chemistry, cure kinetics, and specification authority concentrate value across divergent buyer workflows. Understanding these splits exposes where technical service investments yield margin protection versus where price competition dominates procurement decisions.
Product Type:
Cost tier differentiation separates specification-grade formulations from commodity substitutes in this category.
- Flexible Adhesives:Silane-modified polyether backbones deliver 400-600% elongation with tensile strengths of 2-3 MPa, serving expansion joint sealing and elastic flooring where substrate movement exceeds 25%. German facade contractors specify these grades for curtainwall applications where thermal cycling demands paint compatibility without silicone's surface contamination risks.
- Hybrid Sealants:Combining polyurethane toughness with silane cure chemistry, these formulations achieve primerless adhesion to aluminum, PVC, and concrete while bypassing isocyanate hazard classification. Japanese automotive glazing suppliers absorb rising volumes for panoramic roof installations where UV stability and modulus control overlap.
- Rigid Sealants:Higher modulus formulations with limited elongation serve perimeter sealing in non-moving joints where compressive strength exceeds flexibility requirements.
- Structural Adhesives:High-strength grades above 5 MPa tensile strength bond dissimilar substrates in load-bearing applications across transport manufacturing.
Hybrid sealants lead volumes today; flexible adhesives are gaining share fastest.
Application:
Volume concentration tracks regulatory enforcement intensity and OEM lightweighting mandates across manufacturing clusters.
- Automotive Assembly:Body-in-white bonding and glazing attachment absorb premium hybrid formulations as CAFE standards and parallel CO2 fleet targets in Germany, Japan, and the United States compel mass reduction through fastener elimination. Sika AG and Henkel AG have locked multi-year supply agreements with Volkswagen Group and Toyota Motor Corporation respectively.
- Construction:Building envelope sealing, structural glazing, and elastic flooring constitute the largest value pool where movement accommodation and paint compatibility specifications overlap. German commercial contractors face liquidated damages clauses for envelope failures, concentrating procurement around suppliers with documented project track records.
- Industrial Manufacturing:Equipment panel bonding and vibration-damping applications favor medium-modulus hybrids where solvent-free cure chemistry satisfies indoor air quality protocols.
- Marine Applications:Deck sealing and hull bonding in yacht construction demand saltwater-resistant formulations with extended weathering performance.
Construction anchors current revenue; automotive assembly shows the steepest expansion trajectory.
End User:
Specification authority and technical service requirements fragment procurement patterns across this category.
- OEMs:Automotive and appliance manufacturers negotiate multi-year supply agreements with embedded technical service and joint design engineering. Qualification protocols demand 18-36 month validation cycles that freeze out second-tier formulators without captive resin development capabilities.
- Contractors:German commercial construction general contractors consolidate procurement around single-source adhesive-sealant systems to reduce substrate compatibility testing and warranty fragmentation.
- Distributors:Integrated logistics platforms bundle inventory management, specification support, and application training for mid-tier construction accounts.
- Repair Shops:Automotive collision repair and marine maintenance operations purchase through wholesale channels where immediate availability overrides formulation optimization.
OEMs command the premium tier; contractors represent the volume anchor.
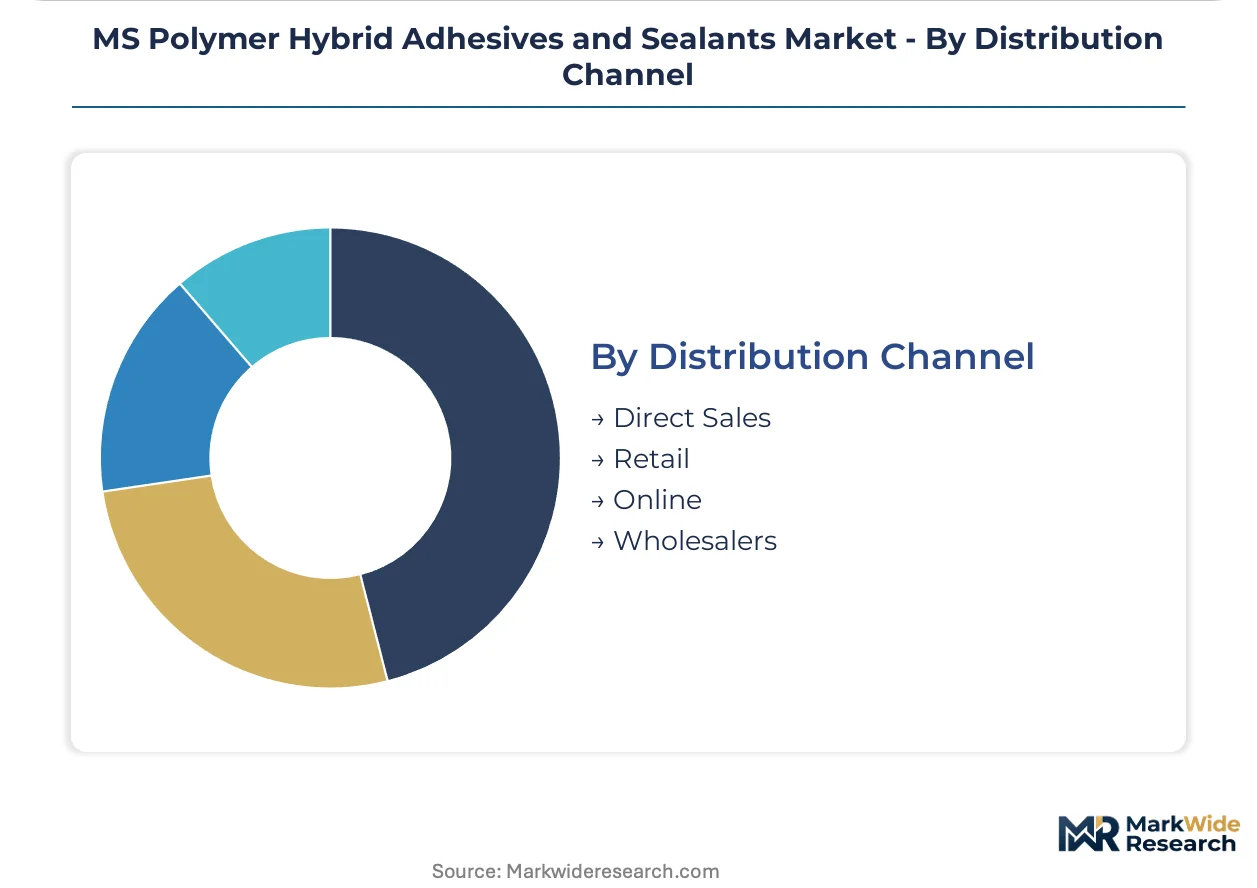
Distribution Channel:
Customer scale and specification complexity determine channel selection and margin structure.
- Direct Sales:Tier-one automotive suppliers and major construction contractors negotiate captive relationships with technical service捆绑 and multi-year volume commitments. This channel captures the specification premium where joint design and cure scheduling require embedded engineering support.
- Wholesalers:Regional distributors serve mid-market contractors with consolidated adhesive-sealant portfolios and application training capabilities.
- Retail:Consumer and light professional products move through hardware and specialty trade stores where brand recognition and shelf placement drive selection.
- Online:E-commerce platforms gain traction in aftermarket repair segments where specification authority rests with individual technicians rather than engineering departments.
Direct sales dominate value capture; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and construction clusters concentrate the highest specification density for MS polymer hybrid formulations, with regulatory pressure from REACH and the EU Green Deal accelerating silane-cure adoption across bonded assembly applications.
United States
Automotive OEMs in Michigan and the Southeast are eliminating mechanical fasteners to meet CAFE standards, driving structural adhesive demand in body-in-white assembly. EPA VOC regulations and California CARB standards enforce solvent-free formulation shifts. Detroit-area suppliers negotiate multi-year supply agreements with embedded technical service.
Germany
Commercial facade contractors specify hybrid sealants for curtainwall applications where paint compatibility and movement accommodation overlap. ECHA restrictions on diisocyanate content push formulators toward silane-cure platforms. Stuttgart and Munich automotive clusters absorb premium grades for panoramic roof bonding.
Japan
Toyota and Honda assembly plants in Aichi and Saitama prefectures substitute bonded joints for rivets to reduce vehicle mass. METI industrial standards and CO2 fleet targets compel lightweighting investments. Nagoya-area glazing suppliers specify UV-stable hybrid formulations for thermal expansion management.
China
EV battery enclosure manufacturing in the Yangtze River Delta demands flame-retardant elastic adhesives with dielectric properties. MEE standards tighten VOC thresholds and accelerate solvent-free shifts. Shanghai and Suzhou construction markets absorb movement-capable sealants for high-rise commercial envelopes.
India
BIS adoption of ISO 11600 sealant classification standards creates first-mover windows for compliant hybrid products. Commercial high-rise construction in Mumbai and Delhi-NCR concentrates procurement around specification-grade formulations. Automotive assembly in Tamil Nadu and Maharashtra drives bonded joint adoption for export-oriented manufacturing.
MS Polymer Hybrid Adhesives and Sealants Market Competitive Landscape
Capacity expansion dominates the current landscape as established formulators build captive silane-terminated polymer production to secure input supply. The market structure concentrates around three to five integrated chemical groups with resin synthesis capabilities, while regional compounders occupy price-sensitive construction segments. Strategic archetypes separate specification-engineering specialists from scale-driven commodity suppliers and niche application-focused innovators. M&A activity targets silane monomer producers and regional distribution networks, while portfolio diversification extends hybrid platforms into EV battery and wind energy applications.
Among European integrated chemical groups, Sika AG and Henkel AG exemplify the specification-engineering archetype through deep OEM qualification relationships and captive resin development. Arkema's Bostik division occupies a position bridging acrylic technology heritage with hybrid formulation expansion. These three anchors represent distinct competitive vectors: construction infrastructure specification, automotive supply chain integration, and technology platform diversification.
| Leading Market Players |
|---|
| Arkema (Bostik) |
| Sika AG |
| H.B. Fuller |
| Henkel AG |
| 3M Company |
| Wacker Chemie AG |
| Tremco Illbruck |
| Soudal Group |
| Mapei S.p.A. |
| Others |
Supply & Pricing Matrix
Captive silane-terminated polymer production anchors pricing power for integrated formulators while locking out regional compounders dependent on merchant resin supply. German and Japanese chemical groups have consolidated backward control over specialty silane coupling agents, creating tiered supply security that translates directly into specification-grade pricing authority.
Pricing Analysis
Specialty silane monomer costs pass through to finished hybrid sealants at ratios that compress margins for non-integrated formulators. Three-tier pricing structure across specification-grade, professional-grade, and commodity-grade levels separates OEM-qualified products from construction-market substitutes. Pricing pressure stems from polyurethane cost competition in non-regulated building segments where VOC enforcement remains patchy. Contractors in price-sensitive emerging markets absorb economy-tier volumes, while automotive OEMs lock in premium-tier contracts with minimal price elasticity.
Supply Chain Analysis
Tier-one automotive qualification protocols gate supply chain access more rigidly than production capacity constraints. Manufacturing concentrates in Germany, Japan, and China where silane-modified polyether synthesis capabilities cluster. Production draws from methoxy-silane coupling agents, polyether polyols, and tin-based catalyst feedstocks. Single-source vulnerability concentrates in German specialty silane manufacturers. Distribution runs through direct sales channels for OEM accounts and consolidated wholesaler networks for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with ECHA diisocyanate restrictions and EPA VOC thresholds simultaneously expanding silane-cure demand across multiple geographies.
For Market Incumbents: Anchor specification authority through captive resin development and accelerated OEM qualification timelines. Lock multi-year supply agreements with embedded technical service before second-tier formulators achieve tier-one validation status. Deepen backward integration into silane monomer production to insulate margin compression from input supply concentration. For New Entrants and Emerging Players: Nano-silica reinforced formulations offer a technology-first wedge into premium facade applications where UV stability and modulus control overlap. Target Indian commercial high-rise construction as BIS adoption of ISO 11600 standards creates first-mover windows before incumbent dossier submission. Pursue wind turbine blade repair segments through field-cure low-viscosity grades that bypass automotive qualification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where silane monomer supply concentration meets formulation chemistry expertise scarcity. Five-to-ten year viability favors integrated chemical groups with captive polymer synthesis and established regulatory dossiers. Watch ECHA substance evaluation timelines as inflection indicators for accelerated platform substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Monomer Production | Secures input supply against German and Chinese manufacturer concentration. |
| Long-term Supply Agreement with Automotive OEM | Locks specification-grade volumes through 18-36 month qualification cycles. |
| Green Manufacturing Transition to Solvent-free Platforms | Aligns with REACH and EPA VOC mandates while eliminating emission control costs. |
| Joint Venture for Regional Distribution Network | Penetrates Indian and Chinese construction markets through localized specification support. |
| Capacity Expansion in EV Battery Adhesive Grades | Captures thermal management module attachment demand from Yangtze River Delta manufacturers. |
Research Methodology
Multiple input streams — technical director interviews at formulator headquarters, procurement lead discussions at tier-one automotive suppliers, and distributor consolidation pattern analysis — were reconciled against secondary validation. Primary fieldwork engaged R&D directors at hybrid sealant manufacturers, specification engineers at facade contractors, and regulatory affairs managers navigating ECHA dossier requirements. Secondary sources included customs trade data for silane monomer flows, SEC filings of integrated chemical groups, and BIS standard adoption records. Bottom-up volume modeling triangulated against top-down market sizing across chemistry platforms.
Data-stream reconciliation anchored the analytical framework across product type, application intensity, and regional regulatory enforcement clusters. Segmentation dimensions covered flexible adhesive, hybrid sealant, and structural adhesive grades; automotive assembly, construction, and industrial manufacturing end-uses; and direct sales versus wholesale channel splits. CAGRs were derived from elasticity modeling against OEM lightweighting mandates and building code evolution timelines. Forecast inputs incorporated REACH phase-out schedules and CAFE standard compliance trajectories without year-specific assumptions.
The model holds under stable regulatory enforcement intensity; deviation in ECHA restriction timelines or MEE standard acceleration would shift substitution rates. Forecasts reflect documented assumptions about silane-cure technology maturation and OEM qualification cycle compression. A model refresh is warranted upon material change in EV battery enclosure bonding specifications or BIS sealant classification implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market