
 AC Power Sources Market | 2026-2036
AC Power Sources Market Size, Share, and Industry Trends Forecast 2026-2036
AC Power Sources Market Analysis
IEC 61000-4 compliance for electromagnetic compatibility testing is collapsing the supplier base to firms with certified calibration chains and accredited test facilities. Chroma ATE leverages its vertically integrated semiconductor test heritage to dominate programmable AC source architectures for EV powertrain validation. Keysight Technologies sustains technology leadership through precision waveform synthesis capabilities that anchor its position in aerospace-grade simulation systems. Pacific Power Source competes on specialized three-phase configurations for naval and defense applications where MIL-STD-1399 compliance gates market access.
AC power sources are precision electrical instruments that generate controlled alternating voltage and current waveforms with programmable frequency, amplitude, and harmonic content for equipment validation and grid-interaction studies. These instruments typically operate from 45 Hz to 1,000 Hz with total harmonic distortion below 0.5%, serving critical functions in product safety certification, renewable energy inverter testing, and uninterruptible power supply verification. Three-phase programmable units command the deepest margin pools due to complexity in multi-channel synchronization and phase-angle control for motor-drive and traction-power emulation. Single-phase rack-mount variants lead unit volumes through dense deployment in telecommunications central offices and enterprise data center commissioning workflows.
US manufacturers navigate FCC Part 15 emissions constraints and NHTSA electrical-safety protocols for automotive test equipment, while European suppliers face REACH substance restrictions and CE marking obligations under the EU Green Deal's ecodesign trajectory. China's GB standards and MIIT certification requirements for grid-connected power electronics create parallel compliance tracks that shape product development roadmaps for domestic and export-oriented producers. Stakeholders must monitor how IEC harmonization efforts reconcile diverging regional test protocols before committing to platform architectures that risk stranded compliance investments.
Market Dynamics
Wafer-level test-bench expansion across Taiwan and South Korea is compressing equipment procurement cycles, forcing AC source manufacturers to accelerate calibration-chain certification timelines to match semiconductor fabrication ramp schedules.
Growth Catalysts
- EV Powertrain Metrology:Domestic inverter manufacturers in China are scaling in-house laboratories, creating sustained demand for three-phase programmable units with sub-0.5% harmonic distortion specifications.
- IEC 61000-4 Harmonization:Electromagnetic compatibility test thresholds are tightening across grid-simulation equipment categories, mandating replacement of legacy qualification benches in certification laboratories.
- Semiconductor Fab Expansion:Wafer-level validation protocols now require dedicated AC power sources for burn-in and stress-testing, concentrating equipment orders near Hsinchu and Pyeongtaek industrial clusters.
Market Restraints
- Precision Component Supply Concentration:High-stability voltage references and low-noise amplifiers rely on specialized foundry capacity concentrated in Taiwan, creating single-source vulnerability for programmable source architectures.
- Calibration Infrastructure Cost:IEC 61000-4 compliance requires accredited facilities with traceable standards chains, imposing capital barriers that collapse the qualified supplier base to vertically integrated test equipment specialists.
- Silicon Carbide Inverter Substitution:Wide-bandgap power electronics operate at switching frequencies beyond traditional AC source emulation ranges, narrowing the addressable test market for conventional 1,000 Hz-limited instruments.
Strategic Opportunities
- Naval Power Systems Modernization:MIL-STD-1399-compliant three-phase configurations for surface vessel and submarine applications represent a defensible niche with limited qualified competitors and extended procurement cycles.
- GB Standards Localization:China's MIIT certification requirements for grid-connected power electronics create parallel product development tracks where domestic certification accelerates market access versus import-dependent rivals.
- Aerospace-Grade Waveform Synthesis:Precision frequency control for avionics bus simulation commands premium positioning, with FAA and EASA airworthiness protocols gating entry to a concentrated buyer set of tier-one aerospace suppliers.
Industry Challenges
- Multi-Channel Synchronization Expertise:Three-phase programmable units require phase-angle control precision below 0.1 degrees, and the specialized firmware engineering talent pool concentrates among legacy motor-drive and traction-power equipment specialists.
- REACH Substance Compliance:European ecodesign trajectories under the EU Green Deal restrict hazardous substances in power electronics assemblies, forcing reformulation of thermal interface materials and magnetic core laminations with elongated qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Power Sources Market |
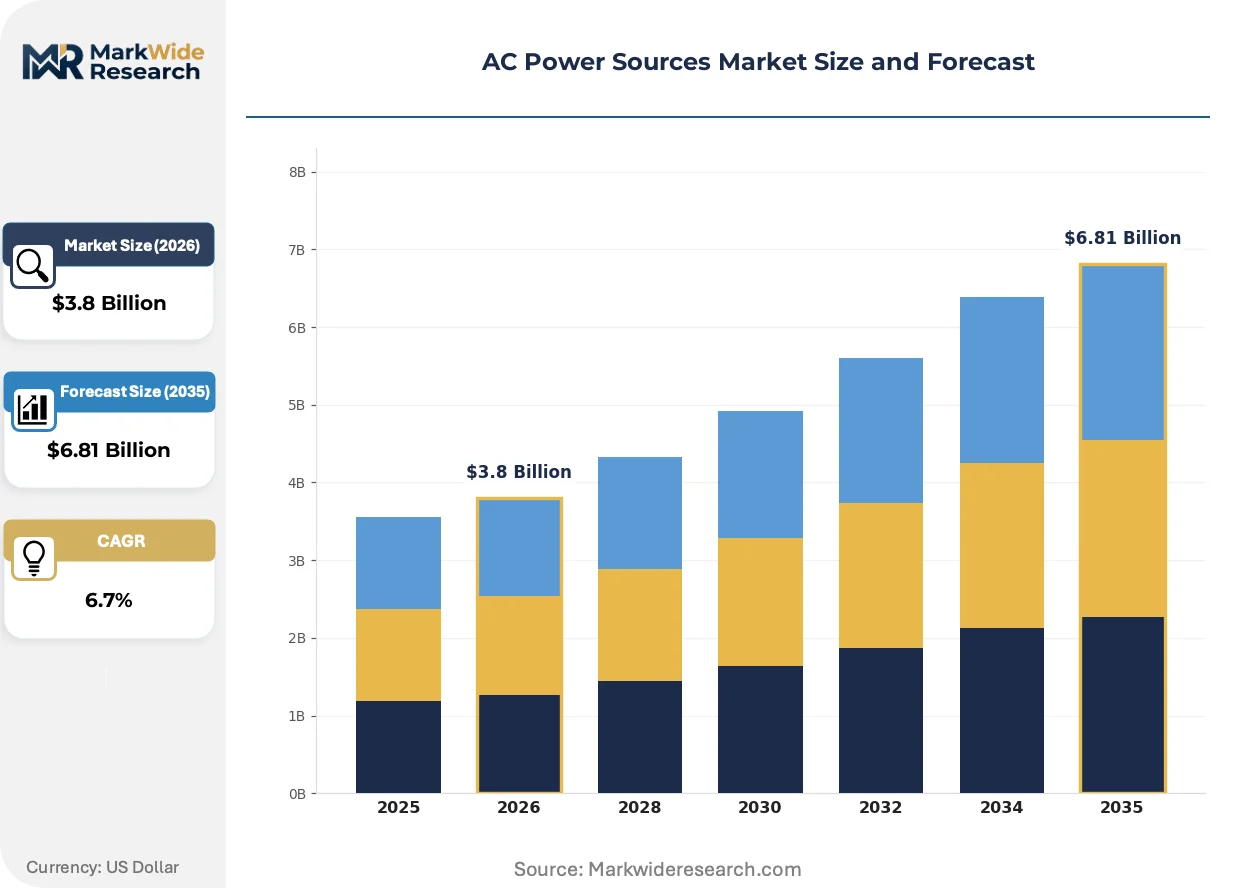
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Programmable, Rack-Mount Technology: Linear, Switching, Inverter, Battery-Backed End User: Telecommunications, Healthcare, Aerospace, Data Centers Application: Testing, Simulation, UPS, Renewable Integration |
| Companies Covered | AMETEK Programmable Power, Chroma ATE, Keysight Technologies, Pacific Power Source, Matsusada Precision, Kikusui Electronics Corporation, Good Will Instrument, Regatron AG, B&K Precision Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Power Sources Market Emerging Trajectories
Digital control architectures are displacing analog waveform generation across mid-range AC source portfolios, compressing price-performance ratios while elevating software-defined functionality as the primary competitive differentiator.
GaN-based output stages are miniaturizing rack-mount AC source footprints by enabling higher switching frequencies with reduced magnetic component mass. Data center commissioning teams in Northern Virginia and Frankfurt are specifying these compact units for dense deployment in hyperscale facility buildouts. The form-factor reduction is collapsing traditional chassis size tiers and enabling new portable field-test configurations previously impractical with silicon-based power stages.
The EU Green Deal's ecodesign trajectory is mandating repairability documentation and extended producer responsibility for industrial power electronics. CE marking obligations now require modular architectures with field-replaceable subassemblies, compelling redesign of integrated source systems. European test equipment distributors are prioritizing suppliers with established spare-part logistics networks to satisfy these aftermarket service requirements.
Telecommunications central offices are consolidating AC source procurement through managed test-service contracts rather than capital equipment purchases. This unbundling of hardware ownership from validation execution is compressing vendor direct sales channels and elevating calibration-chain accreditation as the decisive selection criterion. The shift is most pronounced in South Korea, where KT and SK Telecom infrastructure divisions have adopted outcome-based equipment provisioning models for central office commissioning workflows.
AC Power Sources Market Segmentation
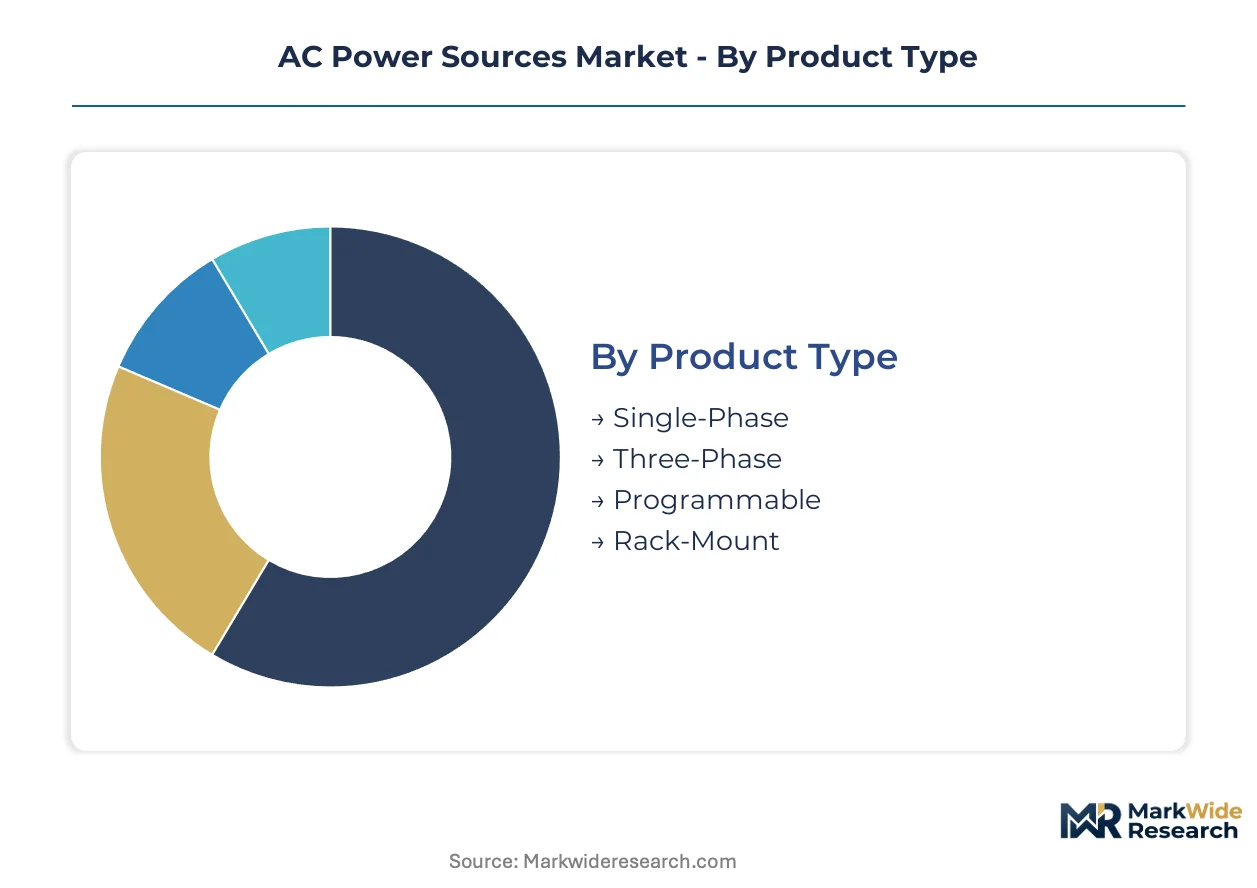
Segmentation in AC power sources reveals how margin pools concentrate in three-phase programmable architectures while volume flows toward rack-mount single-phase units. Understanding these splits exposes where calibration-chain investments and firmware development resources generate returns.
Product Type:
Margin pools concentrate deepest in multi-channel synchronization architectures where phase-angle precision below 0.1 degrees commands premium positioning.
- Three-Phase:Multi-channel units with phase-angle control precision below 0.1 degrees dominate EV powertrain validation and motor-drive emulation. Wafer-level test-bench expansion across Taiwan and South Korea concentrates procurement for these high-specification units near Hsinchu and Pyeongtaek industrial clusters.
- Programmable:Software-defined waveform generation with harmonic distortion below 0.5% serves grid-interaction studies and inverter certification. IEC 61000-4 compliance mandates are forcing replacement of legacy qualification benches, sustaining replacement demand.
- Single-Phase:Rack-mount variants lead unit volumes through dense deployment in telecommunications central offices.
- Rack-Mount:Compact form factors enable hyperscale data center commissioning workflows in Northern Virginia and Frankfurt.
Three-Phase holds installed capacity. Programmable is rotating up the share rankings.
Technology:
Cost tier stratification separates precision linear architectures from mass-market switching implementations.
- Switching:Higher-frequency power stages with reduced magnetic component mass enable compact rack-mount footprints. GaN-based output stages are miniaturizing chassis sizes for data center commissioning teams in Northern Virginia and Frankfurt.
- Linear:Low-noise voltage references deliver harmonic distortion specifications required for aerospace-grade waveform synthesis. Precision component supply concentration in Taiwan creates single-source vulnerability for these architectures.
- Inverter:Grid-simulation capabilities support renewable energy inverter testing protocols.
- Battery-Backed:Uninterruptible validation power for critical test sequences in semiconductor fabrication.
Switching dominates shipment volumes. Linear defends premium positioning through precision specifications.
End User:
Application maturity varies sharply across customer verticals with diverging certification requirements.
- Aerospace:Avionics bus simulation demands precision frequency control with FAA and EASA airworthiness protocols gating market access. Tier-one aerospace suppliers concentrate procurement among vendors with established calibration-chain accreditation.
- Data Centers:Hyperscale facility buildouts in Northern Virginia and Frankfurt specify compact GaN-based units for dense commissioning deployment. Outcome-based equipment provisioning models are compressing direct sales channels.
- Telecommunications:Central office consolidation through managed test-service contracts elevates calibration-chain accreditation as decisive selection criterion.
- Healthcare:Medical device validation requires isolation specifications and safety agency approvals.
Aerospace commands steepest expansion trajectory. Data Centers is climbing the fastest in absolute unit terms.
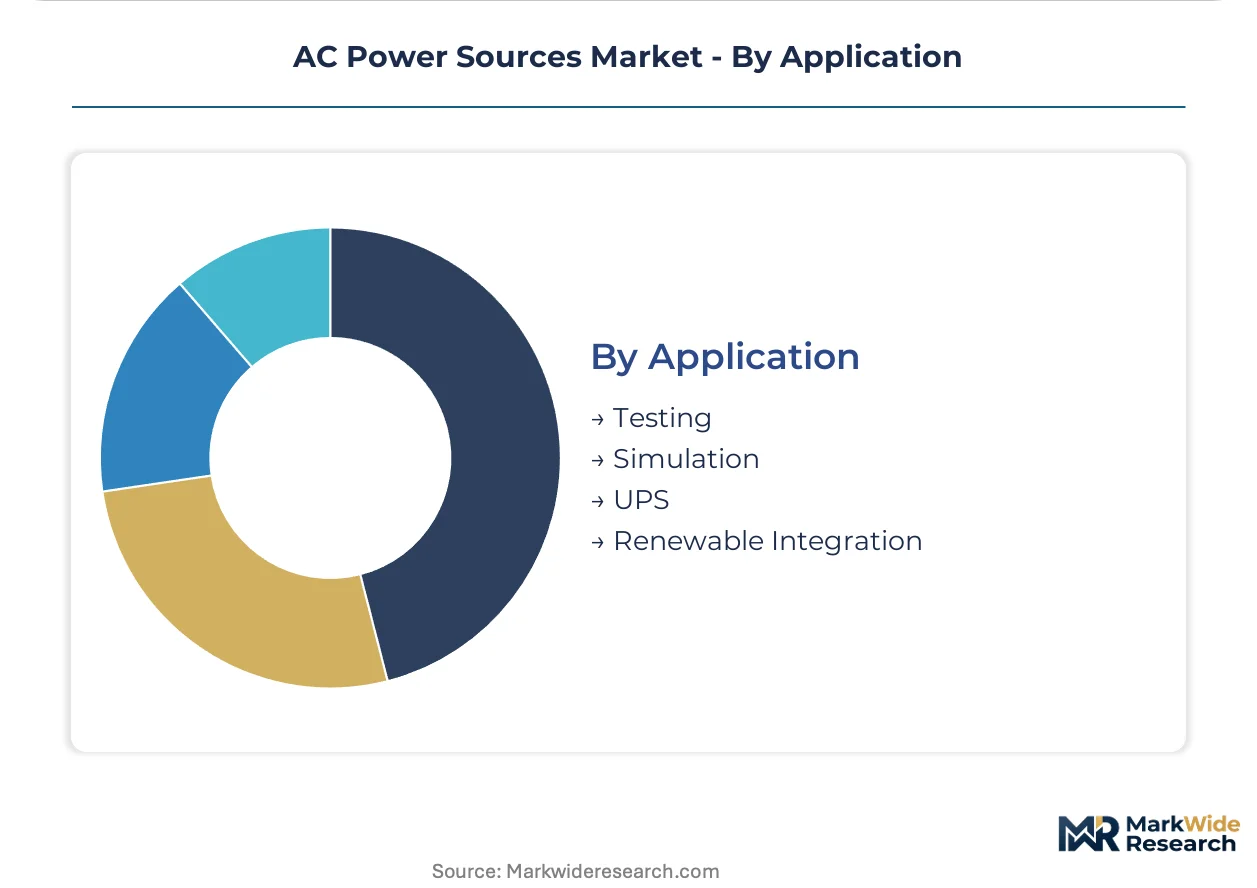
Application:
Customer type differentiation separates capital-equipment purchasers from outcome-based service contract adopters.
- Testing:Product safety certification and burn-in protocols for semiconductor wafer-level validation. Domestic inverter manufacturers in China are scaling in-house metrology laboratories, creating sustained demand for three-phase programmable units.
- Simulation:Grid-interaction studies and electromagnetic compatibility qualification under tightening IEC 61000-4 thresholds. MIL-STD-1399 compliance gates naval and defense procurement access.
- UPS:Uninterruptible power supply verification for enterprise and industrial backup systems.
- Renewable Integration:Inverter interoperability validation for grid-connected power electronics under China's MIIT certification requirements.
Testing holds installed capacity. Simulation is gaining share fastest through regulatory replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification requirements for grid-connected power electronics are accelerating domestic laboratory buildouts, while Taiwan and South Korea expand semiconductor fabrication capacity that demands precision test equipment. Regulatory divergence across IEC, GB standards, and FCC protocols is fragmenting procurement specifications and forcing manufacturers to maintain parallel product development tracks.
China
Domestic inverter and EV powertrain manufacturers are scaling in-house metrology laboratories at unprecedented velocity. MIIT certification requirements for grid-connected power electronics create compliance gates that favor local certification holders over import-dependent rivals. Shenzhen and Shanghai industrial corridors concentrate equipment procurement for three-phase programmable units serving automotive validation workflows.
United States
Hyperscale data center buildouts in Northern Virginia are specifying compact GaN-based AC sources for dense commissioning deployment. FCC Part 15 emissions constraints and NHTSA electrical-safety protocols shape product development roadmaps for automotive test equipment. Austin and Dallas-Fort Worth technology corridors anchor demand for aerospace-grade waveform synthesis systems serving tier-one defense contractors.
Taiwan
Semiconductor fabrication facilities in Hsinchu are expanding wafer-level validation capacity with dedicated burn-in and stress-testing protocols. Precision component supply concentration for high-stability voltage references creates single-source vulnerability that shapes procurement risk assessments. The Hsinchu Science Park industrial cluster concentrates equipment orders for programmable architectures with sub-0.5% harmonic distortion specifications.
Germany
Industrial automation and renewable energy inverter manufacturers are driving demand for grid-simulation equipment under tightening electromagnetic compatibility thresholds. REACH substance restrictions and CE marking obligations under the EU Green Deal's ecodesign trajectory force reformulation of thermal interface materials. The Munich-Stuttgart industrial corridor concentrates procurement for MIL-STD-1399-compliant naval power systems serving European defense modernization programs.
South Korea
KT and SK Telecom infrastructure divisions have adopted outcome-based equipment provisioning models that compress traditional vendor direct sales channels. Wafer-level test-bench expansion near Pyeongtaek is compressing equipment procurement cycles and accelerating calibration-chain certification timelines. The Pyeongtaek industrial cluster concentrates orders for three-phase units with phase-angle control precision below 0.1 degrees.
AC Power Sources Market Vendor Landscape
Player mix skews toward vertically integrated test equipment specialists with accredited calibration facilities and certified standards chains. The supplier base collapses around firms capable of IEC 61000-4 compliance, with capital barriers excluding smaller participants. Three archetypes dominate: precision waveform synthesis specialists, three-phase naval power system providers, and semiconductor test heritage firms. Competitive positioning hinges on geographic certification acceleration and modular architecture redesign for EU repairability mandates.
Among precision instrumentation specialists, Chroma ATE exemplifies the semiconductor test heritage archetype, while Keysight Technologies occupies a position within precision waveform synthesis tiers. Pacific Power Source represents the specialized defense-application segment. These three anchors illustrate how calibration-chain accreditation and firmware engineering concentration determine market access across diverging regional compliance tracks.
| Leading Market Players |
|---|
| AMETEK Programmable Power |
| Chroma ATE |
| Keysight Technologies |
| Pacific Power Source |
| Matsusada Precision |
| Kikusui Electronics Corporation |
| Good Will Instrument |
| Regatron AG |
| B&K Precision Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwanese precision component foundries lock in both high-stability voltage reference supply and price visibility for AC source manufacturers serving semiconductor test-bench expansion. These arrangements insulate qualified suppliers from spot-market volatility while collapsing the viable supplier base to firms with certified calibration chains.
Pricing Analysis
Certification level (IEC 61000-4/MIL-STD-1399/CE marking tier) creates the primary spread between premium three-phase programmable units and economy single-phase rack-mount variants. Three-tier pricing structure across aerospace-grade, industrial-standard, and entry-level configurations reflects harmonic distortion specifications and phase-angle precision thresholds. Cost compression in mid-range switching architectures is intensifying because GaN-based output stages displace traditional silicon power stages. Data center commissioning teams exhibit highest price sensitivity due to outcome-based equipment provisioning models, while naval defense procurement shows lowest sensitivity given MIL-STD-1399 compliance gating.
Supply Chain Analysis
Extended lead times for high-stability voltage references and low-noise amplifiers now stretch eighteen to twenty-four months, constraining output for linear AC source architectures. Manufacturing concentrates in Taiwan, South Korea, and Germany, with precision component fabrication anchored in Hsinchu and Pyeongtaek industrial clusters. Raw material dependencies include rare-earth magnetic core laminations, thermal interface compounds, and specialized ceramic capacitors. Single-source vulnerability for voltage reference foundry capacity represents the dominant structural risk. Distribution runs through vertically integrated test equipment specialists with accredited calibration facilities rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AC power sources function as a service-attach business where calibration-chain accreditation and field-replaceable subassembly logistics generate recurring revenue expanding faster than hardware shipments. Aftermarket service contracts now determine vendor selection in telecommunications and data center verticals.
For Market Incumbents: Fortify calibration-chain certification timelines to match compressed semiconductor fab ramp schedules in Taiwan and South Korea. Deepen backward integration into precision voltage reference sourcing to mitigate single-source foundry vulnerability. Lock in long-term capacity reservations with Hsinchu-based component suppliers before procurement cycles tighten further. For New Entrants and Emerging Players: Anchor in China's domestic MIIT certification track for grid-connected power electronics, where local certification accelerates market access versus import-dependent rivals. Target naval power systems modernization programs requiring MIL-STD-1399 compliance, a defensible niche with limited qualified competitors. Pursue managed test-service contract partnerships with telecommunications operators adopting outcome-based equipment provisioning models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated test equipment specialists with accredited facilities and certified standards chains. Long-term viability hinges on firmware engineering concentration for multi-channel synchronization and modular architecture redesign for EU repairability mandates. Monitor IEC harmonization progress as the decisive inflection indicator for stranded compliance investment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-Chain Accreditation Investment | CE marking and IEC 61000-4 compliance gates market access for European grid-simulation equipment procurement. |
| GaN Output Stage Integration | Compact rack-mount footprints enable dense deployment in Northern Virginia and Frankfurt hyperscale data centers. |
| Modular Architecture Redesign | EU Green Deal repairability mandates require field-replaceable subassemblies with documented spare-part logistics. |
| MIIT Certification Localization | China's GB standards create parallel compliance tracks favoring domestic certification holders over import rivals. |
| Naval Power Systems Specialization | MIL-STD-1399-compliant three-phase configurations serve European defense modernization with extended procurement cycles. |
Methodological Framework
Initial hypotheses were tested against primary input from test equipment procurement managers, semiconductor fab operations directors, calibration laboratory supervisors, and aerospace validation engineers and refined through secondary validation. Primary interviews combined with regulatory filing analysis (IEC standards documentation, FCC Part 15 emissions filings, EASA airworthiness protocols), trade data from customs records, and SEC disclosures from listed test equipment manufacturers. Bottom-up shipment estimates and top-down market sizing triangulated across product type, technology architecture, end-user vertical, and geographic certification cluster.
Variance decomposition across the projection horizon isolates volume drivers (semiconductor fab expansion, EV powertrain laboratory buildouts) from price drivers (certification tier mix, GaN cost curves). Segmentation dimensions modeled include phase configuration, waveform generation technology, end-user industry maturity, and regional regulatory framework. CAGRs derive from installed base replacement cycles, new capacity absorption rates, and technology substitution elasticities. Forecast inputs incorporate IEC 61000-4 harmonization timelines and silicon carbide inverter switching frequency thresholds beyond conventional AC source emulation ranges.
Material uncertainties — tariff exposure on precision components, sudden IEC standard revision, or wide-bandgap power electronics substitution — sit outside the modeled envelope. Forecasts reflect assumptions about calibration infrastructure buildout pacing and regional certification reciprocity that could shift materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Magnetic Bearing Market
Power Equipment
Power Cables Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
China Power EPC Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Power Infrastructure Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Induction Heating System Market
Power Equipment
SCR Power Controller Market
Power Equipment
Asia-Pacific Steam Turbine Market