
 Consumer Network Attached Storage Market | 2026-2036
Consumer Network Attached Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Network Attached Storage Market Intelligence
Small home offices and creative professionals are redrawing demand patterns in consumer network attached storage. Synology leverages its DiskStation ecosystem to anchor premium mindshare among productivity-focused buyers. QNAP competes through aggressive hardware specifications and expandability options for power users. Western Digital sustains volume leadership through vertical integration from hard disk manufacturing to branded NAS enclosures.
Consumer network attached storage denotes dedicated file-level data storage servers connected to home or small-office networks, typically operating on ARM or x86 processors with two to eight drive bays supporting SATA or NVMe interfaces and RAID configurations for redundancy. These systems serve primary purposes of centralized backup, media streaming, and remote file access without recurring cloud subscription fees. Multi-bay units lead hardware shipments as users prioritize storage scalability and data protection, while media streaming use cases generate the fastest-growing engagement as 4K and 8K content libraries expand. RAID technology underpins buyer confidence in data integrity, though cloud-hybrid architectures now capture margin pools from subscription-averse consumers seeking offsite redundancy.
FCC equipment authorization requirements govern wireless-enabled NAS devices in the United States, while GDPR data processing rules in Europe shape product roadmaps toward local encryption and zero-knowledge architectures. CE marking mandates under EU radio equipment directives constrain import timelines for Asian manufacturers. Stakeholders must monitor evolving energy efficiency regulations and right-to-repair legislation that could mandate modular designs and extended software support obligations.
Market Dynamics
GDPR data sovereignty mandates and similar national privacy frameworks are redirecting storage procurement away from hyperscale cloud providers toward self-hosted infrastructure, compressing the addressable market for subscription-based alternatives while expanding hardware attach rates for encrypted local systems.
Growth Catalysts
- 4K/8K Content Workflows:Video creators and home studios require multi-bay RAID systems for direct-to-NAS editing and proxy generation, eliminating transfer bottlenecks from external drives.
- GDPR Article 44 Restrictions:Cross-border data transfer limitations push European small businesses toward on-premise storage with local encryption keys rather than US-hosted cloud services.
- Remote Work Infrastructure:Distributed teams in Germany and South Korea deploy VPN-accessible NAS units as centralized file servers replacing office-bound DAS arrays.
Market Restraints
- NAND Flash Cost Volatility:NVMe cache module pricing fluctuates with foundry utilization rates, compressing margins on performance-tier units targeting creative professionals.
- Hard Disk Supply Concentration:Three manufacturers control platter production, creating vulnerability to facility disruptions in Thailand and Singapore assembly plants.
- Technical Support Burden:RAID rebuild failures and cryptolocker incidents generate disproportionate service costs relative to hardware margins for entry-level two-bay systems.
Strategic Opportunities
- India Broadband Expansion:Fiber-to-the-home rollout in Tier-2 cities creates first-time NAS demand among remote workers previously limited to USB external storage.
- Right-to-Repair Mandates:EU legislation requiring modular component access and extended firmware support opens service revenue streams and reduces replacement cycle pressure.
- AI-Assisted Media Indexing:On-device machine learning for photo recognition and video transcription differentiates premium units from basic file servers without cloud dependency.
Industry Challenges
- Embedded Linux Security Patching:ARM-based systems run aging kernel versions with limited vendor update commitments, exposing SOHO users to unpatched CVEs.
- Legacy SMB Protocol Deprecation:Microsoft elimination of SMB1 support breaks compatibility with older smart TVs and streaming boxes, forcing firmware re-engineering.
- Certification Timeline Compression:FCC Part 15 and CE RED testing for WiFi 6E variants delays product launches by 8-14 weeks against aggressive competitor cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Network Attached Storage Market |
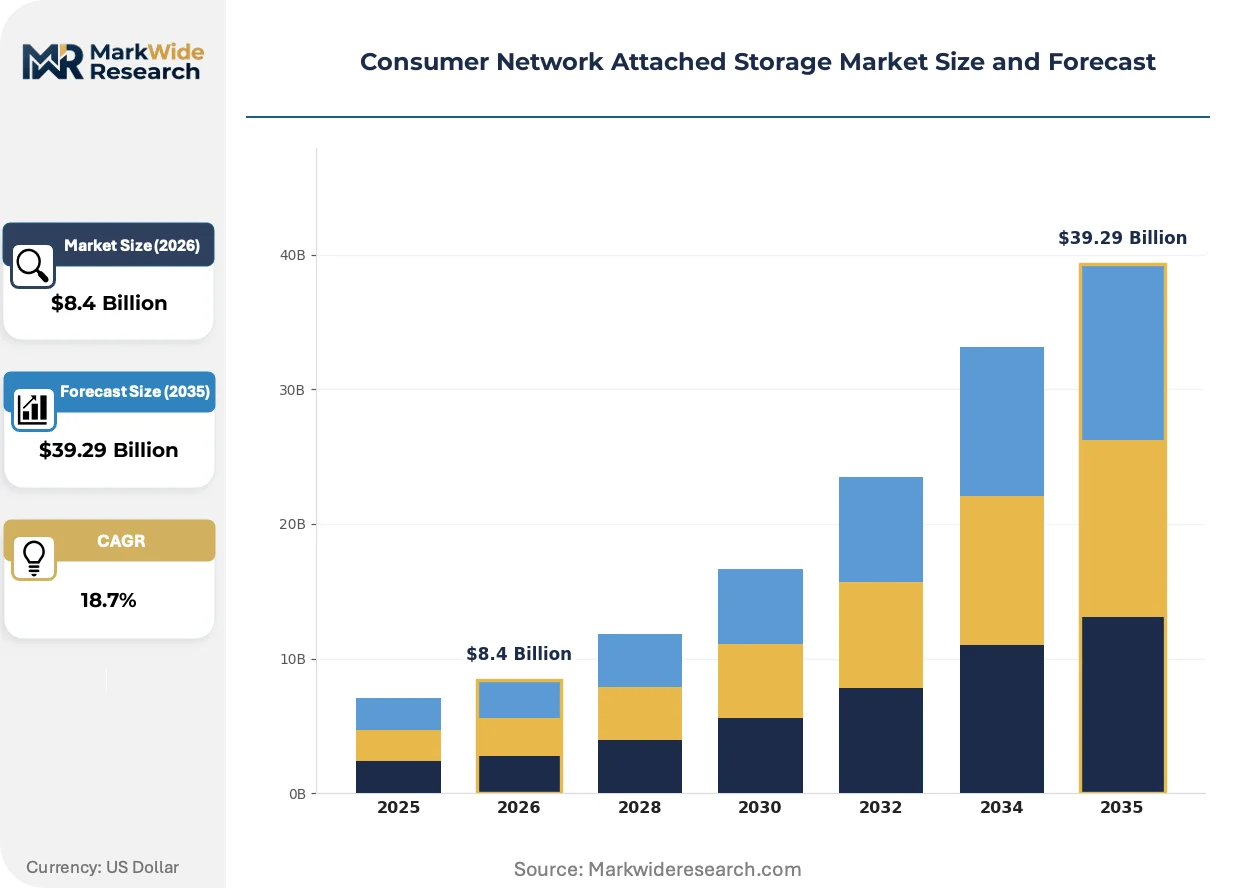
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Bay, Multi-Bay, Rackmount, DAS Technology: NAS, SAN, Cloud Storage, RAID Use Case: Home Backup, Media Streaming, File Sharing, Remote Access End User: Home Users, Small Businesses, Gamers, Content Creators |
| Companies Covered | Ubiquiti, TerraMaster, Synology, Netgear, Western Digital, ASUS, QNAP, Buffalo, UGREEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Network Attached Storage Market Strategic Shifts & Innovations
Storage architecture is bifurcating between all-flash performance tiers for video production and high-capacity HDD-centric cold storage, with software-defined features eroding hardware differentiation at the mid-market level.
NVMe all-flash arrays are supplanting SATA SSD caching in prosumer NAS units, delivering sustained sequential throughput exceeding 2GB/s for direct 4K timeline playback. Content creators operating DaVinci Resolve and Adobe Premiere workstations now specify NVMe pools as baseline requirements, forcing vendors to redesign thermal management and power delivery subsystems previously optimized for slower interfaces.
GDPR's data portability and erasure mandates are accelerating zero-knowledge encryption adoption across EU-bound product lines, requiring hardware security module integration for key management. Manufacturers must now architect systems where even firmware updates cannot access user data, complicating remote diagnostics and automated troubleshooting workflows previously standard in consumer electronics.
Subscription fatigue among home office buyers is collapsing cloud-hybrid bundling strategies that positioned NAS hardware as gateway drug to recurring revenue. Purchasers in the United States and Germany increasingly reject vendor-managed backup services, demanding instead open-protocol sync with self-selected third-party object storage or pure offline operation, compressing lifetime value calculations for ecosystem-dependent vendors.
Consumer Network Attached Storage Market Segmentation
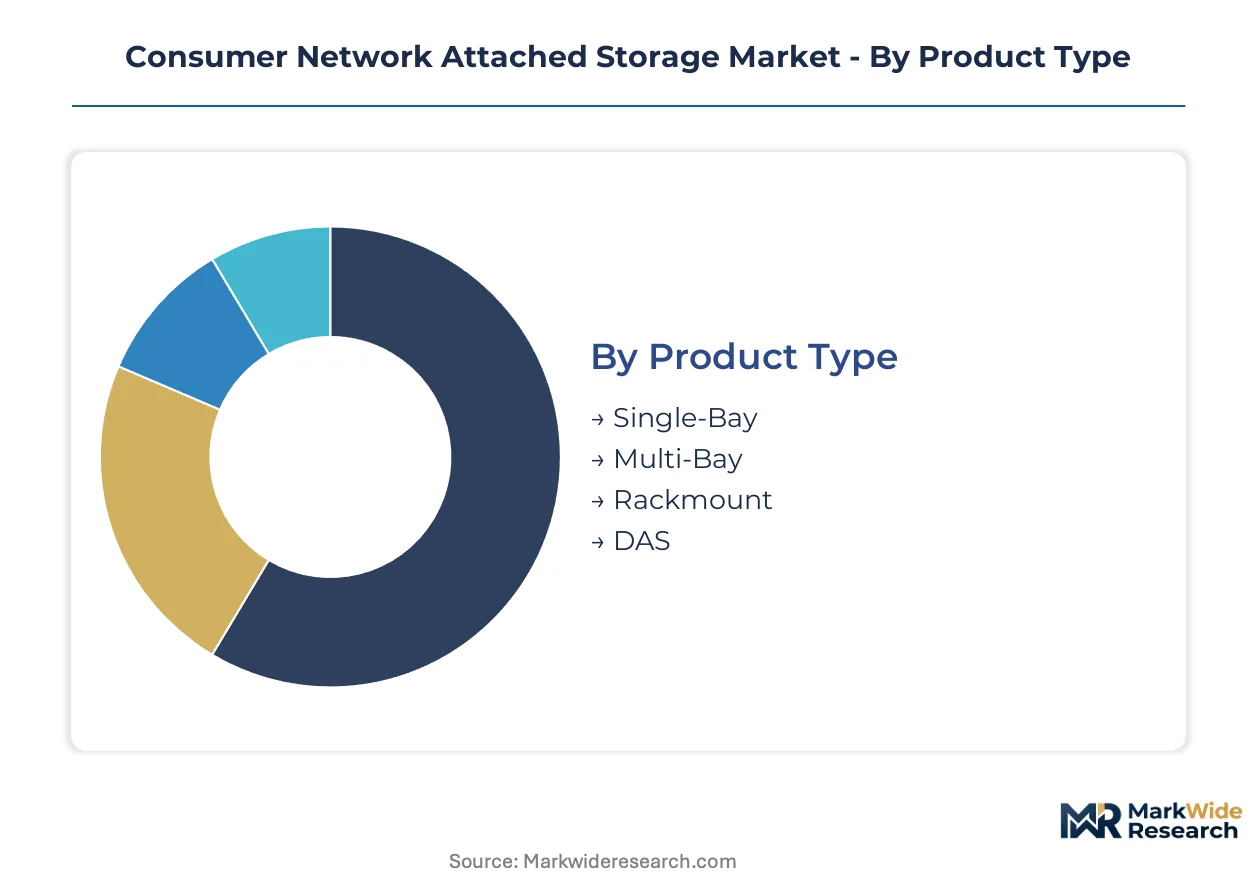
Segmentation in consumer NAS reveals how hardware configuration, deployment architecture, and user workflow requirements create distinct margin profiles and substitution vulnerabilities across the market landscape.
Product Type:
Cloud storage services and external SSDs exert the strongest substitution pressure on entry-level configurations, while multi-bay and rackmount systems defend their positions through data sovereignty and performance attributes that hosted alternatives cannot replicate.
- Multi-Bay:These units accommodate two to eight drive bays with RAID 1, 5, or 6 configurations, delivering redundant storage pools that content creators in Germany and South Korea specify for 4K video proxy workflows. The format commands premium positioning as GDPR-conscious buyers reject cloud dependency for primary storage.
- Single-Bay:Compact enclosures housing one SATA or NVMe drive serve basic backup needs for home users seeking centralized storage without redundancy overhead. USB 3.2 and 2.5GbE connectivity options dominate this tier, though cloud subscription bundles increasingly erode hardware attach rates.
- Rackmount:1U and 2U chassis designs target small business server closets with redundant power supplies and 10GbE networking. These systems integrate with Active Directory and LDAP services, appealing to remote work infrastructure deployments requiring centralized authentication.
- DAS:Direct-attached storage enclosures connect via USB-C or Thunderbolt without network stack complexity, serving video editors prioritizing latency over multi-user access. The segment faces steep compression from NVMe external SSDs offering superior portability.
Multi-bay configurations anchor the volume base while rackmount systems gain share at the steepest rate among commercial deployments.
Technology:
Cost tier differentiation separates enterprise-grade architectures from consumer implementations, with software-defined features collapsing hardware premiums at mid-market price points.
- NAS:File-level storage servers operating on embedded Linux or BSD kernels deliver SMB, NFS, and AFP protocol support for heterogeneous client environments. ARM and x86 processor variants span entry-level to performance tiers, with Intel Atom and AMD Ryzen V-series chips dominating prosumer specifications.
- RAID:Redundant array configurations spanning RAID 0 striping through RAID 10 mirroring protect against single or dual drive failures. Hardware RAID controllers maintain relevance in rackmount segments despite software RAID advances in consumer units, as kernel-level implementations reduce cost and power consumption.
- SAN:Block-level storage architectures remain rare in consumer deployments, appearing primarily in rackmount conversions targeting small business virtualization clusters. iSCSI and Fibre Channel over Ethernet protocols require network infrastructure investments that exceed typical home office budgets.
- Cloud Storage:Hybrid architectures synchronizing local NAS caches with object storage backends face collapsing demand as subscription fatigue drives buyers toward pure offline operation. Vendors now position these as optional rather than bundled features.
RAID technology anchors the volume base while NAS software stacks gain share fastest through ecosystem differentiation.
Use Case:
Application-driven purchasing patterns separate backup-centric buyers from performance-sensitive workflows, with media streaming generating the steepest engagement growth as 4K libraries expand.
- Media Streaming:Plex, Jellyfin, and DLNA server implementations transcode 4K and 8K content for client devices lacking direct playback capability. Hardware-accelerated encoding via Intel Quick Sync or NVIDIA NVENC differentiates premium units, with United States households driving demand for multi-stream concurrent delivery.
- Home Backup:Time Machine, rsync, and vendor-proprietary agents consolidate laptop and mobile device snapshots onto centralized storage. This foundational use case faces commoditization as router-integrated USB storage and cloud alternatives compete on simplicity.
- File Sharing:Cross-platform SMB and AFP access enables household document collaboration without cloud intermediary latency. Sync solutions like Synology Drive and QNAP Qsync replicate Dropbox functionality while maintaining local data control.
- Remote Access:VPN and reverse proxy configurations enable WAN-side file retrieval, with Tailscale and ZeroTier integration simplifying mesh networking setup for non-technical users. Germany's remote work penetration supports strong deployment rates.
Home backup anchors the volume base while media streaming climbs the fastest as content libraries scale beyond local device capacity.
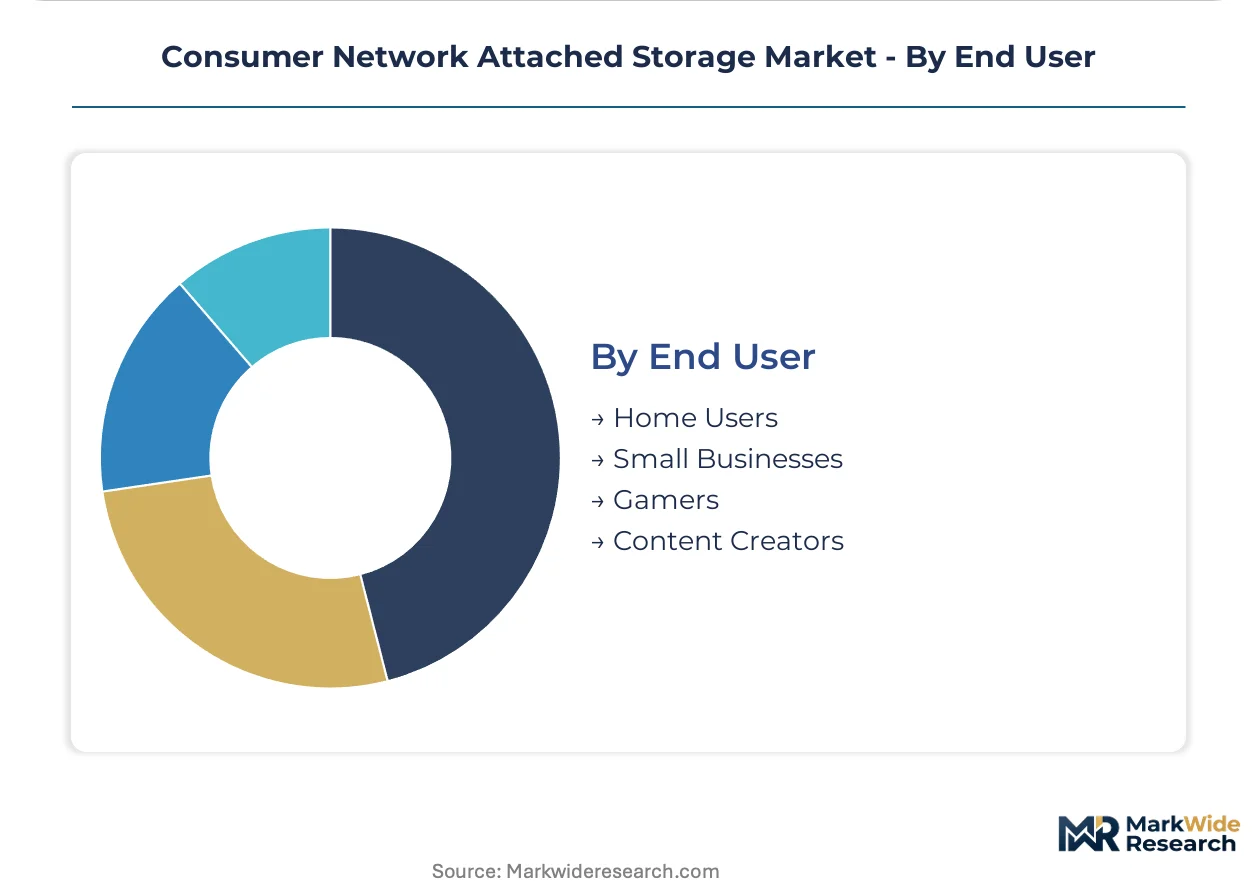
End User:
Customer type segmentation maps directly to margin structure, with content creators and small businesses extracting premium pricing through performance requirements that home users cannot justify.
- Content Creators:Video editors, photographers, and music producers specify NVMe caching, 10GbE networking, and direct-to-NAS editing capabilities. DaVinci Resolve and Adobe Premiere proxy workflows in United States and South Korea home studios drive specification inflation beyond typical consumer budgets.
- Small Businesses:Remote work infrastructure deployments in Germany replace office-bound DAS arrays with VPN-accessible centralized storage. GDPR Article 44 compliance requirements accelerate procurement of encrypted local systems over US-hosted cloud alternatives.
- Home Users:Families consolidating photos, documents, and media libraries across multiple devices represent the broadest addressable base. Price sensitivity concentrates demand at two-bay entry points with periodic external drive backup for redundancy.
- Gamers:Steam library centralization and console storage expansion constitute a niche segment, with PlayStation 5 and Xbox Series X compatibility requirements driving USB and Ethernet-attached configurations rather than traditional NAS protocols.
Home users anchor the volume base while content creators expand most quickly through professional workflow migration into residential settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content creators and small home offices concentrate procurement in markets with robust broadband infrastructure and stringent data sovereignty frameworks. Germany, the United States, South Korea, Japan, and the United Kingdom represent the dominant demand centers.
United States
Media streaming workflows and 4K video production drive multi-bay NAS adoption among home studios in Los Angeles and Austin. FCC Part 15 equipment authorization governs wireless-enabled device distribution. Seattle's tech corridor hosts power-user clusters specifying NVMe all-flash configurations for direct-to-NAS editing.
Germany
GDPR Article 44 cross-border transfer restrictions accelerate encrypted local storage procurement by Berlin and Munich remote work clusters. BSI technical guidelines shape cybersecurity certification requirements for SOHO deployments. Bavaria's creative industry concentration in Munich sustains premium-tier hardware demand.
South Korea
High-density urban housing and gigabit fiber penetration support compact multi-bay deployments for Seoul and Busan content creators. MFDS data governance frameworks influence enterprise-adjacent consumer specifications. Pangyo Techno Valley clusters drive early adoption of AI-assisted media indexing features.
Japan
Disaster recovery consciousness and limited residential space fuel demand for compact redundant systems in Tokyo and Osaka home offices. METI energy efficiency regulations constrain thermal design specifications. Akihabara retail clusters sustain enthusiast-grade component distribution channels.
United Kingdom
Post-Brexit data localization preferences redirect small business storage procurement toward self-hosted infrastructure in London and Manchester. UK GDPR implementation maintains alignment with EU erasure and portability mandates. Cambridge's media technology corridor generates specialized workflow requirements.
Consumer Network Attached Storage Market Key Industry Players
Player mix skews toward vertically integrated storage specialists competing against modular ecosystem architects. Three manufacturers control hard disk supply, creating upstream concentration that downstream enclosure vendors navigate through partnership structures. Strategic archetypes separate software-integrated platform builders from hardware-centric specification competitors and component-integrated volume players. Competitive moves center on thermal engineering advancement and firmware security commitment extension.
Within the ecosystem-integrated tier, Synology and QNAP occupy positions defining software-forward NAS architecture, while Western Digital anchors the component-integrated volume segment through captive hard disk supply. These three exemplify divergent approaches to margin capture: subscription-avoidant software licensing, hardware specification escalation, and vertical control over magnetic storage supply.
| Leading Market Players |
|---|
| Ubiquiti |
| TerraMaster |
| Synology |
| Netgear |
| Western Digital |
| ASUS |
| QNAP |
| Buffalo |
| UGREEN |
| Others |
Cost & Logistics Intelligence
FCC Part 15 equipment authorization and CE RED certification requirements gate both component qualification and price differentiation in consumer NAS, forcing vendors to absorb 8-14 week testing timelines that compress margins on entry-tier units while enabling premium positioning for certified performance-tier configurations.
Pricing Analysis
NVMe all-flash generation pricing gaps separate current-gen 2GB/s throughput units from prior-gen SATA-cached systems and emerging WiFi 6E-enabled next-gen enclosures. Three-tier pricing structure across premium, standard, and economy levels tracks hardware RAID controller inclusion, 10GbE networking presence, and thermal design certification grade. Cost compression in entry-level two-bay segments is intensifying because USB external storage and router-integrated alternatives erode attach rates. Home users exhibit highest price sensitivity, while content creators in Germany and South Korea accept substantial premiums for direct-to-NAS editing capability.
Supply Chain Analysis
Thailand and Singapore assembly plant concentration creates chokepoint vulnerability for hard disk-dependent enclosure manufacturers. Platter production draws from Thailand, China, and Malaysia fabrication facilities, while NAND flash supply rests on South Korea and Taiwan foundry output. Single-source vulnerability in ARM processor supply from specific Taiwanese semiconductor houses exposes vendors to allocation disruptions. Distribution runs through Amazon and B2B IT channel partners in the United States, Germany, and South Korea, with direct-to-consumer attach rates climbing as vendor ecosystems mature.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer NAS market is recovering from NAND flash cost cyclicality, with foundry utilization normalization restoring margin headroom for performance-tier vendors previously squeezed by cache module volatility.
For Market Incumbents: Shield ecosystem lock-in against subscription-fatigue erosion by extending DiskStation and QTS firmware support commitments to seven-year windows, matching emerging right-to-repair mandates. Deepen backward integration into thermal management subsystems to differentiate from modular competitors sourcing common heatsink designs. Channel control through authorized distributor networks in Germany and South Korea remains critical as gray-market imports undercut CE-certified pricing.
For New Entrants and Emerging Players: Lead with AI-assisted media indexing as a software-differentiated wedge against hardware-specification incumbents, targeting content creator segments in India Tier-2 cities where broadband expansion creates first-time NAS demand. White-space availability concentrates in compact single-bay NVMe units for urban South Korean apartments, and in rackmount conversions for small Berlin businesses replacing office-bound DAS arrays. Direct-to-consumer positioning through YouTube creator partnerships bypasses entrenched channel relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from hard disk manufacturers seeking downstream enclosure integration to offset cloud-storage demand erosion. Long-term viability hinges on software-defined feature monetization as hardware margins compress across the analysis window. Watch for GDPR Article 44 enforcement intensity as signal for European self-hosted storage procurement acceleration versus US-hosted cloud alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Commitment Extension | Seven-year update pledges differentiate Synology and QNAP against ARM-based competitors with aging kernel exposure. |
| NVMe All-Flash Thermal Engineering | Redesigned power delivery and heatsink architectures enable sustained 2GB/s throughput for DaVinci Resolve workflows. |
| Zero-Knowledge Encryption Integration | Hardware security module adoption satisfies BSI guidelines and GDPR erasure mandates for Munich creative clusters. |
| India Broadband Expansion Partnership | Fiber-to-the-home rollout in Tier-2 cities creates first-time NAS demand beyond USB external storage limitations. |
| Right-to-Repair Modular Design | EU legislation compliance opens service revenue streams and extends replacement cycles for Berlin small businesses. |
Research Approach
The analysis maps multi-bay, single-bay, rackmount, and DAS configurations, each validated through product managers at Synology, QNAP, and Western Digital, procurement leads at German creative agencies, and channel partners in Seoul and Tokyo. Primary interviews combined with secondary validation against FCC equipment authorization databases, CE marking registries, BSI technical guideline publications, and customs import records for Thailand-assembled hard disk shipments. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across hardware and software-defined segments.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, broadband penetration statistics from OECD and national regulators, and creative software license sales data from Adobe and Blackmagic Design. The modeling framework segments by product type, technology stack, use case intensity, and end-user sophistication, with CAGRs derived from elasticity-adjusted adoption curves and replacement cycle dynamics. Forecast inputs incorporated NAND flash foundry utilization rates, GDPR enforcement case volumes, and remote work infrastructure deployment surveys from Germany and South Korea.
The analysis sits within stated boundaries; outcomes outside sustained broadband infrastructure investment, stable foundry utilization, or consistent GDPR enforcement would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory trajectory. Practitioners should keep alternative scenarios live as right-to-repair legislation timelines and ARM processor supply allocation policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Stand Alone Cloud Storage Market