
 Denmark Data Center Storage Market | 2026-2036
Denmark Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Storage Market Insights
Danish hyperscale facility operators is pivoting toward liquid-cooled storage architectures to manage thermal loads from AI training workloads. Microsoft Azure leverages its Odense region presence to anchor enterprise cloud storage contracts across Scandinavia. Dell Technologies competes through direct attached storage specialization for on-premises financial workloads in Copenhagen.
Data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, with flash arrays achieving sub-millisecond latency and HDDs delivering up to 24 TB per spindle for archival tiers. Network attached storage leads the product type landscape for Danish SMEs requiring file-level access without dedicated SAN infrastructure. Flash storage dominates technology procurement among Copenhagen-based quant funds where microsecond latency directly determines trading profitability. Hybrid storage deployments are expanding fastest among healthcare end users balancing electronic patient record accessibility against long-term imaging archive economics.
BIS compliance requirements for cross-border data residency intersect with Denmark's implementation of EU GDPR and the EU AI Act's training data provenance rules. The Danish Energy Agency enforces efficiency standards that favor flash storage adoption over mechanical disk arrays in new facility certifications. Stakeholders must weigh the capital intensity of all-flash expansion against hybrid configurations that preserve HDD economics for cold tier retention.
Market Dynamics
Liquid-cooled storage architectures are compressing thermal design constraints for Danish hyperscale operators managing AI training loads. Copenhagen's financial district concentrates demand for microsecond-latency flash arrays, while the Danish Energy Agency enforces efficiency standards that accelerate mechanical-to-solid-state transitions.
Growth Catalysts
- EU AI Act compliance mandates:Training data provenance rules require Danish enterprises to expand provenance-tracking storage infrastructure. Financial services firms in Copenhagen upgrade systems to satisfy audit trail retention requirements.
- Algorithmic trading expansion:Quant funds drive procurement of NVMe-oF arrays for tick-data analytics. Sub-millisecond latency directly determines profitability for high-frequency strategies deployed across Denmark's financial sector.
- Odense hyperscale cluster concentration:Microsoft's regional cloud presence anchors enterprise storage demand across Jutland and Funen. Colocation providers expand capacity to capture spillover from Azure's Scandinavian footprint.
Market Restraints
- Flash memory supply concentration:NAND fabrication concentrates in South Korea and Taiwan, exposing Danish buyers to geopolitical supply shocks. Long lead times for enterprise SSDs constrain expansion timelines.
- GDPR-BIS data residency friction:Cross-border replication requirements complicate hybrid cloud architectures. Danish firms face compliance costs for maintaining primary storage within national boundaries.
- HDD archival economics persistence:Cold tier retention costs favor mechanical disks for imaging archives. Healthcare providers delay all-flash conversions for non-critical workloads.
Strategic Opportunities
- Zealand edge deployment whitespace:Suburban Copenhagen lacks distributed storage nodes for IoT and autonomous vehicle data processing. Telecom operators seek localized infrastructure partnerships.
- Healthcare hybrid convergence:Electronic patient record systems require tiered storage combining flash hot tiers with tape archives. Regional hospitals represent underpenetrated mid-market accounts.
- Danish Energy Agency efficiency incentives:Power Usage Effectiveness bonuses for flash-adopting facilities create procurement tailwinds. New data center certifications reward solid-state thermal profiles.
Industry Challenges
- Liquid cooling integration complexity:Retrofitting existing Copenhagen facilities demands specialized mechanical contractors. Skill scarcity in immersion cooling engineering extends deployment timelines.
- Legacy SAN migration friction:Financial institutions maintain decades-old Fibre Channel investments. Parallel infrastructure requirements strain capital allocation during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Storage Market |
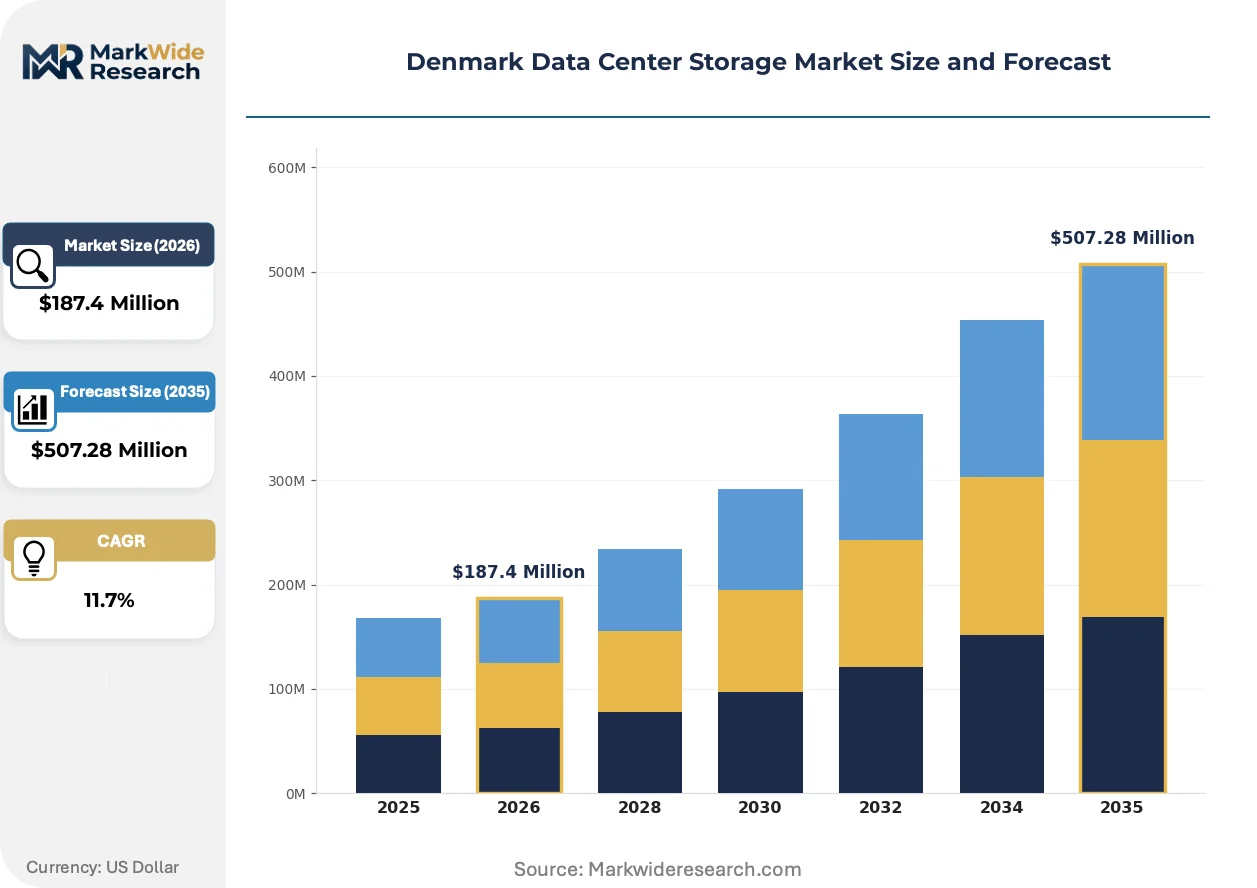
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage Technology: Flash Storage, Hard Disk Drives, Hybrid Storage, Optical Storage End User: IT Services, Government, Telecom, Healthcare Deployment: On-Premises, Off-Premises, Hybrid, Multi-Cloud |
| Companies Covered | Microsoft Azure, Amazon Web Services, Google Cloud, IBM, Dell Technologies, Hewlett Packard Enterprise, NetApp, Pure Storage, GlobalConnect, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Storage Market Trends and Innovations
Computational storage is compressing data movement bottlenecks for Danish AI workloads. Regulatory pressure from Brussels reshapes provenance architecture. Procurement patterns among Copenhagen quant funds accelerate specialized array deployment.
Computational storage drives (CSDs) embed processing capability directly within NAND packages, eliminating host CPU bottlenecks for analytics workloads. Danish hyperscale operators in Odense pilot SmartSSD deployments for training pipeline preprocessing. This architecture is unifying storage and compute silos, reducing rack space requirements for machine learning infrastructure.
The EU AI Act's training data documentation requirements impose granular provenance tracking on Danish enterprise storage systems. Article 10 mandates immutable audit trails for model development datasets. Copenhagen-based financial services firms reconfigure object storage architectures to capture lineage metadata at ingestion.
Danish quant funds compress storage procurement cycles from three-year to eighteen-month refresh intervals. Microsecond latency advantages from newer NVMe generations drive accelerated replacement of prior-generation flash. This pattern concentrates among algorithmic trading shops in Copenhagen's financial district, where hardware depreciation schedules now match software release cadences.
Denmark Data Center Storage Market Segmentation
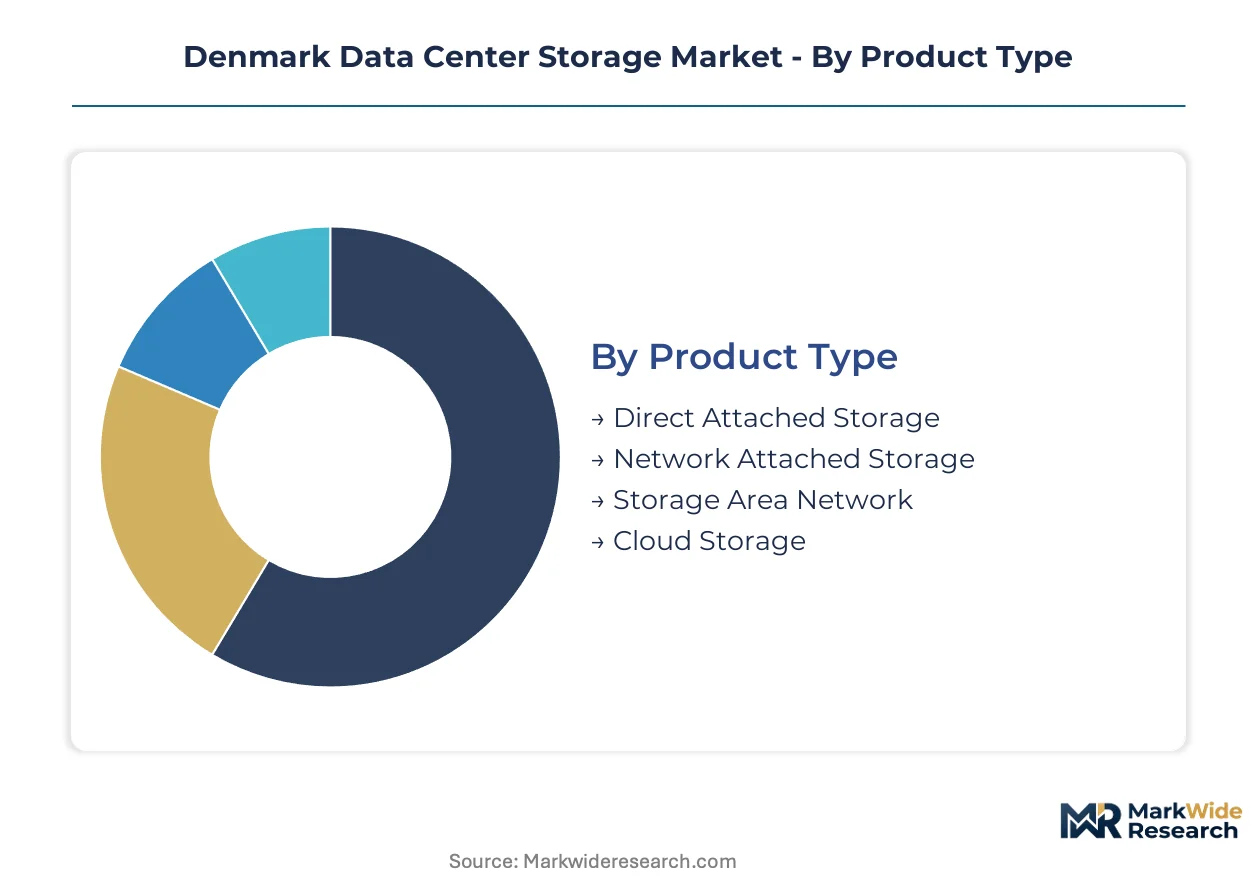
Denmark's data center storage procurement fragments across four structural dimensions, each carrying distinct compliance burdens from the Danish Energy Agency and EU AI Act. Product architecture, storage media, end-use vertical, and deployment topology determine capital allocation patterns across Copenhagen's financial district and Odense's hyperscale cluster.
Product Type:
Danish Energy Agency efficiency certifications apply differentially across product architectures, with liquid-cooled arrays facing stricter thermal verification than air-cooled alternatives.
- Direct Attached Storage:Internal storage subsystems connect directly to host servers via SAS or NVMe interfaces. Copenhagen quant funds deploy DAS for tick-data caching where microsecond latency eliminates network hop overhead. Danish Energy Agency PUE bonuses favor flash-based DAS in new facility certifications.
- Network Attached Storage:File-level storage appliances serve multiple clients over standard Ethernet protocols. Danish SMEs in Zealand and Jutland prefer NAS for shared document repositories without dedicated SAN infrastructure. GDPR data residency requirements complicate cross-border NAS replication for firms with German or Swedish operations.
- Storage Area Network:Block-level Fibre Channel fabrics deliver dedicated high-performance connectivity. Legacy SAN investments at Danske Bank and Nordea strain capital allocation during NVMe-oF transition periods.
- Cloud Storage:Object and file services delivered via hyperscale provider APIs. Microsoft's Odense region anchors enterprise cloud contracts across Jutland and Funen.
Cloud Storage sits at the top of the volume ranking, with Direct Attached Storage climbing the fastest among Copenhagen's algorithmic trading expansion.
Technology:
Cost tiers separate solid-state deployments from mechanical alternatives, with flash commanding premium positioning for latency-sensitive workloads and HDDs retaining cold-tier economics.
- Flash Storage:NAND-based solid-state arrays achieve sub-millisecond latency through NVMe protocols. Copenhagen quant funds drive eighteen-month refresh cycles for newer generations. Danish Energy Agency efficiency standards accelerate flash adoption over mechanical arrays in certified facilities.
- Hybrid Storage:Tiered architectures combine flash hot tiers with HDD cold tiers under automated data placement policies. Regional Danish hospitals balance electronic patient record accessibility against long-term imaging archive economics through hybrid configurations.
- Hard Disk Drives:Electromechanical spindles deliver up to 24 TB per drive for archival retention. Healthcare providers delay all-flash conversions for non-critical imaging workloads.
- Optical Storage:Write-once media for immutable compliance archives. EU AI Act training data provenance rules stimulate optical adoption for audit trail immutability.
Flash Storage dominates the premium tier by margin contribution, with Hybrid Storage expanding most quickly among healthcare providers managing tiered retention economics.
End User:
Application intensity varies sharply across verticals, with financial services demanding microsecond precision while healthcare prioritizes cost-optimized tiering.
- IT Services:Managed service providers and systems integrators provision multi-tenant storage infrastructure. Copenhagen-based MSPs absorb spillover demand from Microsoft's Odense cloud region.
- Government:National and municipal agencies operate under strict BIS data residency mandates. Danish tax authority digitization drives archival storage procurement.
- Telecom:Mobile and fixed-line operators deploy edge storage for 5G network functions virtualization. Zealand suburban zones lack distributed nodes for IoT data processing.
- Healthcare:Hospitals and regional health authorities manage electronic patient records and medical imaging. Danish Energy Agency efficiency incentives favor flash adoption for active clinical systems.
IT Services commands the largest procurement volume, with Healthcare gaining share fastest through regional hospital digitization programs.
Deployment:
Customer type determines topology preference, with regulated financial institutions favoring on-premises control while mid-market enterprises embrace hybrid flexibility.
- On-Premises:Dedicated infrastructure within enterprise-owned or leased facilities. Copenhagen financial institutions maintain on-premises NVMe arrays for algorithmic trading latency requirements.
- Off-Premises:Third-party colocation or managed storage services. Odense hyperscale cluster providers capture off-premises demand from Jutland enterprises.
- Hybrid:Coordinated on-premises and cloud storage with unified management planes. Danish firms navigate GDPR-BIS friction through hybrid architectures keeping primary storage within national boundaries.
- Multi-Cloud:Storage services distributed across two or more hyperscale providers. Large Danish enterprises mitigate vendor concentration risk through multi-cloud object storage strategies.
Hybrid deployment leads current procurement by project count, with Multi-Cloud showing the steepest expansion trajectory among enterprise accounts above 500 employees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping Nordic data center investment patterns as operators migrate toward jurisdictions offering streamlined permitting and renewable energy access. Denmark's EU AI Act implementation timeline creates compliance-cost differentials against Swedish and Norwegian alternatives.
Sweden
Stockholm's data center corridor attracts flash storage procurement for AI training workloads through competitive electricity pricing and the Swedish Energy Agency's efficiency certification programs. The country's implementation of EU GDPR enforcement through the Swedish Authority for Privacy Protection mandates data residency controls that favor domestic storage infrastructure.
Norway
Oslo's enterprise market drives hybrid storage adoption among oil and gas sector firms managing seismic imaging archives. Norway's national digital strategy emphasizes sovereign cloud capacity, with the Norwegian Data Protection Authority enforcing cross-border replication restrictions that complicate multi-cloud architectures.
Germany
Frankfurt's financial hub concentrates NVMe array procurement for algorithmic trading latency requirements. Germany's Federal Financial Supervisory Authority (BaFin) imposes audit trail retention rules that accelerate compliance-driven storage upgrades among quantitative funds.
Netherlands
Amsterdam's hyperscale cluster anchors cloud storage demand for Benelux enterprise customers. The Dutch Data Protection Authority's strict GDPR interpretation creates friction for Danish firms seeking cross-border hybrid architectures, favoring localized primary storage deployment.
United Kingdom
London's quant fund ecosystem drives eighteen-month refresh cycles for microsecond-latency flash systems. The UK Information Commissioner's Office post-Brexit data adequacy determinations complicate storage replication from Danish operations, reinforcing on-premises retention patterns.
Denmark Data Center Storage Market Competitive Landscape
US hyperscale providers anchor the cloud storage tier; European infrastructure specialists hold colocation and managed services positions. The vendor structure concentrates around three strategic archetypes: hyperscale platform operators, legacy systems integrators with direct attached storage specialization, and flash-native array manufacturers. Competitive dynamics center on liquid cooling integration partnerships and NVMe-over-Fabric certification programs.
Within the hyperscale tier, Microsoft Azure exemplifies geographic anchoring through its Odense regional presence. Dell Technologies occupies a position among legacy systems integrators serving Copenhagen's financial district. Pure Storage represents the flash-native archetype with sub-millisecond latency positioning for algorithmic trading workloads.
| Leading Market Players |
|---|
| Microsoft Azure |
| Amazon Web Services |
| Google Cloud |
| IBM |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Pure Storage |
| GlobalConnect |
| Others |
Pricing and Supply Chain Analysis
Copenhagen quant funds' eighteen-month refresh cycles for NVMe arrays compress procurement timelines and force distributors to carry higher flash inventory buffers, elevating working capital costs that transmit into enterprise pricing through channel markups.
Pricing Analysis
Distributor margins on enterprise flash arrays typically run 12-18 percent before value-added integration services. Three-tier pricing structure across premium NVMe-oF, standard SAS flash, and economy HDD tiers reflects latency grade and Danish Energy Agency certification status. Pricing pressure stems from NAND supply concentration in South Korea and Taiwan, with Danish buyers facing extended lead times that compress negotiation leverage. Healthcare providers exhibit highest price sensitivity for cold-tier archival systems, while quant funds prioritize microsecond latency over unit cost.
Supply Chain Analysis
NAND flash supply rests on fabrication concentration in South Korea, Taiwan, and Japan, with Danish buyers dependent on long-haul logistics through Rotterdam and Hamburg ports. Critical inputs include 3D NAND wafers, NVMe controllers from US fabless designers, and specialized cooling components for liquid-cooled deployments. Single-source vulnerability in enterprise SSD controller silicon exposes procurement timelines to geopolitical disruption. Distribution runs through Copenhagen-based systems integrators serving the financial district, with direct OEM relationships dominating hyperscale procurement in Odense.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Denmark data center storage market functions as a stable compounder underpinned by EU AI Act compliance mandates that institutionalize recurring infrastructure refresh cycles across regulated enterprises.
For Market Incumbents: Deepen liquid cooling engineering partnerships with Danish mechanical contractors to capture retrofit demand from Copenhagen's legacy facilities. Secure NVMe-over-Fabric certifications ahead of Danske Bank and Nordea's SAN migration timelines. Vertical integration into flash array assembly within the EU mitigates tariff exposure from Asian NAND supply. For New Entrants and Emerging Players: Enter via Zealand edge storage whitespace for IoT and autonomous vehicle data processing partnerships with telecom operators. Target regional hospitals in Jutland and Funen with hybrid storage configurations balancing electronic patient record flash tiers against imaging archive HDD economics. Lead with Danish Energy Agency efficiency certification as a procurement gatekeeper. For Investors and Strategic Acquirers: Asymmetric upside sits with flash-native array manufacturers possessing sub-millisecond latency positioning for Copenhagen's algorithmic trading expansion. Five-to-ten year viability hinges on sustained EU AI Act enforcement and provenance-tracking storage mandates. Monitor Danish Energy Agency PUE bonus program expansion as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabric Certification | Copenhagen financial institutions require microsecond latency for tick-data analytics workloads. |
| Liquid Cooling Integration Partnership | Danish hyperscale operators in Odense pilot immersion cooling for AI training thermal loads. |
| EU AI Act Provenance Architecture | Immutable audit trail storage captures Article 10 training data lineage requirements. |
| Zealand Edge Deployment | Suburban Copenhagen lacks distributed nodes for IoT and autonomous vehicle processing. |
| Healthcare Hybrid Convergence | Regional hospitals balance electronic patient record accessibility against imaging archive economics. |
Research Methodology
Bottom-up healthcare and financial services modeling reconciled against top-down hyperscale capex tracking forms the analytical core. Primary interviews with data center facility managers, enterprise storage procurement officers, systems integrators, and Danish Energy Agency certification auditors combined with secondary validation from SEC filings, hyperscaler infrastructure disclosures, and EU regulatory documentation. Triangulation across stakeholder inputs and trade data ensures segment-level precision.
Input-output matrices map flash array shipments against end-use intensity across Copenhagen's financial district and Odense's hyperscale cluster. Segmentation dimensions include product architecture, storage media technology, end-use vertical, and deployment topology. CAGRs derive from fitted growth curves calibrated to infrastructure investment patterns and regulatory compliance timelines. Forecast inputs incorporate Danish national digital strategy spending commitments and EU AI Act implementation schedules.
Inputs from Danish Energy Agency certification records and hyperscaler facility announcements were available through the study window; gaps in private quant fund procurement data introduce uncertainty bands around financial services segment estimates. Forecasts reflect documented assumptions regarding NAND supply stability and regulatory enforcement continuity. A small set of triggers—geopolitical disruption to Asian flash fabrication, EU AI Act enforcement intensity, and Danish renewable energy grid expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Thailand Data Center Storage Market