
 Global All-Flash Array Market | 2026-2036
Global All-Flash Array Market Size, Share, and Industry Trends Forecast 2026-2036
Global All-Flash Array Market Foresight
Premium all-flash array performance is decoupling from commodity storage economics as NVMe-oF architectures and custom ASIC controllers widen the latency gap between tier-one and tier-three deployments. Dell Technologies Inc. leverages its integrated supply chain to sustain margin pressure across enterprise and hyperscale segments. Pure Storage Inc. anchors its position through software-defined subscription models that reduce customer switching costs. Huawei Technologies Co. Ltd. dominates procurement cycles across Asia-Pacific state-backed cloud builds despite Western market access constraints.
An all-flash array is a solid-state storage system built entirely from NAND flash memory, delivering sub-millisecond latency through NVMe or SAS interconnects for mission-critical databases, virtualization, and real-time analytics. Enterprise arrays and hyperscale arrays command the deepest margin pools as cloud service providers and financial institutions prioritize consistent low-latency throughput over capital efficiency. NVMe technology leads growth trajectories as Fibre Channel attachments plateau in legacy data centers. Big data analytics and online transaction processing represent the fastest-expanding application segments as AI training pipelines and real-time fraud detection strain disk-based alternatives.
The EU GDPR and EU AI Act impose strict data residency and processing transparency rules that shape procurement specifications for European financial institutions and government agencies. The US SEC and HIPAA frameworks in the United States mandate audit-ready retention architectures that favor encrypted, immutable all-flash configurations over hybrid alternatives. China's GB standards and dual carbon goals from MEE restrict data center power density, pushing operators toward higher-efficiency flash tiers. Stakeholders must weigh regulatory fragmentation against workload consolidation trends when selecting between centralized hyperscale deployments and geographically distributed entry-level arrays.
Market Dynamics
NVMe-oF protocol maturation is compressing storage network latency to sub-100 microseconds, forcing incumbent Fibre Channel architectures into legacy maintenance mode while redistributing margin pools toward software-defined controllers and custom ASIC designs.
Growth Catalysts
- EU AI Act data processing mandates:European financial institutions must deploy localized high-performance infrastructure for algorithmic transparency, accelerating enterprise-grade array procurement cycles in Germany and France.
- Real-time fraud detection pipelines:Banking and insurance sectors require consistent sub-millisecond throughput for transaction scoring, displacing disk-based alternatives in mission-critical workloads.
- Japan's METI digital infrastructure push:State-backed cloud modernization programs concentrate demand for latency-sensitive storage in Tokyo and Osaka financial districts.
Market Restraints
- NAND flash wafer supply concentration:Foundry capacity constraints in Taiwan and South Korea create input cost volatility that compresses array manufacturer margins during demand spikes.
- GDPR cross-border data transfer friction:European data residency requirements fragment procurement specifications, preventing standardized global deployments for multinational enterprises.
- Hybrid cloud storage substitution:Object storage tiering with intelligent caching threatens entry-level all-flash configurations in non-latency-sensitive analytics workloads.
Strategic Opportunities
- India's RBI digital payment infrastructure:Unified Payments Interface expansion and central bank digital currency pilots create underpenetrated demand for real-time transaction processing arrays in Mumbai and Bangalore.
- Computational storage convergence:Integration of processing elements within flash controllers enables edge AI inference without data movement, opening manufacturing and autonomous vehicle applications.
- US IRA clean energy tax credits:Data center efficiency mandates accelerate replacement of power-hungry disk farms with flash tiers in Virginia and Texas hyperscale clusters.
Industry Challenges
- Firmware engineering talent scarcity:NVMe controller optimization and custom ASIC development require specialized skill sets concentrated at a handful of semiconductor firms, constraining vendor R&D velocity.
- Legacy SAN integration complexity:Enterprise migration from Fibre Channel to NVMe-oF demands parallel infrastructure operation during transition periods, extending deployment timelines and requiring dual-protocol expertise.
- SEC audit-ready retention certification:Financial services buyers mandate immutable snapshot architectures with cryptographic verification, adding compliance engineering overhead to product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global All-Flash Array Market |
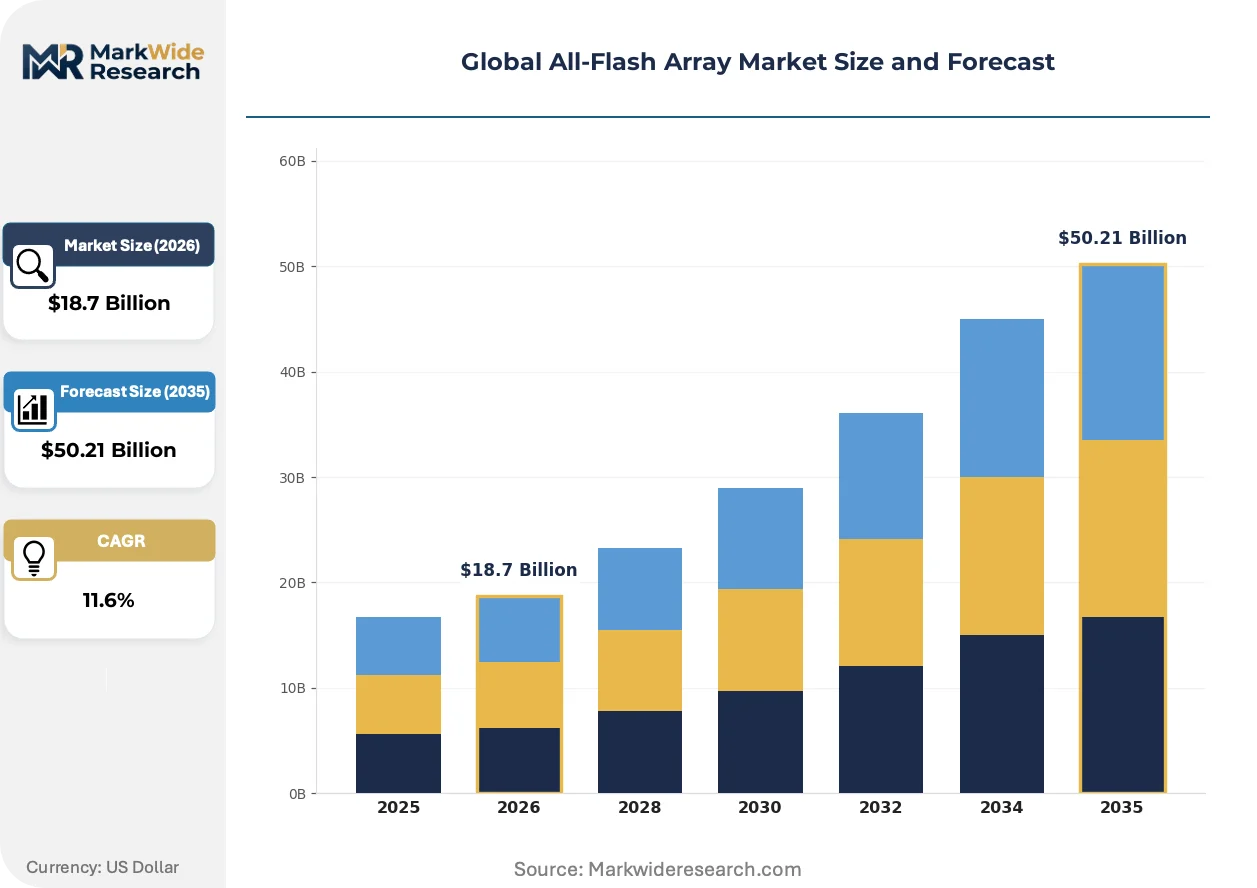
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry-Level Arrays, Mid-Range Arrays, Enterprise Arrays, Hyperscale Arrays Technology: NVMe, SAS, SATA, PCIe, Fibre Channel Application: Data Warehousing, Virtual Desktop Infrastructure, Online Transaction Processing, Big Data Analytics, Backup & Recovery End User: Telecommunications Providers, Financial Institutions, Government Agencies, Cloud Service Providers, Media & Entertainment |
| Companies Covered | Dell Technologies Inc., Pure Storage Inc., NetApp Inc., Hewlett Packard Enterprise Company, IBM Corporation, Huawei Technologies Co. Ltd., Hitachi Vantara LLC, Fujitsu Ltd., INSPUR Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global All-Flash Array Market Shifts & Advancements
Storage-class memory hierarchies and computational flash architectures are collapsing the boundary between memory and persistent storage, enabling new workload consolidation patterns that reshape data center footprint economics.
Computational storage drives with embedded ARM processing cores is expanding into AI training pipeline preprocessing stages. Hyperscale operators in the United States deploy these devices to filter and transform petabyte-scale datasets before transfer to GPU clusters. This compression of data movement is expanding into real-time analytics architectures that previously required separate compute tiers.
The EU AI Act's algorithmic accountability requirements impose processing transparency obligations on automated decision systems. Financial institutions in Germany and France must maintain immutable audit trails for model training data, favoring encrypted all-flash configurations with hardware-rooted immutability over hybrid alternatives. Array vendors are responding with integrated compliance modules that automate retention policy enforcement.
Consumption-based financing models are displacing traditional capital expenditure procurement for enterprise storage. Large banks in Japan and the United States now prefer subscription contracts that bundle hardware refresh cycles with operational support, transferring obsolescence risk to vendors. This behavioral shift concentrates purchasing power among buyers with balance-sheet capacity for multi-year commitments, favoring established suppliers with captive financing arms.
Global All-Flash Array Market Segmentation
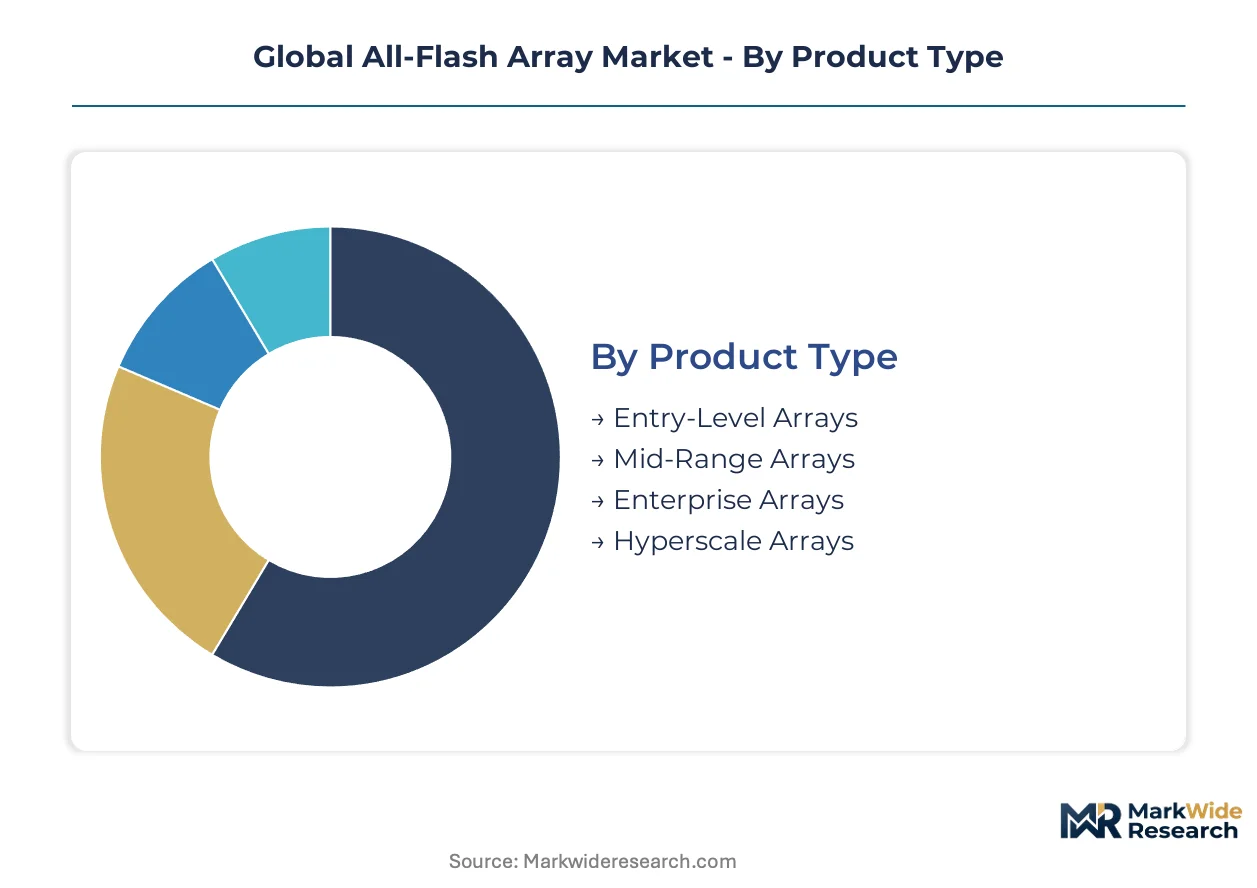
All-flash array procurement patterns diverge sharply across workload latency requirements, infrastructure scale, and regulatory exposure. Buyers self-select into distinct tiers based on whether they prioritize capital efficiency, consistent sub-millisecond performance, or compliance-certified immutability.
Product Type:
Cost tier separates buyers who tolerate higher latency for budget containment from those who pay premium for guaranteed throughput.
- Enterprise Arrays:Purpose-built systems with custom ASIC controllers and NVMe-oF backplanes delivering sub-100 microsecond consistency for mission-critical databases. Financial institutions in Frankfurt and New York deploy these for real-time fraud detection pipelines where latency spikes trigger regulatory scrutiny.
- Hyperscale Arrays:Rack-scale designs optimized for cloud-native software-defined storage with disaggregated compute-storage topologies. Cloud service providers in Virginia and Tokyo financial districts concentrate procurement here for AI training infrastructure and multi-tenant virtualization platforms.
- Mid-Range Arrays:Balanced configurations serving regional healthcare networks and mid-market manufacturers seeking Fibre Channel migration paths without full NVMe-oF investment.
- Entry-Level Arrays:Compact appliances targeting remote office deployments and non-latency-sensitive virtual desktop infrastructure in distributed enterprises.
Enterprise arrays lead volumes today; hyperscale arrays are climbing the fastest as cloud service providers expand sovereign cloud footprints.
Technology:
Volume concentration follows interconnect protocol maturity and controller optimization depth.
- NVMe:Native PCIe-based protocol eliminating SCSI translation overhead to deliver 64K IOPS per drive with sub-10 microsecond controller latency. Germany's automotive sector and Japan's METI-backed cloud modernization programs drive concentrated demand for NVMe-oF fabrics in manufacturing and financial districts.
- Fibre Channel:Legacy 32GFC infrastructure maintained by risk-averse banking IT departments in Switzerland and Singapore requiring backward compatibility during multi-year migration windows.
- SAS:12Gbps and 24Gbps interfaces persisting in cost-optimized tier-two data centers and government agencies with extended procurement cycles.
- PCIe:Direct-attached configurations for high-performance computing clusters and AI training nodes requiring maximum bandwidth density.
- SATA:Limited residual deployment in archival flash tiers and cold storage acceleration where cost per gigabyte dominates latency requirements.
NVMe dominates new procurement; Fibre Channel retains installed base maintenance revenue.
Application:
Customer type determines whether buyers prioritize query concurrency, boot storm resilience, or immutable retention.
- Online Transaction Processing:Workloads requiring atomic consistency with sub-millisecond commit latency for payment networks and securities exchanges. India's UPI expansion and Brazil's instant payment infrastructure create concentrated demand in Mumbai and São Paulo.
- Big Data Analytics:Throughput-intensive pipelines for real-time model training and behavioral scoring where NVMe-oF parallelism outperforms disk-based alternatives. Cloud service providers in the United States deploy petabyte-scale configurations for recommendation engine preprocessing.
- Virtual Desktop Infrastructure:Boot storm and login surge workloads driving consistent low-latency read patterns across thousands of concurrent sessions in healthcare and education sectors.
- Data Warehousing:Columnar query acceleration for business intelligence platforms where scan-heavy analytics benefit from flash random read performance.
- Backup & Recovery:Immutable snapshot targets meeting SEC and HIPAA retention mandates with hardware-rooted encryption and WORM certification.
Online transaction processing anchors current revenue; big data analytics shows steepest expansion trajectory.
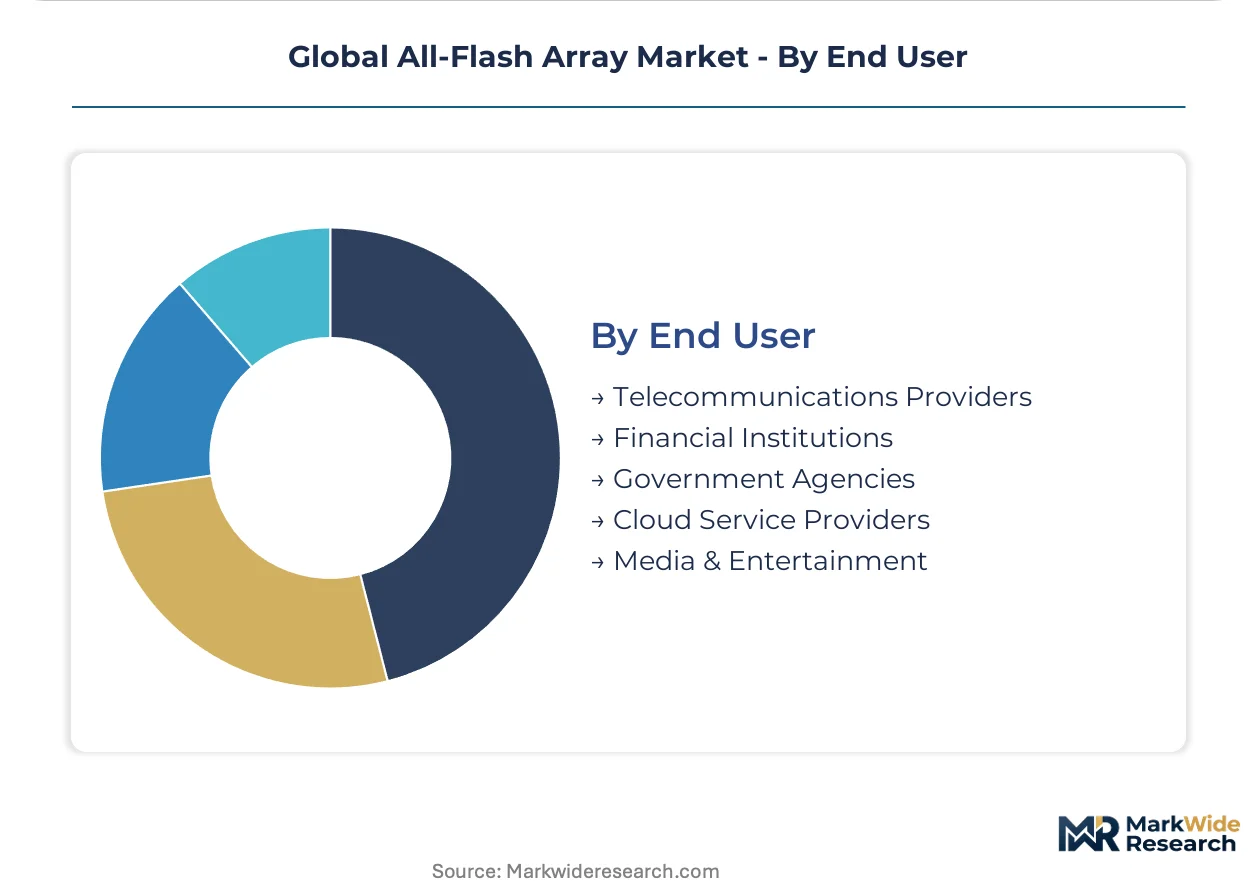
End User:
Regulatory exposure and workload criticality shape procurement specifications more than absolute scale.
- Financial Institutions:Banks, insurers, and securities exchanges subject to SEC, GDPR, and EU AI Act algorithmic accountability mandates. German and French institutions must maintain localized, auditable infrastructure for automated decision systems.
- Cloud Service Providers:Hyperscale operators and regional sovereign cloud builders competing on latency SLAs for enterprise multi-tenant workloads in Tokyo, Frankfurt, and Singapore.
- Government Agencies:Defense, intelligence, and civilian departments requiring FIPS 140-2 encryption and air-gapped deployments for classified data residency.
- Telecommunications Providers:5G core network functions and edge computing infrastructure demanding consistent performance for subscriber data management.
- Media & Entertainment:Post-production studios and streaming platforms accelerating 4K/8K rendering pipelines and content delivery caching layers.
Financial institutions generate largest deal flow; cloud service providers are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized firmware engineers and ASIC architects cluster in Taiwan, South Korea, and California, anchoring the design capabilities that differentiate high-performance arrays from commodity alternatives.
United States
Virginia hyperscale clusters and Texas data centers drive concentrated procurement for AI training infrastructure. The SEC mandates immutable retention architectures for financial audit trails. Cloud service providers in Northern Virginia deploy petabyte-scale NVMe-oF configurations for multi-tenant latency SLAs.
Germany
Frankfurt financial institutions require localized high-performance storage for algorithmic transparency under EU AI Act obligations. The GDPR imposes strict data residency rules on cross-border transfers. Automotive manufacturers in Stuttgart and Munich adopt NVMe fabrics for real-time manufacturing analytics.
Japan
Tokyo and Osaka financial districts concentrate demand for latency-sensitive transaction processing arrays. METI's digital infrastructure modernization programs accelerate sovereign cloud procurement. Regional banks deploy enterprise-grade configurations for instant payment settlement systems.
India
Mumbai and Bangalore emerge as deployment hubs for real-time payment infrastructure under RBI's UPI expansion. The central bank's digital currency pilots create underpenetrated demand for sub-millisecond consistency. Fintech operators in Hyderabad build edge data centers for fraud detection pipelines.
China
State-backed cloud builds across Beijing and Shanghai concentrate procurement for domestic hyperscale operators. MEE dual carbon goals restrict data center power density, pushing efficiency-driven flash adoption. GB standards mandate localized encryption for government and financial workloads.
Global All-Flash Array Market Competitive Landscape
Capital-heavy producers with captive semiconductor fabrication compete with asset-light designers relying on foundry partnerships for controller silicon. The market structures around three tiers: integrated systems vendors with supply chain depth, software-defined specialists with subscription financing arms, and regional champions serving sovereign procurement cycles. Strategic moves concentrate on custom ASIC development for latency differentiation and consumption-based pricing models that transfer obsolescence risk.
Within the integrated systems tier, Dell Technologies Inc. and Hewlett Packard Enterprise Company occupy positions defined by supply chain scale and captive financing capacity. Pure Storage Inc. exemplifies the software-defined archetype through subscription-centric commercial structures. Huawei Technologies Co. Ltd. anchors regional procurement in Asia-Pacific state-backed deployments despite Western market access constraints.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Pure Storage Inc. |
| NetApp Inc. |
| Hewlett Packard Enterprise Company |
| IBM Corporation |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| Fujitsu Ltd. |
| INSPUR Co. Ltd. |
| Others |
Supply & Pricing Matrix
NAND flash wafer spot prices in Taiwan and South Korea cascade through controller foundry costs into three distinct procurement tiers, compressing margins for mid-range array assemblers while enterprise-grade vendors with captive ASIC design retain pricing power.
Pricing Analysis
Bundled subscription contracts now dominate enterprise procurement, separating buyers who self-manage infrastructure from those transferring refresh risk to vendors. Pricing stratifies across premium NVMe-oF configurations, standard Fibre Channel migration tiers, and economy SAS-based appliances based on latency SLAs and compliance certification levels. Cost compression in the entry-level tier is intensifying because object storage tiering with intelligent caching substitutes for flash in non-mission-critical analytics. Cloud service providers exhibit the lowest price sensitivity due to multi-year consumption commitments, while regional healthcare networks face the highest budget constraints.
Supply Chain Analysis
China's GB standards and India's phased manufacturing program are reshaping component sourcing, pushing array vendors toward localized final assembly despite NAND wafer concentration in Taiwan and South Korea. Controller ASICs and flash memory draw from foundry capacity in Taiwan, South Korea, and California, while power supply units and chassis fabrication rest on metalworking clusters in China and Mexico. Single-source vulnerability around specialized NVMe controller engineering talent constrains vendor R&D velocity. Distribution runs through direct enterprise sales forces for large financial institutions and cloud service providers, with systems integrators handling mid-market healthcare and education deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic arbitrage between Germany's EU AI Act compliance premiums and India's cost-optimized real-time payment infrastructure builds, with regulatory stringency in Frankfurt justifying 40-60% higher effective pricing than Mumbai deployments.
For Market Incumbents: Lock in subscription renewal rates by embedding compliance automation modules that automate SEC and EU AI Act retention policy enforcement. Deepen backward integration into custom ASIC controller design to differentiate latency performance against commodity NVMe alternatives. Prioritize captive financing arms to match Pure Storage's subscription-centric commercial structures and reduce customer switching costs.
For New Entrants and Emerging Players: Launch via sovereign cloud partnerships in India and Japan where state-backed procurement cycles favor regional system integrators over global incumbents. Target India's RBI-mandated UPI expansion and central bank digital currency pilots as the most penetrable demand cluster. Lead with consumption-based pricing that transfers hardware obsolescence risk to vendors, matching established subscription models without requiring balance-sheet capacity for captive financing.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined specialists possessing subscription financing arms and vertical integration into controller silicon. Long-term viability hinges on ASIC design capabilities and compliance engineering depth rather than commodity assembly scale. Watch for inflection when India's sovereign cloud procurement shifts from pilot to volume deployment, signaling regional champion emergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Controller Development | Captive silicon design locks in sub-100 microsecond latency differentiation against commodity NVMe competitors. |
| Compliance Automation Module Integration | Embedded EU AI Act and SEC retention enforcement reduces customer switching costs for financial institutions. |
| Sovereign Cloud Partnership Formation | State-backed procurement in India and Japan favors regional integrators with localized support infrastructure. |
| Consumption-Based Financing Expansion | Subscription contracts transfer obsolescence risk and concentrate purchasing power among balance-sheet-capable vendors. |
| Computational Storage Architecture Launch | ARM-embedded flash controllers enable edge AI inference without data movement in manufacturing applications. |
Research Methodology
Multiple input streams — structured interviews with data center infrastructure directors, CTOs at financial institutions, and procurement leads at cloud service providers, plus validation against hyperscaler capex disclosures, SEC 10-K filings, and regulatory submission databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured deployment timelines, latency requirement specifications, and budget allocation patterns across enterprise, hyperscale, and mid-market buyer archetypes. Secondary sources included customs records for NAND flash import volumes, foundry utilization reports from Taiwan and South Korea, and sovereign cloud procurement announcements from India's MeitY and Japan's METI.
Data-stream reconciliation anchored volume projections to installed base refresh cycles, workload consolidation patterns, and regional regulatory enforcement timelines across the analysis window. Segmentation modeling incorporated product type tiers, interconnect protocol adoption curves, application workload characteristics, and end-user regulatory exposure clusters. CAGRs were derived from elasticity-adjusted demand functions and supply-side capacity constraints. Forecast inputs included NAND wafer pricing trajectories, NVMe-oF protocol maturation curves, and compliance deadline schedules for EU AI Act and SEC audit-ready retention mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry capacity constraints in Taiwan or abrupt shifts in cross-border data transfer regulations. Projections reflect assumptions regarding protocol migration timelines, sovereign cloud procurement acceleration, and flash memory cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Denmark Data Center Storage Market