
 Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market | 2026-2036
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market Insights
Single-source reliance on captive reagent supplies is consolidating toward multi-vendor QC ecosystems as labs seek interoperability across sequencing platforms. Thermo Fisher Scientific leverages its instrument-reagent bundling to sustain installed-base loyalty in high-throughput facilities. QIAGEN anchors European demand through automated sample-to-insight workflows with embedded QC checkpoints. Bio-Rad Laboratories competes on modular assay flexibility that accommodates Pacific Biosciences and Oxford Nanopore chemistries.
Next-Generation Sequencing workflow quality control test kits and instruments encompass nucleic acid quantification systems, fragment analyzers, and library validation assays that verify insert size distribution, concentration accuracy, and contaminant absence prior to sequencing runs. These tools prevent costly run failures in instruments generating terabase-scale outputs where reagent costs per flow cell exceed operational labor. Quality Control Assays capture recurring revenue from high-run-volume core facilities, while Sequencing Instruments concentrate capital expenditure among genome centers with amortization schedules tied to grant funding cycles. Library Preparation Kits dominate unit volume as distributed lab networks standardize pre-analytical protocols across multi-site studies.
FDA oversight of laboratory-developed tests and EMA In Vitro Diagnostic Regulation compliance deadlines are elevating traceability requirements for QC kit lot records and calibration certificates. ISO 13485 quality management systems and CLSI analytical performance standards now condition market access for instrument vendors serving regulated clinical environments. Stakeholders must weigh the capital efficiency of platform-agnostic QC instruments against the operational simplicity of locked vendor ecosystems as sequencing menus diversify beyond oncology into rare disease and pharmacogenomic applications.
Market Dynamics
Precision medicine protocols are fragmenting sequencing workflows across multi-vendor instrument fleets, forcing quality control infrastructure to bridge incompatible chemistries rather than serve single-platform ecosystems. This interoperability imperative is compressing margins for bundled reagent-instrument suppliers while elevating modular QC assay vendors.
Growth Catalysts
- Companion diagnostic validation mandates:FDA guidance on analytical performance for oncology companion diagnostics compels clinical laboratories to implement traceable QC lot records and calibration certificates prior to patient sample processing.
- Terabase-scale instrument deployment:High-throughput sequencing platforms in genome centers generate run-failure costs exceeding reagent expenditures alone, driving preventive QC instrumentation investment.
- Rare disease screening expansion:Neonatal and pediatric genetic screening programs in academic medical centers multiply validated NGS assay menus, each requiring platform-agnostic QC verification workflows.
Market Restraints
- Capital intensity of multi-platform QC infrastructure:Fragment analyzers, nucleic acid quantification systems, and library validation instruments require parallel capital commitments that strain core facility grant-funded amortization schedules.
- Reagent supply concentration:Captive reagent bundling by dominant instrument vendors creates switching costs that lock mid-throughput laboratories into suboptimal QC workflows.
- ISO 13485 certification timelines:Clinical diagnostic instrument vendors face twelve-to-eighteen-month quality management system implementation periods that delay regulated market entry.
Strategic Opportunities
- Pharmacogenomic testing networks:Decentralized pharmacy and primary care sites implementing preemptive genotyping panels require portable, simplified QC assays with minimal technical specialist oversight.
- Long-read chemistry integration:Pacific Biosciences and Oxford Nanopore sequencing platforms lack mature QC ecosystems, creating white space for fragment analysis and library validation assay developers.
- EMA IVDR compliance services:European clinical laboratories facing 2028 regulatory deadlines seek outsourced QC kit lot traceability and performance verification documentation.
Industry Challenges
- Bioinformatics specialist scarcity:QC data interpretation across heterogeneous sequencing platforms demands computational biology expertise that outpaces training pipeline output in university programs.
- Legacy LIMS integration friction:Automated sample-to-insight workflows require middleware development to connect modern QC instrumentation with decade-old laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market |
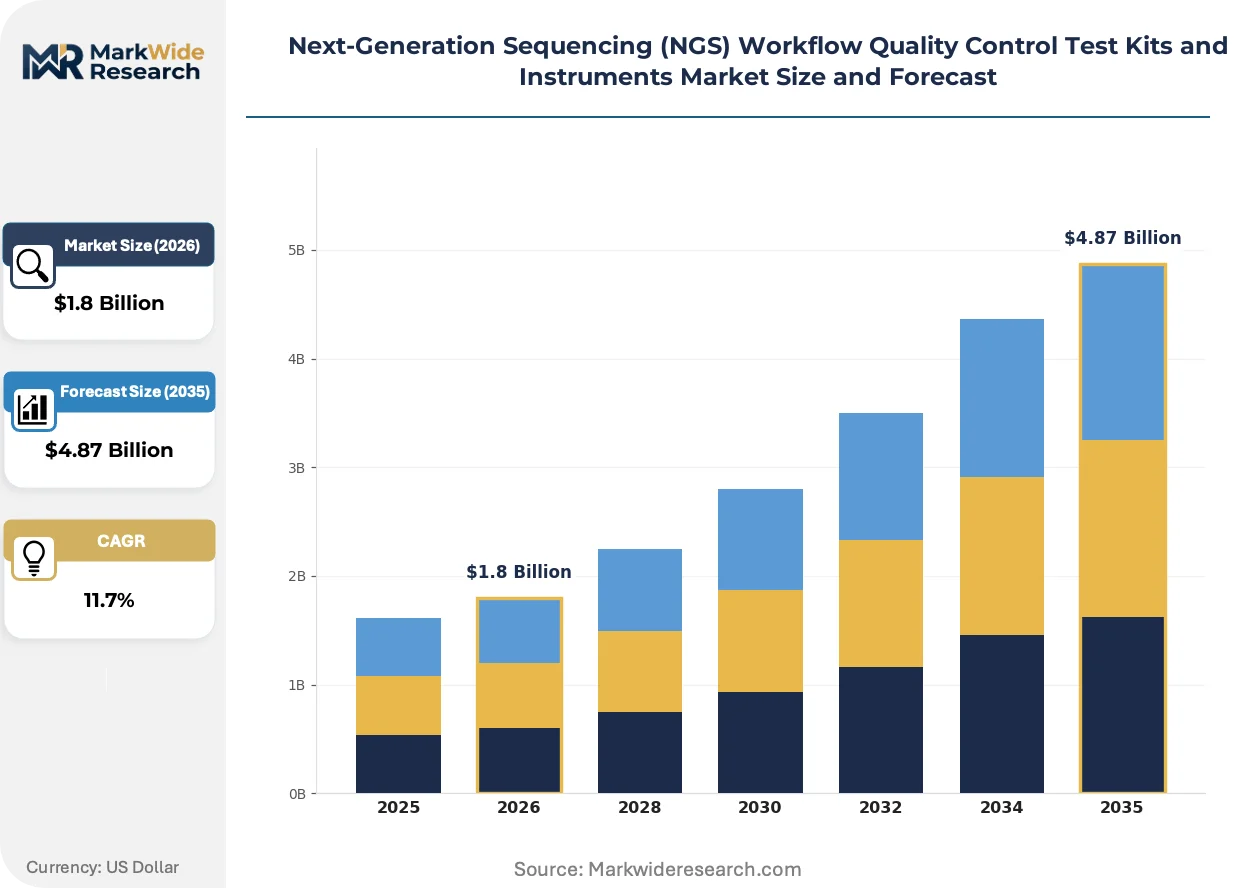
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Library Preparation Kits, Sequencing Instruments, Quality Control Assays, Bioinformatics Software, Sample Extraction Kits Application: Genomic Research, Transcriptome Analysis, Epigenetic Profiling, Personalized Medicine, Plant Genomics End User: Academic Labs, Biotechnology Firms, Pharmaceutical Developers, Contract Research Organizations, Diagnostic Facilities Technology: Illumina Sequencing, Ion Torrent, Pacific Biosciences, Oxford Nanopore, BGI Sequencing |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Roche, QIAGEN, Bio-Rad Laboratories, PerkinElmer, Revvity, Tecan Group, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market Trends and Innovations
Artificial intelligence is compressing QC data interpretation timelines while cloud-native instrument connectivity is displacing on-premise data silos. These shifts are restructuring how laboratories validate sequencing runs and manage compliance documentation.
Capillary electrophoresis fragment analysis is unifying insert size distribution verification across Illumina, Thermo Fisher, and emerging long-read sequencing chemistries. Mid-throughput core facilities in Boston and San Francisco biotech clusters are adopting these platform-agnostic systems to reduce redundant instrumentation footprints. This unification is compressing capital allocation toward single-instrument QC verification rather than chemistry-specific validation workflows.
EMA In Vitro Diagnostic Regulation lot traceability requirements are mandating digital calibration certificate repositories with blockchain-anchored audit trails. European clinical diagnostic laboratories must implement these systems by 2028 or forfeit regulated testing authorization. High-complexity molecular pathology departments are responding by consolidating QC kit procurement through distributors offering compliance-documentation bundling.
Core facility directors are unbundling after-sales service contracts from instrument purchase agreements, negotiating separate maintenance terms with third-party field service organizations. This disintermediation is most visible in United States academic medical centers where grant-funded capital purchases face stricter operational expenditure scrutiny. Service contract fragmentation is pressuring original equipment manufacturers to disclose component-level pricing or lose captive maintenance revenue.
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market Segmentation
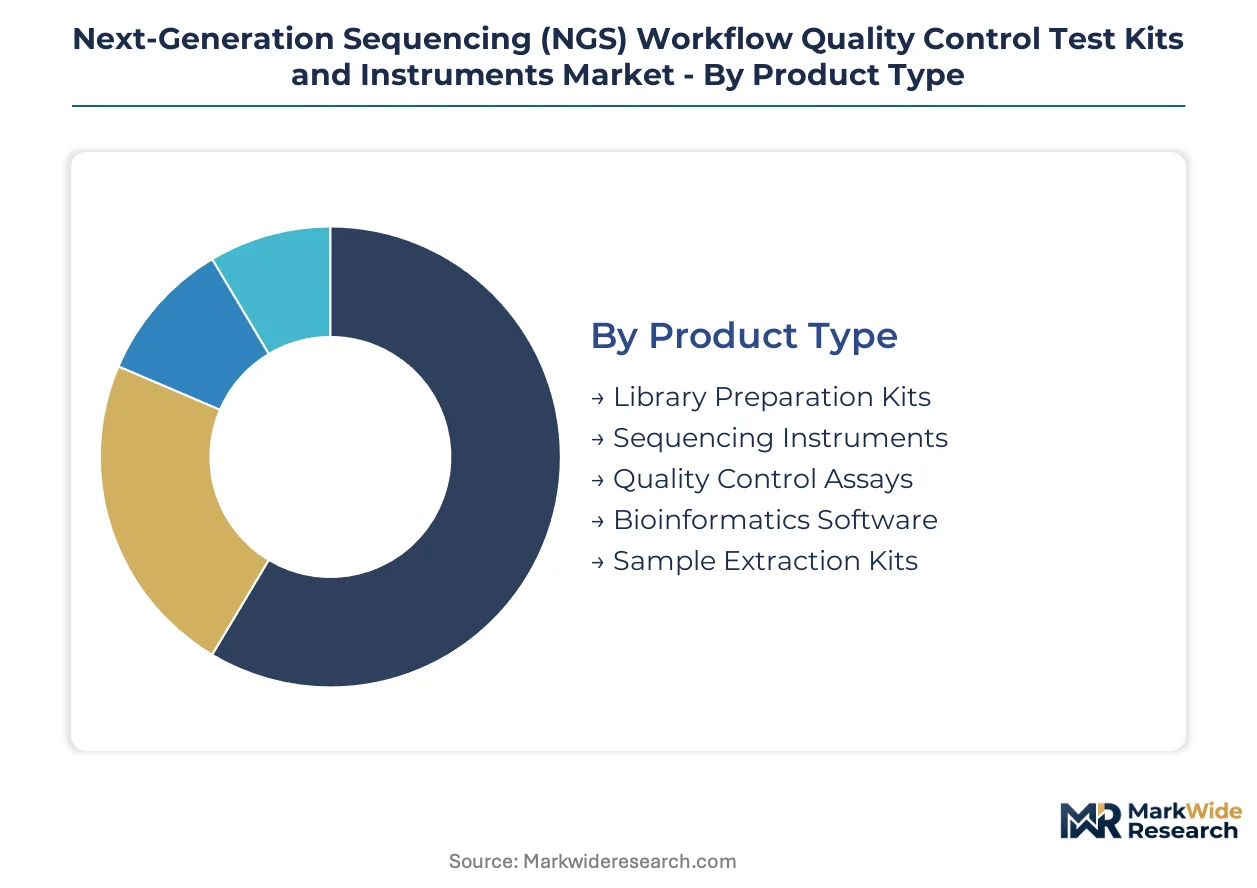
NGS QC workflow segmentation reflects divergent capital allocation strategies across research and clinical environments. Laboratories prioritize consumables for recurring revenue stability, while genome centers concentrate instrument investments around grant cycles. Technology fragmentation across sequencing chemistries forces QC infrastructure decisions that balance interoperability against vendor lock-in.
Product Type:
Standardization pressures dominate consumable categories, while instrument purchasing tilts toward customization based on throughput requirements and chemistry compatibility.
- Library Preparation Kits:Enzymatic and bead-based chemistries standardize input DNA/RNA processing across multi-site studies. Academic medical centers in Boston and San Francisco biotech clusters drive unit volume through distributed protocol harmonization. Kit standardization reduces inter-laboratory variability in large-scale genomics consortia.
- Quality Control Assays:Fragment analysis and nucleic acid quantification reagents verify insert size distribution and concentration accuracy prior to sequencing runs. High-throughput core facilities generate recurring revenue concentration as run volumes scale. FDA companion diagnostic validation mandates tighten analytical performance documentation requirements for clinical deployments.
- Sequencing Instruments:Capital equipment spans nucleic acid quantification systems, fragment analyzers, and library validation platforms.
- Bioinformatics Software:Cloud-native and on-premise solutions manage QC data interpretation and compliance documentation.
- Sample Extraction Kits:DNA/RNA isolation chemistries precede QC workflows in automated sample-to-insight pipelines.
Leading the category by volume: Library Preparation Kits. Expanding most quickly: Quality Control Assays.
Application:
Research-driven applications command larger instrument footprints, while clinical translation accelerates consumable throughput with stricter regulatory documentation.
- Genomic Research:Whole-genome and exome sequencing projects in academic environments demand comprehensive QC validation across diverse sample types. NIH-funded genome centers amortize multi-platform QC instrumentation across heterogeneous research portfolios. Terabase-scale outputs amplify the cost of run failures, elevating preventive QC investment priority.
- Personalized Medicine:Companion diagnostic and pharmacogenomic applications require traceable QC lot records and calibration certificates for regulatory submission. EMA IVDR compliance deadlines in European clinical laboratories mandate digital audit trail implementation. Oncology biomarker validation workflows concentrate demand in United States academic medical centers.
- Transcriptome Analysis:RNA-seq applications verify RNA integrity and library complexity prior to sequencing.
- Epigenetic Profiling:Bisulfite sequencing and ChIP-seq workflows demand specialized QC metrics for modification detection sensitivity.
- Plant Genomics:Agricultural biotechnology applications standardize QC protocols across polyploid and high-repeat-content genomes.
Dominating current revenue: Genomic Research. Steepest expansion trajectory: Personalized Medicine.
End User:
Grant-dependent academic institutions prioritize capital efficiency, while commercial entities absorb higher operational expenditures for regulatory compliance speed.
- Academic Labs:University core facilities balance multi-platform QC instrumentation against constrained amortization schedules tied to federal funding cycles. Shared equipment models spread capital costs across departmental user bases. Service contract unbundling from instrument purchases accelerates as operational expenditure scrutiny intensifies.
- Biotechnology Firms:Venture-funded companies in Boston and San Francisco clusters demand platform-agnostic QC workflows to preserve chemistry flexibility. Rapid assay menu expansion into rare disease and pharmacogenomic applications drives modular QC infrastructure investment. Speed-to-clinical-validation priorities override vendor ecosystem loyalty.
- Pharmaceutical Developers:Internal sequencing capabilities require GMP-aligned QC documentation for regulatory submissions.
- Contract Research Organizations:Multi-client service models standardize QC protocols across diverse sponsor requirements.
- Diagnostic Facilities:Clinical laboratories implement ISO 13485 quality management systems for regulated testing authorization.
Highest instrument placement concentration: Academic Labs. Gaining share fastest: Biotechnology Firms.
Technology:
Short-read dominance persists in clinical validation, while long-read chemistry maturation creates white space for specialized QC assay development.
- Illumina Sequencing:Short-read chemistry maintains installed-base leadership in clinical diagnostic and high-throughput research applications. Mature QC ecosystems offer standardized fragment analysis and library validation workflows. Captive reagent bundling sustains vendor loyalty despite interoperability pressures.
- Oxford Nanopore:Long-read and real-time sequencing platforms lack established QC infrastructure, creating assay development opportunities. Portable device formats demand simplified, technician-minimal QC protocols for decentralized deployment. Pharmacogenomic testing networks in primary care settings require field-deployable validation workflows.
- Ion Torrent:Semiconductor sequencing maintains niche presence in targeted panel applications.
- Pacific Biosciences:HiFi long-read chemistry drives structural variant and methylation detection applications.
- BGI Sequencing:Chinese domestic platforms expand through cost-competitive high-throughput offerings.
Highest QC assay standardization: Illumina Sequencing. Most rapid infrastructure buildout: Oxford Nanopore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for NGS workflow quality control infrastructure concentrates in the United States, where academic medical centers and biotech clusters absorb the majority of high-throughput instrument placements. Precision medicine protocol expansion and companion diagnostic validation mandates drive regional purchasing patterns. Regulatory divergence between FDA and EMA frameworks shapes distinct compliance investment timelines across major markets.
United States
Boston and San Francisco biotech clusters drive instrument placement density through genome center grant funding cycles. FDA guidance on laboratory-developed tests tightens analytical performance documentation requirements for clinical diagnostic laboratories. Academic medical centers in these coastal metros unbundle service contracts from instrument purchases to reduce operational expenditure burdens.
Germany
Automated sample-to-insight workflows with embedded QC checkpoints anchor European demand through centralized laboratory networks. EMA In Vitro Diagnostic Regulation compliance deadlines mandate digital calibration certificate repositories with blockchain-anchored audit trails. Bavarian and Baden-Württemberg molecular pathology departments consolidate QC kit procurement through compliance-documentation bundling.
China
Domestic sequencing platform expansion through BGI and emerging manufacturers creates parallel QC infrastructure requirements. NMPA oversight of in vitro diagnostics elevates traceability standards for clinical laboratory authorization. Yangtze River Delta research institutes deploy multi-platform QC instrumentation to support heterogeneous sequencing chemistries.
United Kingdom
Genomic England and NHS diagnostic networks standardize QC protocols across decentralized testing sites. MHRA alignment with EMA IVDR timelines pressures clinical laboratories to implement ISO 13485 quality management systems. London and Cambridge life science clusters concentrate fragment analyzer and nucleic acid quantification system deployments.
Japan
Pharmacogenomic testing network expansion into community healthcare settings demands portable QC assay formats. PMDA regulatory frameworks for companion diagnostics align analytical performance requirements with FDA and EMA precedents. Tokyo and Osaka academic medical centers amortize multi-platform QC instrumentation across rare disease and oncology screening programs.
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bridge incompatible sequencing chemistries through interoperable QC infrastructure. The vendor base organizes around three tiers: integrated life science conglomerates with captive instrument-reagent bundling, modular assay specialists serving multi-platform environments, and emerging entrants targeting long-read chemistry white space. Consolidation pressures intensify as mid-throughput laboratories seek to reduce switching costs from dominant supplier ecosystems. Technology licensing and geographic expansion represent the primary competitive vectors for market access acceleration.
Among integrated life science conglomerates, Thermo Fisher Scientific and QIAGEN occupy positions exemplifying divergent regional anchoring strategies. Thermo Fisher leverages instrument-reagent bundling to sustain installed-base loyalty in high-throughput United States facilities. QIAGEN represents the automated workflow archetype through European market penetration with sample-to-insight pipelines. Bio-Rad Laboratories sits within the modular flexibility tier, accommodating Pacific Biosciences and Oxford Nanopore chemistries without platform lock-in. These three anchors illustrate how competitive positioning fragments across bundling, automation, and interoperability value propositions.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Roche |
| QIAGEN |
| Bio-Rad Laboratories |
| PerkinElmer |
| Revvity |
| Tecan Group |
| Illumina |
| Others |
Pricing and Supply Chain Analysis
Enzyme reagent costs cascade through three pricing tiers as raw material fermentation capacity concentrates in contract manufacturers serving Illinois and Massachusetts life science clusters. Academic medical centers absorb premium pricing for ISO 13485-certified QC kits while mid-throughput laboratories negotiate volume discounts on standard-grade consumables.
Pricing Analysis
High-throughput core facilities generate 70 percent of consumable volume at compressed margins, while clinical diagnostic laboratories sustain premium pricing through companion diagnostic validation requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical assays from research-use-only reagents and unvalidated bulk chemistries. Pricing pressure stems from multi-vendor QC ecosystem adoption as laboratories unbundle from captive reagent suppliers. Biotechnology firms in Boston and San Francisco demonstrate lowest price sensitivity due to speed-to-validation priorities, while grant-dependent academic labs drive hardest bargain negotiations.
Supply Chain Analysis
Taq polymerase and fluorescent dye supply rests on fermentation facilities in Germany, Switzerland, and the United States, with magnetic bead chemistries drawing from Japanese specialty materials producers. Critical inputs include recombinant enzymes, oligonucleotide primers, and surface-modified nanoparticles. Single-source vulnerability in long-read chemistry QC reagents exposes laboratories to allocation risk during demand surges. Distribution runs through authorized distributors in regulated clinical markets and direct-to-lab e-commerce channels in research environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-driven QC data interpretation is displacing manual bioinformatics review as the dominant validation paradigm across sequencing workflows. Cloud-native instrument connectivity now supersedes on-premise data silos as the infrastructure default.
For Market Incumbents: Anticipate platform-agnostic QC assay demand by accelerating modular chemistry development for Pacific Biosciences and Oxford Nanopore ecosystems. Consolidate service contract offerings into outcome-based maintenance agreements to counter third-party field service disintermediation. ISO 13485 certification investment represents the priority lever for clinical market retention against emerging entrants. For New Entrants and Emerging Players: Long-read chemistry QC assay development offers the most penetrable white space, with fragment analysis and library validation workflows lacking mature vendor ecosystems. Pharmacogenomic testing networks in decentralized primary care settings present underserved demand for portable, technician-minimal validation protocols. Go-to-market execution should prioritize distributor partnerships with compliance-documentation bundling capabilities for EMA IVDR-aligned European laboratories. For Investors and Strategic Acquirers: Blockchain-anchored audit trail implementation in Bavarian molecular pathology departments is the leading indicator that digital calibration certificate repositories will become table stakes for clinical QC kit procurement. Five-to-ten-year viability favors modular assay specialists with multi-platform interoperability over locked vendor ecosystems. Acquisition target archetype: platform-agnostic QC instrument developers with established long-read chemistry validation workflows. The signal to watch is consolidation of QC kit procurement through compliance-documentation bundling distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Agnostic Assay Development | Multi-chemistry compatibility captures laboratories fragmenting across Illumina, PacBio, and Oxford Nanopore fleets. |
| Blockchain Audit Trail Implementation | EMA IVDR compliance deadlines in Germany and United Kingdom mandate digital calibration certificate repositories. |
| Service Contract Unbundling | Grant-funded academic medical centers in Boston and San Francisco pressure OEMs to disclose component-level pricing. |
| Pharmacogenomic Network Partnership | Decentralized primary care genotyping panels in Japan require portable QC assays with minimal specialist oversight. |
| Long-Read Chemistry QC Infrastructure | Pacific Biosciences and Oxford Nanopore sequencing platforms lack mature fragment analysis and library validation ecosystems. |
Research Methodology
Independent corroboration across core facility directors, clinical laboratory managers, and sequencing platform engineers underwrites the qualitative findings in this study. Primary interviews with biomedical informaticists, regulatory affairs specialists at IVD manufacturers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, and NIH grant award databases. Bottom-up instrument placement tracking and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates consumable recurring revenue growth from capital equipment replacement cycles and software subscription expansion. Segmentation dimensions span product type, application, end user, and technology chemistry across the modeling period. CAGRs derive from run-volume projections at high-throughput genome centers, companion diagnostic validation pipeline expansion, and pharmacogenomic testing network penetration. Industry-specific inputs include terabase-scale instrument deployment schedules and EMA IVDR compliance deadline pacing.
Several conditions sit outside the modeled scope, including single-source reagent supply disruptions, bioinformatics specialist training pipeline expansion rates, and legacy LIMS integration friction severity. Forecasts reflect documented assumptions about grant funding continuity and regulatory timeline adherence. Supply concentration in enzyme fermentation, tariff exposure on Chinese-manufactured magnetic beads, and cloud connectivity infrastructure readiness represent specific risk factors that could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next Generation Sequencing Market
Genomics
Microarray Biochips Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Mrna Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Europe Genetic Testing Market
Genomics
Omics Lab Services Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Genomics Personalized Health Market
Genomics
Personal Genome Testing Market
Genomics
Global Digital PCR Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Antisense Oligonucleotides Market
Genomics
Genetic Material Market
Genomics
Europe Cancer Biomarkers Market
Genomics
North America DNA Sequencing Products Market