
 Microarray Biochips Market | 2026-2036
Microarray Biochips Market Size, Share, and Industry Trends Forecast 2026-2036
Microarray Biochips Market Outlook
North American contract manufacturers is repositioning capacity toward microarray substrates with enhanced oligonucleotide density. Thermo Fisher Scientific leverages its integrated reagent-instrument workflow to dominate clinical laboratory placements. Illumina sustains technology leadership in next-generation sequencing-compatible array formats. Agilent Technologies anchors the protein microarray segment through specialized surface chemistry expertise.
Microarray biochips are solid-state substrates—typically glass, silicon, or polymer slides—functionalized with spatially organized biomolecular probes at densities exceeding 100,000 features per square centimeter, enabling parallel detection of nucleic acid or protein binding events in a single assay run. DNA microarrays retain the largest revenue share due to entrenched use in genome-wide association studies, while protein microarrays represent the fastest-expanding category as antibody and peptide libraries improve diagnostic specificity. Academic institutions constitute the most price-sensitive end-user tier, whereas pharmaceutical companies generate the highest per-account consumable pull through repetitive high-content screening campaigns.
The FDA's Quality System Regulation and EPA guidelines on laboratory chemical waste shape manufacturing protocols and facility siting decisions for domestic producers. ISO 13485 certification and the EU In Vitro Diagnostic Regulation govern market access for products destined for European clinical laboratories. Stakeholders must monitor evolving reimbursement codes for molecular diagnostic tests, as coverage determinations directly influence hospital purchasing committee prioritization of biochip-based platforms.
Market Dynamics
Pharmaceutical companies are consolidating their high-throughput screening operations around microarray platforms that compress compound-to-candidate timelines, forcing substrate manufacturers to prioritize oligonucleotide density and reproducibility over unit cost.
Growth Catalysts
- Companion Diagnostic Mandates:The FDA's evolving guidance on in vitro diagnostic devices is tightening quality benchmarks for biochip manufacturers, creating captive demand from oncology drug developers seeking co-approval pathways.
- Academic Medical Center Clustering:Dense genomic research infrastructure in the United States concentrates purchasing power and accelerates platform standardization across contract research organizations.
- Next-Generation Sequencing Convergence:Array formats compatible with NGS workflows are displacing standalone hybridization assays in clinical laboratory placements.
Market Restraints
- Specialized Surface Chemistry Input Concentration:Protein microarray manufacturing depends on silane and epoxide chemistries sourced from a limited German and Japanese supplier base.
- EU In Vitro Diagnostic Regulation Friction:The MDR's expanded clinical evidence requirements extend certification timelines for new biochip submissions by 18-24 months.
- Digital PCR Substitution:Droplet-based digital PCR platforms are capturing share in copy number variation analysis from lower-density DNA microarrays.
Strategic Opportunities
- India's Diagnostic Infrastructure Buildout:The country's PLI scheme for medical devices offers 5-20% incentive on incremental sales for domestic microarray manufacturing.
- Point-of-Care Application Expansion:Miniaturized protein microarrays for infectious disease panels address the unmet need for multiplexed testing in decentralized settings.
- Artificial Intelligence Convergence:Machine learning-based feature extraction from array images is reducing analysis bottlenecks and enabling new diagnostic signatures.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortages of computational biologists proficient in array data normalization are constraining pharmaceutical customer onboarding.
- ISO 13485 Certification Burden:Smaller substrate manufacturers face 12-18 month compliance timelines to access European clinical laboratory procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microarray Biochips Market |
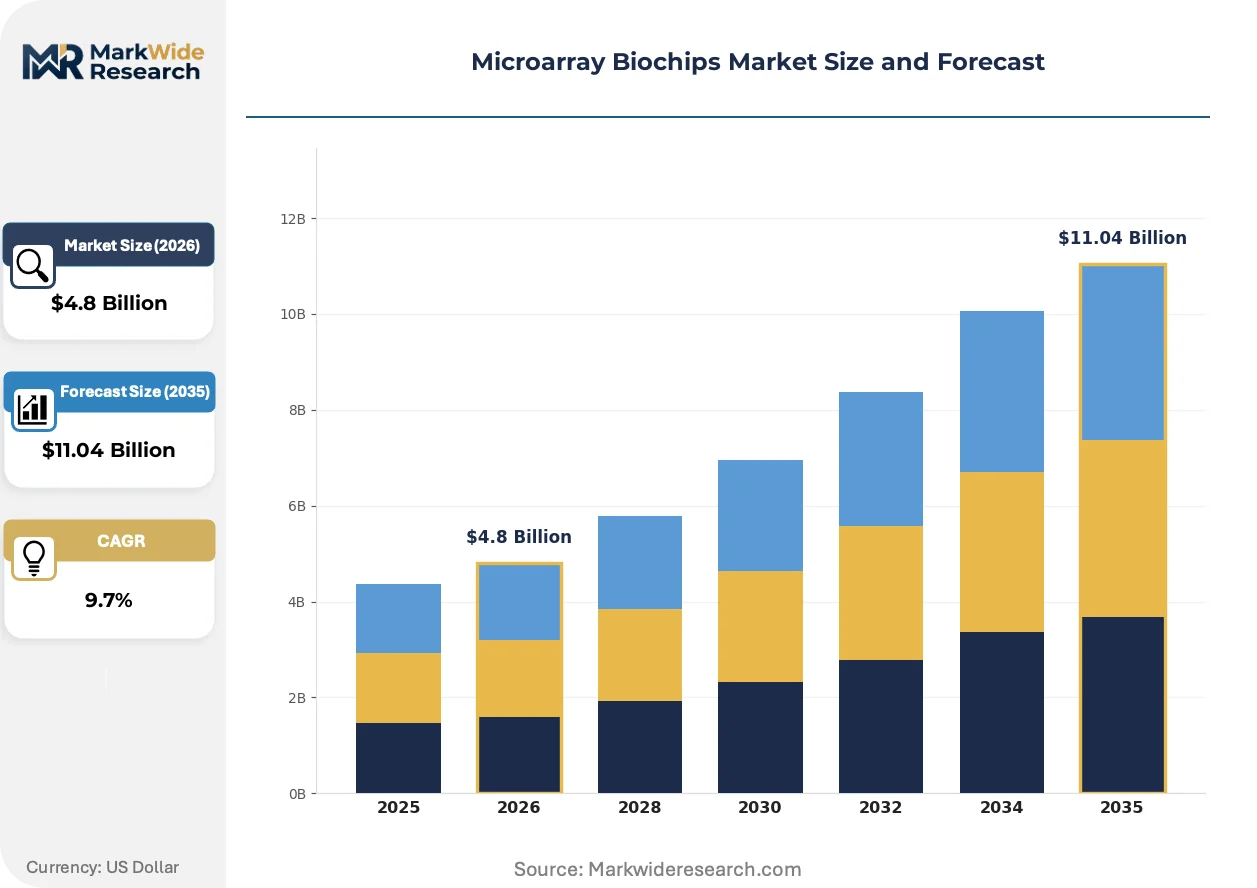
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarrays, Protein Microarrays, Tissue Microarrays, Other Technology: Hybridization-Based, Competitive Hybridization, Array-Based, Others Application: Genomics, Transcriptomics, Proteomics, Diagnostics End User: Academic Institutions, Pharmaceutical Companies, Biotech Firms, Clinical Laboratories |
| Companies Covered | Thermo Fisher Scientific, Illumina, Agilent Technologies, Bio-Rad Laboratories, F. Hoffmann-La Roche, QIAGEN, PerkinElmer, Abbott Laboratories, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microarray Biochips Market Strategic Shifts
Active substrate engineering and regulatory data requirements are compressing product development cycles while fragmenting the competitive landscape between integrated workflow providers and specialized surface chemistry houses.
Photolithographic synthesis of oligonucleotide arrays is integrating digital micromirror device patterning to achieve feature densities exceeding 2 million probes per square centimeter. Thermo Fisher Scientific and academic core facilities are adopting these next-generation formats for epigenome-wide association studies. This density escalation is integrating complex trait genetics and single-cell transcriptomics into unified experimental designs.
The FDA's Quality System Regulation is mandating enhanced design history files for Class III companion diagnostic substrates, requiring manufacturers to document failure mode effects through entire reagent-instrument workflows. Clinical laboratory customers are demanding pre-submission meeting records as a procurement prerequisite. High-complexity molecular diagnostic laboratories in the United States are responding by consolidating vendor qualification lists to three approved suppliers.
Hospital purchasing committees are unbundling after-sales technical support from instrument procurement contracts, treating bioinformatics training and assay optimization as separately negotiated line items. Academic institutions are driving this disintermediation through centralized core facility management offices that standardize service level agreements across multiple principal investigator grants. This behavior is most visible in the United States, where NIH funding mechanisms incentivize shared resource optimization over individual laboratory capital purchases.
Microarray Biochips Market Segmentation
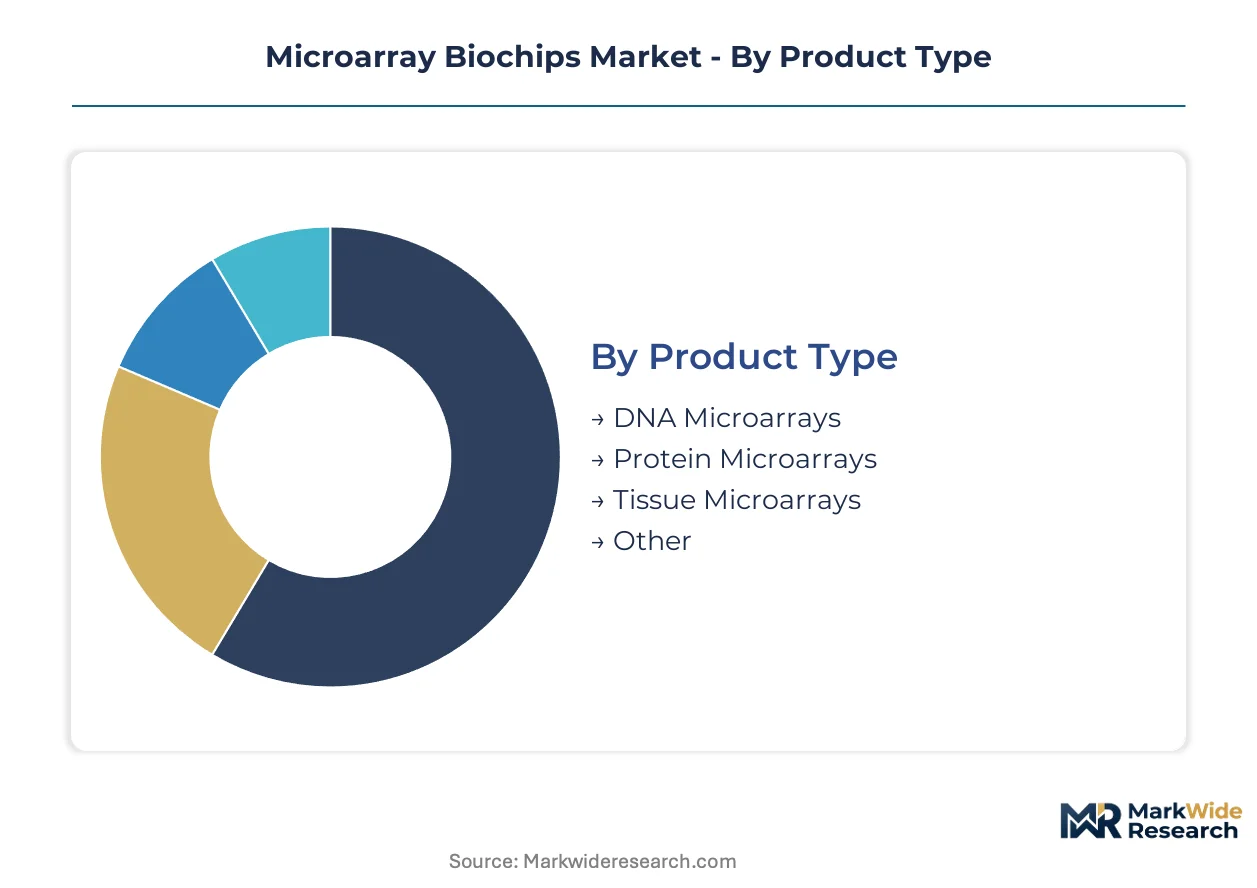
Microarray biochip segmentation reveals divergent capital requirements across substrate technologies, with surface chemistry sophistication and regulatory compliance burden determining manufacturer investment thresholds. Pharmaceutical procurement patterns and academic funding cycles further fragment demand characteristics across end-use categories.
Product Type:
Capital intensity escalates sharply with biomolecular complexity, as protein functionalization demands specialized cleanroom infrastructure absent from nucleic acid workflows.
- DNA Microarrays:Glass or silicon substrates functionalized with oligonucleotide probes at densities exceeding 100,000 features per square centimeter. Academic medical centers in the United States concentrate demand for genome-wide association studies, though digital PCR substitution is eroding share in copy number variation analysis.
- Protein Microarrays:Specialized surface chemistries—silane, epoxide, or nitrocellulose—immobilize antibodies or peptide libraries for multiplexed binding assays. Pharmaceutical companies in high-throughput screening campaigns drive the steepest capacity expansion, constrained by German and Japanese supplier concentration for critical reagents.
- Tissue Microarrays:Paraffin-embedded tissue cores arrayed for histopathological correlation studies.
- Other:Carbohydrate and small-molecule microarrays for glycomics and metabolomics applications.
DNA Microarrays absorb the bulk of installed capacity; Protein Microarrays are expanding most quickly.
Technology:
Process maturity separates segments, with photolithographic synthesis commanding premium equipment investment while competitive hybridization relies on commodified thermal cyclers.
- Hybridization-Based:Fluorescent-labeled target molecules bind complementary surface-immobilized probes, detected via confocal scanning. Clinical laboratories prioritize this established format for companion diagnostic workflows, pressured by FDA Quality System Regulation documentation requirements.
- Competitive Hybridization:Differential binding kinetics enable relative quantification without absolute standard curves. Academic core facilities favor this approach for budget-constrained expression profiling, though throughput lags array-based alternatives.
- Array-Based:Spatially encoded bead or electronic detection formats.
- Others:Emerging electrochemical and nanoparticle-enhanced signal amplification methods.
Hybridization-Based technology commands the dominant installed base; Array-Based formats are gaining share fastest in next-generation sequencing convergence applications.
Application:
Regulatory pathway complexity stratifies investment returns, with diagnostics requiring ISO 13485 certification that genomics research bypasses.
- Genomics:Whole-genome genotyping and structural variation mapping on high-density oligonucleotide platforms. United States academic consortia maintain dense infrastructure for complex trait genetics, consolidating procurement through centralized core facilities.
- Proteomics:Multiplexed protein expression profiling and biomarker discovery. Biotech firms in precision oncology drive demand for antibody array specificity, constrained by bioinformatics talent scarcity in array data normalization.
- Transcriptomics:Gene expression and alternative splicing analysis.
- Diagnostics:FDA-cleared companion diagnostic and infectious disease panels.
Genomics retains the largest revenue footprint; Diagnostics is climbing the fastest on companion diagnostic mandate expansion.
End User:
Procurement sophistication varies dramatically, with pharmaceutical companies negotiating integrated reagent-instrument workflows that academic institutions unbundle.
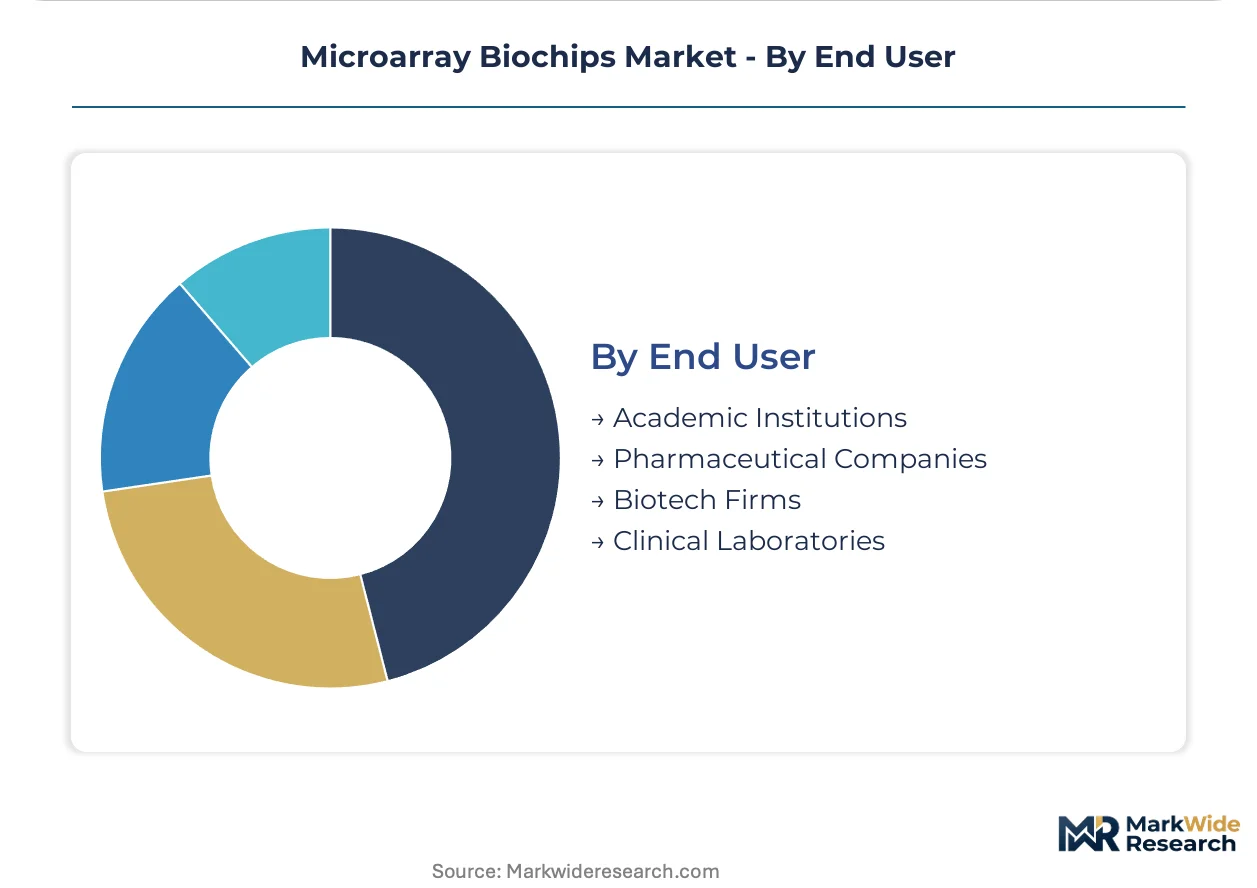
- Pharmaceutical Companies:High-throughput screening platforms compress compound-to-candidate timelines through repetitive high-content campaigns. These customers generate the highest per-account consumable pull and demand pre-submission meeting records as vendor qualification prerequisites.
- Academic Institutions:Price-sensitive researchers accessing shared core facility infrastructure. NIH funding mechanisms in the United States incentivize resource optimization over individual laboratory capital purchases, driving centralized service level agreement standardization.
- Biotech Firms:Venture-funded developers of precision therapeutics.
- Clinical Laboratories:Hospital-based high-complexity molecular diagnostic operations.
Pharmaceutical Companies dominate absolute spending; Clinical Laboratories are expanding procurement fastest on reimbursement code expansion for molecular diagnostic tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese chemical suppliers anchor the specialized surface chemistry input base for protein microarray manufacturing, while the United States concentrates genomic research infrastructure and FDA regulatory precedent.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive dense demand for high-throughput screening platforms. The FDA's Quality System Regulation mandates enhanced design history files for Class III companion diagnostic substrates. NIH-funded core facilities in Bethesda and Research Triangle Park standardize procurement through centralized service level agreements.
Germany
Specialized silane and epoxide chemistry suppliers in the Rhine-Ruhr region constrain protein microarray manufacturing capacity. The EU In Vitro Diagnostic Regulation extends certification timelines for new biochip submissions by 18-24 months. Precision oncology biotech clusters in Munich and Heidelberg generate concentrated demand for antibody array specificity.
Japan
METI-supported genomic medicine initiatives accelerate adoption of next-generation sequencing-compatible array formats. PMDA consultation procedures for companion diagnostics create regulatory precedent for domestic manufacturers. Tokyo-Yokohama and Osaka-Kobe corridors host dense concentrations of pharmaceutical high-throughput screening operations.
India
The PLI scheme for medical devices offers 5-20% incentive on incremental sales for domestic microarray manufacturing. CDSCO's evolving stance on in vitro diagnostic device registration shapes market entry strategies for foreign substrate suppliers. Bangalore and Hyderabad clusters attract contract research organization investment in genomic infrastructure.
China
NMPA's streamlined review pathways for innovative diagnostic devices accelerate local biochip commercialization. Dual carbon goals pressure manufacturers to relocate energy-intensive substrate processing away from coastal provinces. Shanghai and Suzhou industrial parks concentrate domestic oligonucleotide synthesis capacity.
Microarray Biochips Market Competitive Environment
Global majors compete with regional champions across integrated workflow versus specialized substrate dimensions. The vendor base stratifies between full-stack reagent-instrument providers and focused surface chemistry houses. Three archetypes dominate: diversified life science conglomerates with captive distribution, precision substrate specialists with ISO 13485 certification, and sequencing-platform-integrated array format developers. Competitive moves concentrate on strategic partnerships for regulatory co-submission and capacity expansion into India's PLI-incentivized manufacturing zones.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Illumina occupy positions as anchors of integrated workflow dominance. Agilent Technologies exemplifies the specialized surface chemistry archetype through its protein microarray segment focus. These three entities represent the competitive poles around which mid-cap substrate manufacturers and regional diagnostic platform developers organize their market entry and partnership strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Agilent Technologies |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| QIAGEN |
| PerkinElmer |
| Abbott Laboratories |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Specialized silane and epoxide chemistries originating in German and Japanese supplier bases flow through substrate manufacturers into tiered pricing structures that separate ISO 13485-certified clinical-grade products from research-use-only alternatives. Academic institutions in the United States exert downward pressure on economy-tier consumables while pharmaceutical companies absorb premium pricing for companion diagnostic-qualified workflows.
Pricing Analysis
After-sales technical support unbundling from instrument procurement contracts is fragmenting pricing structures across service-level tiers. Three-tier pricing separates premium companion-diagnostic-qualified substrates from standard research-grade formats and economy core-facility consumables, with price differentiation driven by FDA pre-submission documentation depth and oligonucleotide density specifications. Pricing pressure stems from digital PCR substitution eroding share in copy number variation applications. Academic institutions exhibit the highest price sensitivity through centralized NIH-funded core facility negotiations, while pharmaceutical companies prioritize timeline compression over unit cost.
Supply Chain Analysis
India's PLI scheme for medical devices with its 5-20% domestic-content incentive is reshaping sourcing strategies for foreign substrate suppliers seeking market access. Manufacturing capacity concentrates in the United States, Germany, and Japan, with raw material dependencies on Rhine-Ruhr silane chemistry and Japanese epoxide formulations. Single-source vulnerability from this German-Japanese supplier concentration creates exposure for protein microarray manufacturers. Distribution runs through direct sales to pharmaceutical high-throughput screening operations and GPO-aggregated hospital laboratory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next-generation sequencing convergence is displacing standalone hybridization assays, compressing the technology transition window for legacy platform holders. Stakeholders must position around NGS-compatible array formats or risk stranded capacity in lower-density segments.
For Market Incumbents: Anchor companion diagnostic regulatory pathways through FDA pre-submission investments that lock in pharmaceutical customer qualification lists. Deepen backward integration into specialized surface chemistry production to offset German-Japanese supplier concentration risk. Prioritize capacity expansion into India's PLI-incentivized zones to capture emerging diagnostic infrastructure demand.
For New Entrants and Emerging Players: Launch via decentralized point-of-care protein microarray formats targeting infectious disease panels in underserved clinical settings. Exploit white-space in miniaturized multiplexed testing for resource-limited laboratories. Penetrate through AI-enabled feature extraction partnerships that reduce bioinformatics talent barriers for pharmaceutical customers.
For Investors and Strategic Acquirers: FDA companion diagnostic approval paired with oncology drug co-development is the leading indicator that substrate manufacturers have achieved sustainable pricing power. Target precision surface chemistry specialists with ISO 13485 certification and established pharmaceutical workflows. Watch for consolidation signals when hospital purchasing committees narrow vendor qualification lists below five approved suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Co-Submission Partnership | FDA-aligned companion diagnostic pathways lock in pharmaceutical procurement commitments. |
| Backward Integration into Surface Chemistry | In-house silane and epoxide production reduces dependency on German-Japanese suppliers. |
| India Manufacturing Footprint Expansion | PLI scheme incentives improve cost positioning for domestic diagnostic infrastructure buildout. |
| AI-Enabled Image Analysis Integration | Machine learning partnerships address bioinformatics talent scarcity constraining customer onboarding. |
| Point-of-Care Miniaturization Program | Decentralized infectious disease panels access reimbursement expansion in molecular diagnostics. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with biochip manufacturing executives, pharmaceutical high-throughput screening directors, hospital purchasing committee members, and core facility managers. FDA 510(k) and PMA submission databases, EU MDR technical documentation, and NIH grant award records provided demand-side validation. Bottom-up substrate shipment estimates triangulated against top-down pharmaceutical R&D expenditure allocations.
Segment-level granularity modeled product type, technology format, application area, and end-user procurement sophistication across the projection horizon. DNA, protein, and tissue microarray categories were assessed separately for capital intensity and regulatory compliance burden. Hybridization-based and competitive hybridization technologies carried distinct equipment depreciation profiles. CAGR derivation incorporated pharmaceutical pipeline stage transitions, academic funding cycle timing, and reimbursement code expansion trajectories for molecular diagnostic tests.
Regulatory timeline delays, digital PCR substitution acceleration, and companion diagnostic mandate scope changes are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Prenatal Genetic Testing Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
Apolipoprotein Test Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Global Genomics Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Restriction Endonucleases Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Plant Genomics Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Next Generation Sequencing Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Spatial OMICS Market