
 Personal Genome Testing Market | 2026-2036
Personal Genome Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Genome Testing Market Analytics
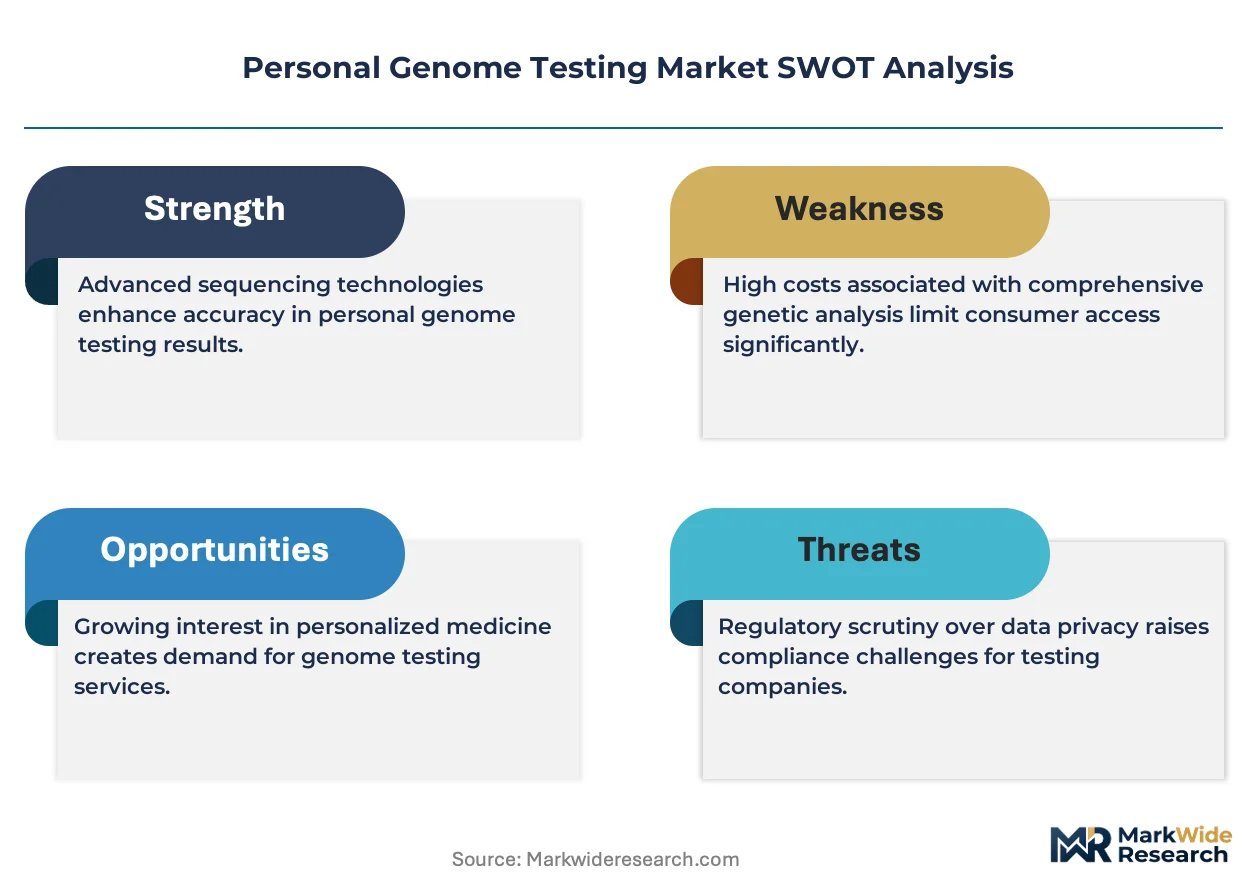
A shortage of board-certified genetic counselors is reorganizing how personal genome testing companies structure patient-facing services and clinical support workflows. 23andMe, Inc. leverages its direct-to-consumer platform to sustain high-volume sample collection without traditional clinical gatekeepers. Illumina, Inc. anchors the sequencing infrastructure layer, dominating the instrument and reagent supply chain that powers most testing laboratories. Thermo Fisher Scientific competes across both research and clinical channels, extending its consumables footprint into certified diagnostic workflows.
Personal genome testing encompasses the analysis of an individual's DNA to identify genetic variants, typically employing SNP arrays with probe densities exceeding 500,000 markers or next-generation sequencing achieving read depths above 30x for clinical-grade variant calling. Its primary commercial purpose spans health risk prediction, ancestry reconstruction, and pharmacogenomic guidance for therapeutic selection. Whole Genome Sequencing commands premium positioning as the most comprehensive analytical tier, while SNP Analysis retains volume leadership through lower cost structures and faster turnaround times. Direct-to-Consumer distribution channels face margin compression from regulatory compliance costs, whereas Healthcare Provider channels capture higher per-test value through integrated clinical interpretation and reimbursement pathways.
The FDA exercises direct oversight of direct-to-consumer genetic health risk claims, requiring premarket authorization for tests with diagnostic implications, while the Centers for Medicare and Medicaid Services governs reimbursement eligibility through molecular diagnostic coding decisions. CLIA certification mandates shape laboratory operational requirements, determining which facilities can return clinically actionable results versus ancestry-only profiles. State-level laboratory licensing regimes add further fragmentation to market access conditions across jurisdictions. Stakeholders must monitor evolving FDA classification paradigms for multi-gene panels and the potential harmonization of state laboratory standards that could reshape competitive barriers for emerging entrants.
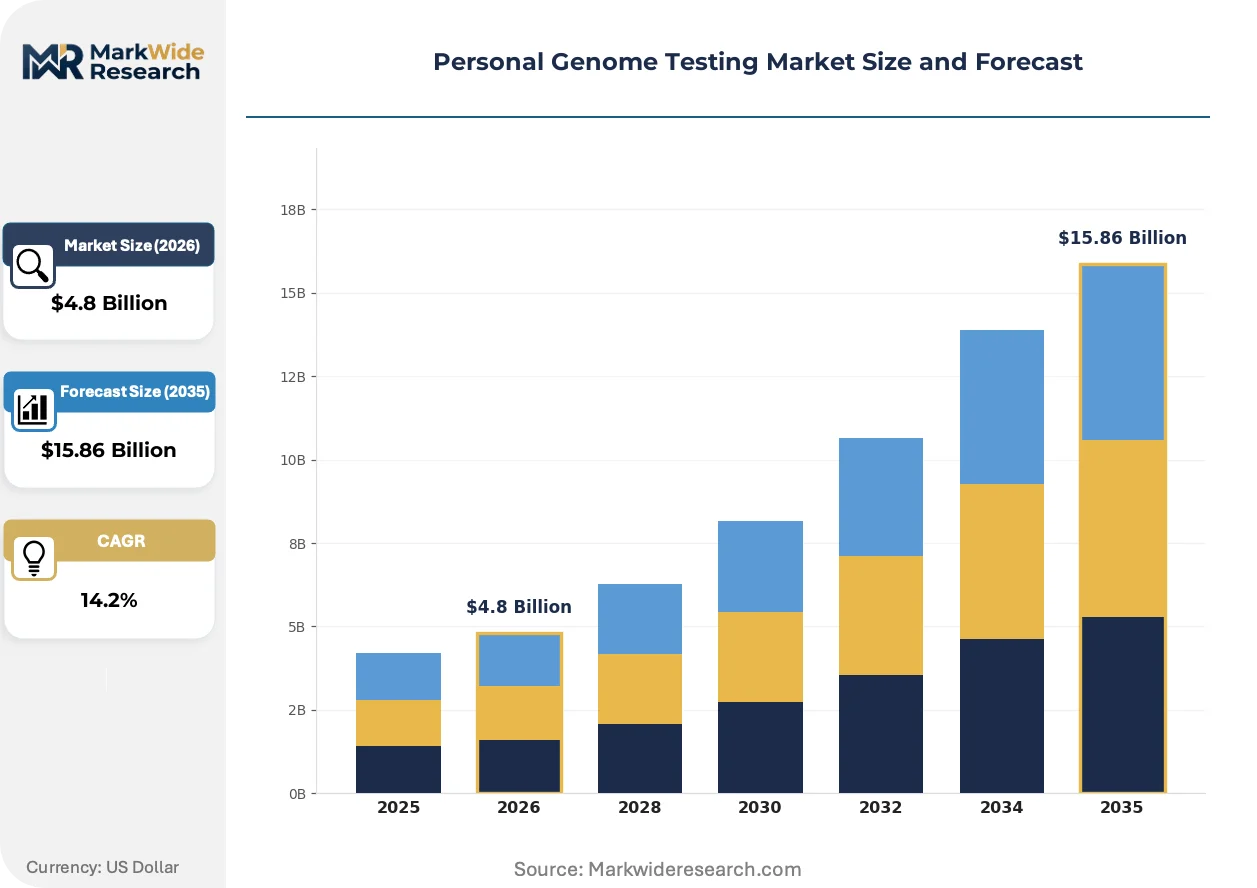
Market Dynamics
Pharmacogenomic integration into routine prescribing workflows is compressing the timeline between sample collection and therapeutic decision, forcing laboratories to restructure turnaround guarantees and clinical support staffing models.
Growth Catalysts
- Pharmacogenomic reimbursement expansion:CMS molecular diagnostic coding decisions in the United States now cover multi-gene panels for antidepressant and anticoagulant selection, pulling testing volume into clinical workflows.
- Consumer ancestry-to-health migration:Established user bases from recreational genetic genealogy are converting to health risk and wellness applications as platform features expand.
- Polygenic risk score refinement:Machine learning architectures trained on biobank-scale cohorts are improving predictive validity for common disease susceptibility, broadening clinical utility.
Market Restraints
- Illumina instrument lock-in:Sequencing chemistry and flow cell supply concentration creates vulnerability for laboratories dependent on single-source reagent continuity.
- FDA premarket authorization timelines:Direct-to-consumer health risk claims face 12-18 month review cycles that compress margin structures for iterative product releases.
- Genetic counselor workforce scarcity:Board-certified professional supply constraints limit scalable clinical interpretation for complex variant reporting.
Strategic Opportunities
- Employer wellness channel penetration:Self-insured corporations in the United States are piloting pharmacogenomic benefits as differentiated recruitment and cost-containment tools.
- AI-assisted variant classification:Deep learning models for ACMG criteria automation are converging with laboratory information systems to compress reporting labor intensity.
- Long-read sequencing adoption:Pacific Biosciences and Oxford Nanopore platforms are opening structural variant detection for hereditary cancer panels previously limited to SNP resolution.
Industry Challenges
- CLIA certification capacity bottlenecks:High-complexity molecular pathology laboratory buildouts require 18-24 month construction and inspection timelines that delay geographic expansion.
- EHR integration fragmentation:Disconnected health record architectures force manual result entry and create interpretation gaps between laboratory output and prescribing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Genome Testing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Direct-to-Consumer, Diagnostic Testing, Ancestry Testing, Nutrigenomics Technology: SNP Analysis, Whole Genome Sequencing, Whole Exome Sequencing, RNA Sequencing End User: Individual Consumers, Healthcare Providers, Research Institutions, Biopharmaceutical Companies Application: Health Risk Assessment, Carrier Testing, Pharmacogenomics, Traits Analysis |
| Companies Covered | 23andMe, Inc., Color Genomics, Inc., Invitae Corporation, Quest Diagnostics, Laboratory Corporation of America Holdings, Myriad Genetics, Inc., Illumina, Inc., Thermo Fisher Scientific, Helix OpCo LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Genome Testing Market Evolving Landscape
Long-read sequencing platforms are compressing the cost-performance gap with short-read dominance, while regulatory frameworks on both sides of the Atlantic recalibrate oversight intensity for algorithmic health predictions.
Third-generation sequencing chemistries from Pacific Biosciences and Oxford Nanopore are displacing short-read Illumina workflows for structural variant detection in hereditary disease panels. Clinical laboratories in the United States and Germany are validating these platforms for repeat expansion disorders and copy number analysis where fragment-based methods fail. The shift is fragmenting the sequencing equipment installed base and forcing reagent suppliers to diversify chemistry portfolios.
The FDA's evolving classification framework for software-as-a-medical-device is tightening premarket scrutiny of polygenic risk algorithms embedded in consumer-facing health reports. Laboratories must now submit locked algorithm versions rather than iterative cloud-based updates, extending product development cycles. Direct-to-consumer channels face the steepest compliance cost escalation, while healthcare provider channels absorb these burdens through integrated quality systems.
Employer-sponsored benefits procurement is redirecting pharmacogenomic testing volume from direct-to-consumer marketing into occupational health contracts with guaranteed minimum volumes. Self-insured technology and financial services firms in California and Massachusetts are contracting directly with CLIA-certified laboratories, bypassing traditional payer networks. This channel compression is forcing ancestry-focused platforms to build clinical sales infrastructure or retreat to recreational applications.
Personal Genome Testing Market Segmentation
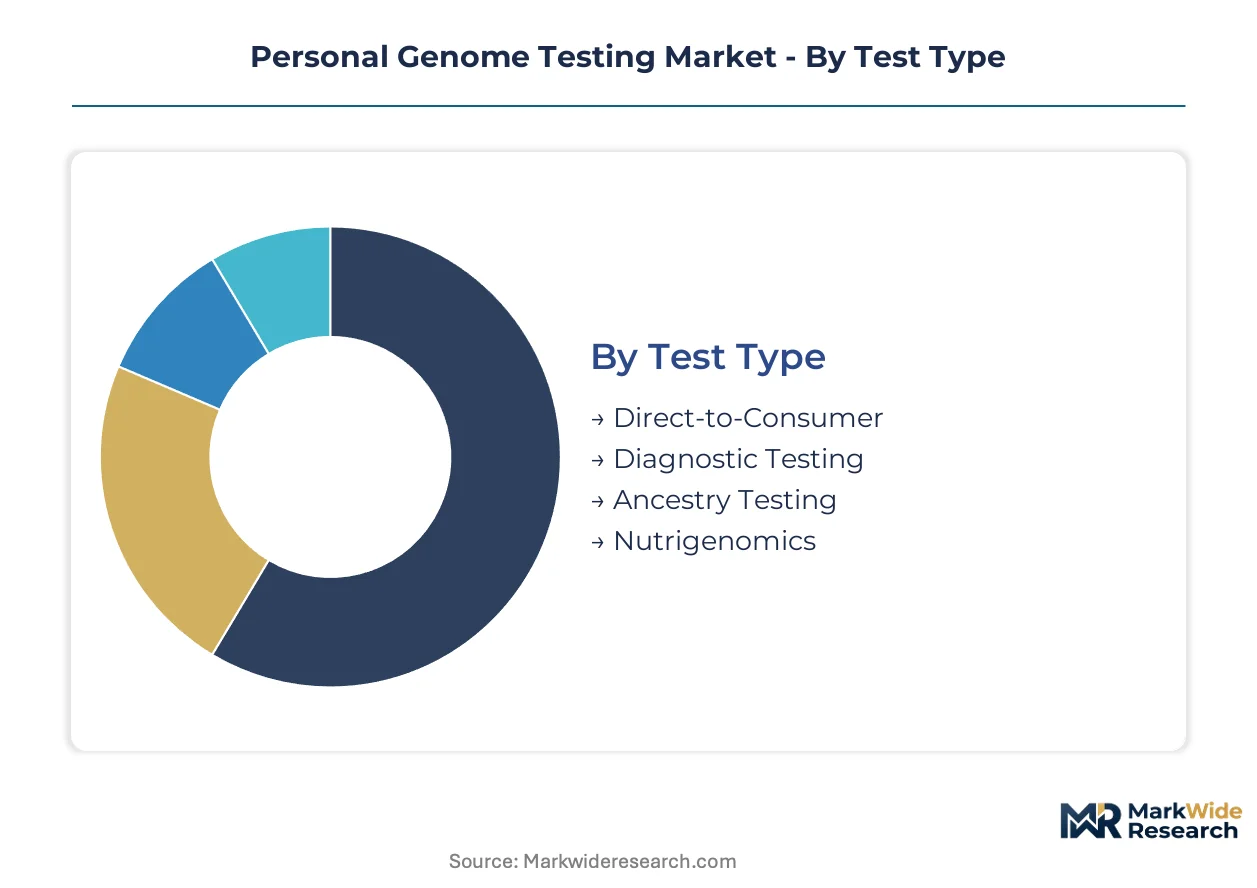
Personal genome testing segments diverge sharply in margin structure, with clinical channels capturing reimbursement premiums while direct-to-consumer volumes face regulatory compliance burdens. Technology tiers separate capital-intensive sequencing infrastructure from scalable array-based workflows. Understanding these fault lines reveals where capital deployment generates sustainable returns versus commodity pressure.
Test Type:
Margin pools concentrate in diagnostic testing where CLIA certification creates reimbursement gatekeeping, while direct-to-consumer channels absorb FDA premarket authorization costs that erode unit economics.
- Direct-to-Consumer:SNP array-based profiles sold without clinical intermediaries, typically returning ancestry and wellness traits. Demand clusters in the United States where consumer familiarity with genetic genealogy runs deepest, though FDA health risk claim restrictions compress iterative product release cycles.
- Diagnostic Testing:Physician-ordered panels with clinical interpretation and actionable variant reporting. Healthcare providers in the United States drive volume through pharmacogenomic integration into prescribing workflows, capturing higher per-test value through established reimbursement codes.
- Ancestry Testing:Genealogical reconstruction using reference population databases. Recreational user bases in the United States and United Kingdom provide foundational sample collection for platform expansion into health applications.
- Nutrigenomics:Dietary and metabolic trait analysis linking genetic variants to nutritional recommendations. Wellness-oriented consumers in Germany and Australia show strongest conversion from general genetic curiosity to lifestyle-specific applications.
The dominant share belongs to Diagnostic Testing, while Direct-to-Consumer is closing the gap fastest through employer wellness channel penetration.
Technology:
Cost tier separation defines competitive positioning, with premium sequencing workflows commanding clinical-grade pricing and array technologies sustaining high-throughput consumer volumes.
- SNP Analysis:Microarray platforms interrogating 500,000+ markers for common variant detection. Laboratories dependent on Illumina chemistry face supply concentration risks, though turnaround speed and reagent cost structures maintain volume leadership in consumer and carrier screening applications.
- Whole Genome Sequencing:30x+ coverage read depths enabling comprehensive variant calling across coding and non-coding regions. Academic medical centers in the United States and United Kingdom are validating clinical utility for rare disease diagnosis, where diagnostic odyssey compression justifies premium pricing.
- Whole Exome Sequencing:Protein-coding region capture at reduced cost versus whole genome. Research institutions in Germany and the Netherlands leverage exome breadth for hereditary cancer panel development where structural variant detection requirements remain limited.
- RNA Sequencing:Transcriptomic profiling for gene expression and fusion detection. Biopharmaceutical companies in Massachusetts and California deploy RNA-seq for biomarker discovery in immuno-oncology trials, though clinical diagnostic adoption lags DNA-based methods.
SNP Analysis retains volume leadership through cost efficiency, while Whole Genome Sequencing is gaining share fastest as long-read platforms compress the cost-performance gap.
End User:
Customer type determines channel economics, with institutional procurement generating guaranteed minimum volumes and individual transactions bearing highest customer acquisition costs.
- Individual Consumers:Self-directed purchasers accessing tests through direct-to-consumer platforms or physician-ordered channels. United States consumers show deepest penetration of repeat testing behavior, migrating from ancestry to health risk and pharmacogenomic applications.
- Healthcare Providers:Hospitals, clinics, and integrated delivery networks ordering diagnostic panels. Provider systems in California and Texas are building in-house pharmacogenomic programs, pulling volume from reference laboratories through CLIA-certified hospital labs.
- Research Institutions:Academic and government laboratories generating population-scale genomic data. Biobanks in the United Kingdom and Estonia contribute cohort data refining polygenic risk algorithms, though data governance frameworks constrain commercial translation speed.
- Biopharmaceutical Companies:Drug developers employing genomic stratification for trial enrollment and companion diagnostic development. Oncology-focused firms in Massachusetts and New Jersey contract for tumor-normal sequencing paired with germline testing for hereditary risk assessment.
Healthcare Providers capture the dominant revenue share, while Biopharmaceutical Companies are expanding most quickly through precision medicine pipeline investments.
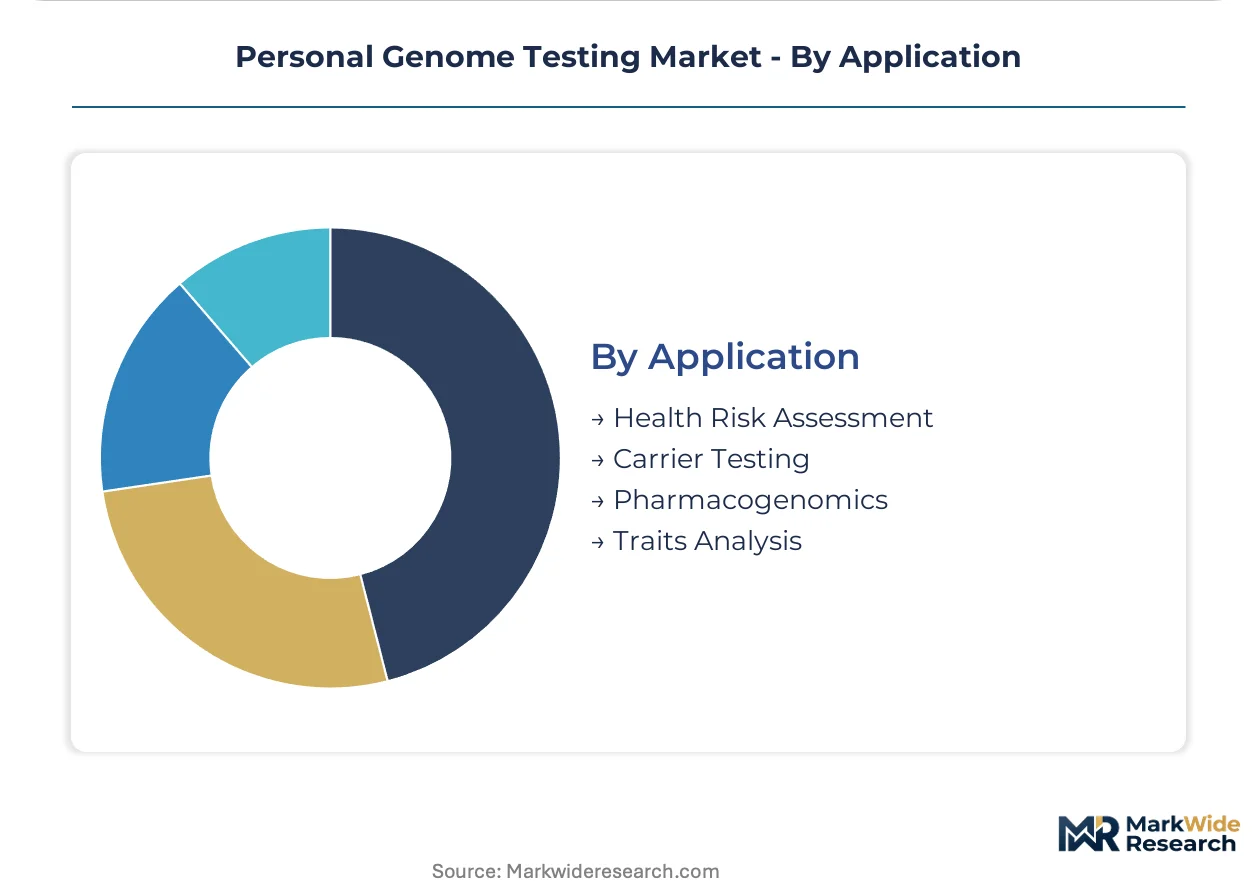
Application:
Maturity gradients separate established reimbursement pathways from emerging utility demonstrations, with pharmacogenomic integration advancing fastest into routine clinical workflows.
- Health Risk Assessment:Polygenic and monogenic susceptibility scoring for common diseases. FDA premarket authorization requirements for direct-to-consumer delivery in the United States have shifted volume toward healthcare provider channels where clinical interpretation absorbs regulatory burden.
- Carrier Testing:Preconception screening for autosomal recessive conditions. Obstetrics practices in the United States have standardized expanded carrier panels, with Ashkenazi Jewish and Mediterranean population-focused testing showing highest positive predictive value.
- Pharmacogenomics:Drug-gene interaction guidance for therapeutic selection. CMS molecular diagnostic coding decisions now cover antidepressant and anticoagulant panels in the United States, compressing the timeline between sample collection and prescribing decision.
- Traits Analysis:Non-medical phenotype prediction including ancestry, physical characteristics, and behavioral tendencies. Recreational applications face margin pressure as consumer novelty attenuates and platforms pivot toward health-relevant utility.
Pharmacogenomics commands the steepest expansion trajectory, while Health Risk Assessment retains the largest installed base from early direct-to-consumer penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where CMS reimbursement codes for pharmacogenomic panels sustain premium capture, while laboratories in Germany and the United Kingdom compete on turnaround speed and integrated clinical interpretation services.
United States
Healthcare provider channel expansion and employer wellness program procurement drive volume concentration. FDA premarket authorization requirements for direct-to-consumer health risk claims compress margin structures for iterative product releases. Boston and San Francisco Bay Area clusters anchor precision medicine infrastructure development.
Germany
Nutrigenomics applications and lifestyle-specific genetic testing show strongest consumer conversion from general curiosity. The country's national pharmaceutical regulator maintains stringent laboratory certification standards that shape competitive barriers. Munich and Heidelberg metropolitan areas concentrate clinical research validation partnerships.
United Kingdom
Biobank-scale cohort contributions refine polygenic risk algorithms for common disease susceptibility. Data governance frameworks constrain commercial translation speed from research to clinical utility. London and Cambridge clusters lead structural variant detection platform validation for hereditary cancer panels.
China
Domestic sequencing instrument development accelerates as national regulators prioritize supply chain independence from foreign reagent dependencies. The national medical products administration shapes approval pathways for clinical-grade variant calling workflows. Shanghai and Shenzhen metropolitan hubs concentrate next-generation sequencing service provider buildouts.
Australia
Carrier screening standardization in obstetrics practices and pharmacogenomic integration into prescribing workflows expand clinical test volumes. The country's therapeutic goods administration governs laboratory-developed test registration requirements. Melbourne and Sydney clusters anchor population-scale genomic research infrastructure.
Personal Genome Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with sequencing infrastructure suppliers commanding supply-side concentration while direct-to-consumer platforms compete on customer acquisition efficiency and clinical channel penetration. The market structure fragments across three tiers: integrated diagnostic conglomerates with CLIA-certified laboratory networks, specialized genetic testing platforms with ancestry-to-health migration strategies, and sequencing technology suppliers anchoring the reagent and instrument layer. Dominant competitive moves include strategic partnerships between testing platforms and electronic health record vendors, plus capacity expansion through high-complexity molecular pathology laboratory buildouts.
Within the direct-to-consumer platform tier, 23andMe, Inc. and Helix OpCo LLC exemplify archetypes leveraging established user bases for health application expansion. Among integrated diagnostic conglomerates, Quest Diagnostics and Laboratory Corporation of America Holdings occupy positions spanning reference laboratory networks with established payer relationships. On the sequencing infrastructure vector, Illumina, Inc. and Thermo Fisher Scientific anchor the instrument and reagent supply chain that powers most testing laboratories globally.
| Leading Market Players |
|---|
| 23andMe, Inc. |
| Color Genomics, Inc. |
| Invitae Corporation |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Myriad Genetics, Inc. |
| Illumina, Inc. |
| Thermo Fisher Scientific |
| Helix OpCo LLC |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Illumina's San Diego sequencing instrument factories shapes both reagent pricing floors and laboratory procurement bargaining power across the personal genome testing value chain. High-throughput CLIA-certified facilities achieve per-sample cost advantages that compress margins for mid-volume competitors while sustaining premium capture for clinical-grade interpretation services.
Pricing Analysis
The customization-premium spread separates standard SNP array profiles from physician-ordered panels with integrated clinical interpretation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and turnaround guarantee, with FDA-authorized diagnostic tests commanding reimbursement multiples over direct-to-consumer ancestry products. Cost compression in the consumer tier stems from employer wellness channel procurement consolidating volume under guaranteed minimum contracts. Healthcare provider segments show lowest price sensitivity due to established CMS molecular diagnostic coding, while individual consumers face highest sensitivity as novelty-driven demand attenuates.
Supply Chain Analysis
The United States and China anchor sequencing instrument manufacturing and reagent production respectively, with Germany contributing specialized laboratory automation equipment. Flow cells, polymerases, and synthetic oligonucleotides constitute critical input dependencies that draw from concentrated chemical synthesis hubs. Single-source vulnerability in Illumina's sequencing chemistry creates supply continuity exposure for laboratories lacking platform diversification. Distribution runs through CLIA-certified reference laboratory networks in the United States and direct-to-consumer logistics partnerships for ancestry-focused platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacogenomic clinical interpretation services and recurring subscription models for health risk monitoring are expanding faster than sequencing hardware sales, repositioning the market as a service-attach opportunity with durable recurring revenue streams.
For Market Incumbents: Consolidate CLIA-certified laboratory networks through selective acquisition of regional molecular pathology facilities facing certification capacity bottlenecks. Deepen backward integration into bioinformatics pipelines to offset genetic counselor workforce scarcity compressing scalable clinical interpretation. Defensive moves should prioritize locking in employer wellness channel contracts before emerging platforms build clinical sales infrastructure. For New Entrants and Emerging Players: AI-assisted variant classification tools where incumbents under-serve mid-tier laboratories lacking in-house bioinformatics capacity offer immediate white-space penetration. Employer-sponsored benefits procurement in self-insured technology firms represents the most penetrable segment, with direct contracting models bypassing traditional payer network complexity. A go-to-market angle pairing long-read sequencing platforms with structural variant detection for hereditary cancer panels differentiates against established SNP array incumbents. For Investors and Strategic Acquirers: Specialized genetic testing platforms with ancestry-to-health migration capabilities and established CLIA certification represent the priority acquisition archetype for portfolio exposure to clinical channel conversion. Long-term viability over the projection horizon hinges on successful navigation of FDA software-as-a-medical-device classification tightening for polygenic risk algorithms. The signal to watch is employer wellness contract announcement velocity as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Certified Laboratory Acquisition | Consolidates geographic presence and accelerates pharmacogenomic test volume capture under established reimbursement codes. |
| AI-Assisted Variant Classification Development | Compresses reporting labor intensity for ACMG criteria automation, addressing genetic counselor workforce constraints. |
| Employer Wellness Channel Partnership | Redirects testing volume from direct-to-consumer marketing into guaranteed minimum occupational health contracts. |
| Long-Read Sequencing Platform Validation | Opens structural variant detection for hereditary cancer panels previously limited to SNP resolution methods. |
| EHR Integration Infrastructure Investment | Closes interpretation gaps between laboratory output and prescribing workflows, reducing manual result entry friction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors at CLIA-certified facilities, genetic counselors managing clinical interpretation workflows, and procurement officers at self-insured employer health plans. Secondary validation drew from FDA 510(k) premarket notification databases, CMS molecular diagnostic coding decisions, ClinicalTrials.gov pharmacogenomic study registrations, and SEC filings of publicly traded testing platforms. Bottom-up test volume estimates triangulated against top-down market sizing derived from instrument installed base and reagent consumption patterns.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning test type, technology tier, end-user category, and application area with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation of reimbursement expansion trajectories and consumer channel migration patterns, cross-referenced against sequencing cost decline curves and polygenic risk algorithm validation milestones in biobank-scale cohorts.
Underlying assumptions cover pharmacogenomic coding expansion continuity and long-read platform cost-performance convergence, with deviation risk concentrated in FDA software-as-a-medical-device classification shifts and state-level laboratory licensing harmonization delays. Recalibration cycles align with material shifts in CMS coverage determinations and employer benefits procurement adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Optical Genome Mapping Market
Genomics
Europe Digital PCR Market
Genomics
United States DNA Sequencing Products Market
Genomics
Global Pharmacogenomics Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Human Genetics Market
Genomics
North America Genetic Testing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
SNP Genotyping Market
Genomics
Next Generation Molecular Assay Market
Genomics
Global Metagenomics Market
Genomics
Global Genotyping Assay Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market