
 Next-Generation Industrial Metrology and Inspection Market | 2026-2036
Next-Generation Industrial Metrology and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Industrial Metrology and Inspection Market Foresight
Silicon carbide is rebalancing probe durability and thermal stability in high-precision coordinate measuring machines. Hexagon AB leverages its software-hardware integration to dominate multi-sensor CMM platforms across automotive quality control. Renishaw plc anchors its position through in-house production of encoder and probe technologies that sustain measurement repeatability. Carl Zeiss AG specializes in optical measurement systems where sub-micron resolution commands premium positioning in electronics testing.
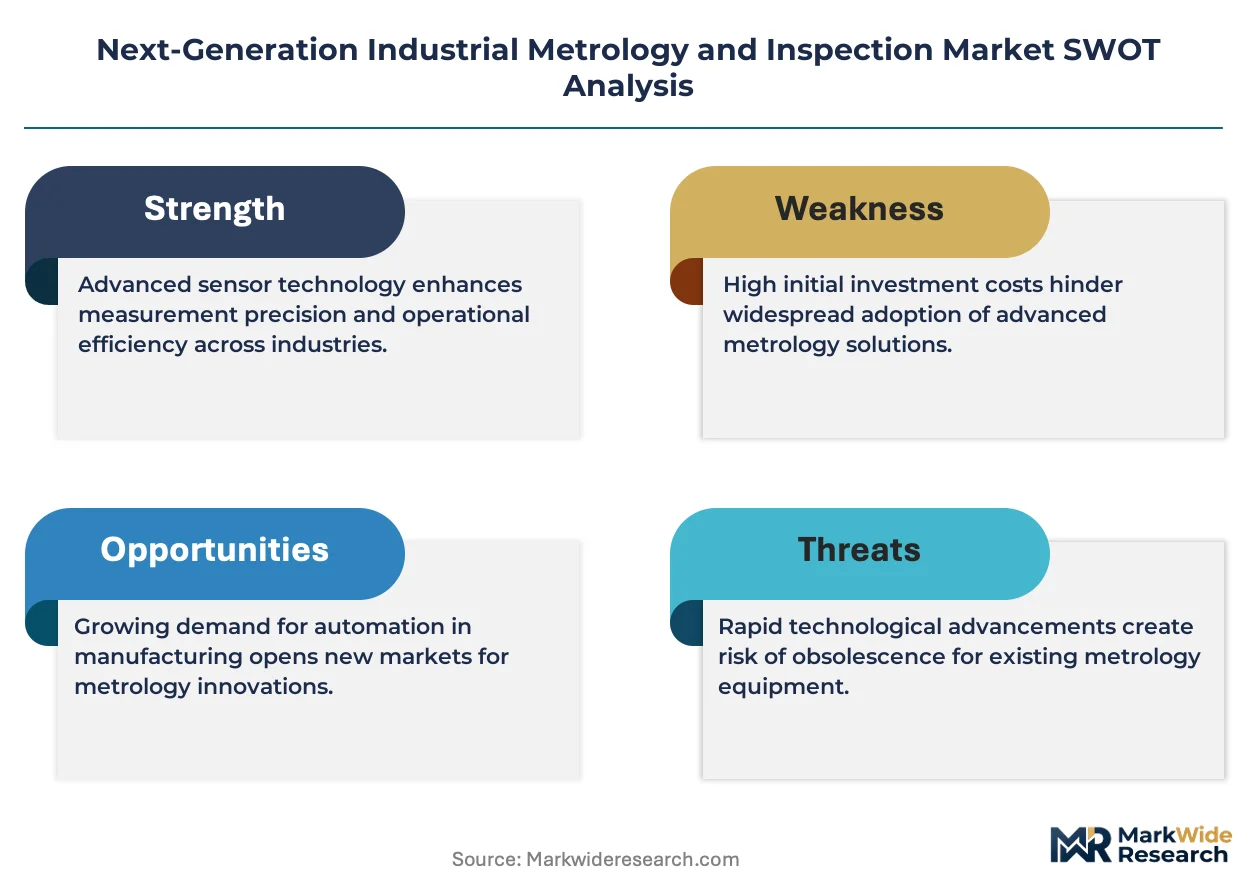
Next-generation industrial metrology and inspection encompasses dimensional verification, surface characterization, and defect detection using tactile probes, structured light, laser triangulation, and machine vision algorithms with accuracy thresholds reaching nanometer scales for semiconductor wafer qualification. Optical Measurement Systems lead installed base value due to non-contact speed advantages in medical device inspection, while 3D Scanning Devices represent the fastest-growing product category as aerospace manufacturers adopt portable laser trackers for in-situ airframe verification. Machine Vision technology captures expanding margin pools through AI-enhanced defect classification that reduces false-reject rates in electronics testing lines.
FDA quality system regulation and EU MDR conformity requirements compel medical device manufacturers to deploy validated automated measurement systems with full traceability chains. ISO 10360 calibration standards and Germany's national metrology institute (PTB) framework shape CMM accuracy certification protocols that govern cross-border equipment acceptance. Stakeholders must decide whether to build captive optical sensor competencies or partner with established subsystem suppliers as inspection data becomes integral to digital thread architectures.
Market Dynamics
Machine vision algorithms are compressing inspection cycle times while nanometer-scale accuracy requirements from semiconductor lithography are forcing metrology suppliers to merge optical and tactile sensing architectures into unified platforms.
Growth Catalysts
- EU AI Act compliance mandates:Medical device manufacturers in Germany and France must deploy validated automated measurement systems with full algorithmic traceability chains for Class IIb and III device qualification.
- Silicon carbide probe materials:Tactile measurement systems achieve thermal stability thresholds that sustain repeatability across temperature-varying production floors in automotive powertrain machining.
- Aerospace composite airframe tolerances:Boeing and Airbus tier-one suppliers in Wichita and Hamburg drive laser tracker deployments for in-situ verification of carbon-fiber wing box assemblies.
Market Restraints
- Encoder supply concentration:High-precision linear encoder manufacturing concentrates among Japanese and German component specialists, creating single-source vulnerability for CMM builders.
- Certified technician scarcity:ISO 10360 calibration competency requires 18-24 month training pipelines that lag equipment deployment schedules in emerging manufacturing clusters.
- Optical sensor input costs:Specialized CMOS sensors and laser diode arrays face price volatility from semiconductor foundry capacity allocation to consumer electronics.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentive corridors near Chennai and Bengaluru create demand for entry-level optical measurement systems with localized service networks.
- Battery cell dimensional verification:Lithium-ion gigafactories in Nevada and Thuringia require in-line CT scanning for electrode alignment validation at production speeds.
- AI-enhanced defect classification:Machine learning inference at the edge enables real-time false-reject reduction in electronics testing lines without cloud latency dependencies.
Industry Challenges
- Multi-sensor platform integration:Combining structured light, tactile probing, and chromatic confocal sensing demands firmware architectures that most legacy quality departments cannot maintain internally.
- Digital thread certification:Medical device suppliers struggle to align measurement data formats with FDA 21 CFR Part 11 electronic record requirements across heterogeneous equipment vintages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Industrial Metrology and Inspection Market |
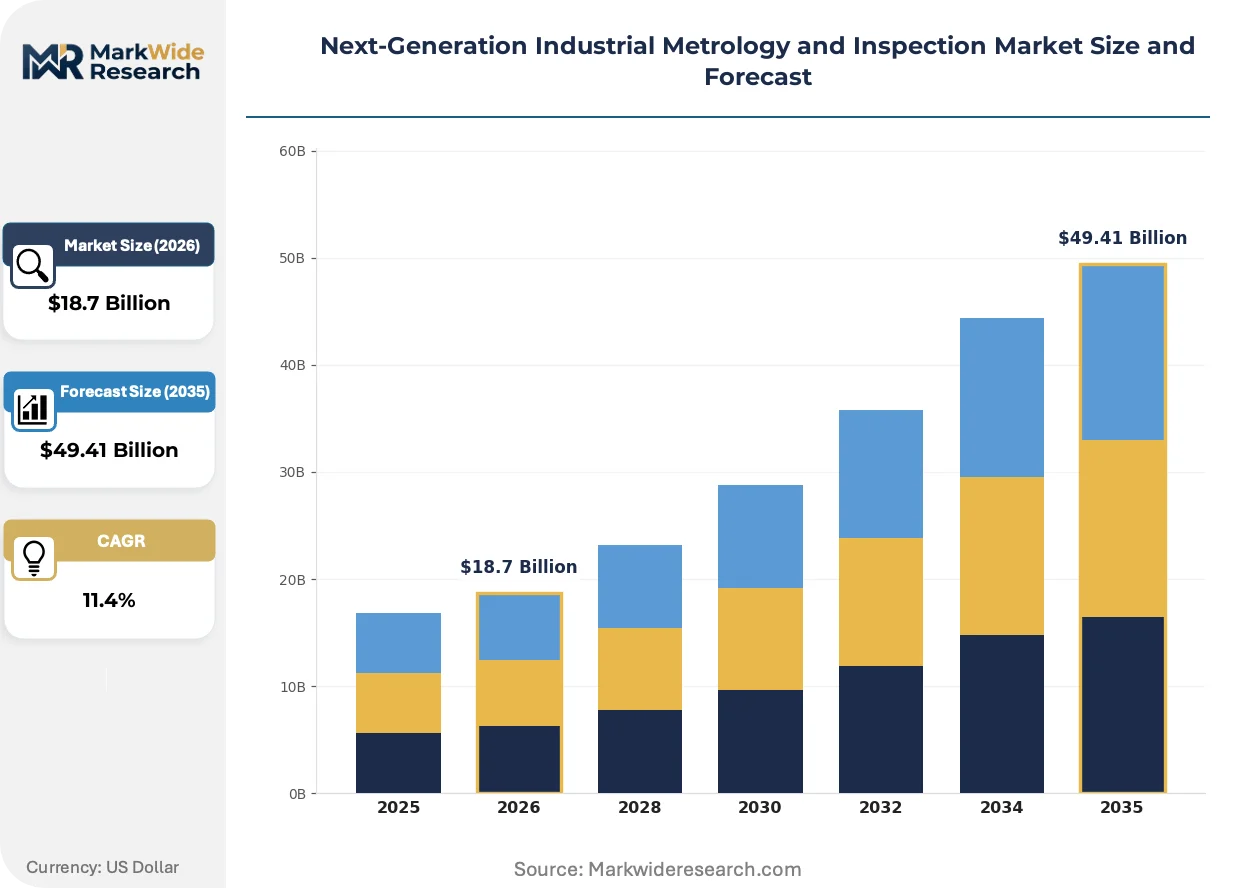
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coordinate Measuring Machines, Optical Measurement Systems, 3D Scanning Devices, Laser Inspection Tools Technology: Machine Vision, Automated Measurement Systems, Optical Sensors, Digital Height Gauges Application: Aerospace Manufacturing, Automotive Quality Control, Electronics Testing, Medical Device Inspection End User: OEMs, Tier-1 Suppliers, Manufacturing Plants, Research Institutions |
| Companies Covered | Hexagon AB, Renishaw plc, Carl Zeiss AG, FARO Technologies, Jenoptik AG, Nikon Corporation, KLA Corporation, Applied Materials, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Industrial Metrology and Inspection Market Shifts & Advancements
Inspection architectures are converging toward edge-computing nodes that process measurement data locally while feeding centralized quality management systems, collapsing the latency between detection and corrective action.
Chromatic confocal microscopy is absorbing displacement measurement tasks previously assigned to laser interferometry in semiconductor wafer qualification lines. TSMC and Samsung Foundry process engineers specify these sensors for sub-100nm thickness mapping of deposited films. The technology is absorbing market share from established optical methods by eliminating moving parts that degrade in cleanroom environments.
EU MDR conformity assessment procedures now mandate validated measurement uncertainty budgets for active implantable device dimensions. Notified bodies in Germany and the Netherlands reject submissions lacking ISO 14253-1-compliant inspection records. Medical device OEMs in Ireland and Switzerland respond by retrofitting CMMs with multi-sensor heads that generate compliant documentation packages automatically.
Capital equipment procurement committees now unbundle hardware acquisition from software licensing and calibration service contracts. Automotive tier-one suppliers in Stuttgart and Detroit negotiate three-year total-cost-of-ownership agreements rather than upfront purchase prices. This pattern is most visible among battery and powertrain manufacturers seeking operational expenditure predictability for capacity expansion planning.
Next-Generation Industrial Metrology and Inspection Market Segmentation
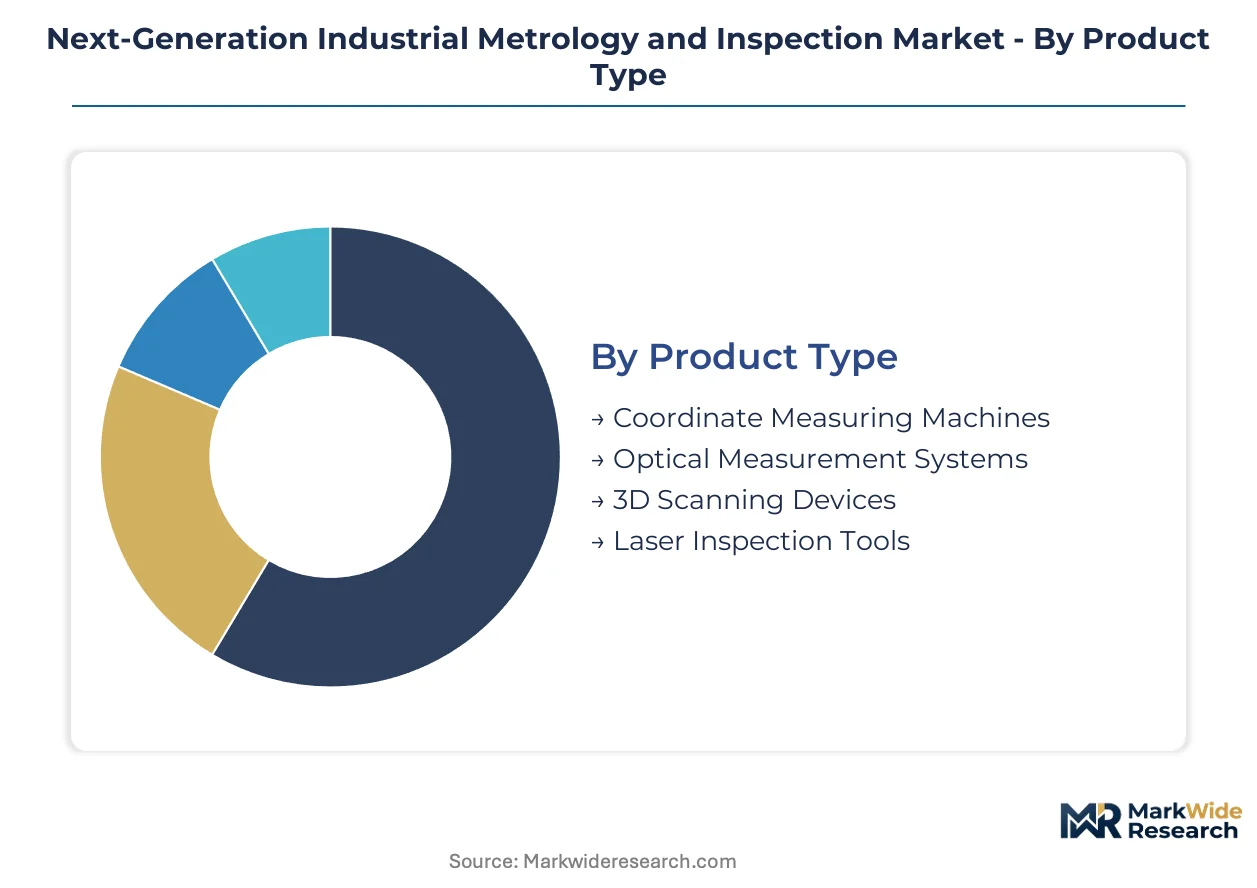
Segmentation in next-generation industrial metrology reveals how accuracy requirements and production environments dictate equipment selection. Aerospace and semiconductor end-users deploy fundamentally different architectures despite shared nanometer-scale ambitions.
Product Type:
Optical Measurement Systems command premium positioning through non-contact speed advantages, while 3D Scanning Devices capture volume growth from portable deployment needs.
- Coordinate Measuring Machines:Tactile probing platforms with granite base construction and air-bearing guidance achieve sub-micron repeatability in climate-controlled quality labs. Automotive powertrain manufacturers in Germany deploy these for crankshaft and camshaft dimensional verification where thermal stability overrides throughput speed.
- Optical Measurement Systems:Structured light and chromatic confocal architectures eliminate mechanical contact for fragile medical device components. FDA-regulated orthopedic implant suppliers in Ireland specify these systems for titanium femoral head surface finish validation where stylus damage risks scrapped inventory.
- 3D Scanning Devices:Portable laser trackers enable in-situ airframe verification without fixture transport to centralized labs.
- Laser Inspection Tools:Line-laser triangulation sensors integrate directly into machining centers for tool-wear compensation.
Today's leader: Optical Measurement Systems. Tomorrow's challenger: 3D Scanning Devices.
Technology:
Machine Vision algorithms compress cycle times through edge inference, while Automated Measurement Systems integrate multi-sensor fusion for complex geometry capture.
- Machine Vision:AI-enhanced defect classification running on GPU-accelerated edge nodes identifies solder joint voids in electronics testing lines at production speeds. TSMC backend facilities in Taiwan deploy these systems for wafer-level package inspection where cloud latency would stall throughput.
- Automated Measurement Systems:Robotic part handling combined with programmable probe changers enables lights-out operation in high-mix manufacturing. Medical device OEMs in Switzerland retrofit these for EU MDR-compliant batch record generation with full measurement uncertainty documentation.
- Optical Sensors:CMOS-based chromatic confocal probes map deposited film thickness without moving parts.
- Digital Height Gauges:Entry-level dimensional verification for shop-floor operators without CMM programming training.
Machine Vision expands most quickly in electronics. Automated Measurement Systems defend share in regulated medical device manufacturing.
Application:
Aerospace tolerances drive capital-intensive platform sales, while Electronics Testing generates volume through machine vision deployment at scale.
- Aerospace Manufacturing:Carbon-fiber composite airframes demand laser tracker verification of wing box assemblies where traditional fixtures distort under thermal load. Boeing tier-one suppliers in Wichita deploy in-situ measurement to eliminate transport damage risks on large structures.
- Automotive Quality Control:Powertrain machining lines integrate touch-trigger probes for real-time tool compensation. Battery gigafactories in Nevada specify CT scanning for electrode alignment validation where dimensional drift causes thermal runaway risks.
- Electronics Testing:High-volume PCB inspection with sub-10-micron placement accuracy requirements.
- Medical Device Inspection:Validated measurement systems with full algorithmic traceability for Class III device qualification.
Aerospace Manufacturing anchors premium equipment sales. Electronics Testing scales fastest through machine vision replication.
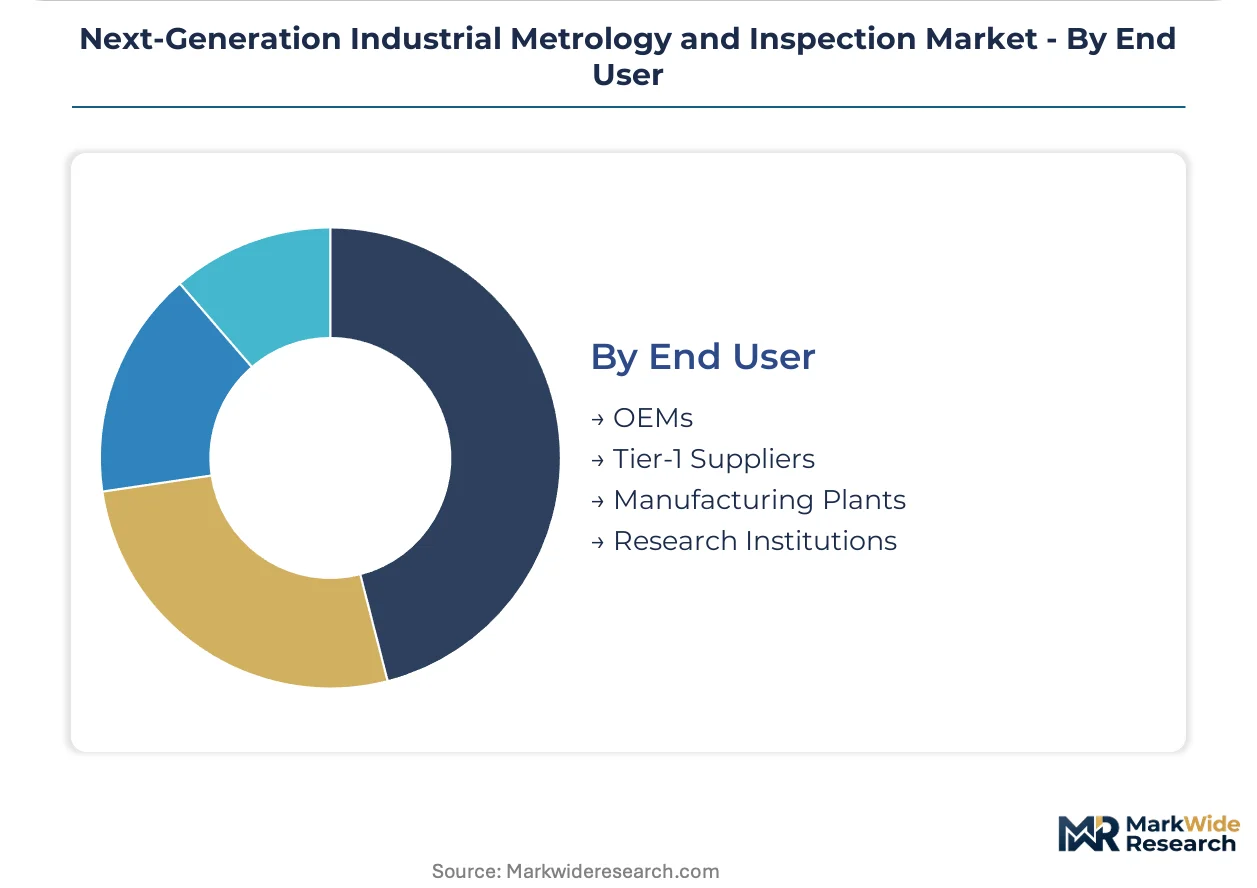
End User:
OEMs specify integrated digital thread architectures, while Tier-1 Suppliers prioritize equipment interoperability across heterogeneous customer requirements.
- OEMs:Airbus and medical device multinationals mandate validated measurement systems with direct MES integration for closed-loop quality control. These buyers negotiate multi-site enterprise agreements with centralized calibration management and software license pooling.
- Tier-1 Suppliers:Automotive and aerospace subcontractors in Stuttgart and Detroit deploy portable CMMs and laser trackers that relocate between customer programs. Equipment flexibility outweighs single-application optimization when contract durations compress.
- Manufacturing Plants:Captive quality departments with dedicated metrology technicians and climate-controlled labs.
- Research Institutions:National metrology institutes and university labs advancing interferometry and probe technology.
OEMs dictate platform standards. Tier-1 Suppliers drive portability and service contract flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters anchor technology diffusion for next-generation metrology systems. The United States and Japan concentrate aerospace and semiconductor demand respectively. National metrology institutes in these countries validate equipment calibration protocols that govern cross-border acceptance.
Germany
Automotive powertrain manufacturers and medical device suppliers drive coordinate measuring machine deployments. The EU AI Act and MDR conformity requirements compel validated automated measurement systems with full algorithmic traceability. Stuttgart and Hamburg host tier-one aerospace suppliers deploying laser trackers for carbon-fiber airframe verification.
United States
Boeing tier-one suppliers and battery gigafactories generate demand for portable 3D scanning and CT inspection systems. FDA quality system regulation mandates validated measurement systems with full traceability chains for Class III medical devices. Wichita's aerospace cluster deploys in-situ laser tracker verification to eliminate transport damage risks on large wing structures.
Japan
Semiconductor lithography equipment manufacturers impose nanometer-scale accuracy requirements on metrology suppliers. METI standards and JIS calibration frameworks shape equipment certification protocols. Tokyo-Yokohama and Osaka-Kobe manufacturing corridors concentrate encoder and probe component specialists.
China
Electronics contract manufacturers and automotive OEMs scale machine vision deployment for high-volume inspection lines. GB standards and MIIT industrial upgrading programs accelerate automated measurement system adoption. Yangtze River Delta and Pearl River Delta clusters house backend semiconductor facilities specifying sub-100nm thickness mapping sensors.
India
Electronics manufacturing incentive corridors near Chennai and Bengaluru create demand for entry-level optical measurement systems. The PLI scheme for semiconductor and component manufacturing drives localized service network requirements. Tamil Nadu and Karnataka host contract manufacturers retrofitting quality labs for export compliance.
Next-Generation Industrial Metrology and Inspection Market Competitive Landscape
Software-hardware integration dominates the current landscape as suppliers merge optical and tactile sensing architectures into unified platforms. The vendor base concentrates among European precision engineering groups and Japanese component specialists. Two strategic archetypes prevail: integrated platform providers bundling multi-sensor heads with proprietary software ecosystems, and component specialists supplying encoders, probes, and optical subsystems to third-party equipment builders. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire AI-enhanced defect classification capabilities and chromatic confocal microscopy patents.
Among European integrated platform providers, Hexagon AB and Carl Zeiss AG exemplify the software-hardware bundling archetype, while Renishaw plc occupies a position within the component specialist tier. Hexagon AB represents the multi-sensor CMM platform approach through its captive software ecosystems. Carl Zeiss AG exemplifies premium optical measurement positioning. Renishaw plc anchors the encoder and probe technology segment that sustains measurement repeatability across equipment vintages. These three firms collectively illustrate how European precision engineering heritage translates into differentiated competitive positioning against Asian component suppliers and American portable scanning specialists.
| Leading Market Players |
|---|
| Hexagon AB |
| Renishaw plc |
| Carl Zeiss AG |
| FARO Technologies |
| Jenoptik AG |
| Nikon Corporation |
| KLA Corporation |
| Applied Materials |
| Keyence Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 10360-validated coordinate measuring machines and uncertified shop-floor gauges manifests in both pricing power and supply chain sourcing patterns. Premium-tier equipment commands captive service contracts and multi-year calibration agreements, while economy-tier optical systems flow through distributor networks with minimal aftermarket attachment.
Pricing Analysis
Specialized CMOS sensors and laser diode arrays pass through semiconductor foundry cost volatility to end-equipment pricing, compressing margins on mid-tier optical measurement systems. Three-tier pricing structure across premium, standard, and economy levels separates multi-sensor CMM platforms with algorithmic traceability from portable laser trackers and entry-level digital height gauges. Pricing pressure stems from automotive OEM procurement committees unbundling hardware from software licensing and demanding operational expenditure predictability. Tier-1 suppliers in Stuttgart and Detroit exhibit highest price sensitivity, while medical device OEMs in Ireland and Switzerland absorb premium positioning for FDA-validated systems.
Supply Chain Analysis
Refurbished probe heads and recalibrated encoder subsystems flow back through authorized service centers in Germany and Japan, extending equipment lifecycles and constraining new-unit demand. High-precision linear encoder manufacturing concentrates among Japanese and German component specialists, creating single-source vulnerability for CMM builders in the United States and China. Silicon carbide probe materials and chromatic confocal optical subsystems draw from semiconductor and precision optics supply bases respectively. Tariff exposure on Chinese-sourced CMOS sensors threatens cost structures for machine vision system assemblers. Distribution runs through direct enterprise sales for OEM accounts and regional distributor networks for Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in next-generation industrial metrology hinges on software licensing attach rates rising above hardware depreciation curves, with premium-tier shift toward validated measurement systems for EU MDR and FDA compliance accelerating recurring revenue pools.
For Market Incumbents: Lock in multi-sensor platform dominance by acquiring chromatic confocal microscopy patents and embedding AI-enhanced defect classification into captive software ecosystems. Deepen backward integration into encoder production to offset Japanese component specialist concentration risk. Defend against portable 3D scanning specialists by expanding laser tracker service contract coverage in aerospace clusters. For New Entrants and Emerging Players: Edge-computing inference nodes for real-time false-reject reduction represent the most penetrable white-space target, particularly in electronics contract manufacturing corridors near Chennai and Bengaluru. Battery gigafactories in Nevada and Thuringia present second-entry opportunity for CT scanning specialists with electrode alignment validation expertise. Go-to-market through equipment-as-a-service models lowers capital barriers for emerging manufacturing clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists possessing captive probe or encoder technology that sustains measurement repeatability across equipment vintages. Long-term viability favors firms with software-hardware integration depth and validated algorithmic traceability for regulated medical device manufacturing. Watch FDA 21 CFR Part 11 enforcement intensity and EU AI Act implementation timelines as inflection indicators for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Platform Integration | Unified tactile-optical architectures capture aerospace composite verification contracts from Boeing and Airbus tier-one suppliers. |
| AI-Enhanced Defect Classification | Machine learning inference at the edge reduces false-reject rates in TSMC backend facilities without cloud latency dependencies. |
| Calibration Service Network Expansion | Localized ISO 10360 competency addresses 18-24 month technician training gaps in emerging manufacturing clusters. |
| Backward Integration into Encoders | In-house linear encoder production mitigates single-source vulnerability from Japanese and German component specialists. |
| Equipment-as-a-Service Launch | Operational expenditure models align with automotive procurement committee demands for three-year total-cost-of-ownership agreements. |
Research Methodology
Multiple input streams — primary interviews with metrology equipment executives, quality engineering directors at automotive OEMs, and biomedical engineers at FDA-regulated device manufacturers; secondary validation through SEC filings of precision engineering groups, ISO calibration standard documentation, and EU MDR conformity assessment records; plus customs data on encoder and probe component trade flows — were reconciled through bottom-up equipment deployment tracking and top-down market sizing across product type, technology, application, and end-user dimensions.
Data-stream reconciliation anchored volume and value outputs to installed base estimates by geography and replacement cycle analysis, with segmentation modeling across coordinate measuring machines, optical measurement systems, 3D scanning devices, and laser inspection tools by technology tier. CAGRs were derived from equipment procurement pipeline analysis and regulatory compliance-driven replacement elasticity. Semiconductor lithography equipment capex disclosures and aerospace composite airframe production schedules provided industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and continued precision manufacturing cluster concentration; deviation in EU AI Act implementation timelines or FDA 21 CFR Part 11 audit frequency would shift replacement cycle assumptions. Practitioners should monitor notified body capacity constraints in Germany and the Netherlands and semiconductor foundry capacity allocation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Volte Testing Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Test Benches Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market