
 Stress Test Equipment Market | 2026-2036
Stress Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Test Equipment Market Analytics
REACH compliance in Europe is expanding the cost-of-entry calculus for stress test equipment manufacturers seeking CE marking. GE Healthcare leverages its installed base of imaging systems to bundle cardiac diagnostics workflows. Koninklijke Philips N.V. anchors its position through integrated software analysis platforms that span hospital and ambulatory settings. Schiller AG specializes in compact ergometer designs that occupy a distinct niche in European diagnostic centers.
Stress test equipment comprises electrocardiographic monitoring systems, programmable ergometers, and automated blood pressure modules that measure cardiac response under controlled physical exertion, typically operating at workloads calibrated in watts with 12-lead signal acquisition at sampling rates exceeding 500 Hz. Cardiac testing systems dominate the product landscape due to their embedded role in coronary artery disease protocols, while wireless monitoring represents the fastest-expanding technology segment as telemetry-enabled units displace tethered configurations in outpatient settings. Exercise stress test systems sustain stable demand from fitness facilities seeking clinical-grade prevention tools.
The FDA governs 510(k) clearance pathways for exercise ECG devices in the United States, while the EU Medical Device Regulation mandates notified body involvement for Class IIa cardiac monitors entering European markets. Japan's PMDA enforces Good Quality Management System Practice standards that extend approval timelines but elevate product reliability benchmarks. Stakeholders must weigh regulatory capital requirements against the margin compression inherent in commoditized 12-lead ECG hardware.
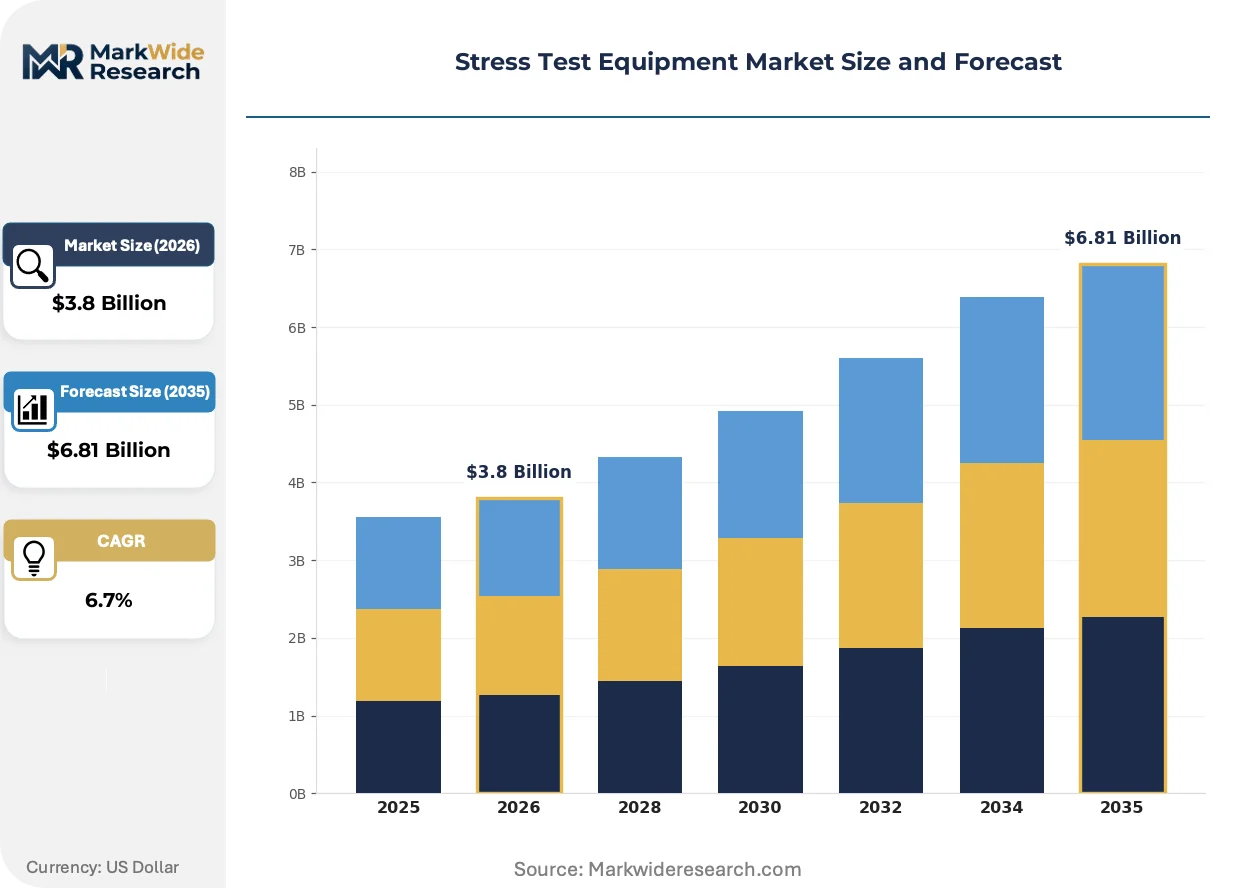
Market Dynamics
Wireless telemetry is compressing the replacement cycle for tethered cardiac monitoring systems as hospitals prioritize patient mobility and reduced bed occupancy times.
Growth Catalysts
- Japan's PMDA GQMS standards:Elevated reliability benchmarks create competitive moats for manufacturers that invest in quality infrastructure, filtering out marginal suppliers.
- Ambulatory surgical centers:Expansion of outpatient cardiac diagnostics drives demand for compact, transportable ergometer systems with integrated telemetry.
- AI-enabled ECG analysis:Machine learning algorithms embedded in stress test platforms accelerate diagnostic throughput and reduce specialist interpretation burden.
Market Restraints
- Copper and rare earth magnet costs:Input volatility for electromagnetic ergometer components compresses hardware margins and complicates long-term pricing contracts.
- Single-source telemetry module suppliers:Concentration in Nordic semiconductor fabrication creates vulnerability for wireless-enabled system manufacturers.
- EU MDR Class IIa notified body bottlenecks:Extended CE marking timelines delay product launches and freeze R&D capital for eighteen to thirty months.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Tier-2 and Tier-3 city hospital upgrades under the Ayushman Bharat scheme create first-mover advantages for portable stress test systems.
- Remote patient monitoring reimbursement codes:CMS physician fee schedule updates in the United States enable home-based cardiac stress telemetry billing.
- Cloud-native software platforms:Convergence of edge computing and HIPAA-compliant data architectures permits subscription-based diagnostic workflow monetization.
Industry Challenges
- Biomedical engineering talent scarcity:Shortage of specialists capable of integrating 12-lead analog signal processing with wireless transmission protocols extends development cycles.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for Software as a Medical Device require iterative regulatory submissions that consume technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Test Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Testing Systems, Exercise Stress Test Systems, Ultra-Fast Systems, Clinical Testing Equipment End User: Hospitals, Diagnostic Centers, Home Healthcare, Fitness Facilities Technology: Ergometer, 12-Lead ECG, Wireless Monitoring, Software Analysis Application: Cardiology Assessments, Pre-Operative Evaluations, Sports Medicine, Health Screening |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Schiller AG, Nihon Kohden Corporation, Meditech Equipment, Contec Medical Systems, BPL Medical Technologies, COSMED Srl, MGC Diagnostics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Test Equipment Market Evolving Landscape
Digital biomarker extraction and edge computing architectures are redefining what stress test equipment captures, moving beyond heart rate variability toward multi-parameter physiological signatures.
Photoplethysmography-based oxygen saturation monitoring is integrating with traditional ECG stress platforms to deliver continuous SpO2 trending during exertion protocols. Cardiac rehabilitation departments in German university hospitals are piloting these multimodal configurations for heart failure patient stratification. The technology is integrating respiratory and metabolic data streams into unified diagnostic dashboards that compress specialist review time by consolidating previously separate monitoring silos.
REACH SVHC candidate list expansion is forcing reformulation of cable jacketing and electrode adhesive compounds used in European-market devices. Manufacturers with pre-2021 product registrations face retrospective compliance obligations that require supply chain requalification. Cardiac monitor vendors serving the EU are responding by accelerating partnerships with bio-based polymer suppliers to secure alternative material pathways before sunset dates crystallize.
Subscription-based equipment-as-a-service contracts are displacing capital purchase models among US hospital networks facing constrained CAPEX budgets. Third-party financing entities now intermediate stress test system procurement, unbundling hardware, software, and maintenance into monthly operational expenditures. This restructuring is most visible in the Southeast and Midwest regions where independent cardiac catheterization labs consolidate into regional networks with centralized equipment standardization committees.
Stress Test Equipment Market Segmentation
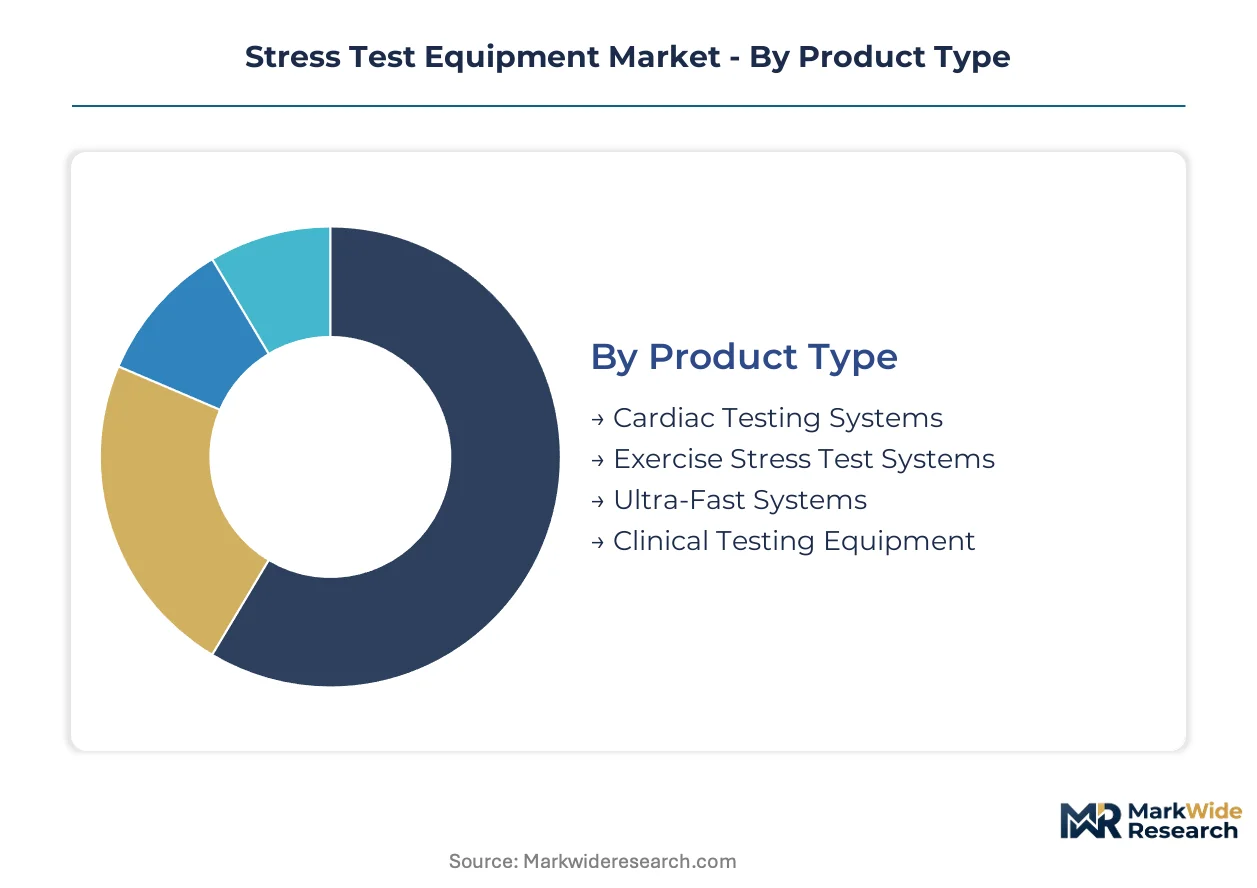
Segmentation in stress test equipment reveals divergent engineering requirements across clinical versus consumer-grade applications. Wireless telemetry and AI-embedded software are collapsing traditional boundaries between hospital and ambulatory deployment models.
Product Type:
Technology specifications define performance thresholds and regulatory classification pathways for each product category.
- Cardiac Testing Systems:These integrate programmable ergometers with 12-lead ECG acquisition at sampling rates exceeding 500 Hz for coronary artery disease protocols. Demand concentrates in United States hospital cardiac catheterization labs where bundled imaging workflows justify premium procurement.
- Exercise Stress Test Systems:Compact ergometer platforms calibrated in watts for controlled physical exertion measurement. German diagnostic centers favor these configurations for outpatient prevention programs under statutory health insurance reimbursement frameworks.
- Ultra-Fast Systems:High-throughput units designed for high-volume screening environments with rapid patient turnover protocols.
- Clinical Testing Equipment:General-purpose diagnostic hardware serving multi-specialty hospital departments with modular upgrade paths.
Cardiac Testing Systems lead on scale; Ultra-Fast Systems lead on momentum.
End User:
Procurement authority and reimbursement codes shape equipment specification requirements across care settings.
- Hospitals:Integrated enterprise systems with EMR connectivity and centralized maintenance contracts. United States health networks prioritize wireless telemetry to reduce bed occupancy times and improve patient throughput metrics.
- Diagnostic Centers:Standalone facilities requiring compact footprints and rapid installation cycles. Japan's PMDA GQMS standards elevate reliability benchmarks that filter equipment choices toward established manufacturers with quality infrastructure investments.
- Home Healthcare:Portable devices enabling remote cardiac monitoring with simplified operation protocols.
- Fitness Facilities:Clinical-grade prevention tools for high-end wellness centers seeking differentiation through medical credibility.
Hospitals dominate procurement volume; Home Healthcare shows steepest expansion trajectory.
Technology:
Core measurement modalities determine signal fidelity, patient mobility, and software integration depth.
- Ergometer:Electromagnetic and mechanical workload generators with watt-precision calibration. Copper and rare earth magnet input costs compress hardware margins and complicate long-term pricing contracts for manufacturers.
- 12-Lead ECG:Analog signal processing hardware with embedded amplification and noise filtration. FDA 510(k) predicate device drift for Software as a Medical Device creates iterative regulatory submission burdens for hardware-software integrated systems.
- Wireless Monitoring:Telemetry-enabled units displacing tethered configurations in outpatient settings. Nordic semiconductor fabrication concentration creates supply vulnerability for system manufacturers dependent on single-source radio module suppliers.
- Software Analysis:Machine learning algorithms for automated ECG interpretation and diagnostic workflow acceleration.
12-Lead ECG anchors installed base; Wireless Monitoring is gaining share fastest.
Application:
Clinical indication determines protocol duration, parameter complexity, and specialist interpretation requirements.
- Cardiology Assessments:Comprehensive coronary artery disease evaluation with full 12-lead acquisition and blood pressure trending. German university hospitals pilot multimodal configurations integrating photoplethysmography-based SpO2 monitoring for heart failure patient stratification.
- Pre-Operative Evaluations:Risk stratification protocols for non-cardiac surgery candidates requiring cardiac clearance documentation.
- Sports Medicine:Athletic performance optimization and return-to-play clearance for professional and collegiate programs.
- Health Screening:Preventive assessment protocols in corporate wellness and insurance medical examination contexts.
Cardiology Assessments command premium pricing; Health Screening shows strongest volume elasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Massachusetts, Bavaria, and Kanagawa Prefecture anchor regional innovation capacity for cardiac diagnostic equipment.
United States
Hospital network consolidation in the Southeast and Midwest drives standardized procurement of wireless telemetry systems. CMS physician fee schedule updates enable home-based cardiac stress telemetry billing codes. The Greater Boston cluster hosts concentrated FDA premarket review expertise that accelerates 510(k) clearance pathways for software-integrated devices.
Germany
Statutory health insurance reimbursement frameworks sustain outpatient prevention program demand for compact ergometer platforms. REACH SVHC candidate list expansion forces reformulation of cable jacketing compounds for CE-marked devices. The Baden-Württemberg medical technology corridor houses diagnostic center networks piloting multimodal SpO2-ECG configurations.
Japan
Aging demographics and coronary artery disease prevalence elevate hospital procurement of high-reliability cardiac testing systems. PMDA Good Quality Management System Practice standards extend approval timelines but filter equipment choices toward quality-infrastructure investments. The Kanagawa-Tokyo medical device cluster concentrates PMDA regulatory consulting capacity and specialist interpretation services.
India
Tier-2 and Tier-3 city hospital upgrades under Ayushman Bharat create first-mover opportunities for portable stress test systems. CDSCO medical device rules harmonization with global standards accelerates import substitution for diagnostic hardware. The Karnataka medical technology corridor in Bangalore hosts emerging domestic manufacturers targeting cost-optimized ergometer production.
China
Cardiovascular disease burden and hospital infrastructure expansion drive demand for clinical-grade stress test equipment. NMPA medical device registration requirements for Class II cardiac monitors mandate domestic clinical trial data. The Yangtze River Delta cluster concentrates contract manufacturing capacity for electromagnetic ergometer components and wireless telemetry modules.
Stress Test Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between imaging-system incumbents bundling cardiac workflows and compact-equipment specialists occupying diagnostic center niches. Three archetypes dominate: integrated platform providers, ergometer-focused manufacturers, and regional cost-optimized suppliers. Competitive moves concentrate on software analysis platform integration and equipment-as-a-service contract restructuring.
Among diversified healthcare technology conglomerates, GE Healthcare and Koninklijke Philips N.V. represent integrated platform providers that span hospital and ambulatory settings. Schiller AG exemplifies the specialized European manufacturer archetype with focused ergometer expertise. These three companies anchor the competitive structure, with GE Healthcare and Philips leveraging installed imaging bases for workflow bundling while Schiller occupies distinct compact-design positioning in European diagnostic centers.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Schiller AG |
| Nihon Kohden Corporation |
| Meditech Equipment |
| Contec Medical Systems |
| BPL Medical Technologies |
| COSMED Srl |
| MGC Diagnostics Corporation |
| Others |
Value Network & Pricing Analysis
Third-party financing entities rolling up hospital network procurement contracts are reshaping both supply chain sourcing patterns and pricing discipline in stress test equipment markets. Their equipment-as-a-service restructuring concentrates buyer power and compresses vendor margins across wireless telemetry and ergometer categories.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes capital purchase models from subscription-based operational expenditure structures. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, wireless telemetry integration depth, and after-sales service bundling. Pricing pressure stems from copper and rare earth magnet cost volatility in electromagnetic ergometer components. Diagnostic centers in Germany and Japan show least price sensitivity due to statutory reimbursement frameworks, while India's Tier-2 hospital upgrades under Ayushman Bharat concentrate volume demand at economy tiers.
Supply Chain Analysis
Freight cost escalation for electromagnetic ergometer components from China and precision ECG signal processing modules from Taiwan is elevating landed costs for North American and European system integrators. Rare earth magnet sourcing draws from Chinese processing facilities, while Nordic semiconductor fabrication concentrates telemetry radio module supply. Single-source vulnerability in wireless chipset supply creates procurement risk for manufacturers dependent on Nordic fabrication capacity. Distribution runs through third-party financing intermediaries and regional hospital network standardization committees rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in stress test equipment hinges on software-as-a-service monetization offsetting hardware commoditization, with cloud-native diagnostic platforms capturing recurring revenue streams from hospital network subscribers.
For Market Incumbents: Deploy software analysis platform integration to defend against pure-play AI-ECG entrants eroding interpretation service margins. Deepen backward integration into electromagnetic ergometer component production to offset copper and rare earth magnet cost volatility. Secure CE marking pathway acceleration through pre-submission engagement with EU notified bodies before MDR Class IIa bottlenecks extend. For New Entrants and Emerging Players: Enter via India's Tier-2 and Tier-3 city hospital infrastructure upgrades under Ayushman Bharat, where portable stress test system penetration remains nascent and procurement authority is decentralized. Target diagnostic center networks in Southeast US regions where independent cardiac catheterization labs are consolidating and seeking cost-optimized telemetry solutions. Pursue GPO contract positioning through equipment-as-a-service financing partnerships rather than capital sales cycles. For Investors and Strategic Acquirers: Imaging-system conglomerates are the most active acquirer in this space, seeking cardiac workflow bundling capabilities to complement installed radiology bases. Long-term viability centers on software-enabled diagnostic throughput differentiation rather than hardware scale economies. Watch FDA Software as a Medical Device predicate device drift resolution as inflection indicator for regulatory capital efficiency and platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Class IIa notified body engagement reduces eighteen-to-thirty month approval freezes for wireless cardiac monitors. |
| Hospital System Partnership | Southeast US network consolidation creates standardized procurement committees favoring telemetry-integrated enterprise systems. |
| Software Companion Development | Cloud-native HIPAA-compliant architectures enable subscription-based diagnostic workflow monetization beyond hardware margins. |
| Reimbursement Strategy | CMS physician fee schedule remote monitoring codes unlock home-based cardiac stress telemetry billing in United States markets. |
| Backward Integration | In-house electromagnetic ergometer production mitigates copper and rare earth magnet input cost volatility compression. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and cardiac catheterization lab administrators grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU MDR notified body registers, CMS physician fee schedule updates, and hospital procurement database extracts. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis triangulated market sizing across product categories.
Segment-level projections for cardiac testing systems, exercise stress test platforms, and wireless monitoring technologies were generated across the analysis window. Modeled dimensions included ergometer watt-precision calibration tier, 12-lead ECG sampling rate threshold, telemetry integration depth, and end-user facility type. CAGRs were derived from equipment replacement cycle compression rates and ambulatory surgical center expansion trajectories. Forecast inputs incorporated PMDA GQMS approval timeline distributions and REACH SVHC compliance cost pass-through assumptions.
Inputs from FDA premarket notification databases and EU notified body capacity registers were available through the study window; gaps in real-time hospital network CAPEX commitment disclosures introduce uncertainty bands around near-term procurement volume assumptions. Forecasts reflect documented assumptions regarding wireless telemetry adoption curves and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Production Testing Market
Test and Measurement
DSL Tester Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Sound Meter Market
Test and Measurement
Digital Moisture Meters Market