
 Quantum Key Distribution System Performance and Security Test Equipment Market | 2026-2036
Quantum Key Distribution System Performance and Security Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Key Distribution System Performance and Security Test Equipment Market Insights
Silicon photonics is recalibrating device economics for QKD test equipment by displacing discrete fiber-coupled components with integrated optical circuits. Keysight Technologies leverages in-house photonic integration to compress form factors for portable security analyzers. ID Quantique anchors European supply through Geneva-based manufacturing of single-photon detectors. Toshiba competes in Asia-Pacific deployment programs with cryogenically cooled receiver modules.
Quantum Key Distribution System Performance and Security Test Equipment comprises calibrated instrumentation that validates quantum channel fidelity, measures quantum bit error rates, and verifies information-theoretic security proofs across fiber and free-space links. Optical Test Instruments dominate current revenue as carriers validate deployed QKD links against ITU-T standards. Discrete Variable QKD sustains the largest installed base, though Twin-Field QKD commands premium pricing for metropolitan distances exceeding 500 kilometers. Federal Agencies represent the fastest-growing end user category as sovereign quantum communication programs expand procurement budgets.
NIST, ETSI, and the ITU-T collectively shape product requirements through evolving standards for quantum random number entropy certification and QKD security proofs. The EU's Cybersecurity Act and national quantum communication infrastructure programs in Germany, France, and the Netherlands mandate certified test equipment for sovereign network acceptance. Stakeholders must monitor standardization convergence between ETSI QKD specifications and NIST post-quantum migration frameworks to anticipate interoperability testing obligations.
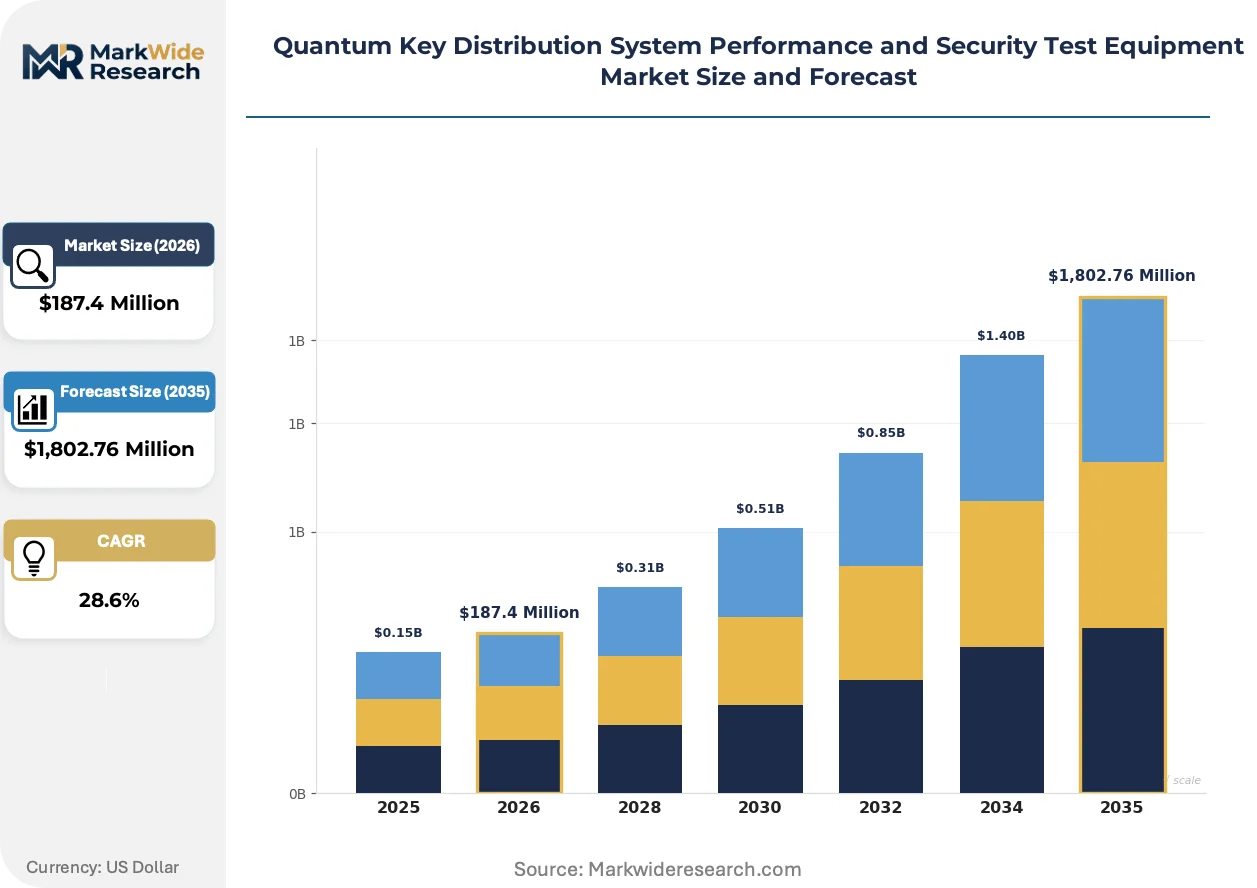
Market Dynamics
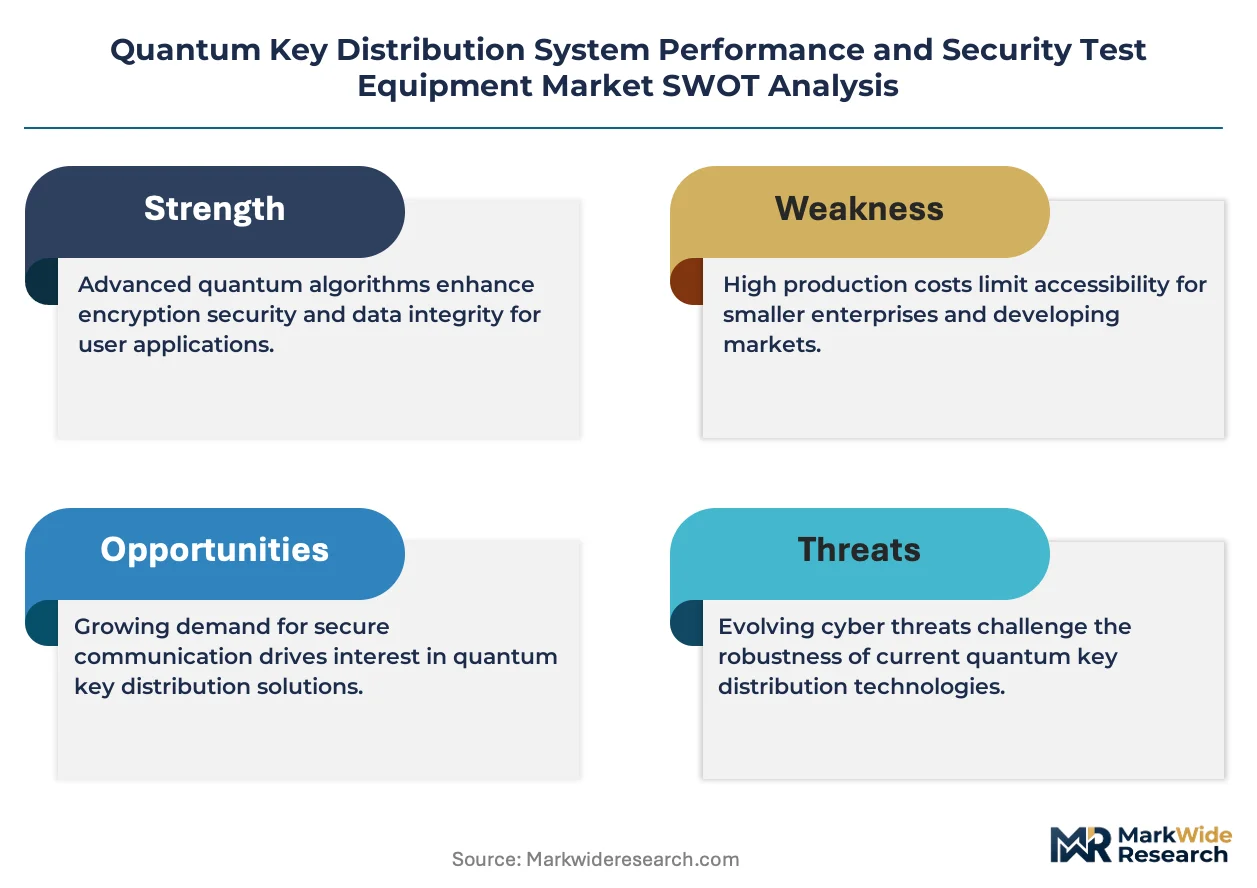
Silicon photonics integration is compressing device economics while NIST's post-quantum cryptography migration compresses vendor certification cycles, forcing test equipment makers to accelerate hardware-software co-development.
Growth Catalysts
- ETSI QKD Specifications:The European Telecommunications Standards Institute's evolving security proof frameworks mandate certified instrumentation for sovereign network acceptance across EU member states.
- NATO Communication Networks:Allied government procurement programs are accelerating validation requirements for quantum-secured fiber links between defense installations.
- Twin-Field QKD:This protocol variant commands premium deployment for metropolitan distances exceeding 500 kilometers, expanding addressable test scenarios.
Market Restraints
- Single-photon detector supply:Cryogenic cooling requirements and limited manufacturing capacity in European detector foundries create input bottlenecks.
- ITU-T standard fragmentation:Divergent national implementations of optical channel testing protocols force redundant certification investments.
- Classical encryption substitution:Post-quantum cryptographic algorithms without quantum hardware threaten to displace QKD in cost-sensitive applications.
Strategic Opportunities
- Free-space QKD testing:Satellite-to-ground link validation represents underpenetrated application territory with defense and space agency budgets.
- Germany's quantum cluster:The Munich-Stuttgart corridor concentrates R&D funding and sovereign infrastructure procurement.
- Silicon photonics foundry access:Fabless test equipment vendors can now access commercial photonic integrated circuit fabrication.
Industry Challenges
- Quantum optics talent scarcity:Specialized photonics engineering and cryogenic system design skills command premium compensation and extended hiring timelines.
- NIST certification compression:Accelerated post-quantum migration timelines force parallel hardware development and documentation submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Key Distribution System Performance and Security Test Equipment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Test Instruments, Photon Detectors, Synchronization Units, Security Analyzers, Key Management Modules Technology: Discrete Variable QKD, Continuous Variable QKD, Measurement Device Independent QKD, Twin-Field QKD, Device Independent QKD Application: Telecom Network Security, Data Center Protection, Government Communication, Financial Transactions, Critical Infrastructure Safeguarding End User: Telecommunication Providers, Data Center Operators, Federal Agencies, Banking Institutions, Cybersecurity Firms |
| Companies Covered | Keysight Technologies, ID Quantique, Rohde & Schwarz, Anritsu, VIAVI Solutions, Toshiba, QuantumCTek, QuintessenceLabs, SK Telecom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Key Distribution System Performance and Security Test Equipment Market Trends and Innovations
Instrumentation architecture is pivoting from discrete benchtop systems toward integrated photonic platforms, while regulatory convergence between NIST and ETSI frameworks reshapes product roadmaps.
Silicon photonics is modularizing test equipment architecture by embedding fiber couplers, beam splitters, and phase modulators onto single substrates. Defense procurement offices in NATO member states are specifying portable analyzers with compressed form factors. This integration is modularizing supply chains, enabling fabless vendors to compete without captive optical component manufacturing.
The EU Cybersecurity Act now mandates certified test equipment for quantum communication infrastructure acceptance in Germany, France, and the Netherlands. National regulators are transposing ETSI QKD specifications into binding procurement requirements. Equipment vendors are responding with dual-track certification programs targeting both European sovereign networks and NIST-aligned federal systems.
Carrier procurement teams are unbundling after-sales calibration services from initial hardware acquisition. Telecommunication operators in Asia-Pacific markets now contract third-party metrology labs for annual quantum channel validation. This service separation is most visible in Japan, where METI-funded quantum network pilots specify independent security auditing.
Quantum Key Distribution System Performance and Security Test Equipment Market Segmentation
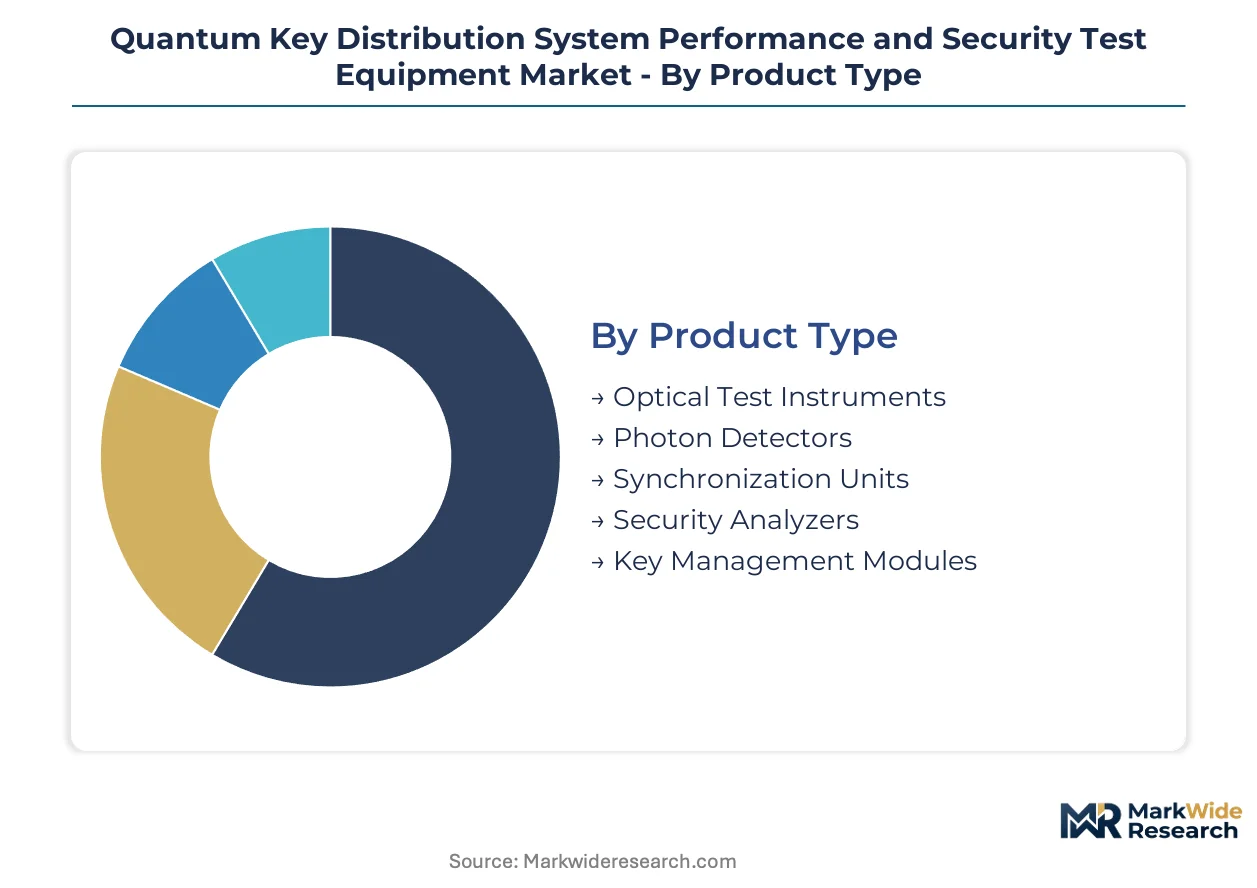
Segmentation in QKD test equipment reveals how capital allocation, technical complexity, and regulatory pressure distribute across distinct procurement profiles. Equipment buyers face fundamentally different validation requirements depending on whether they secure metropolitan fiber links, free-space satellite channels, or sovereign government networks.
Product Type:
Capital intensity varies sharply across product categories, with cryogenic photon detection systems demanding the highest upfront equipment investment while software-centric security analyzers require minimal hardware infrastructure.
- Optical Test Instruments:These systems calibrate quantum channel fidelity against ITU-T standards using integrated photonic circuits for beam splitting and phase modulation. Carrier procurement teams in Germany's quantum cluster around Munich validate deployed fiber links through these instruments, driven by ETSI-mandated certification requirements for sovereign network acceptance.
- Photon Detectors:Cryogenically cooled single-photon avalanche diodes and superconducting nanowire detectors form the measurement backbone of any QKD validation setup. Limited manufacturing capacity in European foundries creates persistent supply bottlenecks, forcing extended lead times for defense procurement offices across NATO member states.
- Synchronization Units:Precision timing distribution modules maintain coherence across quantum channel endpoints.
- Security Analyzers:Portable instrumentation validates information-theoretic security proofs and quantum bit error rates.
- Key Management Modules:Hardware security modules handle post-processing and key distillation protocols.
Most installed capacity flows through Optical Test Instruments. Expansion is steepest in Security Analyzers as portable form factors penetrate defense field operations.
Technology:
Application requirements determine which protocol variants command procurement budgets, with metropolitan distance specifications and threat models driving technology selection.
- Discrete Variable QKD:Polarization or phase-encoded single-photon protocols constitute the dominant installed base across commercial deployments. Telecom operators in Japan's METI-funded quantum network pilots specify these systems for metropolitan fiber validation, constrained by detector efficiency limitations at extended distances.
- Twin-Field QKD:Phase-matching protocols enable metropolitan distances exceeding 500 kilometers through single-photon interference without trusted nodes. China's quantum communication infrastructure programs deploy these systems for inter-city backbone links, commanding premium pricing for test equipment capable of validating phase-stabilized channels.
- Continuous Variable QKD:Coherent-state homodyne detection protocols leverage standard telecom components.
- Measurement Device Independent QKD:Protocols eliminating detector side-channel vulnerabilities through Bell-state measurements.
- Device Independent QKD:Theoretically optimal security proofs without hardware trust assumptions.
Discrete Variable QKD retains the largest validation equipment base. Twin-Field QKD is climbing the fastest as sovereign networks extend beyond metropolitan boundaries.
Application:
End-use risk profiles segment procurement specifications, with classified government traffic demanding more stringent validation protocols than commercial data center protection.
- Government Communication:Classified fiber links between defense installations require validated information-theoretic security against computational and quantum cryptanalysis. NATO procurement programs across multiple member states mandate certified test equipment for quantum-secured backbone acceptance, compressing vendor certification cycles under NIST post-quantum migration timelines.
- Telecom Network Security:Carrier-grade quantum key distribution for enterprise VPN and infrastructure protection.
- Data Center Protection:Inter-facility encryption for cloud computing and colocation services.
- Financial Transactions:Settlement system protection and trading infrastructure security.
- Critical Infrastructure Safeguarding:Energy grid, transportation, and utility control system encryption.
Government Communication concentrates the highest-value test equipment contracts. Data Center Protection is gaining share fastest as cloud operators pilot quantum-secured interconnection.
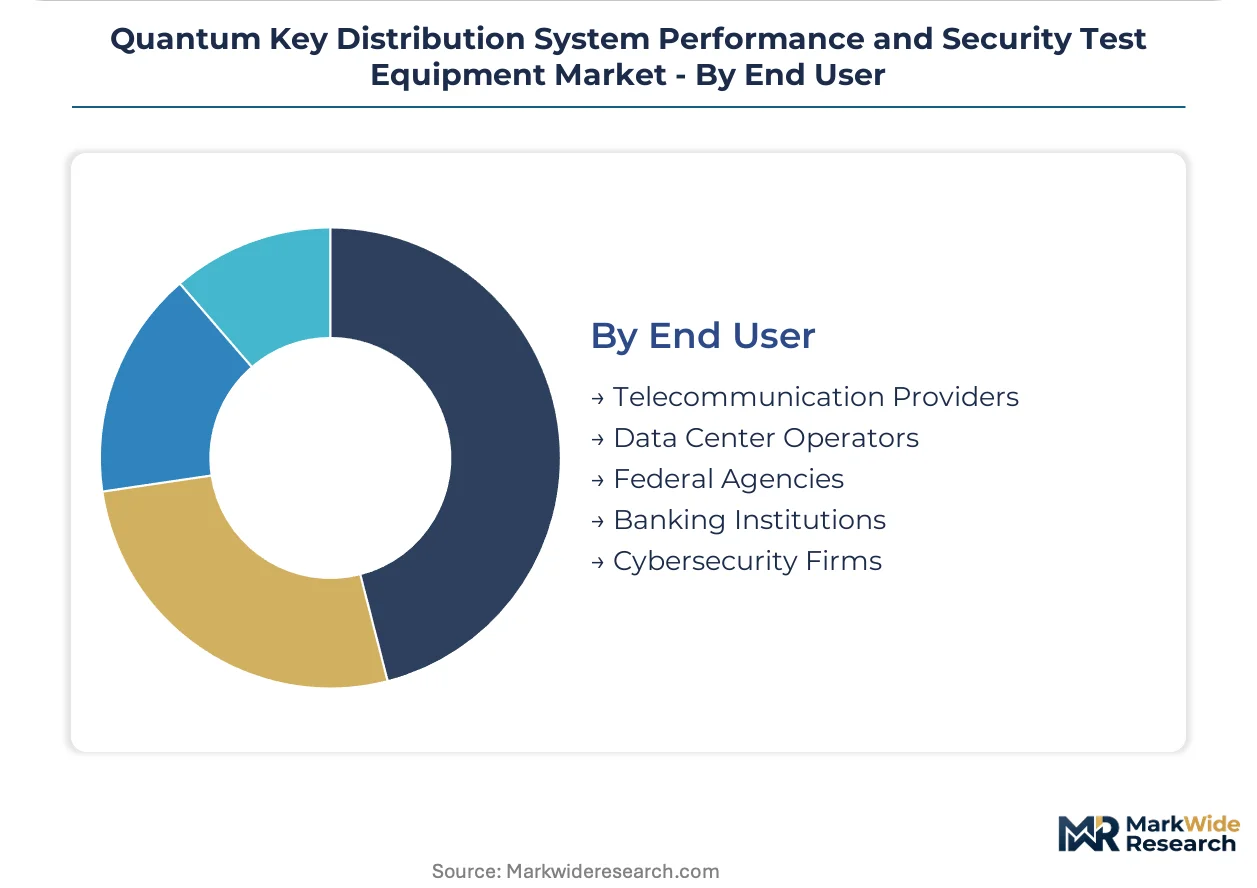
End User:
Procurement authority and technical sophistication vary across buyer categories, with federal agencies specifying standards that cascade into commercial requirements.
- Federal Agencies:Sovereign quantum communication programs in Germany, France, and the Netherlands mandate certified test equipment under the EU Cybersecurity Act. National regulators transpose ETSI QKD specifications into binding procurement requirements, forcing dual-track certification programs for equipment vendors.
- Telecommunication Providers:Carrier procurement teams unbundle after-sales calibration from initial hardware acquisition.
- Data Center Operators:Hyperscale and colocation providers validate quantum-secured inter-facility links.
- Banking Institutions:Financial regulators specify quantum-safe transition timelines for payment infrastructure.
- Cybersecurity Firms:Third-party auditors and managed security service providers.
Federal Agencies anchor premium equipment demand. Cybersecurity Firms are expanding most quickly as independent security auditing unbundles from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Munich-Stuttgart corridor anchors European procurement gravity for quantum test equipment, though sovereign programs in Asia and North America are compressing certification timelines and fragmenting vendor concentration across three distinct regulatory spheres.
Germany
Bavaria's quantum technology cluster around Munich and Stuttgart concentrates ETSI-mandated test equipment procurement for sovereign network infrastructure. The EU Cybersecurity Act transposes binding certification requirements for quantum communication acceptance, forcing dual-track vendor qualification. Fraunhofer institutes in Munich coordinate applied research contracts with defense procurement offices validating fiber links between federal installations.
United States
NIST's accelerated post-quantum cryptography migration compresses hardware-software co-development cycles for test equipment vendors serving federal agencies. The Department of Defense specifies portable security analyzers for field validation of quantum-secured backbone links between defense installations. Research concentration in Maryland and Colorado reflects proximity to NIST facilities and Air Force quantum communication programs.
China
MIIT-funded quantum communication infrastructure programs deploy Twin-Field QKD systems for inter-city backbone links exceeding 500 kilometers, commanding premium test equipment specifications. National standards for quantum channel validation diverge from ITU-T frameworks, forcing redundant certification investments for multinational vendors. The Hefei-Shanghai corridor concentrates domestic manufacturing of cryogenic photon detection systems.
Japan
METI-funded quantum network pilots specify independent security auditing through third-party metrology labs, unbundling calibration services from hardware procurement. NTT and Toshiba anchor domestic demand for discrete variable QKD validation equipment in metropolitan fiber deployments. The Tokyo-Osaka corridor concentrates carrier procurement teams specifying ITU-T standard compliance for commercial quantum key distribution links.
Switzerland
Geneva-based manufacturing of single-photon detectors supplies European defense and research markets, though cryogenic cooling requirements limit foundry capacity expansion. Swissmedic-equivalent cybersecurity frameworks for critical infrastructure mandate certified test equipment for financial and government network acceptance. The Lake Geneva region concentrates photonics engineering talent for quantum optics instrumentation development.
Quantum Key Distribution System Performance and Security Test Equipment Market Competitive Landscape
Global majors compete with regional champions across certification alignment, as NIST-track and ETSI-track qualification requirements fragment procurement specifications and compress vendor development timelines. The vendor base concentrates around three strategic archetypes: integrated photonics specialists with captive silicon foundry access, cryogenic detector manufacturers with European foundry relationships, and telecommunications incumbents leveraging existing carrier relationships. Dominant competitive moves include dual-track certification programs targeting both European sovereign networks and NIST-aligned federal systems, plus strategic partnerships with national quantum communication infrastructure programs.
Within the integrated instrumentation tier, Keysight Technologies exemplifies photonic integration capabilities for portable security analyzers, while ID Quantique anchors European supply through Geneva-based manufacturing operations. Toshiba occupies a position bridging Asia-Pacific deployment programs with cryogenically cooled receiver module development. These three companies represent distinct geographic and technological positioning strategies that vendors must navigate to capture procurement contracts across fragmented regulatory environments.
| Leading Market Players |
|---|
| Keysight Technologies |
| ID Quantique |
| Rohde & Schwarz |
| Anritsu |
| VIAVI Solutions |
| Toshiba |
| QuantumCTek |
| QuintessenceLabs |
| SK Telecom |
| Others |
Pricing and Supply Chain Analysis
Indium phosphide wafer pricing indices cascade through QKD test equipment supply chains, compressing margins for cryogenic detector manufacturers while amplifying pricing power for silicon photonics integrators serving NATO procurement offices. This input-cost divergence stratifies equipment tiers across ETSI-mandated certification grades.
Pricing Analysis
Input-cost pass-through from cryogenic cooling systems and single-photon detector materials drives three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture ETSI QKD certification-grade equipment for sovereign networks, while economy tiers serve academic research labs with reduced detector efficiency specifications. Pricing pressure stems from silicon photonics displacement of discrete fiber-coupled components. Federal agencies exhibit lowest price sensitivity due to mandated security requirements; third-party metrology labs in Asia-Pacific markets demonstrate highest sensitivity as calibration services unbundle from hardware.
Supply Chain Analysis
Single-source vulnerability sits with European cryogenic detector foundries in Switzerland and Germany, where limited superconducting nanowire manufacturing capacity constrains output expansion. Supply chains draw from indium phosphide substrates, helium-3 cooling systems, and precision timing distribution modules sourced through specialized distributors. Tariff exposure on cryogenic components imported into NATO member states creates procurement friction. Distribution runs through defense procurement offices, carrier technical validation teams, and third-party security auditors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as sovereign quantum communication infrastructure programs institutionalize recurring test equipment procurement cycles across defense and critical infrastructure networks.
For Market Incumbents: Deploy dual-track certification investment as the primary lever to capture both ETSI-mandated European sovereign networks and NIST-aligned federal systems. ID Quantique and Keysight Technologies exemplify this positioning through Geneva-based manufacturing and in-house photonic integration respectively. Cryogenic detector supply bottlenecks threaten margin compression; backward integration into silicon photonics foundry partnerships defends cost position against emerging fabless competitors. For New Entrants and Emerging Players: Direct-to-defense procurement portals offer the most penetrable route for portable security analyzer specialists targeting NATO field validation requirements. Free-space QKD testing for satellite-to-ground links remains underpenetrated, with defense and space agency budgets concentrated in Germany's Munich-Stuttgart corridor and US research clusters around Maryland. Channel partnerships with national quantum communication infrastructure programs accelerate initial reference deployments. For Investors and Strategic Acquirers: Asymmetric upside sits with silicon photonics specialists possessing captive foundry access and existing ETSI certification track records. The five-to-ten-year viability window favors equipment vendors with demonstrated sovereign network acceptance rather than component suppliers vulnerable to integration. Watch NIST post-quantum cryptography migration timeline compression as the inflection signal accelerating vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Certification Investment | ETSI and NIST alignment captures procurement from German sovereign networks and US federal agencies simultaneously. |
| Silicon Photonics Foundry Partnership | Fabless vendors gain cost parity with integrated manufacturers through commercial PIC fabrication access. |
| Free-Space QKD Testing Capability | Satellite-to-ground validation addresses defense budgets in NATO member states and Asia-Pacific space programs. |
| Calibration Services Unbundling | Third-party metrology contracts in Japan's METI-funded pilots create recurring revenue independent of hardware cycles. |
| Cryogenic Detector Capacity Expansion | European foundry relationships anchor supply security for superconducting nanowire systems in Geneva and Stuttgart. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and Switzerland, with primary inputs from each market through structured interviews with quantum optics instrumentation engineers, defense procurement officers, carrier network validation leads, cryogenic system designers, and third-party security auditors. Secondary validation drew from ITU-T standards documentation, ETSI QKD specification releases, NIST post-quantum cryptography migration frameworks, EU Cybersecurity Act transposition notices, and METI-funded quantum network pilot disclosures. Bottom-up equipment shipment tracking triangulates against top-down sovereign infrastructure budget allocations.
Granularity-level modeling disaggregates revenue across optical test instruments, photon detectors, synchronization units, security analyzers, and key management modules; by discrete variable, twin-field, continuous variable, measurement device independent, and device independent protocols; and across government communication, telecom network security, data center protection, financial transactions, and critical infrastructure safeguarding applications. CAGRs derive from protocol-specific deployment trajectories and certification timeline compression effects. Forecast inputs include silicon photonics integration curves, cryogenic detector manufacturing capacity constraints, and ETSI-NIST standardization convergence patterns.
The model assumes a particular technology adoption path; alternative pathways for post-quantum cryptographic algorithms without quantum hardware would alter the outlook for QKD displacement risk. Forecasts reflect assumptions regarding NATO procurement acceleration, EU Cybersecurity Act enforcement timing, and single-photon detector foundry expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
E-Beam Wafer Inspection System Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market