
 Fogging Tester Market | 2026-2036
Fogging Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Fogging Tester Market Analysis
REACH chemical safety thresholds are recalibrating the cost-of-entry calculus for fogging tester suppliers serving European automotive supply chains. Labthink leverages its optical sensor integration to dominate high-throughput configurations in Asia-Pacific manufacturing hubs. BYK-Gardner GmbH anchors its position through deep specialization in standardized visual inspection protocols for OEM certification labs. Elastocon AB competes by sustaining precision thermal measurement architectures that align with German automotive interior testing specifications.
A fogging tester quantifies volatile organic compound condensation on cooled glass surfaces from heated polymer, textile, or adhesive samples, typically operating at controlled temperatures between 100°C and 120°C with reflectometric or gravimetric readout to predict windshield haze and cabin air quality degradation. Benchtop systems command the installed base due to their compatibility with ISO 6452 and DIN 75201 workflows, while automated configurations represent the fastest-expanding segment as Tier-1 suppliers integrate them into continuous quality assurance lines. Optical sensor technology leads revenue contribution because it delivers reproducible haze quantification without operator variance, though chemical analysis modules capture expanding interest from polymer compounders seeking molecular-level VOC profiling.
EMA chemical safety guidelines, EPA indoor air quality frameworks, and China's GB/T 27630 cabin air standards collectively tighten acceptable VOC emission thresholds and expand mandatory testing scope across jurisdictions. The EU Green Deal accelerates substitution of legacy plasticizers, forcing reformulated materials through renewed fogging validation cycles before automotive platform approval. Stakeholders must monitor regulatory divergence between European hazard-based restrictions and China's prescriptive substance limits when configuring multi-territory testing protocols.
Market Dynamics
REACH chemical safety thresholds are recalibrating the cost-of-entry calculus for fogging tester suppliers serving European automotive supply chains. Labthink leverages its optical sensor integration to dominate high-throughput configurations in Asia-Pacific manufacturing hubs. BYK-Gardner GmbH anchors its position through deep specialization in standardized visual inspection protocols for OEM certification labs. Elastocon AB competes by sustaining precision thermal measurement architectures that align with German automotive interior testing specifications.
Growth Catalysts
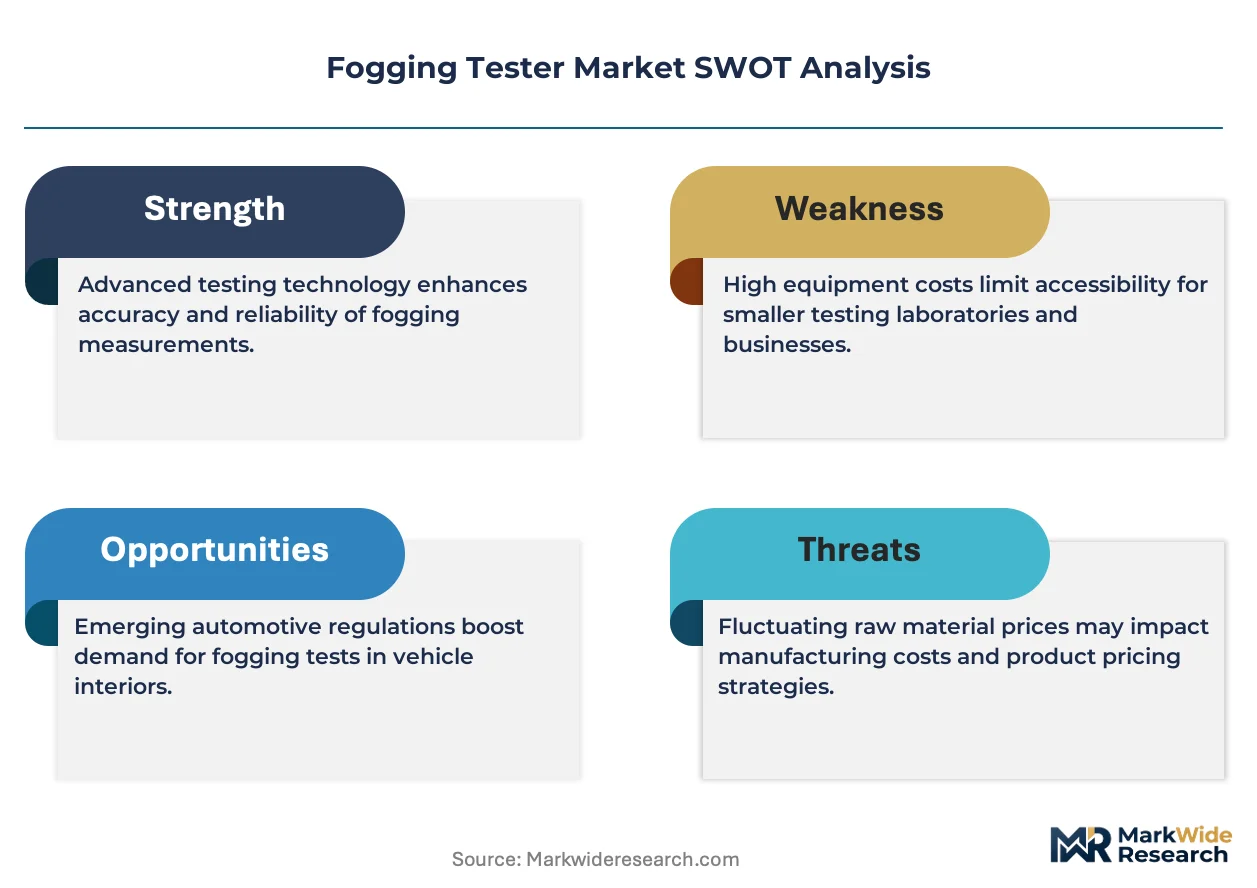
- EU Green Deal substitution mandates:Legacy plasticizer phase-outs force reformulated polymers through renewed fogging validation cycles before automotive platform approval.
- GB/T 27630 cabin air standards:China's prescriptive VOC substance limits expand mandatory testing scope for interior component suppliers serving domestic OEMs.
- Automated benchtop integration:Tier-1 suppliers embed continuous quality assurance lines to compress polymer validation workflow timelines.
Market Restraints
- Optical sensor component concentration:Specialized photodetector supply chains concentrate in East Asian semiconductor foundries, creating input vulnerability.
- Gravimetric method obsolescence risk:Manual weighing protocols face displacement by reflectometric systems, stranding capital in legacy installations.
- REACH registration cost escalation:ECHA fee structures for novel testing chemicals raise operational barriers for mid-scale validation laboratories.
Strategic Opportunities
- India BIS adoption gap:Domestic automotive interior standards remain underdeveloped versus European benchmarks, creating first-mover positioning for ISO 6452-aligned system providers.
- Chemical analysis module convergence:Molecular-level VOC profiling capabilities attract polymer compounders seeking upstream material characterization integration.
- EPA indoor air quality framework expansion:Residential building material emission protocols extend fogging tester applicability beyond automotive into construction adhesives and furnishings.
Industry Challenges
- ISO 6452-DIN 75201 harmonization gaps:Divergent cooling plate specifications between international and German national standards complicate multi-territory certification workflows.
- Thermal calibration technician scarcity:Precision temperature control expertise at 100°C-120°C operating ranges exceeds available skilled labor pools in emerging manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fogging Tester Market |
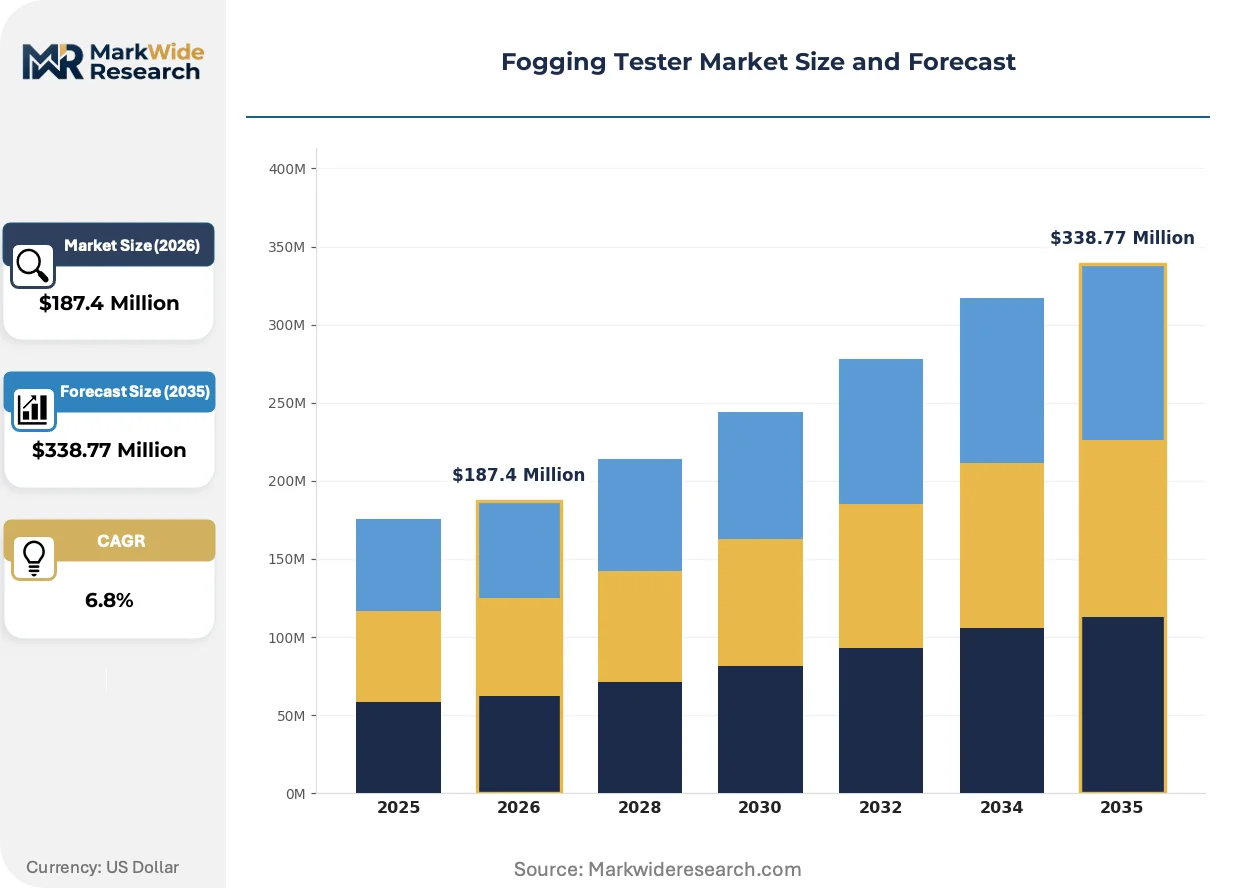
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Automated, Manual Application: Automotive Interiors, Building Materials, Electronics, Packaging End User: Manufacturers, Research Institutions, Testing Laboratories, Automotive Companies Technology: Optical Sensors, Thermal Measurement, Chemical Analysis, Visual Inspection |
| Companies Covered | Labthink, BYK-Gardner GmbH, Elastocon AB, Presto Stantest Pvt. Ltd, Elcometer Limited, Thermo Fisher Scientific, Atlas, Q-Lab Corporation, Qualitest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fogging Tester Market Emerging Trajectories
Sensor fusion architectures are compressing the distinction between optical haze quantification and chemical speciation in next-generation fogging analysis platforms. Multi-modal readout systems now capture both reflectometric surface condensation and molecular VOC identity within single workflow integration.
Reflectometric optical sensor technology is electrifying competitive positioning in high-throughput manufacturing environments. Automotive OEM certification labs in Stuttgart and Toyota City adopt these systems to eliminate operator variance in windshield haze prediction. The technology is electrifying margin structures by reducing per-test labor content while accelerating throughput for continuous quality assurance lines.
REACH authorization list expansion under ECHA oversight is forcing material reformulation cycles across European automotive supply chains. Suppliers must revalidate interior components against revised SVHC thresholds before platform launch. German OEMs and their Tier-1 networks bear the heaviest compliance burden, driving replacement demand for upgraded fogging tester configurations.
Validation service unbundling is fragmenting traditional equipment-plus-protocol bundled sales. Independent testing laboratories now procure bare hardware and subscribe to cloud-based method libraries separately. This pattern concentrates in Asia-Pacific manufacturing clusters where capital constraints favor operational expenditure models over upfront instrument acquisition.
Fogging Tester Market Segmentation
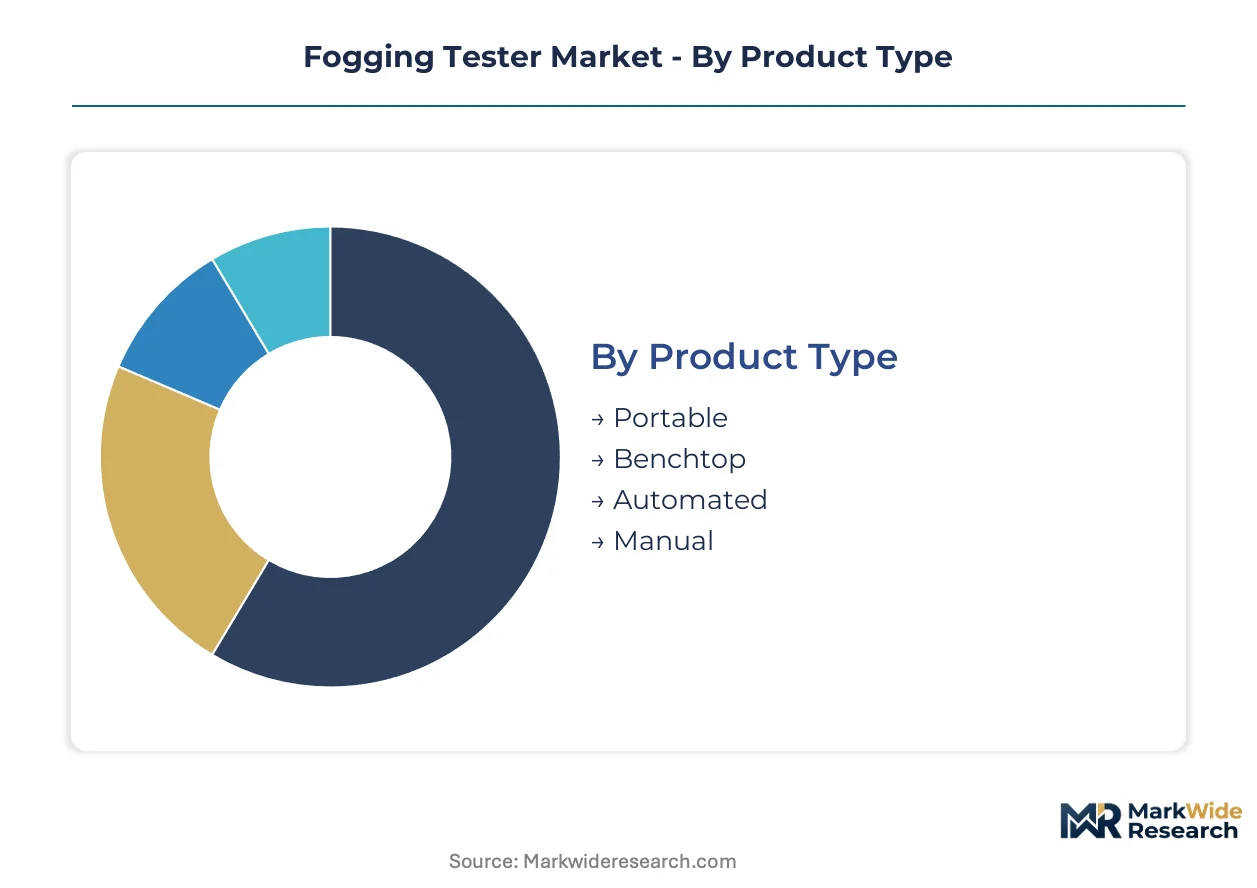
Fogging tester procurement decisions pivot on throughput requirements, regulatory compliance scope, and integration depth with existing quality assurance infrastructure. Segmentation reveals how optical sensor dominance and automated workflow adoption are restructuring competitive positioning across automotive supply chains.
Product Type:
Capital deployment intensity and labor substitution potential drive buyer selection across portable, benchtop, and automated configurations.
- Benchtop:Compact stationary units operating at controlled temperatures between 100°C and 120°C serve as the installed base standard for ISO 6452 and DIN 75201 validation workflows. German and Japanese automotive OEMs concentrate procurement here for polymer qualification before platform approval.
- Automated:Continuous-feed systems with robotic sample handling integrate into Tier-1 supplier quality assurance lines, compressing validation timelines from days to hours. Asia-Pacific manufacturing hubs in Toyota City and Shenzhen drive fastest adoption as labor costs rise.
- Portable:Mobile units enable on-site emission screening at supplier facilities without laboratory infrastructure.
- Manual:Entry-level configurations with operator-dependent gravimetric readout face displacement risk from reflectometric systems.
Volume sits with benchtop systems; growth tilts toward automated configurations.
Application:
Regulatory stringency divergence across end-use sectors creates tiered pricing and specification requirements.
- Automotive Interiors:Dashboard polymers, seat textiles, and adhesive layers undergo mandatory fogging testing under REACH SVHC thresholds and China's GB/T 27630 cabin air standards. German OEM certification labs in Stuttgart anchor global demand concentration.
- Building Materials:Construction adhesives and furnishing textiles face expanding EPA indoor air quality framework scrutiny, extending fogging tester applicability beyond automotive.
- Electronics:Enclosure polymers and cable insulation require VOC emission validation for enclosed device safety.
- Packaging:Food-contact and pharmaceutical barrier materials use fogging analysis for volatile migration prediction.
Revenue concentrates in automotive applications; building materials show steepest expansion trajectory as residential emission protocols tighten.
End User:
Organizational scale and certification authority determine system specification complexity and service bundling preferences.
- Automotive Companies:OEM certification labs demand highest optical precision and multi-territory protocol compliance for platform launch authorization.
- Testing Laboratories:Independent validation service providers increasingly unbundle hardware from cloud-based method subscriptions.
- Manufacturers:Polymer compounders and Tier-1 suppliers prioritize throughput and integration with continuous production lines.
- Research Institutions:Academic and government laboratories drive chemical analysis module adoption for molecular-level VOC profiling.
Procurement volume clusters with testing laboratories; automotive companies command premium pricing tiers.
Technology:
Readout modality selection determines reproducibility, labor content, and downstream analytical extensibility.
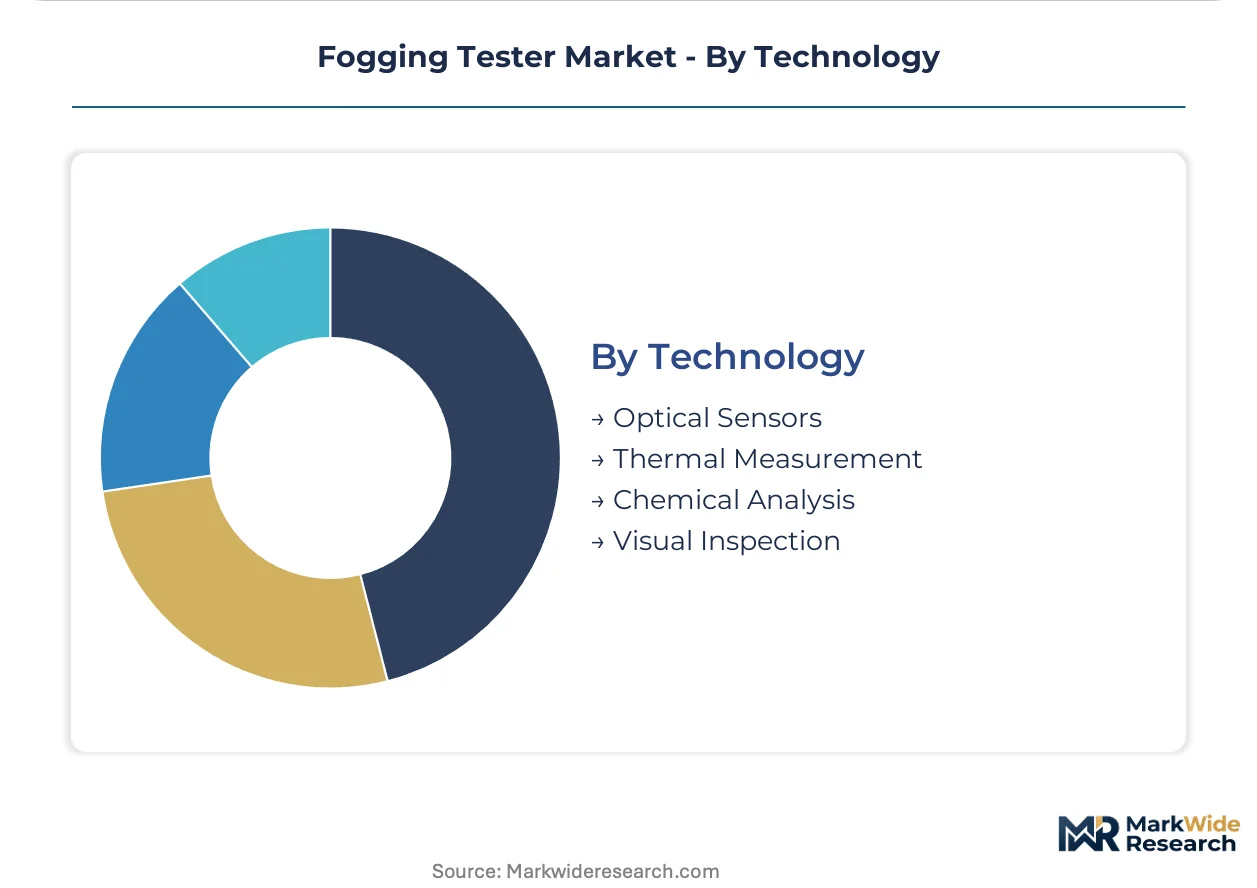
- Optical Sensors:Reflectometric photodetector arrays deliver reproducible haze quantification without operator variance, electrifying competitive positioning in high-throughput environments. Labthink dominates Asia-Pacific manufacturing hub deployments through integrated sensor architectures.
- Chemical Analysis:Mass spectrometry and chromatography modules capture molecular VOC identity, attracting polymer compounders seeking upstream material characterization integration.
- Thermal Measurement:Precision temperature control architectures align with German automotive interior testing specifications.
- Visual Inspection:Standardized operator-dependent protocols retain relevance in OEM certification labs requiring human-interpretable documentation.
Optical sensors command revenue leadership; chemical analysis modules gain share fastest as multi-modal fusion architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEM certification labs concentrate procurement of high-precision fogging testers for interior air quality validation, while Japanese and Chinese manufacturing hubs drive automated system adoption for continuous production line integration.
Germany
Stuttgart-based OEM certification labs anchor European demand for DIN 75201-compliant benchtop systems. ECHA REACH authorization list expansions force reformulated polymer validation cycles before platform launches. Bavarian Tier-1 supplier networks embed automated fogging testers into continuous quality assurance lines to compress approval timelines.
Japan
Toyota City manufacturing clusters drive fastest adoption of robotic sample-handling configurations for polymer qualification workflows. METI industrial standards align with JIS testing protocols for interior component emission control. Kansai region electronics enclosure manufacturers extend fogging analysis to cable insulation and device housing materials.
China
Shenzhen and Yangtze River Delta polymer compounders procure high-throughput optical sensor systems for GB/T 27630 cabin air compliance. MIIT mandates tighten VOC emission thresholds for domestic OEM interior platforms. Shandong Peninsula automotive supplier parks integrate automated testers into just-in-time manufacturing cells.
United States
EPA indoor air quality framework expansion extends fogging tester applicability into construction adhesives and residential furnishings beyond automotive. Michigan-based OEM labs validate dashboard polymers against emerging SVHC screening protocols. Southeast manufacturing corridors attract portable system deployments for on-site supplier emission screening.
India
Maharashtra and Tamil Nadu automotive clusters create first-mover positioning opportunities for ISO 6452-aligned system providers. BIS domestic interior standards remain underdeveloped versus European benchmarks. Gujarat polymer processing hubs invest in entry-level benchtop configurations as OEM supply chain localization accelerates.
Fogging Tester Market Vendor Landscape
European producers anchor the premium-tier certification lab segment; Asia-Pacific specialists hold volume positions in manufacturing hub deployments. The vendor base organizes around three strategic archetypes: optical sensor integrators serving high-throughput environments, thermal measurement precision specialists aligned with German automotive specifications, and standardized visual inspection protocol providers for OEM documentation requirements. Competitive moves concentrate on sensor fusion technology licensing and automated workflow partnerships with Tier-1 supplier networks.
Within the optical integration archetype, Labthink occupies a position exemplifying Asia-Pacific manufacturing hub dominance. BYK-Gardner GmbH represents the European certification lab specialization tier. Elastocon AB anchors the precision thermal measurement segment aligned with German automotive interior testing specifications.
| Leading Market Players |
|---|
| Labthink |
| BYK-Gardner GmbH |
| Elastocon AB |
| Presto Stantest Pvt. Ltd |
| Elcometer Limited |
| Thermo Fisher Scientific |
| Atlas |
| Q-Lab Corporation |
| Qualitest |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between DIN 75201-compliant precision systems and entry-level ISO 6452 configurations manifests in both margin structures and component sourcing geographies. German OEM certification labs absorb 40-60% pricing premiums for thermal calibration precision while Asia-Pacific manufacturing hubs drive commoditization of optical sensor arrays through volume procurement.
Pricing Analysis
Volume-margins split sharply between automated high-throughput configurations and manual gravimetric systems facing obsolescence. Three-tier pricing structure across premium, standard, and economy levels reflects certification authority, optical sensor integration depth, and after-sales service bundling. Cost compression in entry-tier benchtop units intensifies as Chinese polymer compounders scale domestic production. Testing laboratories exhibit highest price sensitivity; automotive OEM certification labs prioritize precision over unit economics.
Supply Chain Analysis
Domestic-content mandates under China's MIIT localization directives are reshaping sourcing patterns for photodetector arrays and precision thermal control modules. Specialized optical sensor production concentrates in Japan, South Korea, and Taiwan. Fogging tester assembly draws from German precision temperature control components and Chinese structural manufacturing. Single-source vulnerability in East Asian semiconductor foundries for reflectometric photodetectors elevates supply risk. Distribution runs through direct OEM relationships in Stuttgart and Toyota City, with independent testing laboratories served through regional distribution partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fogging tester market sits in a technology-transition phase where reflectometric optical sensors are displacing manual gravimetric protocols. This substitution wave restructures competitive positioning across validation workflows.
For Market Incumbents: Hedge against sensor component supply concentration by securing dual-source agreements with Japanese and South Korean photodetector manufacturers. Deepen backward integration into precision thermal control calibration capabilities to defend margin position against Asian optical specialists. ECHA REACH fee escalation threatens mid-scale validation laboratory demand; prioritize automated workflow partnerships with Tier-1 supplier networks over certification lab dependence. For New Entrants and Emerging Players: Digital-channel direct sales to polymer compounders in India's Gujarat and Maharashtra clusters bypass established European distributor relationships. India's BIS standards underdevelopment creates white-space positioning for ISO 6452-aligned system providers before regulatory harmonization. Target subscription-based cloud method libraries for capital-constrained Asia-Pacific testing laboratories as the primary go-to-market vector. For Investors and Strategic Acquirers: Re-rating potential sits with chemical analysis module specialists given convergence toward multi-modal sensor fusion architectures. Long-term viability favors platforms spanning optical haze quantification and molecular VOC speciation rather than single-modality hardware. Watch ECHA SVHC threshold expansion velocity as the inflection indicator for replacement demand cycles in European automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Technology Licensing | Multi-modal readout capabilities attract polymer compounders seeking upstream integration with material characterization workflows. |
| Automated Workflow Partnership | Tier-1 supplier integration in Toyota City and Shenzhen compresses validation timelines from days to hours. |
| Backward Integration into Optical Components | In-house photodetector sourcing mitigates East Asian semiconductor foundry concentration risk. |
| Cloud-Based Method Subscription Launch | Operational expenditure models align with capital-constrained Asia-Pacific testing laboratory procurement patterns. |
| GB/T 27630 Compliance Certification | Chinese MIIT mandate alignment unlocks domestic OEM interior platform validation opportunities. |
Methodological Framework
Independent corroboration across primary interviews with automotive OEM platform engineers, Tier-1 supplier procurement leads, independent testing laboratory directors, and polymer compounder R&D heads underwrites the qualitative findings. Secondary validation draws from ECHA REACH authorization databases, MIIT GB standard filings, SEC equipment manufacturer disclosures, and automotive production registration data. Bottom-up instrumentation demand modeling and top-down regulatory mandate scope analysis triangulate market sizing.
Comparable-period anchoring to historical ISO 6452 and DIN 75201 adoption cycles structures the projection horizon. Segmentation dimensions span product configuration, readout technology modality, end-user organizational scale, and regional regulatory framework cluster. CAGRs derive from instrument replacement cycle analysis, polymer formulation velocity, and compliance mandate expansion trajectories. Forecast inputs incorporate ECHA SVHC list revision frequency and MIIT VOC threshold tightening schedules.
The model holds under stable REACH authorization timelines and continued GB/T 27630 enforcement; deviation in ECHA fee structures or BIS standard acceleration would shift replacement demand patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Signal Generator Market
Test and Measurement
Calibration Services Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market