

Backside Power Delivery Network (BPDN) Analysis Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market Insights
Modular test-cell bundling is consolidating procurement patterns across BPDN analysis workflows. Thermo Fisher Scientific leverages its electron microscopy portfolio to anchor backside metrology workflows for advanced node development. KLA competes through defect inspection systems that map power via continuity across thinned wafer architectures. Oxford Instruments specializes in plasma etch and deposition tools that prepare samples for subsequent BPDN electrical characterization.
Backside Power Delivery Network analysis test equipment comprises instruments that characterize electrical performance, physical structure, and thermal behavior of power routing layers relocated to the wafer backside in advanced logic devices. These systems typically resolve sub-micron features through focused ion beam milling combined with nano-probing, operating at voltage scales below one volt to preserve gate oxide integrity during power integrity measurement. Probe cards and network analyzers lead current revenue contribution as foundries validate signal paths across redesigned interconnect stacks. Frequency domain analysis methods are gaining share fastest where parasitic extraction demands grow at each process shrink, while electrostatic discharge testing commands premium pricing due to qualification rigor imposed by automotive semiconductor standards.
US export controls administered by the Bureau of Industry and Security restrict BPDN test equipment shipments to specific Chinese fabs, redirecting vendor focus toward Taiwan, South Korea, and domestic US expansion projects. REACH substance restrictions from ECHA constrain etchant chemistries used in sample preparation, pushing equipment makers toward closed-loop processing architectures. SEMI safety guidelines and ISO 17025 calibration standards further shape product certification requirements across major supply corridors. Stakeholders must monitor evolving multilateral coordination on semiconductor equipment controls while calibrating regional service infrastructure to match fab construction timelines.
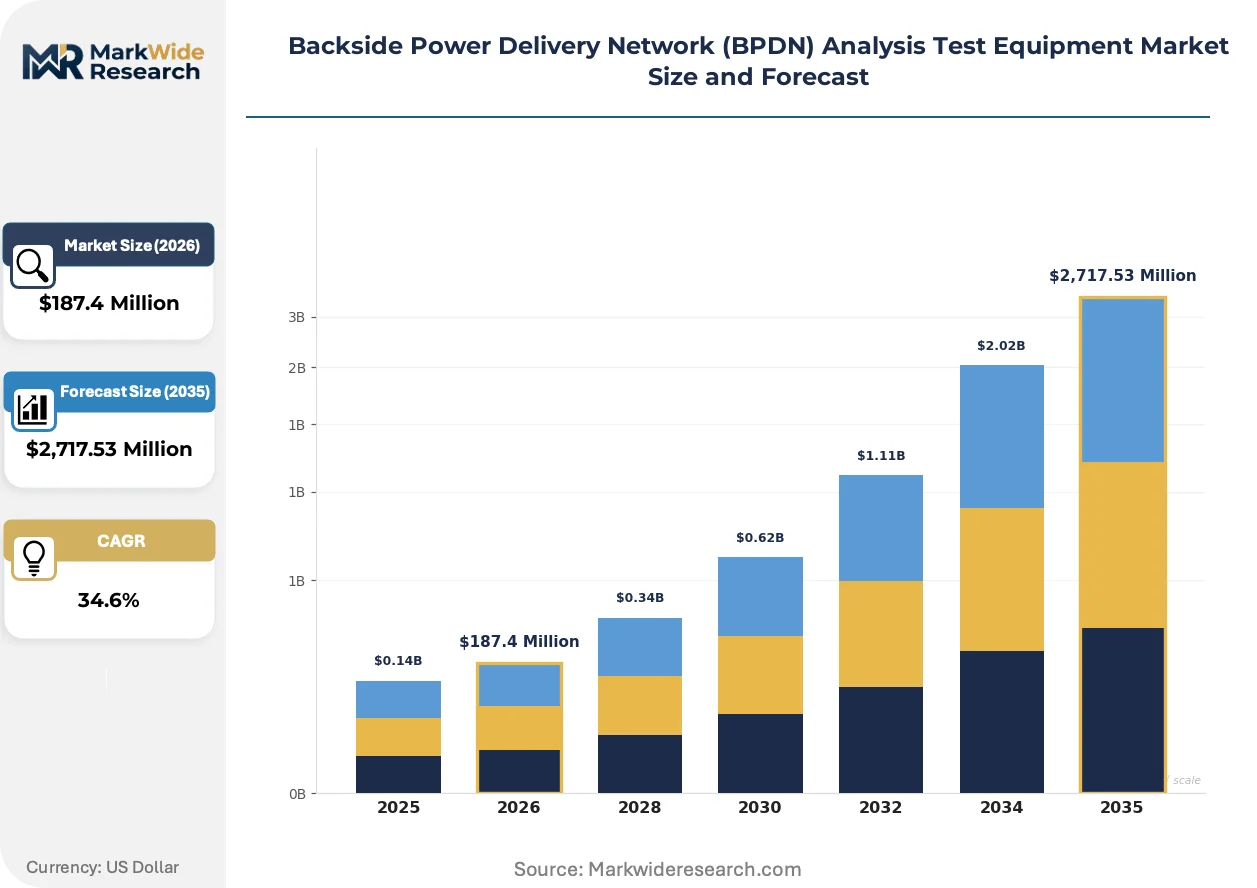
Market Dynamics
EUV lithography roadmaps from ASML and TSMC process node requirements are compressing test cycles for backside power routing validation, forcing equipment vendors to accelerate throughput specifications while maintaining sub-nanometer measurement precision.
Growth Catalysts
- Sub-2nm node migration:Foundries in Taiwan and South Korea are scaling BPDN validation protocols as transistor architectures migrate below two nanometers, creating sustained demand for advanced metrology systems.
- Automotive qualification rigor:Electrostatic discharge testing commands premium pricing due to qualification standards imposed by automotive semiconductor requirements, expanding the addressable test equipment base.
- REACH substance mandates:ECHA restrictions on etchant chemistries push equipment makers toward closed-loop processing architectures, stimulating replacement cycles for legacy sample preparation tools.
Market Restraints
- Helium supply concentration:Focused ion beam systems depend on helium-3 and neon isotope supplies concentrated in Russia and Algeria, exposing vendors to geopolitical supply interruptions.
- US export control friction:Bureau of Industry and Security restrictions on BPDN test equipment shipments to specific Chinese fabs redirect vendor focus but compress total addressable market geography.
- Technical throughput ceiling:Nano-probing at sub-1V scales preserves gate oxide integrity but limits parallel test head density, constraining foundry floor productivity gains.
Strategic Opportunities
- India semiconductor manufacturing:PLI scheme incentives for domestic fab construction create virgin demand territory for BPDN analysis equipment as first-mover vendors establish service infrastructure.
- Frequency domain analysis convergence:Parasitic extraction demands at each process shrink position network analyzer integration with electron microscopy as a high-value bundled offering.
- Modular test-cell bundling:Procurement consolidation across BPDN workflows enables vendors to anchor multi-instrument contracts through electron microscopy portfolio leverage.
Industry Challenges
- Multi-physics simulation talent scarcity:BPDN characterization requires simultaneous expertise in thermal, electrical, and mechanical modeling, with foundry compensation packages competing for limited specialists.
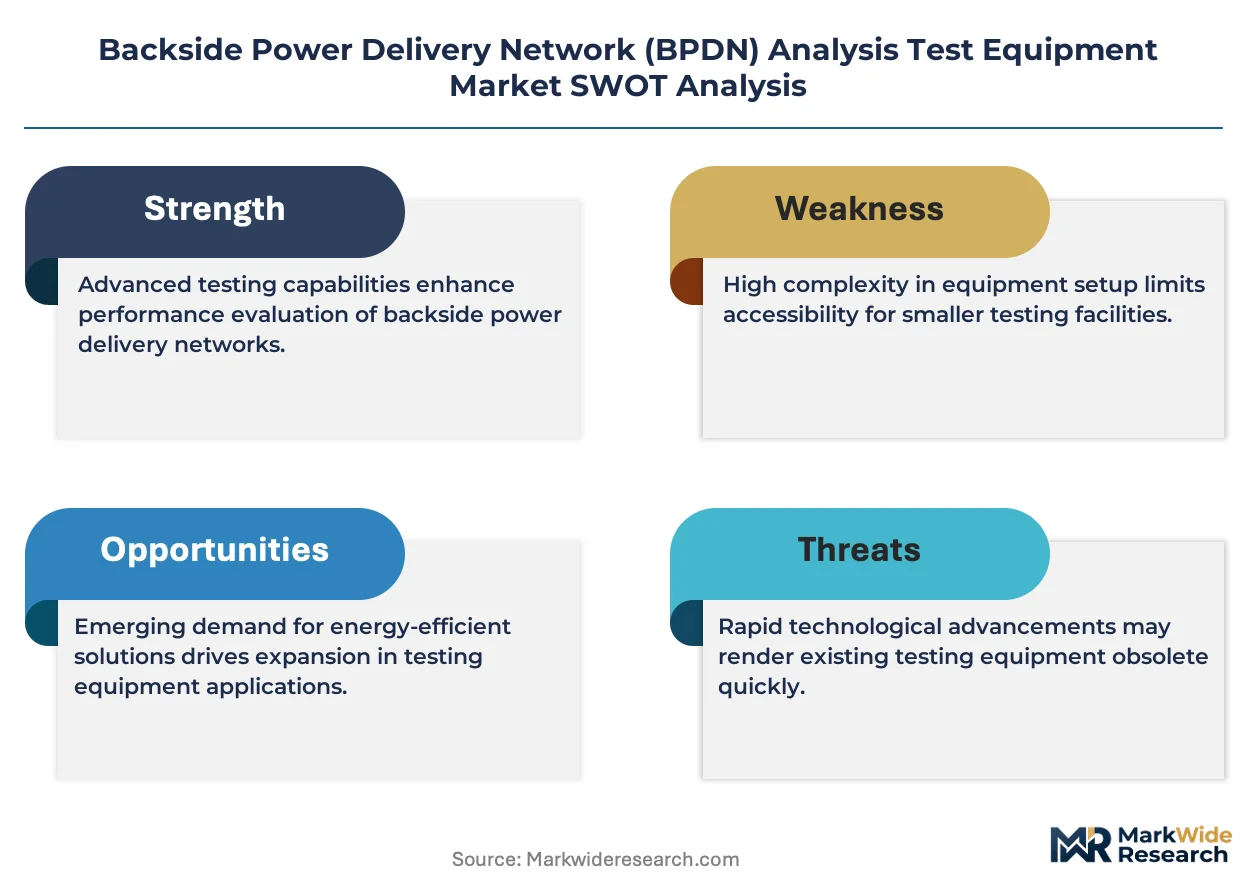
- ISO 17025 calibration backlog:Accreditation timelines for nano-probe calibration laboratories extend equipment commissioning schedules, delaying foundry process qualification milestones.
- Legacy interconnect integration:Backside power routing must coexist with existing frontside metallization stacks, complicating test fixture design for hybrid validation protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market Trends and Innovations
Test equipment architectures are converging around unified data pipelines that bridge physical metrology with electrical characterization, eliminating workflow fragmentation that previously required multiple vendor handoffs during BPDN validation cycles.
Hybrid focused ion beam systems with integrated cryo-stages are unifying sample preparation and in-situ electrical measurement within single vacuum envelopes. Leading-edge foundries in Taiwan and South Korea are adopting these platforms for sub-3nm node development. This convergence is compressing test cycle duration from days to hours while reducing contamination risk during wafer thinning operations.
REACH substance restrictions from ECHA are mandating closed-loop etchant recovery in sample preparation workflows. Equipment vendors are redesigning plasma etch chambers with integrated chemical regeneration modules. European foundry customers are specifying these configurations in procurement tenders ahead of anticipated regulatory expansion.
Foundry buyers are consolidating vendor relationships through multi-year test-cell bundling agreements that span electron microscopy, probe cards, and network analyzers. Traditional point-product procurement through separate capital committees is yielding to integrated workflow contracts. This pattern is most pronounced in Taiwan where TSMC and UMC are rationalizing supplier bases to reduce qualification overhead.
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market Segmentation
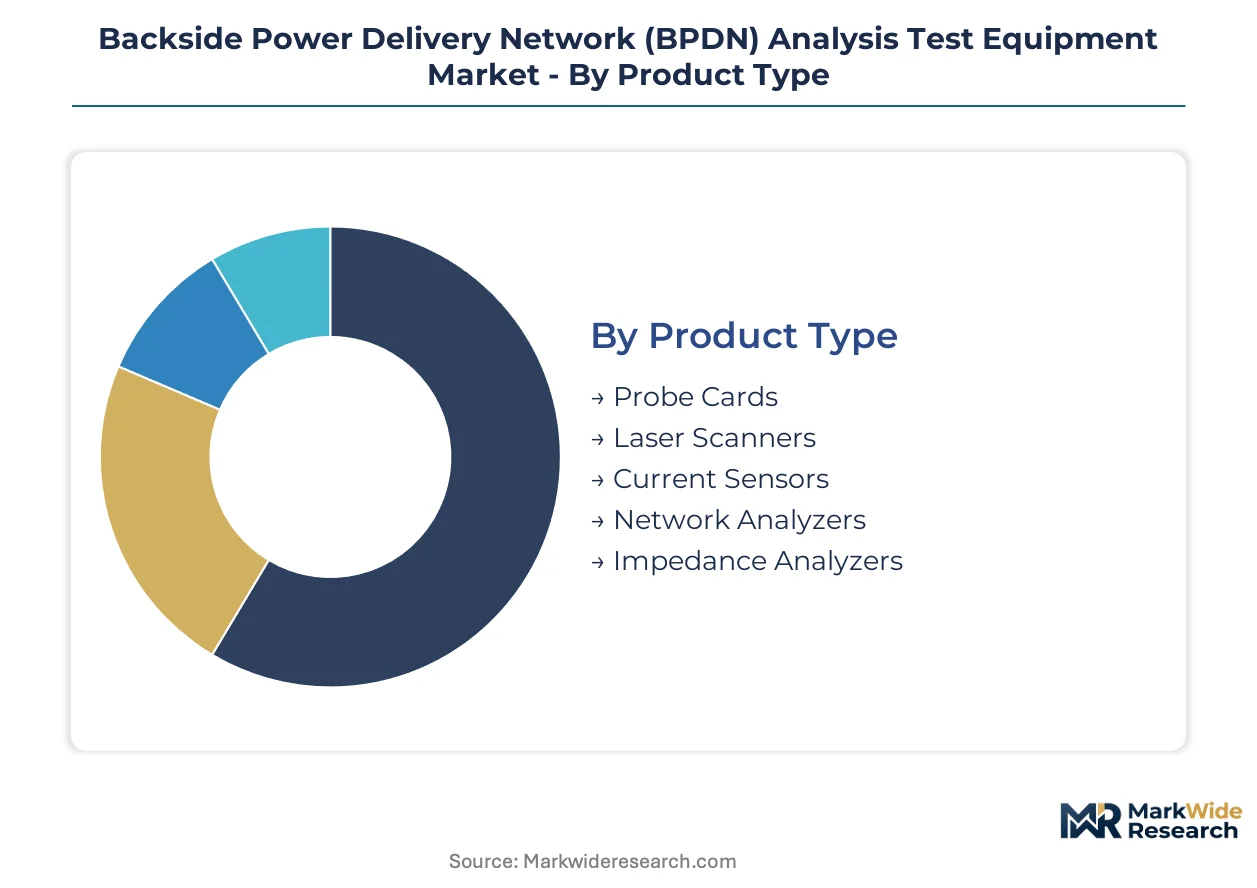
Equipment selection in BPDN analysis hinges on whether tools operate as standalone workstations or integrate into automated fab workflows. Procurement committees weight interoperability against specialized performance metrics when allocating capital across these segment boundaries.
Product Type:
Standalone probe cards anchor high-volume production floors, while laser scanners embed into inline metrology chains for continuous monitoring.
- Probe Cards:Multi-point contact arrays establish electrical pathways to backside power vias at sub-micron pitch. TSMC and Samsung Foundry deploy these for wafer-level screening before dicing, with qualification cycles tightening at each node shrink.
- Network Analyzers:Vector measurement engines capture scattering parameters across GHz-range frequencies to characterize impedance mismatches in power delivery paths. Frequency domain methods are gaining share fastest where parasitic extraction demands intensify below 3nm geometries.
- Laser Scanners:Optical profilometers map surface topology for via depth uniformity.
- Current Sensors:Hall-effect and shunt-based monitors track power distribution in real-time.
- Impedance Analyzers:LCR meters quantify reactive components in thinned wafer stacks.
Volume placements concentrate in probe cards; the faster expansion belongs to network analyzers.
Technology:
Cost tiers separate premium frequency-domain platforms from standard time-domain instruments and economy thermal imaging configurations.
- Frequency Domain Analysis:S-parameter extraction enables precise modeling of power network behavior across operating frequencies. Taiwan foundries specify these for 2nm development programs where signal integrity margins compress.
- Electrostatic Discharge Testing:Pulsed current injection validates robustness against automotive qualification standards. Premium pricing reflects AEC-Q100 rigor demanded by tier-1 automotive semiconductor suppliers.
- Time Domain Reflectometry:Impulse response analysis locates discontinuities in power routing.
- Thermal Imaging:Infrared cameras detect hot spots in backside power distribution.
- Noise Measurement:Spectrum analyzers quantify power supply induced jitter.
Standard TDR systems dominate unit shipments; ESD testing commands the steepest expansion trajectory in value terms.
Application:
Customer maturity varies between routine chip testing protocols and emerging failure diagnostics requiring specialist interpretation.
- Semiconductor Chip Testing:Wafer-level electrical validation consumes the majority of BPDN equipment operating hours. South Korean memory and logic foundries drive replacement cycles as process nodes advance.
- Signal Integrity Analysis:High-speed digital characterization demands integrated probe-network analyzer bundles. Fabless design houses in Silicon Valley specify these for pre-silicon correlation studies.
- PCB Evaluation:Board-level power integrity verification extends BPDN concepts to substrate manufacturing.
- Package Verification:3D integration testing covers interposer and through-silicon via structures.
- Failure Diagnostics:Root-cause analysis for returned devices requires specialized nano-probing.
Chip testing absorbs the greatest installed base; signal integrity analysis is climbing the fastest as data rates escalate.
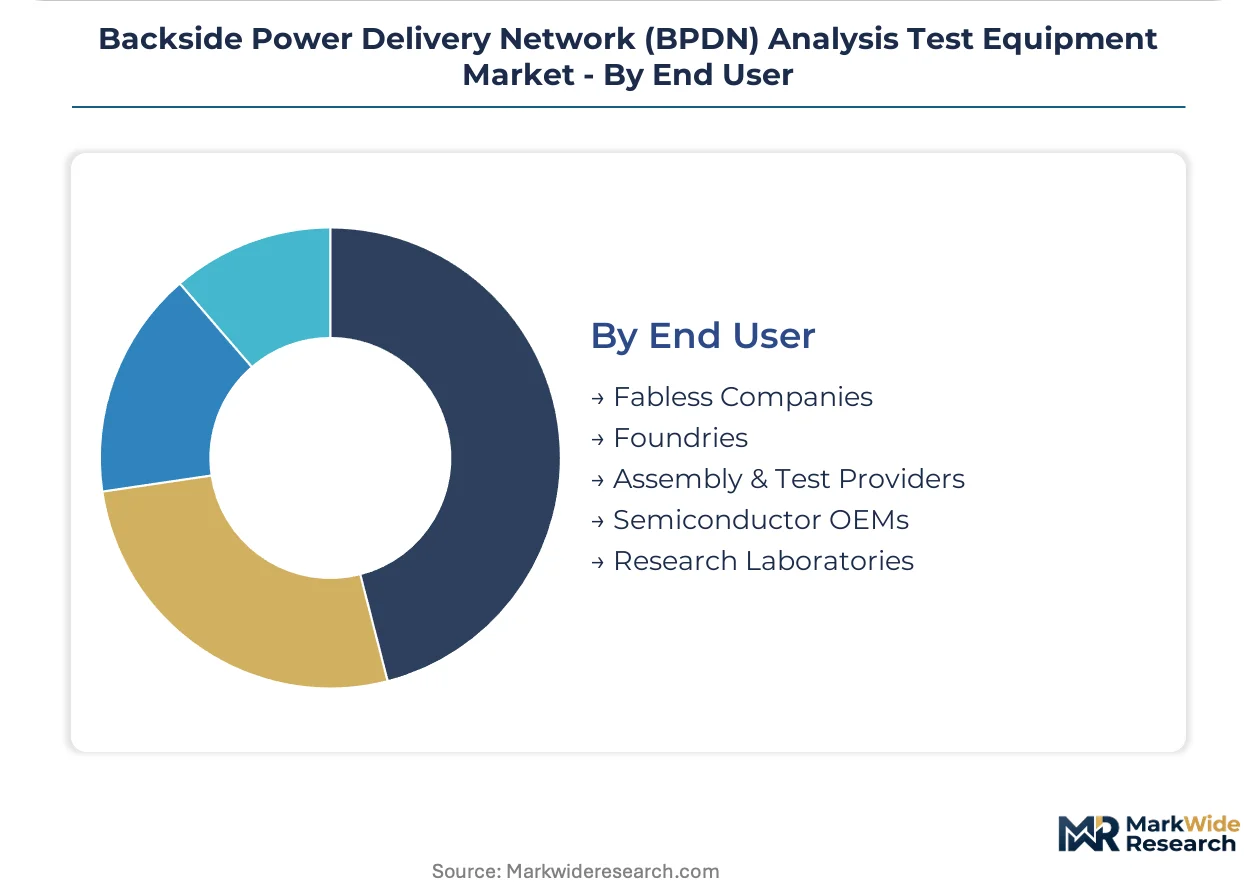
End User:
Supply concentration aligns with foundry capital intensity versus fabless asset-light models and captive OEM manufacturing.
- Foundries:Taiwan Semiconductor Manufacturing and Samsung Foundry operate the largest installed bases of BPDN analysis equipment. Their process development roadmaps dictate vendor R&D priorities and throughput specifications.
- Assembly & Test Providers:OSATs in Malaysia and Vietnam add BPDN screening to final test flows. These facilities prioritize equipment with minimal operator training requirements.
- Fabless Companies:Design-focused firms purchase limited equipment for early silicon bring-up.
- Semiconductor OEMs:Integrated device manufacturers maintain captive test capabilities.
- Research Laboratories:University and government labs explore next-generation characterization methods.
Foundry procurement exceeds all other categories combined; assembly and test providers are expanding most quickly as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Germany and Japan while consumption clusters in Taiwan and South Korea where leading-edge foundries operate. This geographic split shapes vendor service infrastructure investments and regulatory compliance portfolios.
Taiwan
TSMC and UMC drive probe card and network analyzer procurement for sub-2nm development programs. The National Science and Technology Council coordinates semiconductor R&D subsidies under the Chip Implementation Act. Hsinchu Science Park hosts the densest concentration of BPDN validation workflows globally.
South Korea
Samsung Foundry and SK Hynix expand electrostatic discharge testing capacity for automotive qualification standards. The Ministry of Trade, Industry and Energy administers K-Chips Act tax credits for domestic equipment procurement. Pyeongtaek and Yongin semiconductor clusters anchor backside metrology demand.
United States
Intel and GlobalFoundries scale domestic BPDN analysis capabilities under CHIPS Act funding allocations. The Bureau of Industry and Security administers export controls restricting equipment shipments to specific Chinese fabs. Arizona and Ohio fab construction projects are attracting vendor service center investments.
Japan
Tokyo Electron and Shin-Etsu supply critical components while domestic foundries adopt hybrid focused ion beam systems. METI coordinates supply chain resilience initiatives under the Economic Security Promotion Act. Kyushu and Tohoku regions concentrate electron microscopy equipment manufacturing.
Germany
Infineon and Bosch semiconductor divisions specify REACH-compliant closed-loop etchant recovery systems. ECHA substance restrictions mandate chemical regeneration modules in plasma etch chambers. Dresden and Munich anchor equipment R&D and automotive qualification testing workflows.
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market Competitive Landscape
The competitive structure tilts toward diversified instrumentation conglomerates with electron microscopy heritage. Three to five multinational groups control premium-tier positioning through bundled test-cell offerings. Two strategic archetypes dominate: portfolio-anchored conglomerates leveraging microscopy-to-probe-card integration, and specialized defect inspection vendors mapping power via continuity. Competitive moves concentrate on multi-year service contracts and modular test-cell bundling agreements that span electron microscopy, probe cards, and network analyzers.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Hitachi High-Tech exemplify portfolio-anchored positioning through electron microscopy heritage. KLA occupies a specialist position in defect inspection systems for thinned wafer architectures. These three represent contrasting approaches to BPDN workflow integration: one leveraging analytical instrument breadth, another drawing on electron optics manufacturing scale, and the third focusing on process control specialization for advanced node validation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hitachi High-Tech |
| Carl Zeiss |
| JEOL |
| Bruker |
| Oxford Instruments |
| Keysight Technologies |
| KLA |
| Applied Materials |
| Others |
Pricing and Supply Chain Analysis
Foundry procurement consolidation toward multi-year test-cell bundling agreements is compressing vendor margins while elevating service infrastructure requirements, forcing equipment makers to absorb qualification overhead costs into headline pricing.
Pricing Analysis
Margin tightening in standard-tier probe card systems reflects foundry pressure for throughput guarantees bundled with calibration services. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive qualification configurations from general-purpose semiconductor testing platforms. Price differentiation hinges on ISO 17025 calibration certification and after-sales service bundling. Cost-down pressure on economy-tier thermal imaging tools accelerates because OSAT facilities in Malaysia and Vietnam prioritize minimal operator training requirements over measurement precision.
Supply Chain Analysis
Dual-sourcing mandates from TSMC and Samsung Foundry require helium-3 isotope suppliers to maintain parallel qualification tracks with Russian and Algerian extraction facilities. Component fabrication concentrates in Germany, Japan, and the United States. Focused ion beam systems draw from neon isotope feedstocks and precision electron optics manufacturing. Single-source vulnerability in helium-3 supply exposes vendors to geopolitical interruption. Distribution runs through direct vendor-foundry relationships with embedded field service engineers rather than third-party channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium-3 isotope supply concentration props pricing power for vendors with secured long-term offtake agreements, insulating premium-tier positioning against standard-tier margin erosion.
For Market Incumbents: Acquire cryogenic sample preparation capabilities to anchor hybrid focused ion beam system bundling. Defend against emerging Chinese equipment vendors by embedding ISO 17025 calibration laboratories within TSMC and Samsung Foundry campuses. Capacity addition in Arizona and Ohio under CHIPS Act funding creates captive service infrastructure leverage. For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting Indian OSAT facilities under PLI scheme incentives. White-space opportunity sits with failure diagnostics nano-probing for automotive semiconductor returns. The most penetrable segment is research laboratories exploring next-generation multi-physics characterization methods. For Investors and Strategic Acquirers: Re-rating potential sits with plasma etch specialists possessing closed-loop etchant recovery technology given REACH regulatory expansion. Long-term viability favors vendors with electron microscopy heritage capable of spanning metrology-to-probe-card integration. The signal to monitor is Bureau of Industry and Security export control expansion to additional Chinese fabrication facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Test-Cell Bundling Agreement | TSMC and UMC consolidation reduces vendor qualification overhead across electron microscopy portfolios. |
| Closed-Loop Etchant Recovery System Deployment | ECHA REACH mandates drive replacement cycles for legacy plasma etch chambers at Infineon and Bosch. |
| Cryogenic Sample Preparation Integration | Hybrid focused ion beam adoption in Taiwan and South Korea compresses test cycles from days to hours. |
| Field Service Infrastructure Expansion | Intel Arizona and GlobalFoundries Ohio projects attract vendor service center investments under CHIPS Act. |
| Automotive Qualification Certification Investment | AEC-Q100 rigor commands premium pricing for electrostatic discharge testing at Samsung Foundry. |
Research Methodology
Independent corroboration across foundry procurement executives, electron microscopy equipment engineers, and semiconductor process integration specialists underwrites the qualitative findings. Primary interviews with TSMC and Samsung Foundry capital committee members, KLA and Thermo Fisher Scientific product managers, and Bureau of Industry and Security licensing officers combined with secondary validation. Secondary sources include SEC 10-K equipment vendor filings, SEMI capital expenditure databases, and ECHA REACH substance restriction regulatory notices. Bottom-up equipment shipment tracking and top-down foundry capex allocation analysis provided triangulation.
Rate-of-change decomposition across technology adoption curves, process node migration timelines, and regulatory implementation schedules structured the analytical framework. Segmentation dimensions modeled include product type, technology tier, application maturity, and end-user capital intensity across the projection horizon. CAGRs derived from equipment shipment velocity correlated with foundry announced capacity expansion. Industry-specific forecast inputs incorporate ASML EUV lithography roadmaps and TSMC process node requirements.
The model assumes a particular technology adoption path; alternative pathways for hybrid focused ion beam convergence with network analyzer integration would alter the outlook. Forecasts reflect assumptions on helium-3 isotope supply continuity and Bureau of Industry and Security export control stability. Deviation in multilateral semiconductor equipment coordination would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.