
 Flow Meter Calibration Market | 2026-2036
Flow Meter Calibration Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Meter Calibration Market Foresight
Digital twin integration is tilting how calibration protocols are designed and executed across industrial facilities. Southwest Research Institute leverages its multi-fluid test loops to sustain leadership in high-pressure gas calibration. CEESI anchors its position through extensive pipe prover facilities in North America. Tektronix competes by extending electromagnetic flow meter validation into semiconductor-grade water systems.
Flow meter calibration encompasses the systematic comparison of a flow meter's output against a traceable reference standard under controlled fluid conditions, typically requiring Reynolds number matching and temperature compensation within 0.1% uncertainty. Its primary purpose is to certify measurement accuracy for custody transfer, process control, and regulatory compliance in continuous industrial operations. Ultrasonic and electromagnetic calibrations command premium service rates due to their dominance in water utility and energy generation applications where non-intrusive measurement preserves pipeline integrity. Automated calibration technology is displacing manual methods in pharmaceutical production environments where batch documentation and audit trails are mandatory.
The EPA mandates calibration traceability for continuous emissions monitoring systems under 40 CFR Part 75, while ISO 17025 accreditation governs laboratory competence for flow calibration certificates accepted across WTO member states. China's SAMR enforces GB/T standard updates that require recalibration intervals tied to fluid corrosivity classifications. Stakeholders must monitor how remote calibration protocols evolve under emerging cybersecurity frameworks before committing capital to distributed sensor networks.
Market Dynamics
Digital twin integration is compressing calibration cycle times and redefining traceability requirements across industrial facilities. Virtual validation environments now precede physical testing, altering capital deployment patterns for calibration infrastructure.
Growth Catalysts
- EPA 40 CFR Part 75 mandates:Continuous emissions monitoring systems require traceable calibration protocols, expanding service demand from power generation and petrochemical facilities.
- Ultrasonic meter proliferation:Non-intrusive measurement adoption in water utilities accelerates recertification volume for custody-transfer accuracy.
- Pharmaceutical batch documentation:Automated calibration systems with audit trails satisfy FDA validation requirements for sterile manufacturing environments.
Market Restraints
- Reference standard scarcity:Primary flow standards require specialized gravimetric facilities concentrated in Germany, the United States, and Japan, creating geographic bottlenecks.
- Skilled technician shortages:Reynolds number matching and uncertainty analysis expertise remains concentrated among aging specialist workforces.
- High-pressure gas loop capex:Multi-fluid test facilities demand capital intensity that excludes mid-tier service providers from hydrocarbon calibration markets.
Strategic Opportunities
- Brazilian water utility expansion:Sabesp and other regional operators are building calibration capabilities for large-diameter custody-transfer applications.
- Remote calibration protocols:Cybersecurity framework maturation enables distributed sensor network validation without physical site visits.
- Semiconductor-grade water systems:Electromagnetic meter validation for ultrapure water represents an underpenetrated niche with premium service rates.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory competence certification for flow calibration requires extended audit cycles that delay market entry.
- Legacy DCS integration:Automated calibration systems must interface with decades-old distributed control architectures in process industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Meter Calibration Market |
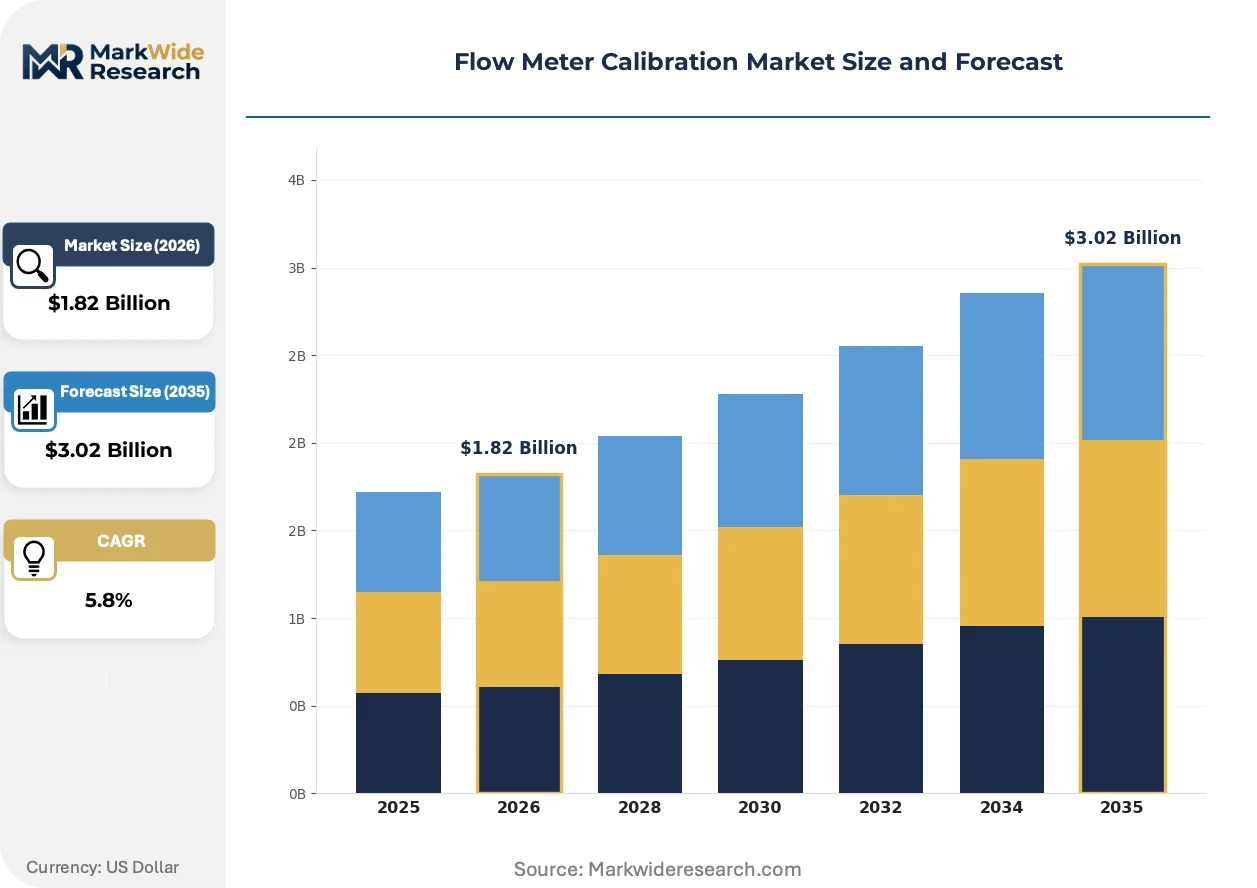
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Electromagnetic, Turbine, Differential Pressure, Vortex, Positive Displacement Technology: Manual Calibration, Automated Calibration, Inline Calibration, Portable Calibration, Remote Calibration Application: Chemical Processing, Water Treatment Plants, Energy Generation, Food & Beverage, Pharmaceutical Production End User: Oil Refining Facilities, Power Plants, Beverage Manufacturers, Pharmaceutical Labs, Water Utilities |
| Companies Covered | Southwest Research Institute, CEESI, Tektronix, Micro Precision Calibration, Fox Valley Metrology, Verdantas Flow Labs, Badger Meter, SwRI, Applied Technical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Meter Calibration Market Shifts & Advancements
Calibration protocols are migrating from physical test benches to synthetic environments, compressing validation timelines while preserving traceability chains. This shift demands new competencies in computational fluid dynamics and sensor fusion.
Digital twin platforms are virtualizing calibration execution before physical verification occurs. Pharmaceutical manufacturers in Germany deploy these environments to pre-validate batch protocols, reducing physical testing cycles by half. The technology is virtualizing documentation workflows, enabling real-time audit trail generation that satisfies regulatory inspection requirements.
China's SAMR enforcement of GB/T standard updates tightens recertification intervals based on fluid corrosivity classifications. Industrial facilities must now maintain dynamic calibration schedules rather than fixed periodicity. Chemical processing and wastewater treatment operations face the steepest compliance burden under these tiered requirements.
Service unbundling separates hardware calibration from ongoing accuracy verification contracts. Water utilities in Japan and South Korea now procure discrete validation events rather than bundled maintenance agreements. This pattern concentrates purchasing power among large municipal operators while fragmenting revenue streams for service providers.
Flow Meter Calibration Market Segmentation
Flow meter calibration segments diverge sharply in service intensity, with custody-transfer applications demanding continuous traceability while process control environments tolerate longer intervals between recertification. Technology choices determine whether providers capture recurring revenue through automated validation or episodic income from manual interventions.
Product Type:
After-sales-service intensity varies dramatically across meter technologies, with ultrasonic and electromagnetic units requiring specialized non-intrusive validation protocols that sustain long-term service relationships.
- Ultrasonic:Non-intrusive measurement using transit-time or Doppler principles eliminates pressure drop and preserves pipeline integrity. Water utilities in Germany and Japan concentrate procurement here, driven by custody-transfer mandates for large-diameter distribution networks where shutdown costs prove prohibitive.
- Electromagnetic:Faraday's law-based measurement delivers accuracy across conductive fluids without moving parts. Pharmaceutical labs in South Korea and semiconductor fabs deploy these for ultrapure water systems, where FDA validation requirements and particle-free operation create premium calibration service tiers.
- Turbine:Rotor-based mechanical measurement suits clean, low-viscosity hydrocarbons with predictable flow profiles.
- Differential Pressure:Orifice plate and venturi configurations dominate legacy installations in chemical processing.
- Vortex:Shedding frequency measurement withstands high-temperature steam applications in power generation.
- Positive Displacement:Oval gear and piston mechanisms excel in high-viscosity fluid metering for oil refining custody transfer.
Ultrasonic holds the largest share; momentum sits with electromagnetic as pharmaceutical and semiconductor applications expand.
Technology:
Cost tier separation distinguishes capital-intensive automated installations from labor-dependent manual methods, with mid-tier providers struggling to bridge the capability gap.
- Automated Calibration:Robotic test benches execute Reynolds number matching and temperature compensation without technician intervention. Pharmaceutical manufacturers in Germany deploy these systems to satisfy FDA batch documentation requirements, where audit trail automation justifies premium capital expenditure.
- Manual Calibration:Technician-operated gravimetric or volumetric reference standards remain prevalent in emerging markets. Brazilian water utilities rely on these methods for large-diameter meter verification where automated infrastructure investment lags.
- Inline Calibration:Prover loop integration enables verification without process interruption.
- Portable Calibration:Mobile reference standards serve distributed asset bases in pipeline networks.
- Remote Calibration:Sensor network validation via secure protocols is gaining traction as cybersecurity frameworks mature.
Manual calibration still dominates transaction volume; automated systems are climbing the fastest as regulatory documentation requirements tighten.
Application:
Volume concentration in water infrastructure creates scale economies for service providers, while pharmaceutical and food segments generate margin through compliance complexity.
- Water Treatment Plants:Municipal and industrial facilities require continuous accuracy verification for regulatory reporting and custody transfer. EPA mandates under 40 CFR Part 75 and China's MEE enforcement of GB/T standards drive recertification frequency in US and Chinese utilities.
- Pharmaceutical Production:Sterile manufacturing environments demand automated calibration with electronic batch records. FDA validation requirements and EU GMP Annex 15 guidelines create sticky service relationships with documentation-intensive providers.
- Chemical Processing:Corrosive fluid handling accelerates meter degradation and shortens calibration intervals.
- Energy Generation:Steam and cooling water measurement supports plant efficiency optimization.
- Food & Beverage:Hygienic design requirements constrain calibration method selection.
Water treatment plants hold the largest share; pharmaceutical production shows the steepest expansion trajectory as biologics manufacturing scales.
End User:
Customer type determines procurement sophistication, with integrated oil companies and multinational pharmas demanding global service consistency while municipal utilities prioritize local response capability.
- Water Utilities:Municipal operators across Germany, Japan, and Brazil manage extensive meter fleets with varying ages and technologies. Sabesp and Tokyo Metropolitan Waterworks concentrate procurement among accredited laboratories with ISO 17025 certification and documented uncertainty budgets.
- Pharmaceutical Labs:sterile manufacturing facilities require calibration partners capable of cleanroom entry and electronic signature compliance. South Korean and German operations lead adoption of automated validation to minimize human intervention in aseptic processes.
- Oil Refining Facilities:custody-transfer accuracy requirements drive high-pressure gas calibration demand.
- Power Plants:continuous emissions monitoring mandates sustain recurring service contracts.
- Beverage Manufacturers:CIP-compatible calibration methods support hygienic production lines.
Water utilities hold the largest share; pharmaceutical labs are gaining share fastest as bioprocessing capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration service trade flows heavily favor Germany, the United States, and Japan as net exporters of primary standard gravimetric verification, while Brazil and China remain import-dependent for high-pressure gas loop certification. Cross-border service procurement concentrates among laboratories holding dual EPA and ISO 17025 accreditations.
United States
Power generation utilities drive continuous emissions monitoring calibration demand under EPA 40 CFR Part 75 mandates. The EPA enforces traceability requirements for stack flow measurement systems serving coal and natural gas plants. Houston and the Gulf Coast petrochemical corridor anchor high-volume custody-transfer calibration services for hydrocarbon pipelines.
Germany
Water utilities in Bavaria and North Rhine-Westphalia expand ultrasonic meter recertification programs for large-diameter distribution networks. The country's national measurement institute maintains primary flow standards that attract cross-border pharmaceutical clients from Switzerland and Austria. Stuttgart's industrial automation cluster deploys automated calibration systems for FDA-validated batch manufacturing.
China
GB/T standard updates from SAMR compress recalibration intervals for corrosive fluid applications in chemical processing. Municipal water operators in the Yangtze River Delta build captive calibration capabilities to reduce dependence on imported reference standards. Shanghai's semiconductor fabrication parks drive electromagnetic meter validation demand for ultrapure water systems.
Brazil
Sabesp and regional water operators invest in large-diameter custody-transfer calibration infrastructure for São Paulo's distribution network. ANVISA alignment with international measurement standards accelerates pharmaceutical lab accreditation requirements. Rio de Janeiro's offshore oil services cluster imports high-pressure gas calibration from US and European laboratories.
Japan
Tokyo Metropolitan Waterworks concentrates procurement among ISO 17025 laboratories with documented uncertainty budgets for aging meter fleet management. METI efficiency standards tighten accuracy requirements for industrial steam measurement in power generation. Osaka's pharmaceutical manufacturing belt adopts automated calibration to minimize cleanroom human intervention.
Flow Meter Calibration Market Competitive Landscape
On the supply side, the industry is bifurcated between capital-intensive primary standard laboratories and specialized service providers. Gravimetric and pipe prover facilities demand multi-million dollar infrastructure that excludes mid-tier entrants. Two strategic archetypes dominate: integrated research institutes with multi-fluid test loops, and focused calibration laboratories serving single-industry verticals. Competitive positioning hinges on accreditation breadth and geographic proximity to custody-transfer infrastructure. Consolidation pressure concentrates among regional laboratories seeking ISO 17025 expansion into adjacent fluid types.
Within the research institute tier, Southwest Research Institute and CEESI exemplify capital-heavy positioning through extensive test loop infrastructure. Tektronix occupies a position among technology-originated providers extending electromagnetic validation into semiconductor-grade water applications. These three entities represent distinct geographic and capability anchors—San Antonio-based multi-fluid testing, Colorado-centered pipe prover facilities, and Oregon-originated precision electronics calibration.
| Leading Market Players |
|---|
| Southwest Research Institute |
| CEESI |
| Tektronix |
| Micro Precision Calibration |
| Fox Valley Metrology |
| Verdantas Flow Labs |
| Badger Meter |
| SwRI |
| Applied Technical Services |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese primary gravimetric facilities determines both tiered pricing spreads across certification grades and the elongated supply chain shape for high-pressure gas calibration. Tariff exposure on imported reference standards from these concentration points compresses margins for mid-tier service providers while amplifying premium capture by accredited laboratories with captive standard capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to ISO 17025-accredited certificates with documented uncertainty budgets for custody-transfer applications, while economy tiers serve process control environments with reduced traceability requirements. Cost compression in the standard tier intensifies because Brazilian and Chinese utilities are building captive calibration capabilities. Pharmaceutical labs exhibit the lowest price sensitivity due to FDA validation requirements, whereas municipal water utilities concentrate purchasing power to extract volume discounts.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize procurement relationships between water utilities and calibration service providers, straining working capital for mid-tier laboratories. Primary flow standard manufacturing concentrates in Germany, the United States, and Japan, with specialized gravimetric facilities drawing from precision-machined orifice plates, traceable mass standards, and temperature-controlled test loops. Single-source vulnerability on high-pressure gas loop components creates bottlenecks for hydrocarbon calibration services. Distribution runs through accredited laboratory networks with regional service territories rather than integrated national platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow meter calibration represents a service-attach opportunity where recurring validation contracts expand faster than hardware sales as regulatory documentation requirements tighten across pharmaceutical and water utility verticals.
For Market Incumbents: Pre-empt margin erosion in manual calibration services by accelerating automated system deployment for FDA-validated pharmaceutical environments. Capture backward integration into primary standard manufacturing through partnerships with German and Japanese national measurement institutes. Defensive consolidation of regional ISO 17025 laboratories in Brazil and China blocks emerging competitor access to custody-transfer infrastructure. For New Entrants and Emerging Players: Build out semiconductor-grade water calibration capabilities in South Korea and China's Yangtze River Delta, where electromagnetic meter validation for ultrapure systems remains underpenetrated. Target remote calibration protocol development as cybersecurity frameworks mature, enabling distributed sensor network validation without physical site presence. Partner with industrial automation OEMs to embed calibration modules within smart meter product lines. For Investors and Strategic Acquirers: EPA 40 CFR Part 75 enforcement reshapes the acquisition landscape by concentrating service demand among dual-accredited laboratories with continuous emissions monitoring expertise. Over the coming decade, laboratories with multi-fluid test loops and documented uncertainty budgets represent the most defensible acquisition profile. Watch for SAMR acceleration of GB/T recalibration interval compression as the signal indicating Chinese captive capability buildout versus continued import dependence.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Calibration System Deployment | Pharmaceutical manufacturers in Germany deploy robotic test benches to satisfy FDA batch documentation requirements. |
| ISO 17025 Accreditation Expansion | Regional laboratories in Brazil pursue certification to capture Sabesp custody-transfer calibration procurement. |
| Remote Calibration Protocol Development | Cybersecurity framework maturation enables distributed sensor network validation without physical site visits. |
| Multi-Fluid Test Loop Investment | High-pressure gas calibration capabilities anchor positioning in hydrocarbon custody-transfer markets. |
| Digital Twin Integration | Virtual validation environments compress physical testing cycles while preserving traceability chains. |
Research Methodology
A standing panel of calibration laboratory directors, pharmaceutical manufacturing engineers, water utility procurement managers, and aftermarket service heads provided ongoing calibration of demand assumptions across the analysis window. Primary fieldwork with these stakeholders combined with secondary validation from EPA enforcement records, SAMR GB/T standard publications, ISO 17025 accreditation databases, and customs trade data on reference standard imports. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario bracketing around regulatory enforcement intensity, captive capability buildout rates, and automation adoption curves shaped the projection framework. The analysis modeled meter technology type, calibration method, application vertical, and end-user sophistication across the modeling period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators for industrial investment and utility capital expenditure. Industry-specific inputs included pharmaceutical batch documentation mandate expansion and water utility privatization trajectories in Brazil and Japan.
Stress conditions across tariff escalation on German and Japanese reference standards, accelerated SAMR recalibration interval compression, and semiconductor fabrication capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology adoption S-curves. Macroeconomic contraction, regulatory enforcement delays, or breakthroughs in virtual calibration accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Hour Meter Market
Test and Measurement
Telescopic Inspection Mirror Market