
 Miniaturized Package Solder Joint Reliability Test Equipment Market | 2026-2036
Miniaturized Package Solder Joint Reliability Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Miniaturized Package Solder Joint Reliability Test Equipment Market Insights
Modular thermal cycling systems bundled with vibration testing units is pivoting buyer preference away from standalone machines toward integrated reliability suites. Instron leverages its materials testing heritage to anchor premium positioning in mechanical shock equipment. Koh Young Technology competes through automated optical inspection integration with solder joint stress test workflows. Nordson Test & Inspection extends its electronics assembly equipment footprint into adjacent validation stages.
Miniaturized package solder joint reliability test equipment encompasses systems that subject solder interconnects to thermal, mechanical, and electrical stress sequences to predict failure modes in chip-scale and wafer-level packages, typically operating across temperature ranges from minus 65 degrees Celsius to 150 degrees Celsius with cycle counts exceeding one thousand iterations. The equipment serves semiconductor packaging houses and PCB assembly lines by quantifying crack propagation, intermetallic growth, and electrical continuity degradation before field deployment. Thermal cycling systems and vibration testing units command the largest installed base due to their alignment with JEDEC JESD22-A104 and MIL-STD-883 test protocols, while X-ray imaging and ultrasonic inspection segments within non-destructive testing technology capture expanding share as hidden solder defect detection becomes critical for flip-chip and underfilled packages. Bend test machines and fatigue test apparatus remain specialized margin pools serving aerospace component verification and automotive electronics qualification where strain-rate sensitivity demands custom fixturing.
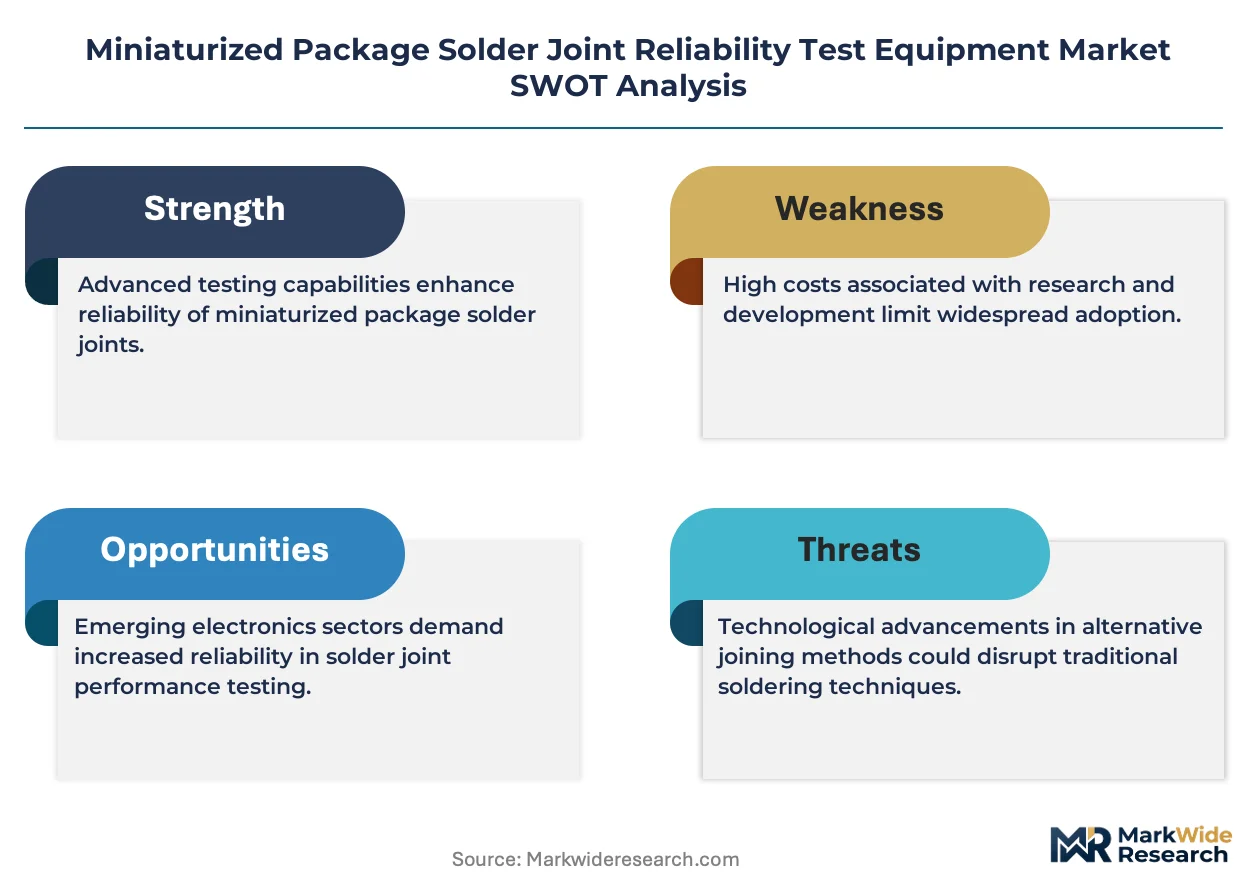
IEC thermal cycling standards, IPC J-STD-001 solderability requirements, and JEDEC JESD22 mechanical test methods collectively define acceptance thresholds that equipment must reproduce to qualify for supplier approval at tier-one semiconductor firms. The US FAA and DoD procurement branches enforce MIL-STD-883 and MIL-STD-202 test equivalency for solder joint reliability in avionics and defense microelectronics, restricting market access to vendors with demonstrated traceability. Stakeholders must monitor evolving JEDEC standards for heterogeneous integration packages and assess whether existing thermal cycling system architectures accommodate the expanded temperature gradients and joint densities of chiplet-based designs.

Market Dynamics
Chiplet architectures and 2.5D/3D integration are multiplying solder joint counts per device, forcing packaging houses to expand thermal cycling and mechanical stress validation capacity at rates outpacing traditional single-die qualification workflows.
Growth Catalysts
- JEDEC JESD22-A104 thermal cycling protocols:Tier-one semiconductor firms mandate compliance for supplier approval, driving automated test platform procurement across Taiwan, South Korea, and the United States.
- Automotive electronics qualification:Electric vehicle powertrain controllers and ADAS modules require fatigue test apparatus meeting AEC-Q100 stress standards, expanding addressable equipment demand.
- Underfilled flip-chip packages:Hidden solder defect detection needs are accelerating X-ray imaging and ultrasonic inspection segment expansion in advanced packaging lines.
Market Restraints
- High-purity helium supply volatility:Thermal cycling systems depend on helium for extreme temperature control, with price swings constraining test facility operating budgets.
- Equipment vendor concentration in East Asia:Core component sourcing from Taiwan and South Korea creates geographic supply risk for Western packaging houses.
- MIL-STD-883 equivalency barriers:FAA and DoD traceability requirements restrict market access for vendors without demonstrated aerospace qualification histories.
Strategic Opportunities
- India semiconductor packaging:PLI scheme incentives for display and specialty fab capacity are creating greenfield test equipment demand as domestic assembly scales.
- AI accelerator chiplet validation:Heterogeneous integration packages with expanded temperature gradients require next-generation thermal cycling architectures.
- Non-destructive testing convergence:Automated optical inspection integration with solder joint stress workflows is opening premium service contract models.
Industry Challenges
- Reliability engineering talent scarcity:Packaging houses in the United States and Germany report acute shortages of engineers trained in JEDEC mechanical test method interpretation.
- Legacy system integration friction:New modular thermal cycling suites face protocol compatibility issues with existing data management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniaturized Package Solder Joint Reliability Test Equipment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cycling Systems, Vibration Testing Units, Mechanical Shock Equipment, Bend Test Machines, Fatigue Test Apparatus Technology: Accelerated Life Testing, Non-Destructive Testing, Ultrasonic Inspection, Electrical Resistance Analysis, X-ray Imaging Application: Semiconductor Packaging, PCB Assembly Validation, Microelectronics Quality Control, Consumer Electronics Testing, Aerospace Component Verification End User: Contract Manufacturers, OEMs, Electronics Test Labs, Quality Assurance Departments, Research Institutes |
| Companies Covered | Instron, Shimadzu, Nordson Test & Inspection, Koh Young Technology, Hitachi High-Tech, Bruker, ZwickRoell, Thermo Fisher Scientific, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniaturized Package Solder Joint Reliability Test Equipment Market Trends and Innovations
Modular platform architectures are displacing standalone machines as packaging houses seek integrated reliability suites that compress qualification timelines and reduce floor space requirements.
Hybrid thermal-mechanical test systems are consolidating vibration and cycling capabilities into single-chamber platforms. Packaging houses in Taiwan and South Korea are adopting these units to accommodate chiplet-based designs with denser interconnect arrays. The consolidation is compressing capital deployment cycles and reducing per-joint qualification costs.
REACH substance restrictions on lead-free solder alloys are forcing equipment recalibration for tin-silver-copper intermetallic growth monitoring. European packaging houses must demonstrate RoHS-compliant solder joint reliability under revised thermal cycling profiles. This regulatory pressure is accelerating replacement demand for aging test platforms.
Contract manufacturers are unbundling after-sales calibration services from equipment purchases, creating recurring revenue streams for specialized service providers. This shift is visible in South Korea's OSAT sector, where packaging houses prefer per-test pricing over capital ownership. The model is spreading to United States-based fabless semiconductor firms operating captive validation labs.
Miniaturized Package Solder Joint Reliability Test Equipment Market Segmentation
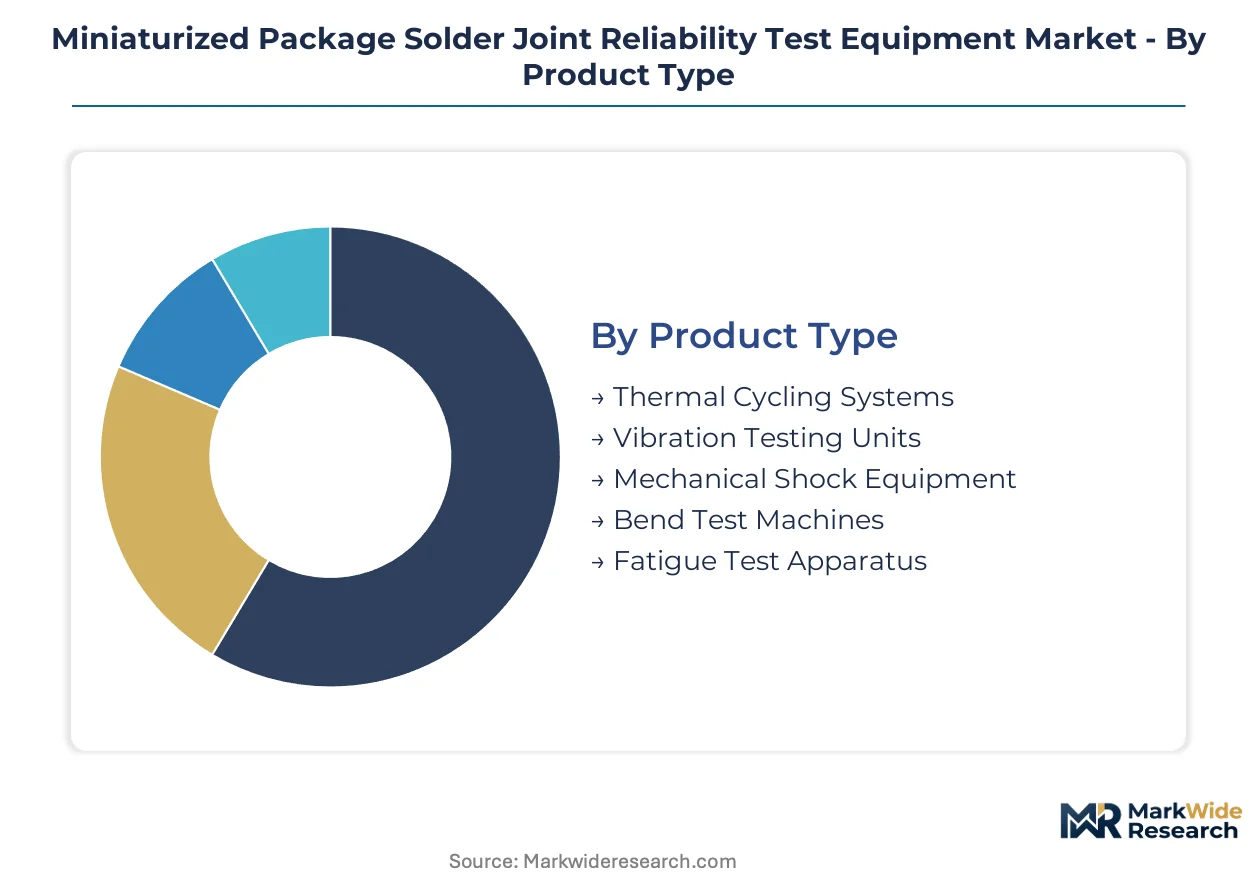
Solder joint reliability testing demands divergent equipment configurations depending on whether validation occurs inline during packaging or as standalone qualification. Segmentation reveals how thermal cycling and mechanical stress platforms serve distinct integration depths across semiconductor manufacturing workflows.
Product Type:
Thermal cycling systems anchor standalone reliability labs, while mechanical shock equipment increasingly embeds directly into packaging lines for real-time screening.
- Thermal Cycling Systems:These platforms execute JEDEC JESD22-A104 protocols across temperature ranges from minus 65 degrees Celsius to 150 degrees Celsius with automated cycle counting. Taiwan and South Korea packaging houses deploy these as centralized qualification assets for chiplet-based designs multiplying joint counts per device.
- Vibration Testing Units:Electrodynamic shakers apply frequency-swept mechanical stress to detect solder fatigue under operational vibration profiles. Automotive electronics qualification for electric vehicle powertrain controllers drives procurement at AEC-Q100 compliant facilities in the United States and Germany.
- Mechanical Shock Equipment:Drop towers and impulse generators simulate handling and transportation stresses. Aerospace component verification mandates MIL-STD-883 equivalency for avionics suppliers.
- Bend Test Machines:Strain-rate controlled flexure testers measure solder joint durability under board-level mechanical loading. PCB assembly validation lines in Japan integrate these for RoHS-compliant lead-free alloy characterization.
- Fatigue Test Apparatus:Cyclic load frames quantify crack propagation rates in underfilled flip-chip interconnects. Research institutes employ custom fixturing for heterogeneous integration package development.
Thermal cycling systems lead volumes today; mechanical shock equipment is gaining share fastest through inline integration.
Technology:
Destructive accelerated life testing dominates volume applications, while non-destructive modalities capture premium positioning for hidden defect detection in advanced packages.
- Accelerated Life Testing:Combined thermal-mechanical stress protocols compress years of field aging into weeks of laboratory testing. Contract manufacturers in Taiwan rely on these methods for high-volume consumer electronics qualification.
- Non-Destructive Testing:X-ray imaging and ultrasonic inspection modalities detect voids, cracks, and intermetallic growth without sample destruction. Flip-chip and underfilled package proliferation in South Korea drives segment expansion.
- Ultrasonic Inspection:High-frequency acoustic microscopy identifies delamination and crack initiation at solder-pad interfaces. Quality assurance departments prioritize this for automotive radar module validation.
- Electrical Resistance Analysis:In-situ continuity monitoring during thermal cycling captures intermittent failure modes. PCB assembly validation lines integrate these sensors for real-time process feedback.
- X-ray Imaging:Computed tomography systems reconstruct three-dimensional solder joint geometries for dimensional analysis. Aerospace component verification requires FAA-traceable inspection records.
Accelerated life testing commands the largest installed base; non-destructive testing climbs the fastest as hidden defect detection becomes critical.
Application:
Semiconductor packaging applications concentrate capital deployment, while aerospace verification sustains specialized margin pools through stringent traceability requirements.
- Semiconductor Packaging:Wafer-level and chip-scale package validation drives thermal cycling capacity expansion. Taiwan packaging houses multiply test cell counts to accommodate 2.5D/3D integration architectures.
- PCB Assembly Validation:Board-level solder joint qualification supports high-volume electronics manufacturing. Contract manufacturers in South Korea integrate bend test and vibration capabilities into production lines.
- Microelectronics Quality Control:Incoming inspection and process monitoring protocols ensure joint integrity across assembly stages. OEMs in the United States operate captive labs for fabless semiconductor partners.
- Consumer Electronics Testing:Smartphone and wearable device qualification emphasizes compact equipment footprints. Electronics test labs favor modular thermal cycling suites with reduced floor space requirements.
- Aerospace Component Verification:MIL-STD-883 and MIL-STD-202 equivalency mandates restrict supplier qualification to vendors with demonstrated defense traceability. FAA procurement branches enforce test method documentation standards.
Semiconductor packaging anchors current demand; aerospace verification maintains the steepest pricing premiums.
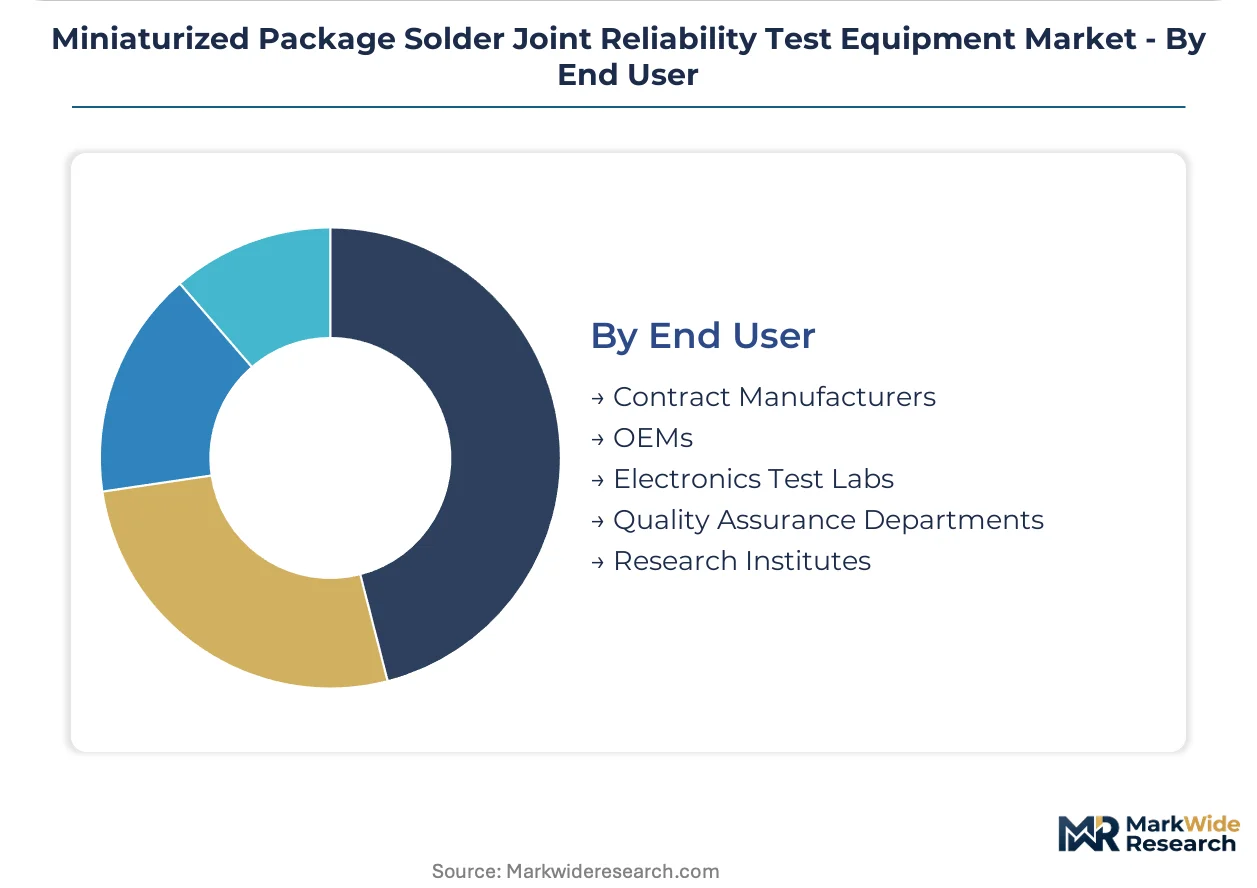
End User:
Contract manufacturers and OEMs split procurement patterns between outsourced qualification services and captive validation infrastructure.
- Contract Manufacturers:OSATs and EMS providers operate high-throughput reliability labs serving multiple semiconductor clients. South Korean packaging houses are unbundling after-sales calibration services toward per-test pricing models.
- OEMs:Integrated device manufacturers and automotive tier-one suppliers maintain proprietary test capabilities. United States-based fabless firms operate captive validation labs for chiplet architecture development.
- Electronics Test Labs:Independent validation facilities provide third-party certification for regulatory compliance. European packaging houses demonstrate RoHS-compliant solder joint reliability under REACH substance restrictions.
- Quality Assurance Departments:Incoming inspection and supplier audit functions deploy portable mechanical stress equipment. Automotive electronics qualification demands AEC-Q100 documented test traceability.
- Research Institutes:University and government laboratories develop next-generation test protocols for heterogeneous integration. India's PLI scheme incentives are creating greenfield test equipment demand as domestic assembly scales.
Contract manufacturers lead equipment procurement volumes today; research institutes are expanding fastest through government-funded packaging initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The semiconductor test equipment industry traces its commercial origins to post-war American electronics manufacturing, with subsequent scaling concentrated in East Asian packaging corridors during the 1980s and 1990s. Equipment procurement patterns today reflect this bifurcated heritage: legacy semiconductor ecosystems in the United States and Germany sustain premium-tier demand, while Taiwan and South Korea drive volume expansion through OSAT capacity buildouts.
Taiwan
TSMC and ASE Holdings operate the world's densest concentration of advanced packaging lines, multiplying thermal cycling system deployments for chiplet-based designs. The National Development Council's semiconductor industry support programs subsidize reliability lab infrastructure at Hsinchu Science Park facilities. Tainan's Southern Taiwan Science Park anchors the fastest-growing cluster of heterogeneous integration test capacity.
South Korea
Samsung Electronics and SK Hynix captive packaging divisions procure hybrid thermal-mechanical test systems for 2.5D memory-logic integration. MFDS-aligned quality frameworks for automotive electronics push AEC-Q100 compliance investments at Pyeongtaek and Icheon campuses. The government's K-Semiconductor Belt initiative channels funding toward domestic test equipment vendor development.
United States
Intel, AMD, and Qualcomm operate captive validation labs for fabless semiconductor partners, concentrating thermal cycling capacity in Oregon, Arizona, and California. FAA and DoD procurement branches enforce MIL-STD-883 traceability requirements that restrict supplier qualification to vendors with demonstrated aerospace histories. The CHIPS Act fabrication subsidies are triggering packaging co-location investments in the Southwest and Midwest.
China
JCET and Tongfu Microelectronics expand OSAT capacity for domestic consumer electronics supply chains, driving procurement of modular reliability suites. MIIT's GB standards for microelectronics reliability push equipment localization requirements at Suzhou and Wuxi industrial parks. Yangtze River Delta packaging clusters face equipment import substitution pressures under dual carbon goals.
Germany
Infineon and Bosch automotive electronics divisions sustain specialized demand for fatigue test apparatus meeting AEC-Q100 strain-rate specifications. KBA vehicle type approval frameworks extend reliability documentation requirements to solder joint validation stages. Dresden's Silicon Saxony cluster concentrates research institute procurement for next-generation heterogeneous integration protocols.
Miniaturized Package Solder Joint Reliability Test Equipment Market Competitive Landscape
The competitive structure tilts toward diversified precision instrumentation conglomerates with materials testing heritage. Market participation splits between consolidated multi-divisional groups and specialized semiconductor equipment pure-plays. Three archetypes dominate: universal testing machine manufacturers extending into microelectronics, automated optical inspection vendors integrating stress test workflows, and electronics assembly equipment suppliers expanding into adjacent validation stages. Competitive dynamics center on modular platform bundling and after-sales service contract unbundling.
Within the materials testing heritage tier, Instron and ZwickRoell exemplify archetypes leveraging mechanical testing legacies into solder joint reliability applications. Shimadzu occupies a position bridging analytical instrumentation and semiconductor process equipment. Among semiconductor-focused specialists, Koh Young Technology and Nordson Test & Inspection represent contrasting integration strategies—AOI-centric versus assembly equipment-centric. Hitachi High-Tech and Bruker anchor the analytical instrumentation vector, while Keysight Technologies sits within the electronic measurement domain extending into validation workflows.
| Leading Market Players |
|---|
| Instron |
| Shimadzu |
| Nordson Test & Inspection |
| Koh Young Technology |
| Hitachi High-Tech |
| Bruker |
| ZwickRoell |
| Thermo Fisher Scientific |
| Keysight Technologies |
| Others |
Pricing and Supply Chain Analysis
Helium spot price volatility at industrial gas exchanges cascades through thermal cycling system manufacturing into three-tier pricing structures across premium, standard, and economy equipment levels, with Taiwan and South Korea packaging houses absorbing upstream cost shocks through long-term service contracts while Western buyers face spot-market exposure.
Pricing Analysis
Per-test pricing models with unbundled calibration services are displacing capital ownership structures in East Asian OSAT procurement. Price differentiation separates MIL-STD-883 traceable systems from commercial-grade thermal cycling platforms, with aerospace certification premiums widening as FAA documentation requirements tighten. Cost compression in standard-tier equipment intensifies because Chinese domestic vendors localize component sourcing under MIIT equipment substitution mandates. Contract manufacturers exhibit highest price sensitivity due to per-joint qualification cost pressures, while aerospace verification labs maintain lowest sensitivity given traceability compliance requirements.
Supply Chain Analysis
Ocean freight rate fluctuations from East Asian ports to European and North American packaging corridors directly impact landed equipment costs for modular thermal cycling suites. Component manufacturing concentrates in Taiwan, South Korea, and Japan, with precision temperature control modules and electrodynamic shaker assemblies drawing from specialized machine tool ecosystems in Osaka and Taichung. Single-source vulnerability sits with high-purity helium supply chains from Qatar and Algeria. Distribution runs through semiconductor equipment distributors with captive service engineering teams at Hsinchu, Pyeongtaek, and Phoenix industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where JEDEC JESD22-A104 protocol updates automatically trigger equipment replacement cycles across tier-one semiconductor supplier bases.
For Market Incumbents: Anchor defensive positioning through backward integration into precision temperature control module production, reducing exposure to helium supply volatility and Japanese machine tool lead times. Expand MIL-STD-883 equivalency certification portfolios to capture aerospace verification margin pools before emerging Chinese vendors achieve traceability documentation. Defend against modular platform unbundling by embedding predictive maintenance software into thermal cycling system architectures. For New Entrants and Emerging Players: Begin with India's PLI scheme subsidized packaging corridors, where greenfield reliability lab infrastructure creates first-mover equipment procurement opportunities without incumbent replacement friction. Target automotive electronics qualification segments in Germany and the United States where AEC-Q100 compliance documentation gaps exist among mid-tier OSATs. Pursue automated optical inspection integration partnerships as the primary go-to-market angle, leveraging existing machine vision deployment relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fatigue test apparatus manufacturers serving heterogeneous integration package development, where research institute procurement accelerates through government-funded semiconductor packaging initiatives. Long-term viability favors vendors with demonstrated JEDEC standards committee participation and evolving protocol adaptation capabilities. Watch for inflection signals in chiplet architecture adoption rates at TSMC and Intel, which directly correlate with thermal cycling capacity expansion announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Integration | Consolidated thermal-mechanical test systems compress qualification timelines at Taiwan packaging houses. |
| Non-Destructive Testing Convergence | AOI integration with stress workflows opens premium service contracts in South Korean OSAT sector. |
| Helium Supply Diversification | Alternative cryogenic cooling architectures reduce operating cost exposure for high-volume test facilities. |
| JEDEC Standards Committee Participation | Early protocol visibility enables equipment architecture adaptation before mandate effective dates. |
| Per-Test Pricing Model Expansion | Recurring revenue streams shift capital ownership risk from packaging houses to equipment vendors. |
Research Methodology
Coverage spans Taiwan, South Korea, the United States, China, and Germany, with primary inputs from each territory combining reliability engineering directors at OSATs, semiconductor packaging procurement managers, thermal cycling system field service engineers, and JEDEC standards committee participants. Secondary validation draws from SEC 10-K equipment vendor filings, IEC thermal cycling protocol documentation, MIIT equipment localization mandates, and customs trade data for thermal chamber imports. Bottom-up equipment unit deployment tracking triangulates against top-down packaging capacity expansion announcements.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon, with segmentation modeling across product type, technology modality, application depth, and end-user procurement archetype. CAGRs derive from installed base replacement cycles, greenfield capacity buildout timelines, and protocol-driven equipment obsolescence patterns. Industry-specific forecast inputs include chiplet architecture adoption curves, helium price trajectory assumptions, and automotive electronics AEC-Q100 qualification volume projections.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, breakthrough non-thermal reliability validation technologies, and semiconductor demand cyclicality beyond packaging capacity planning horizons. Forecasts reflect assumptions about JEDEC protocol evolution timelines and helium supply chain stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Density Meter Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
United States Borescope Market
Test and Measurement
Electrolyzer Test System Market