

AI-Enabled Semiconductor Defect Classification and Review Systems Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Enabled Semiconductor Defect Classification and Review Systems Market Insights
Foundries and advanced packaging houses are redrawing procurement priorities for defect review equipment. KLA leverages its installed base of inspection tools to extend into AI-classification software layers. Applied Materials anchors its position through backward integration into process control modules. Tokyo Electron competes with specialized electron-beam review systems tuned for sub-3nm node requirements.
AI-enabled semiconductor defect classification and review systems combine machine vision hardware with deep learning inference engines to automatically categorize wafer anomalies, lithography errors, and packaging faults at throughput rates exceeding manual review by orders of magnitude. These systems serve the essential commercial purpose of protecting yield in fabs where single defect excursions can scrap millions of dollars of silicon. Deep learning architectures now lead technology adoption as convolutional neural networks prove superior at classifying novel defect morphologies unseen in training data. Wafer inspection remains the largest application segment by installed base, though advanced packaging quality control is expanding fastest as heterogeneous integration multiplies inspection points per device. Cloud-based deployment is gaining share among foundries seeking centralized model retraining across geographically distributed fabs.
ISO 9001 quality management frameworks and IEC 61508 functional safety standards shape product certification requirements for equipment sold into automotive chip supply chains. The EU AI Act imposes conformity obligations on automated classification systems deployed in European fabs, pushing vendors to document algorithmic decision boundaries. The U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment to China are fragmenting regional supply strategies. Stakeholders must monitor whether national security restrictions expand to cover AI inference software bundled with inspection hardware.
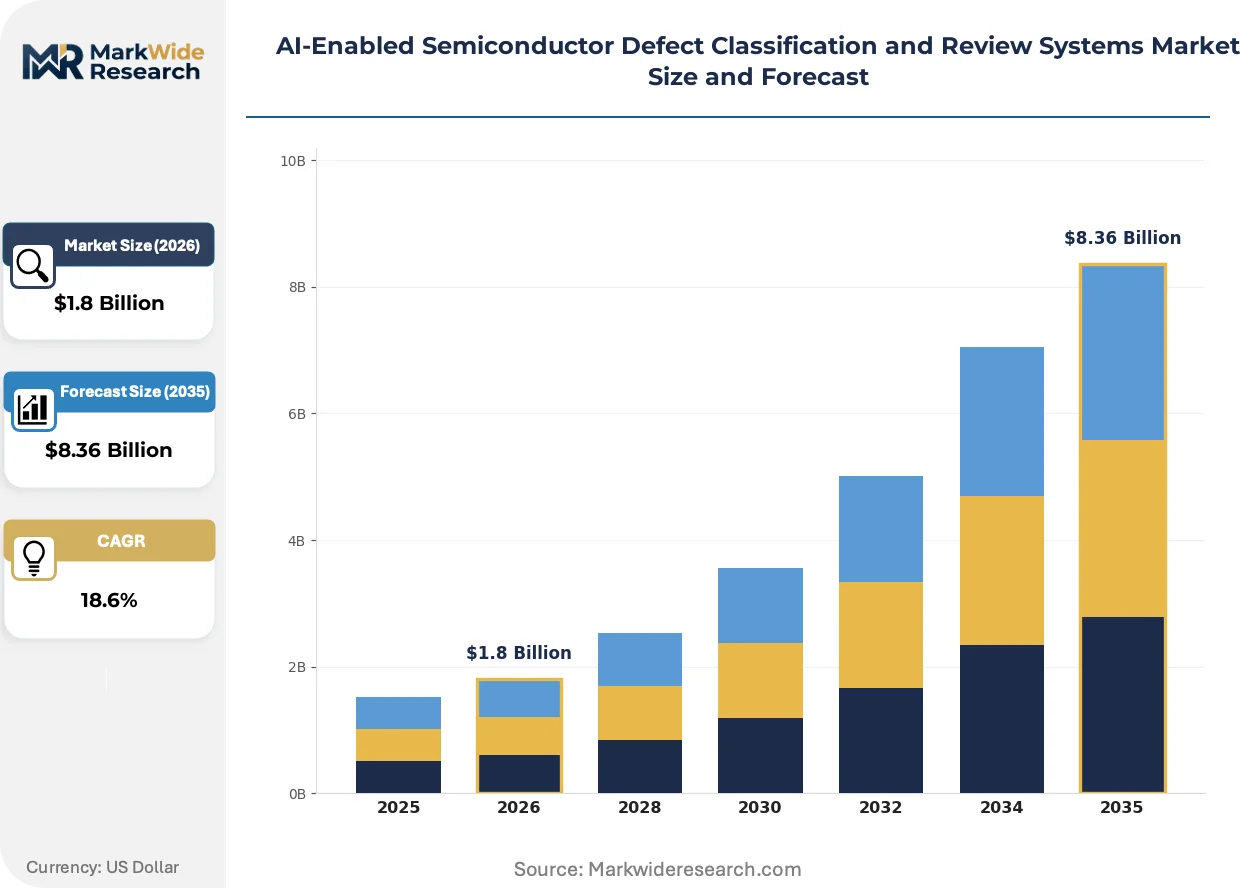
Market Dynamics
The EU AI Act is tightening algorithmic transparency requirements for automated defect classification systems deployed in European fabs, forcing vendors to document decision boundaries and retrain models under stricter conformity assessment procedures.
Growth Catalysts
- Sub-3nm node migration:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding electron-beam review capacity to resolve atomic-scale defects that optical systems miss, pulling AI-classification software demand.
- EU AI Act conformity obligations:Automated decision-making systems in European semiconductor facilities now require documented risk management and human oversight protocols, creating certified product demand.
- Heterogeneous integration:Advanced packaging houses face multiplied inspection points per device as chiplets and 3D stacking proliferate, extending hardware and software procurement cycles.
Market Restraints
- High-purity rare gas supply concentration:Ukrainian neon and Russian krypton supply disruptions have exposed vulnerability in excimer laser lithography systems that feed defect review workflows.
- Computational lithography cost escalation:Inverse lithography technology software licenses and GPU clusters for optical proximity correction now consume 15-20% of advanced node R&D budgets.
- Export control fragmentation:U.S. Department of Commerce restrictions on advanced semiconductor manufacturing equipment to China are forcing dual supply chain configurations and redundant engineering.
Strategic Opportunities
- Indian fab buildouts:Tata Electronics and CG Power are constructing 28nm and 65nm facilities in Gujarat and Assam, opening greenfield procurement for AI-enabled inspection systems without legacy equipment constraints.
- Cloud-based model retraining:Foundries with geographically distributed fabs are centralizing defect classification model updates through secure cloud infrastructure, reducing per-site software maintenance.
- Automotive functional safety certification:ISO 26262 compliance for automotive chip supply chains creates premium pricing tiers for inspection systems with documented traceability and fault coverage metrics.
Industry Challenges
- Deep learning model validation:fabs struggle to verify that convolutional neural networks trained on historical defect libraries will generalize to novel failure modes at emerging process nodes.
- Legacy tool integration:brownfield facilities must retrofit AI-classification software layers onto 15-20 year old inspection hardware with incompatible data formats and compute architectures.
- Interpretability requirements:process engineers demand explainable AI outputs for root-cause analysis, but neural network decision boundaries remain opaque without significant engineering investment.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Enabled Semiconductor Defect Classification and Review Systems Market Trends and Innovations
Deep learning architectures are compressing defect review cycles from hours to minutes while regulatory pressure on algorithmic transparency intensifies across major manufacturing jurisdictions.
Transformer-based vision models are supplanting convolutional neural networks for defect classification in leading-edge fabs. Samsung Foundry and Intel Foundry Services have deployed self-attention mechanisms to capture long-range spatial dependencies in wafer map patterns. This architecture shift is supplanting rule-based preprocessing pipelines and enabling single-model generalization across multiple process layers.
The EU AI Act's high-risk system classification for automated manufacturing decisions is mandating conformity assessments for defect classification software sold into European fabs. Vendors must now document training data provenance, model performance metrics, and human oversight interfaces. Memory and automotive chip facilities in Germany and France face the tightest compliance timelines as their customers demand supply chain liability protection.
Equipment-as-a-service contracting is displacing traditional capital purchase models for high-end review systems. Foundries in Taiwan and South Korea now prefer per-wafer pricing with bundled model retraining and field application engineer support. This shift concentrates vendor risk on uptime guarantees and algorithmic performance rather than hardware reliability alone.
AI-Enabled Semiconductor Defect Classification and Review Systems Market Segmentation
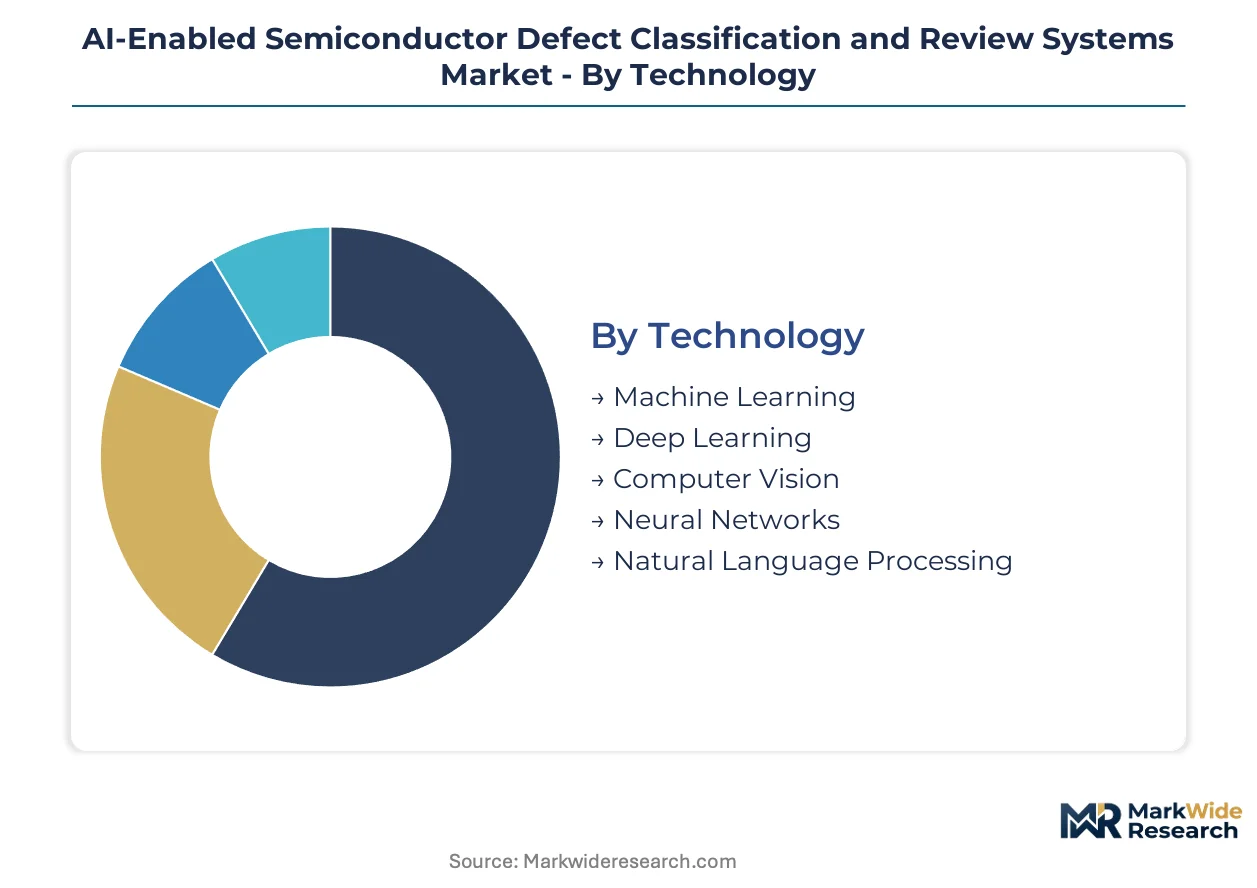
Segmentation in AI-enabled semiconductor defect classification reveals how regulatory frameworks, node complexity, and supply chain concentration reshape procurement patterns across technology layers and deployment models. Vendors must align certification requirements with specific end-use liability exposures.
Technology:
The EU AI Act's high-risk system classification creates divergent compliance burdens across algorithmic architectures, with neural network-based approaches facing stricter documentation requirements than classical machine learning in European fabs.
- Deep Learning:Convolutional and transformer-based architectures process wafer map imagery through multi-layer neural networks. Samsung Foundry and Intel Foundry Services deploy self-attention mechanisms for sub-3nm defect detection where long-range spatial dependencies determine yield outcomes. EU AI Act conformity assessments mandate documented training data provenance and human oversight interfaces for these systems in German and French facilities.
- Machine Learning:Supervised classification algorithms using support vector machines and random forests persist in mature node facilities with established defect libraries. Tata Electronics' greenfield 28nm fabs in Gujarat prioritize these approaches for faster deployment without extensive neural network validation cycles.
- Computer Vision:Edge detection and morphological processing pipelines preprocess raw inspection imagery before algorithmic classification.
- Neural Networks:Recurrent architectures process sequential inspection data from multi-step fabrication sequences.
- Natural Language Processing:Automated parsing of equipment logs and maintenance records supplements visual defect detection.
Established volume favors machine learning; emerging adoption favors deep learning.
Application:
Cost tier differentiation separates capital-intensive wafer inspection from software-weighted packaging quality control, with lithography defect identification commanding premium pricing due to computational lithography integration.
- Wafer Inspection:Optical and electron-beam systems scan bare silicon for particles, scratches, and crystallographic defects at throughputs exceeding thousands of wafers hourly. Taiwan Semiconductor Manufacturing and Samsung Foundry anchor demand here as sub-3nm node migration multiplies inspection points per device. Ukrainian neon supply disruptions have constrained excimer laser lithography systems feeding these workflows.
- Packaging Quality Control:AI classification of bond wire integrity, solder joint formation, and substrate warpage addresses heterogeneous integration complexity. Advanced packaging houses in South Korea face multiplied inspection points per device as chiplets and 3D stacking proliferate, extending procurement cycles fastest in this segment.
- Lithography Defect Identification:Pattern fidelity verification against design intent catches bridging, necking, and line-edge roughness.
- Yield Enhancement:Root-cause correlation across process steps identifies systemic excursion sources.
- Failure Analysis:Destructive and non-destructive techniques characterize returned devices from automotive and memory supply chains.
Procurement concentrates in wafer inspection; packaging quality control climbs the fastest.
End User:
Customer type determines liability exposure, with automotive chip supply chains demanding ISO 26262 functional safety certification that standard consumer electronics procurement does not require.
- Foundries:Merchant silicon manufacturers operate at highest volumes and tightest yield tolerances, driving most aggressive AI classification adoption. Taiwan and South Korea foundries now prefer equipment-as-a-service contracting with per-wafer pricing and bundled model retraining.
- Chip Fabricators:Integrated device manufacturers with captive production balance inspection automation against legacy tool retrofit constraints.
- Assembly & Test Centers:Final packaging and electrical verification facilities deploy classification systems for outgoing quality assurance.
- Equipment Manufacturers:Original equipment producers integrate AI layers into next-generation inspection tool platforms.
- Quality Assurance Labs:Third-party validation services certify supplier conformance to automotive and medical device standards.
Contracting innovation centers on foundries; certification requirements tighten most for automotive-facing chip fabricators.
Deployment:
Supply concentration in cloud infrastructure providers shapes hybrid and edge computing adoption, with data sovereignty concerns fragmenting regional deployment preferences.
- Cloud-Based:Centralized model retraining across geographically distributed fabs reduces per-site software maintenance. Foundries with facilities in Taiwan, South Korea, and the United States leverage secure cloud infrastructure for defect classification updates, though U.S. Department of Commerce export controls on AI inference software bundled with inspection hardware create compliance uncertainty.
- Edge Computing:On-device inference at inspection tools minimizes latency for real-time process control decisions.
- On-Premises:Air-gapped installations satisfy defense and classified program security requirements.
- Hybrid:Training in cloud with inference at edge balances model currency against latency constraints.
Capital efficiency favors cloud-based; latency sensitivity favors edge computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundries and advanced packaging houses concentrate procurement authority in Taiwan, South Korea, and the United States, where sub-3nm node migration and heterogeneous integration multiply inspection points per device.
United States
Intel Foundry Services and GlobalFoundries drive electron-beam review capacity expansion for domestic advanced node production. The Department of Commerce export controls on semiconductor manufacturing equipment to China fragment supply chain strategies. Arizona and New York fabs anchor procurement for AI-classification systems with bundled cloud-based model retraining.
Taiwan
Taiwan Semiconductor Manufacturing anchors global wafer inspection volume as sub-3nm migration accelerates. The island's national semiconductor strategy prioritizes equipment-as-a-service contracting with per-wafer pricing. Hsinchu Science Park concentrates foundry investment where demand for defect review systems tightens fastest.
South Korea
Samsung Foundry and SK Hynix expand advanced packaging capacity for chiplets and 3D stacking applications. The Korean Ministry of Trade, Industry and Energy subsidizes domestic equipment procurement under the K-Semiconductor Belt initiative. Pyeongtaek and Yongin clusters multiply inspection points per device through heterogeneous integration.
Germany
Bosch, Infineon, and automotive chip suppliers demand ISO 26262 functional safety certification for inspection systems. The EU AI Act imposes conformity obligations on automated defect classification in Dresden and Reutlingen fabs. Bavaria and Saxony face the tightest compliance timelines as customers demand supply chain liability protection.
Japan
Tokyo Electron and Hitachi High-Tech anchor domestic equipment production while serving export markets. METI's semiconductor revitalization strategy funds inspection technology development for sub-3nm nodes. Kyushu and Hiroshima prefectures concentrate memory fab investment where yield protection drives AI-classification adoption.
AI-Enabled Semiconductor Defect Classification and Review Systems Market Competitive Landscape
Player mix skews toward diversified equipment conglomerates with backward integration into process control modules. The market structure concentrates around three to five dominant vendors leveraging installed bases of inspection hardware to extend into software layers. Two strategic archetypes prevail: lithography-integrated platform providers and specialized electron-beam review system fabricators. Competitive moves center on equipment-as-a-service contracting with bundled model retraining and field application engineer support.
Among diversified equipment conglomerates, KLA and Applied Materials occupy positions where installed inspection tool bases enable software layer extension. Tokyo Electron exemplifies the specialized electron-beam review archetype tuned for sub-3nm node requirements. These three companies represent the dominant competitive anchors, with KLA and Applied Materials competing through backward integration into process control modules while Tokyo Electron competes through specialized system architectures.
| Leading Market Players |
|---|
| KLA |
| Applied Materials |
| ASML |
| Hitachi High-Tech |
| Tokyo Electron |
| Nikon |
| Thermo Fisher Scientific |
| Lasertec |
| Cognex |
| Others |
Pricing and Supply Chain Analysis
Equipment-as-a-service contracts with per-wafer pricing lock in multi-year supply access and cost visibility for foundries in Taiwan and South Korea. These arrangements bundle AI-classification software updates with field engineer support, shifting vendor risk from capital recovery to uptime guarantees.
Pricing Analysis
Cost-plus contracts indexed to GPU cluster and rare gas input costs dominate AI-enabled defect classification procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified automotive systems from consumer electronics configurations. Cost compression in standard-tier offerings is intensifying because foundries demand bundled cloud retraining without per-site maintenance fees. Advanced packaging houses show highest price sensitivity due to margin pressure from heterogeneous integration complexity.
Supply Chain Analysis
Strategic stockpiling of Ukrainian neon and Russian krypton has replaced just-in-time preferences after lithography laser supply disruptions. Hardware production concentrates in Japan, the United States, and the Netherlands, while AI inference software development clusters in Taiwan and South Korea. The supply chain rests on high-purity rare gas feedstocks, EUV optical components, and advanced GPU accelerators. Single-source vulnerability in excimer laser optics creates structural risk. Distribution runs through direct vendor-foundry relationships with dedicated field application teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification triggers a regulatory inflection that will separate certified vendors from non-compliant suppliers. This disruption compresses the window for strategic repositioning.
For Market Incumbents: Consolidate software layer control through backward integration into process control modules. Lock in foundry relationships with equipment-as-a-service contracts before EU AI Act compliance deadlines tighten. Neutralize emerging cloud-native challengers by embedding AI-classification deeper into inspection hardware architectures. For New Entrants and Emerging Players: Cloud-based model retraining services for brownfield fabs with legacy tool constraints represent an underserved layer where incumbents under-serve. Target Indian greenfield facilities in Gujarat and Assam with lightweight machine learning deployments that bypass lengthy neural network validation cycles. Lead with rapid deployment guarantees and lower total cost of ownership against established vendor maintenance contracts. For Investors and Strategic Acquirers: Capital is best deployed toward specialized electron-beam review system fabricators with sub-3nm node capabilities. Long-term viability hinges on regulatory certification moats rather than hardware scale alone. Watch for EU AI Act enforcement actions against non-compliant systems as the inflection signal for vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Shifts vendor risk from capital recovery to algorithmic performance guarantees for Taiwan foundries. |
| EU AI Act Conformity Certification | Creates regulatory moats separating compliant German automotive suppliers from non-certified competitors. |
| Cloud-Based Model Retraining Infrastructure | Enables centralized software maintenance across geographically distributed Samsung and Intel fabs. |
| Backward Integration into Process Control | Allows Applied Materials and KLA to capture margin from adjacent lithography and deposition steps. |
| Automotive Functional Safety Certification | Opens premium pricing tiers for Bosch and Infineon supply chains demanding ISO 26262 traceability. |
Research Methodology
Desk research of SEC equipment manufacturer filings, foundry capex disclosures, and EU regulatory databases preceded structured interviews with process control engineers, fab procurement directors, and field application specialists. Primary intelligence from equipment vendors and foundry operators was cross-validated against customs trade data, patent filings, and hyperscaler infrastructure announcements. Bottom-up wafer inspection unit economics were triangulated against top-down semiconductor capital equipment spending forecasts.
Variance decomposition across technology adoption curves, node migration timelines, and regulatory compliance phases shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include algorithmic architecture, application layer, end-user liability exposure, and deployment topology. CAGRs were derived from equipment shipment trajectories and software attach rate assumptions. Forecast inputs incorporated EU AI Act implementation schedules and sub-3nm node yield ramp patterns.
Underlying assumptions cover stable rare gas supply restoration, continued U.S. Department of Commerce export control enforcement, and linear transformer architecture adoption curves, with deviation risk concentrated in geopolitical supply disruptions and regulatory delay scenarios. Revision becomes warranted when EU AI Act enforcement intensity or Chinese market access restrictions cross threshold levels that reshape vendor addressable markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.