

EMC Electromagnetic Compatibility Test Laboratory Market Size, Share, and Industry Trends Forecast 2026-2036
EMC Electromagnetic Compatibility Test Laboratory Market Insights
The EU Green Deal is restructuring procurement criteria for electronics across European supply chains, compelling manufacturers to pre-validate components through accredited EMC facilities. SGS leverages its pan-European chamber network to capture automotive and medical device workflows. Bureau Veritas anchors its position through maritime and industrial equipment specializations with deep IMO and IEC expertise. DEKRA competes aggressively in automotive subsystem testing, where OEMs now mandate full-vehicle electromagnetic validation before platform release.
An EMC test laboratory is a controlled facility equipped with anechoic chambers, shielded enclosures, and calibrated antenna arrays that measure electromagnetic emissions and immunity across defined frequency spectra, typically from 9 kHz to 40 GHz depending on application scope. These laboratories exist to certify that electronic devices neither emit harmful interference nor fail when exposed to ambient electromagnetic fields, a requirement for market access in regulated jurisdictions. Emission testing and immunity testing represent the two dominant service categories, with emission testing occupying the mature revenue base while immunity testing grows faster as 5G base stations and electric drivetrains raise susceptibility stakes. Among end users, aerospace manufacturers and defense contractors concentrate the highest-margin contracts due to MIL-STD and DO-160 certification complexity, whereas consumer electronics OEMs drive volume through shorter-cycle smartphone and wearable programs.
EMA's medical device regulations, FCC Part 15 rules for unintentional radiators, and the EU's Radio Equipment Directive collectively determine which laboratories gain market access and which test reports receive cross-border recognition. China's GB standards and NMPA device registration requirements add a separate accreditation layer that shapes where multinational firms build captive or third-party capacity. Stakeholders must track how divergent national frequency allocation tables and evolving automotive radar bands reshape chamber calibration schedules and capital deployment priorities.
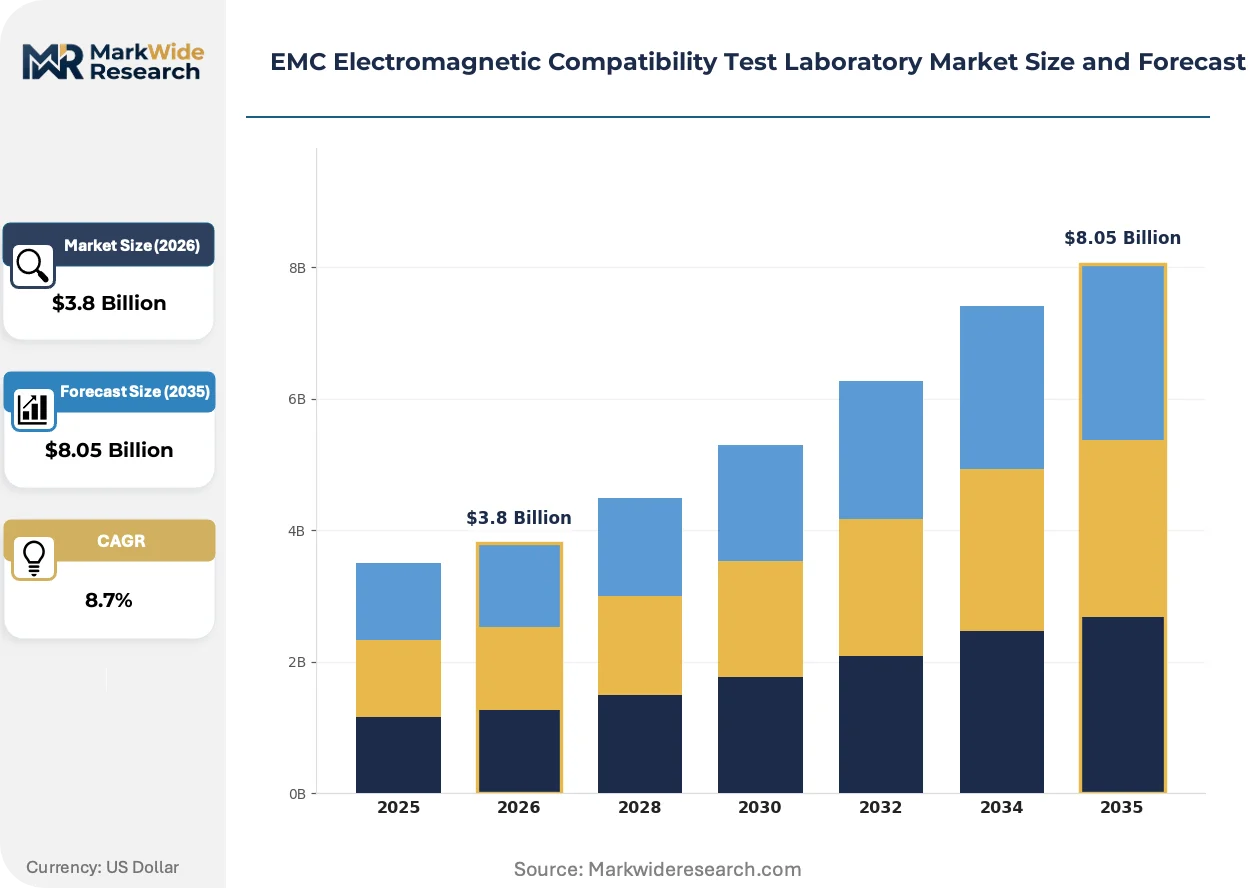
Market Dynamics
Automotive electrification and 5G infrastructure deployment are compressing test cycles and forcing chamber operators to recalibrate for higher-frequency validation protocols.
Growth Catalysts
- EU Green Deal electronics mandates:Tightened electromagnetic emissions thresholds for imported equipment are compelling manufacturers to pre-validate through accredited facilities before customs clearance.
- Automotive subsystem validation:OEMs now require full-vehicle electromagnetic certification prior to platform release, pulling capacity expansion across certified anechoic chambers.
- 5G base station immunity protocols:Higher susceptibility stakes in telecommunications infrastructure are accelerating demand for immunity testing services.
Market Restraints
- Anechoic chamber construction costs:Specialized ferrite tile and absorber material inputs face volatile pricing from limited specialty chemical suppliers.
- Accreditation concentration:Germany hosts the densest concentration of ISO 17025-accredited facilities in Europe, creating geographic supply bottlenecks for urgent validation programs.
- Frequency allocation fragmentation:Divergent national spectrum tables force redundant test sequences and extend certification timelines.
Strategic Opportunities
- Medical device EMC pre-certification:EMA's tightened MDR requirements create white space for laboratories offering combined electrical safety and electromagnetic validation.
- Maritime equipment specialization:IMO-compliant testing for vessel navigation and communication systems remains underserved relative to automotive and consumer electronics.
- GB standard localization:China's NMPA device registration requirements favor laboratories with captive capacity in Shanghai and Shenzhen.
Industry Challenges
- RF engineer scarcity:Calibration technicians with MIL-STD and DO-160 expertise command premium compensation and extended recruitment cycles.
- Chamber downtime coordination:Multi-client scheduling conflicts arise when automotive OEMs demand exclusive access blocks for platform-level validation.
- Cross-border report recognition:FCC Part 15 acceptance varies by importing jurisdiction, forcing redundant documentation for multinational product launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMC Electromagnetic Compatibility Test Laboratory Market Trends and Innovations
Digital twin simulation and automated test sequencing are compressing physical chamber time and reshaping how laboratories price validation services.
Reverberation chamber methodology is rewriting automotive immunity testing protocols by enabling faster multi-frequency excitation than traditional anechoic approaches. Tier-1 suppliers in Stuttgart and Wolfsburg are adopting hybrid physical-digital validation workflows. This convergence is compressing prototype cycles from months to weeks while demanding new calibration competencies from laboratory staff.
REACH restrictions on fire-retardant absorber materials are forcing chamber operators to source alternative pyramidal foam formulations. The transition disrupts existing supplier relationships and requires requalification of measurement uncertainty budgets. German laboratories are absorbing these input transitions fastest due to proximity to alternative chemical manufacturers.
Certificate bundling is consolidating what were discrete electrical safety, radio, and EMC validations into single-procurement contracts. Medical device OEMs in Ireland and the Netherlands now prefer laboratories offering combined MDR and RED compliance pathways. This preference shift disadvantages pure-play EMC facilities without adjacent accreditation scopes.
EMC Electromagnetic Compatibility Test Laboratory Market Segmentation
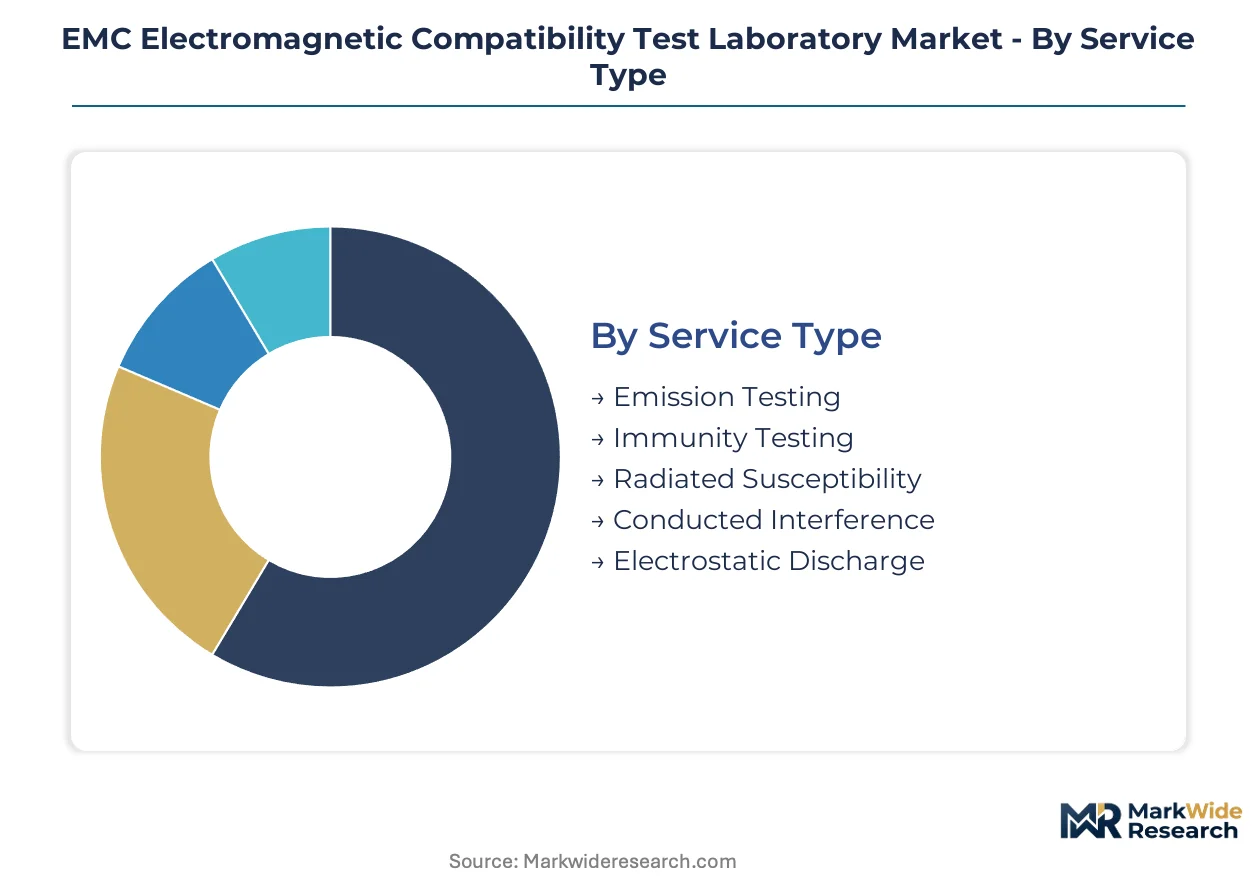
EMC laboratory revenue splits unevenly across service categories and end-use verticals, with emission testing anchoring mature cash flows while immunity protocols capture expanding 5G and automotive electrification workflows. Technology specialization and application-specific accreditation scopes determine which facilities win multi-year contracts versus spot-market validation business.
Service Type:
Emission testing commands the volume base with standardized protocols and shorter cycle times, while immunity testing extracts premium pricing from complex automotive and telecommunications validation programs.
- Emission Testing:Measures electromagnetic energy radiated or conducted from equipment under test across regulated frequency bands. Consumer electronics OEMs in Shenzhen and Dongguan concentrate demand for FCC Part 15 pre-certification ahead of US market entry, compressing turnaround times to 48-72 hours for high-volume smartphone programs.
- Immunity Testing:Validates device resilience against external electromagnetic interference through controlled field exposure and surge injection. Automotive subsystem suppliers in Stuttgart and Wolfsburg drive capacity expansion as OEMs mandate full-vehicle electromagnetic validation prior to platform release, with 5G base station deployments accelerating telecommunications infrastructure protocols.
- Radiated Susceptibility:Aerospace manufacturers and defense contractors specify MIL-STD-461 RS103 protocols for avionics and mission-critical electronics.
- Conducted Interference:Medical device developers require IEC 61000-4-6 validation for implantable and diagnostic equipment EMA submissions.
- Electrostatic Discharge:Semiconductor fabs and integrated circuit packagers pre-qualify components against HBM and MM stress models.
Today's leader: Emission Testing. Tomorrow's challenger: Immunity Testing.
End User:
Margin concentration follows certification complexity, with defense and aerospace contracts commanding rates 3-4x above consumer electronics spot pricing due to extended documentation and witness-test requirements.
- Consumer Electronics OEMs:Smartphone, wearable, and laptop manufacturers drive the highest test volumes with compressed 2-4 week certification cycles. Facilities in Taiwan and South Korea capture recurring programs from Apple and Samsung supply chain partners, though pricing pressure intensifies as OEMs consolidate vendor lists to 2-3 preferred laboratories per region.
- Aerospace Manufacturers:Boeing, Airbus, and tier-1 avionics suppliers require DO-160 and MIL-STD compliance with full test witnessing and proprietary data handling. Wichita, Toulouse, and Hamburg clusters anchor demand, with laboratories charging premiums for ITAR-controlled facility zones and cleared personnel.
- Telecommunication Firms:Ericsson, Nokia, and Huawei base station programs require immunity validation against 3.5 GHz and 28 GHz 5G field strengths.
- Defense Contractors:Lockheed Martin, Raytheon, and BAE Systems specify TEMPEST and AMSG 7060 protocols for classified platforms.
- Medical Device Developers:Medtronic, Siemens Healthineers, and Philips demand combined electrical safety and EMC validation under EMA MDR and FDA 510(k) pathways.
Defense Contractors extract the steepest pricing premiums. Medical Device Developers represent the fastest-climbing demand trajectory as MDR enforcement tightens.
Technology:
Chamber configuration and antenna array investments align with frequency coverage requirements, with 40 GHz-capable facilities capturing automotive radar and satellite communications workflows.
- Radiated Emission:Open-area test sites and anechoic chambers measure field strength from 30 MHz to 18 GHz using calibrated biconical and log-periodic antennas. Germany's TÜV network and US EMC test houses in Silicon Valley dominate this mature segment with standardized CISPR 32 and CISPR 25 protocols.
- Conducted Emission:Line impedance stabilization networks quantify disturbance voltage on power and signal ports. Industrial equipment manufacturers in China's Pearl River Delta concentrate demand as GB 9254 compliance becomes mandatory for domestic market access.
- Transient Immunity:Surge, burst, and voltage dip generators simulate grid disturbances and lightning strikes.
- Harmonic Distortion:IEC 61000-3-2 validation for lighting and appliance current draw shapes inverter and power supply test programs.
- Voltage Fluctuation Testing:Flicker meters assess equipment impact on power quality per IEC 61000-3-3.
Radiated Emission anchors current capacity utilization. Conducted Emission gains share as industrial motor drive electrification accelerates.
Application:
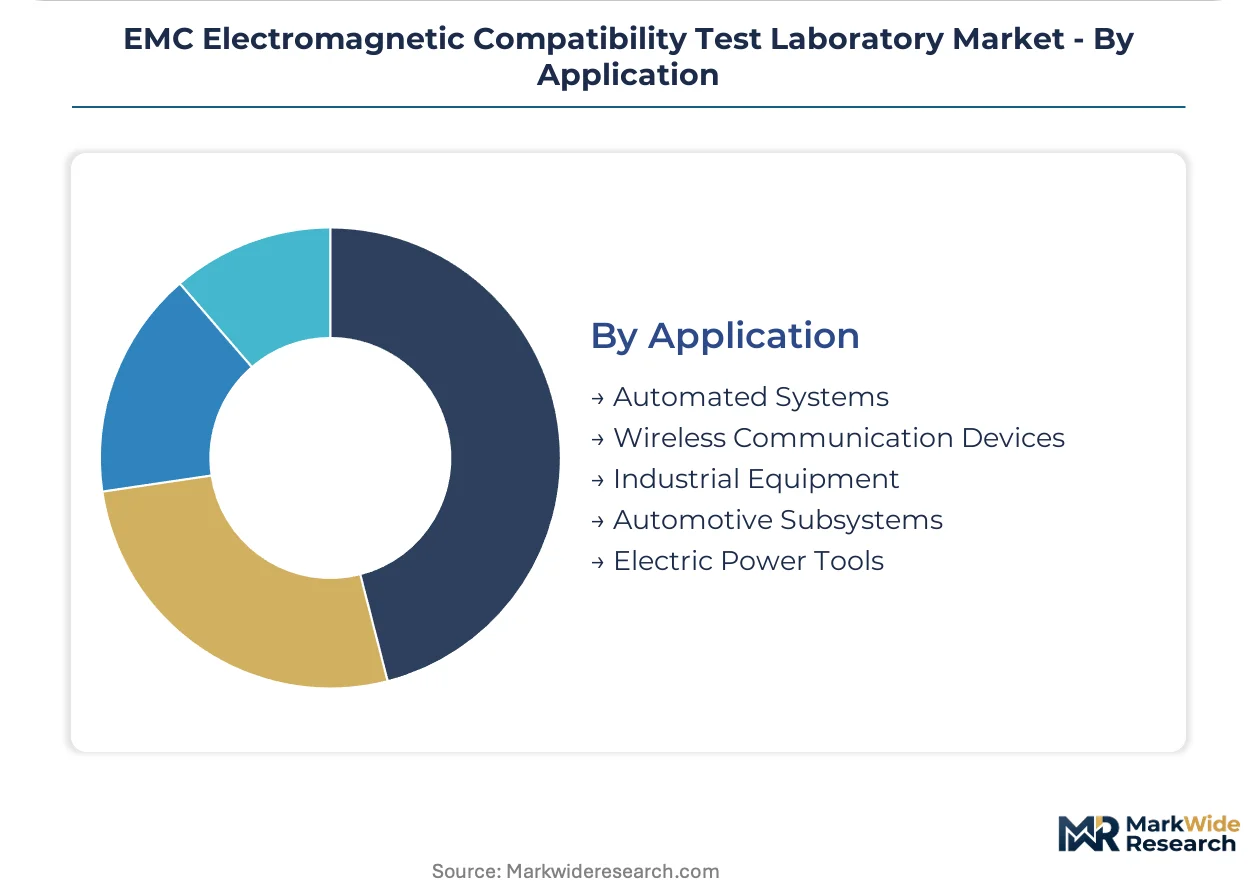
Application-specific standards fragmentation forces laboratories to maintain multiple accreditation scopes, with automotive and medical pathways requiring the deepest regulatory expertise investments.
- Automotive Subsystems:Electric drivetrains, ADAS sensors, and infotainment modules require CISPR 25, ISO 11452, and OEM-specific validation. DEKRA and TÜV SÜD facilities in Munich and Stuttgart capture platform-level programs from BMW, Mercedes-Benz, and Volkswagen as full-vehicle electromagnetic certification becomes mandatory pre-release.
- Wireless Communication Devices:Wi-Fi 6E, Bluetooth 5.3, and UWB modules demand spurious emission and co-existence testing. Taiwan's Bureau of Standards, Metrology and Inspection accreditation holders and US Telecommunications Certification Body laboratories split this high-volume segment.
- Automated Systems:Industrial robotics and PLC networks require IEC 61000-6-2 immunity validation for factory floor deployment.
- Industrial Equipment:Variable frequency drives and welding equipment face tightened EU Green Deal electromagnetic emission thresholds.
- Electric Power Tools:Cordless drill and lawn equipment manufacturers pre-validate against EN 55014-1 for CE marking.
Automotive Subsystems concentrate the highest capital deployment. Wireless Communication Devices drive the steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EMC laboratory industry traces its modern scale to post-war German industrial standardization, where TÜV-affiliated facilities pioneered anechoic chamber construction for automotive and industrial equipment certification. This heritage established accreditation protocols that now govern electromagnetic validation across regulated markets worldwide.
Germany
Automotive subsystem validation from BMW, Mercedes-Benz, and Volkswagen pulls capacity expansion across Munich and Stuttgart laboratory clusters. The EU Green Deal tightens electromagnetic emissions thresholds for imported industrial equipment, compelling pre-validation through DEKRA and TÜV SÜD facilities before customs clearance. Bavaria hosts the densest concentration of ISO 17025-accredited anechoic chambers in Europe.
United States
FCC Part 15 pre-certification demand from smartphone and consumer electronics OEMs concentrates in Silicon Valley and Greater Boston test houses. FDA electromagnetic compatibility requirements for medical devices under 510(k) pathways drive combined electrical safety and EMC validation workflows. Wichita's aerospace cluster anchors MIL-STD and DO-160 certification for Boeing and tier-1 avionics suppliers.
China
GB standards compliance for domestic market access forces multinational electronics manufacturers to pre-validate through NMPA-registered facilities in Shanghai and Shenzhen. MIIT radio equipment type approval requirements accelerate 5G base station immunity testing programs. The Pearl River Delta's electronics manufacturing density supports captive laboratory capacity for Huawei and supply chain partners.
Japan
METI radio law certification and JIS electromagnetic compatibility standards structure demand for Tokyo and Osaka testing facilities. Automotive electrification from Toyota and Honda suppliers compresses validation cycles for hybrid drivetrain components. Kansai region laboratories capture medical device EMC workflows under revised PMDA pharmaceutical and medical device regulations.
South Korea
Samsung and LG supply chain partners drive high-volume smartphone and display panel emission testing in Seoul Capital Area facilities. RRA radio certification requirements for Wi-Fi 6E and UWB modules expand spurious emission validation capacity. Busan-Ulsan industrial corridors concentrate maritime equipment testing for IMO-compliant navigation systems.
EMC Electromagnetic Compatibility Test Laboratory Market Competitive Landscape
Capital-heavy chamber operators compete with asset-light accreditation consultants for EMC validation contracts. The market structures around three tiers: pan-European networks with dense anechoic chamber portfolios, specialized automotive-focused facilities with OEM-direct relationships, and regional spot-market laboratories serving consumer electronics spot demand. Consolidation pressures intensify as certificate bundling—combining electrical safety, radio, and EMC validations—favors multi-scope operators over pure-play EMC houses. Strategic moves concentrate on geographic expansion into Chinese GB standard zones and vertical integration into medical device pre-certification services.
Within the pan-European network tier, SGS and Bureau Veritas occupy positions anchored by maritime and industrial equipment specializations, while TÜV SÜD and DEKRA exemplify automotive-centric operators capturing platform-level validation programs. Intertek Group sits within the diversified certification archetype spanning consumer goods and electronics workflows. These structures reflect how accreditation scope breadth and geographic chamber density determine contract access more than pricing alone.
| Leading Market Players |
|---|
| Intertek Group |
| SGS |
| Bureau Veritas |
| TÜV SÜD |
| TÜV Rheinland |
| DEKRA |
| Eurofins Scientific |
| UL Solutions |
| Element Materials Technology |
| Others |
Pricing and Supply Chain Analysis
OEM consolidation of preferred laboratory vendor lists to two or three partners per region compresses pricing power for pure-play EMC facilities and forces supply-side specialization into combined electrical safety and electromagnetic validation services. This procurement concentration reshapes how chamber operators invest in adjacent accreditation scopes and where they deploy capital for captive capacity.
Pricing Analysis
Project-based validation contracts with volume-scaled discounts dominate the EMC laboratory market, separating premium-tier facilities with MIL-STD and DO-160 expertise from standard-tier operators serving FCC Part 15 pre-certification and economy-tier spot-market houses in Shenzhen and Dongguan. Price differentiation hinges on certification grade complexity and geographic proximity to automotive OEM engineering centers. Cost compression in consumer electronics emission testing intensifies as smartphone manufacturers demand 48-hour turnaround guarantees. Medical device developers exhibit the lowest price sensitivity due to EMA MDR compliance penalties for delayed market entry.
Supply Chain Analysis
RF engineer scarcity in Stuttgart, Munich, and Wolfsburg clusters constrains chamber calibration capacity and extends recruitment cycles for technicians with anechoic chamber expertise. Manufacturing inputs draw from Germany for precision ferrite tiles, Japan for specialty absorber foams, and China for pyramidal foam formulations facing REACH substitution pressures. Single-source vulnerability concentrates in European specialty chemical suppliers for fire-retardant absorber materials. Distribution runs through direct OEM engineering relationships and tier-1 supplier procurement frameworks rather than spot-market brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal electronics mandates and EMA MDR enforcement tighten electromagnetic emissions thresholds and expand mandatory pre-certification volumes across European supply chains.
For Market Incumbents: Anchor platform-level validation relationships with automotive OEMs through exclusive access blocks for full-vehicle electromagnetic certification prior to release. Defend against pure-play electrical safety laboratories expanding into EMC scope by deepening backward integration into medical device combined validation workflows. Prioritize capacity addition in Shanghai and Shenzhen to capture GB standards localization demand from multinational electronics manufacturers. For New Entrants and Emerging Players: The price-point gap between TÜV-affiliated premium facilities and spot-market economy houses in China's Pearl River Delta creates entry space for mid-tier operators with hybrid physical-digital validation capabilities. Maritime equipment specialization for IMO-compliant vessel navigation systems remains the most penetrable application segment relative to saturated automotive and consumer electronics verticals. Pursue certificate bundling strategies combining radio equipment directive and electrical safety validations to displace pure-play EMC incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with diversified testing groups with captive anechoic chamber networks and multi-scope accreditation spanning electrical safety, radio, and EMC pathways. Long-term viability favors operators with demonstrated calibration competency in 40 GHz automotive radar and 5G base station immunity protocols. Watch for inflection signals in NMPA device registration volume from Shanghai-registered facilities as indicator of GB standards enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Physical-Digital Validation Workflow Deployment | Compresses prototype cycles from months to weeks for Stuttgart automotive suppliers. |
| Certificate Bundling Service Integration | Captures combined MDR and RED compliance demand from Irish medical device OEMs. |
| GB Standards Captive Capacity Buildout | Positions laboratories for NMPA device registration requirements in Shanghai clusters. |
| Maritime Equipment Specialization Investment | Addresses underserved IMO-compliant testing demand in Busan-Ulsan corridors. |
| 40 GHz Chamber Calibration Competency Development | Enables automotive radar and satellite communications workflow capture from aerospace manufacturers. |
Research Methodology
Direct dialogue with EMC laboratory operations directors, automotive OEM electromagnetic validation engineers, medical device regulatory affairs leads, and tier-1 supplier procurement managers grounded qualitative findings in operational reality. Secondary validation drew from FCC equipment authorization databases, EMA MDR submission filings, ISO 17025 accreditation registries, and MIIT radio equipment type approval records. Bottom-up chamber capacity utilization estimates and top-down OEM R&D spending patterns were triangulated against trade data from German TÜV networks and Chinese GB standards certification volumes.
Bottom-up modeling segmented the market by service type, end user vertical, technology configuration, and application-specific accreditation scope across the projection horizon. Top-down validation cross-referenced regulatory mandate expansion timelines against OEM platform release cycles and telecommunications infrastructure deployment schedules. CAGRs were derived from capacity expansion announcements, accreditation scope additions, and documented shifts in procurement consolidation patterns rather than extrapolated trend lines.
Caveats apply where REACH absorber material restrictions, frequency allocation table divergence between national regulators, or automotive OEM platform delay decisions could materially shift the outlook. Forecasts reflect assumptions about EMA MDR enforcement consistency, EU Green Deal customs pre-validation implementation timing, and 5G base station immunity protocol standardization. Material deviation in automotive electrification investment cycles or NMPA registration processing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.