
 Panama Facility Management Market | 2026-2036
Panama Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Panama Facility Management Market Analytics
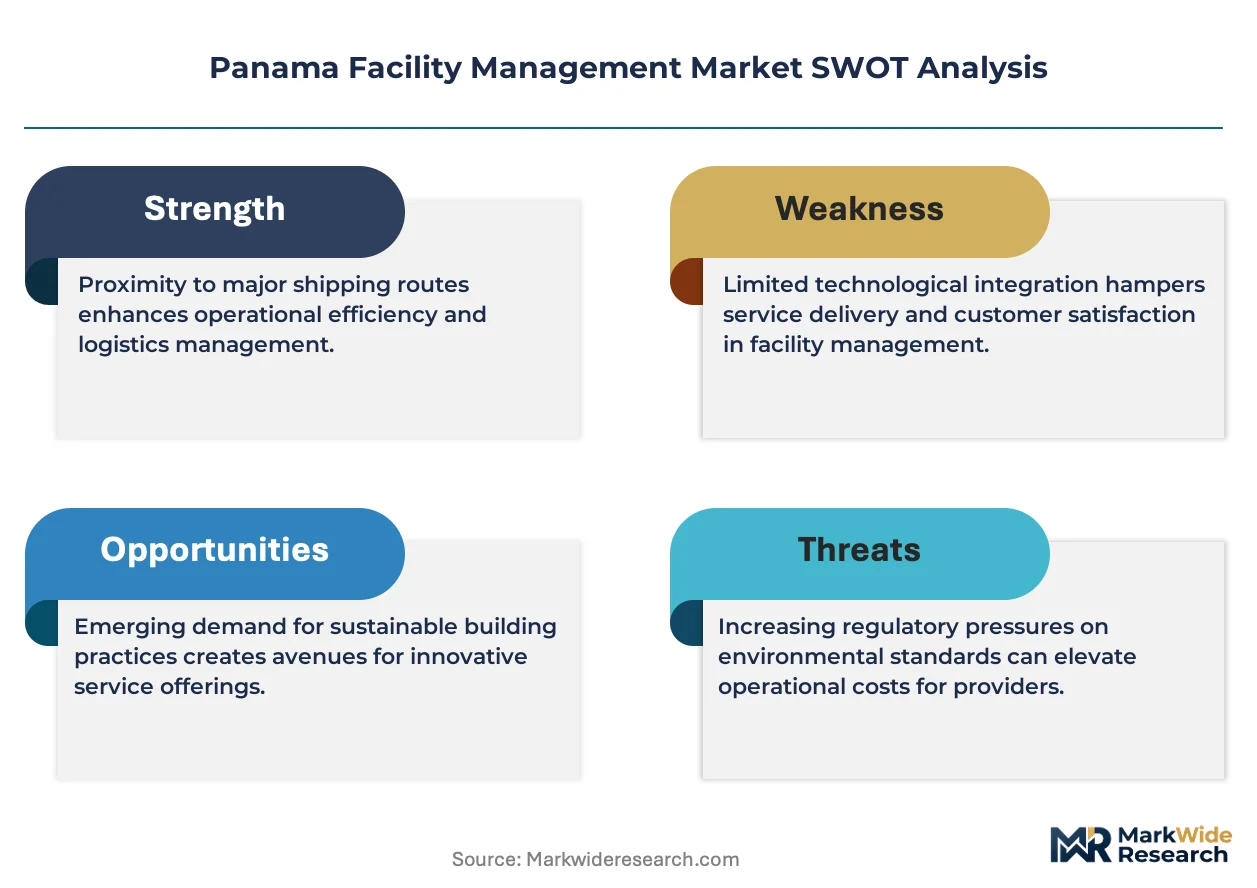
The premium-commodity split in Panama's facility management sector is repositioning around compliance depth and technology integration rather than basic service delivery. EULEN Group leverages its integrated security-cleaning bundles to dominate high-specification contracts in banking and logistics hubs. CBRE Group, Inc. anchors its competitive stance through proprietary workplace analytics platforms tailored to multinational tenants in Panama City's Class A towers. H&H Facility Management Corp differentiates via specialized healthcare sanitation protocols that exceed baseline Ministry of Health requirements.
Facility management encompasses the coordinated oversight of building operations, maintenance, and support services to ensure functional, safe, and efficient built environments, typically integrating preventive maintenance schedules, energy systems monitoring, and vendor coordination across multi-site portfolios. Cleaning services command the largest revenue pool within service type segmentation due to universal building code mandates and labor intensity, while IoT Solutions within technology segmentation represents the fastest structural expansion as building owners deploy sensor networks for predictive HVAC and lighting optimization. The outsourced contract type captures disproportionate growth relative to in-house alternatives as Panamanian firms seek to offload regulatory liability and specialized labor recruitment.
Panama's Ministry of Health sanitation protocols and Ministry of Commerce and Industry labor regulations jointly elevate compliance costs for facility operators, particularly in healthcare and food service adjacent properties. The Technical Standards and Industrial Metrology Unit (ETTI) of the Panamanian Accreditation Bureau shapes equipment calibration and safety certification requirements that filter into maintenance service specifications. Stakeholders must monitor how impending energy efficiency mandates for commercial buildings will reshape procurement criteria and vendor qualification thresholds.
Market Dynamics
Panama's facility management sector is reconfiguring around compliance depth as the Ministry of Health tightens sanitation mandates for healthcare infrastructure and commercial landlords face escalating liability exposure from outsourced operations.
Growth Catalysts
- Healthcare expansion:Hospital networks across Panama City and Colón are extending facility management contracts to cover specialized biomedical waste handling and infection control protocols.
- Panama Pacifico special economic zone:Multinational logistics and banking tenants in this corridor require integrated security-cleaning-landscaping bundles that exceed baseline service specifications.
- IoT sensor deployment:Building owners are installing predictive maintenance networks for HVAC and lighting systems, creating demand for technology-enabled service providers.
Market Restraints
- Labor cost escalation:Panama's minimum wage adjustments and social security contribution requirements are compressing margins for labor-intensive cleaning and security operations.
- Specialized talent scarcity:Certified technicians for medical-grade sanitation and building automation systems are concentrated in Panama City, limiting service radius expansion.
- Regulatory fragmentation:The Ministry of Commerce and Industry's labor regulations and the Ministry of Health's facility protocols create overlapping compliance burdens without unified enforcement standards.
Strategic Opportunities
- Colón Free Trade Zone:Warehouse and logistics facilities in this Caribbean hub remain underserved by integrated facility management providers capable of bilingual operations and customs-adjacent security protocols.
- Energy efficiency mandates:Impending commercial building performance standards will force retrofits and create recurring contracts for monitoring-based commissioning services.
- Convergence of access control and cleaning analytics:Providers bundling IoT-enabled occupancy sensors with dynamic sanitation scheduling can capture premium pricing from Class A office towers.
Industry Challenges
- ETTI calibration certification timelines:Equipment safety verification through the Technical Standards and Industrial Metrology Unit creates procurement delays for maintenance contractors.
- Legacy building system integration:Pre-digital HVAC and electrical infrastructure in Panama City's older commercial stock resists sensor retrofit without expensive gateway hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panama Facility Management Market |
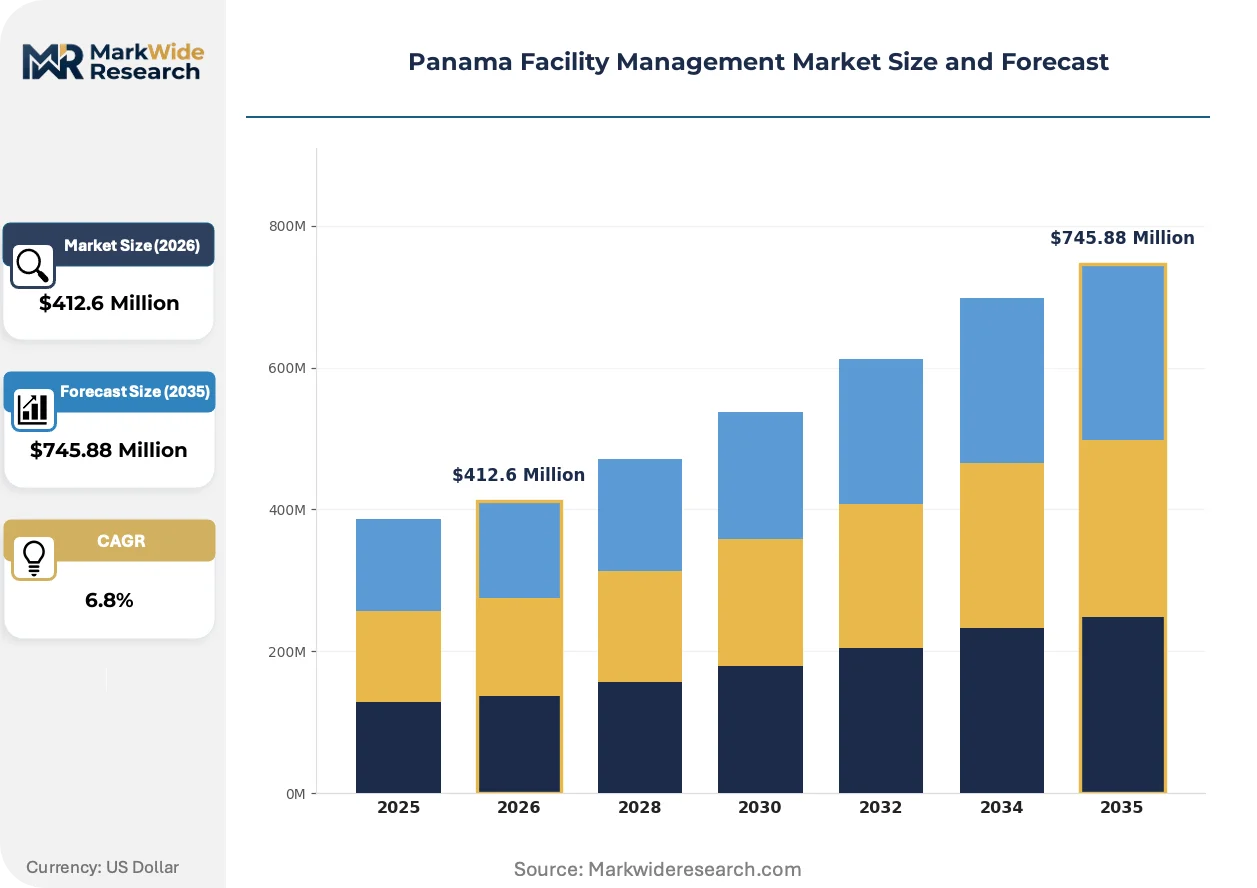
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping End User: Commercial, Residential, Educational, Healthcare Technology: IoT Solutions, Software, Automation, Energy Management Contract Type: Outsourced, In-house, Hybrid, Time & Material |
| Companies Covered | EULEN Group, H&H Facility Management Corp, CBRE Group, Inc., Accuro Prime, One Facilities Asset Management, Sodexo Inc., Hines Group, Newmark & Company Real Estate, Inc., Ecolab Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panama Facility Management Market Evolving Landscape
Technology integration and regulatory stringency are compressing the traditional separation between hard services and soft services, forcing facility operators to retrain workforces and restructure contract economics.
Computerized maintenance management systems (CMMS) with mobile workforce interfaces are automating work order dispatch and asset tracking across Panama's commercial portfolios. Property managers in Avenida Balboa towers are adopting these platforms to reduce administrative overhead and demonstrate compliance to multinational tenants. The technology is automating preventive maintenance scheduling that previously relied on paper logs and verbal coordination.
The Ministry of Health's updated sanitation protocols for medical infrastructure are mandating documented cleaning frequencies and chemical concentrations that exceed prior voluntary standards. Hospital accreditation bodies are incorporating these requirements into facility audit criteria. Private clinic operators are responding by consolidating vendor relationships with providers carrying specialized healthcare certifications.
Building owners are unbundling long-term bundled service contracts in favor of shorter performance-based agreements with explicit KPIs for energy consumption and tenant satisfaction metrics. This shift is visible among Panama Pacifico multinationals seeking quarterly service reviews tied to occupancy cost transparency. The model transfers operational risk to vendors while retaining owner oversight of capital planning decisions.
Panama Facility Management Market Segmentation
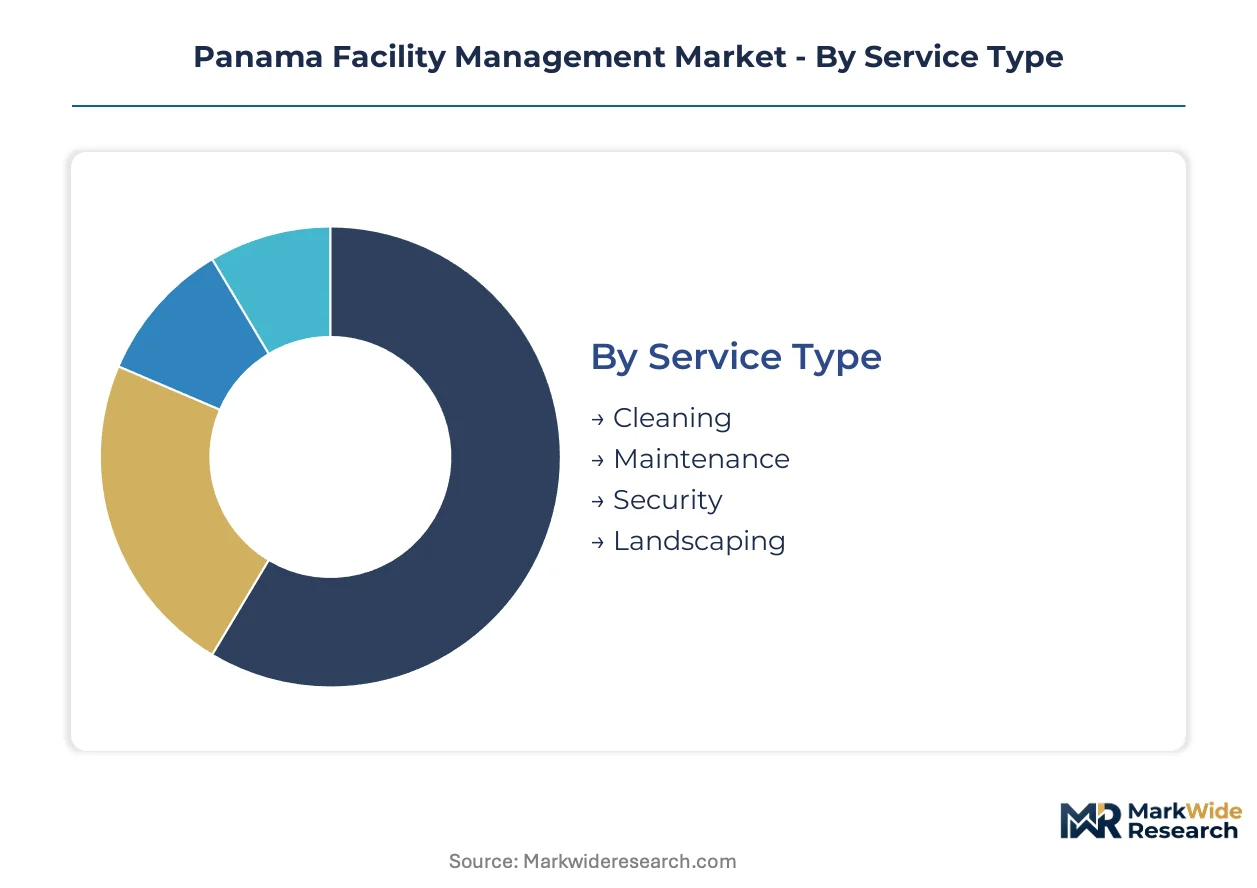
Panama's facility management providers structure service portfolios around compliance intensity and technology embedding depth. Segmentation reveals where bundled offerings command premium pricing versus where standalone services compete on labor arbitrage.
Service Type:
Cleaning and maintenance services operate as embedded operational necessities across all building classes, while security and landscaping function as discretionary enhancements with variable integration depth.
- Cleaning:Labor-intensive surface sanitation, waste removal, and consumables replenishment form the revenue foundation. Demand concentrates in Panama City's Class A office towers along Avenida Balboa, where multinational tenants mandate hospital-grade protocols exceeding baseline Ministry of Health standards.
- Maintenance:Preventive and corrective work on HVAC, electrical, and plumbing systems requires certified technician deployment. Panama Pacifico special economic zone multinationals are consolidating vendor relationships with providers carrying ETTI equipment calibration certifications to reduce procurement delays.
- Security:Personnel-based access control and surveillance integration for banking and logistics corridors.
- Landscaping:Exterior grounds maintenance with seasonal irrigation management for commercial campuses.
Cleaning leads volumes today; maintenance is gaining share fastest as building owners prioritize predictive asset management over reactive repair cycles.
End User:
Contract economics vary sharply by sector liability exposure, with healthcare and commercial commanding compliance premiums while residential and educational compete on cost efficiency.
- Commercial:Office towers, retail centers, and mixed-use developments requiring integrated service bundles. Banking and logistics tenants in Panama Pacifico are specifying bilingual operations teams and customs-adjacent security protocols as mandatory contract terms.
- Healthcare:Hospitals, clinics, and medical laboratories with specialized biomedical waste handling and infection control mandates. The Ministry of Health's updated sanitation protocols are forcing private clinic operators to consolidate with certified healthcare facility management specialists.
- Residential:Condominium and apartment building management focused on amenity maintenance and common area upkeep.
- Educational:School and university campus facilities with seasonal demand fluctuations tied to academic calendars.
Commercial anchors revenue concentration; healthcare exhibits the steepest expansion trajectory as hospital networks extend outsourced contracts across Panama City and Colón.
Technology:
Technology deployment separates premium providers from commodity competitors, with software and IoT requiring capital investment that reshapes contract margin structures.
- IoT Solutions:Sensor networks for predictive HVAC monitoring, occupancy-based lighting optimization, and real-time air quality tracking. Building owners in Avenida Balboa towers are deploying these systems to demonstrate energy compliance to multinational tenants and reduce administrative overhead.
- Software:Computerized maintenance management systems with mobile workforce interfaces automating work order dispatch and asset tracking. Property managers are adopting these platforms to replace paper logs and verbal coordination systems.
- Automation:Robotic cleaning equipment and automated access control systems reducing labor dependency.
- Energy Management:Monitoring-based commissioning services and building performance optimization tools.
Software dominates current adoption; IoT Solutions is climbing the fastest as sensor deployment costs decline and energy efficiency mandates tighten procurement criteria.
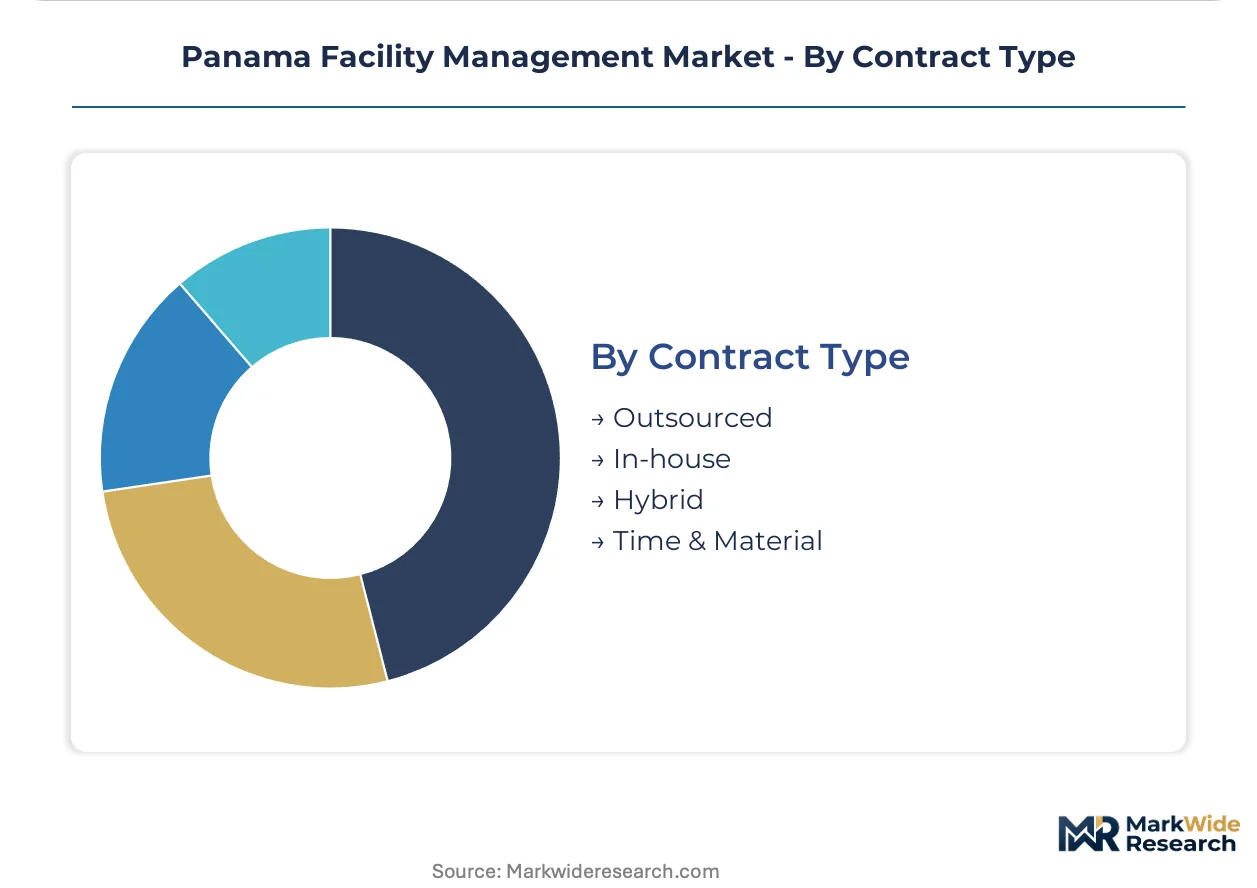
Contract Type:
Panamanian firms are reconfiguring procurement around risk transfer, shifting from long-term bundled arrangements toward performance-based structures with explicit accountability metrics.
- Outsourced:Third-party providers assume full operational responsibility including regulatory liability and specialized labor recruitment. This model captures disproportionate growth as firms seek to offload compliance burdens from the Ministry of Commerce and Industry's labor regulations and Ministry of Health facility protocols.
- In-house:Direct employment of facility staff retaining owner control over capital planning and operational decisions.
- Hybrid:Core functions retained internally with specialized services contracted to external providers.
- Time & Material:Reactive service arrangements for non-recurring maintenance needs and emergency response.
Outsourced contracts lead volume expansion; hybrid structures are advancing most quickly as owners retain strategic control while externalizing compliance-intensive functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified facility technicians cluster disproportionately in Panama City, creating service radius constraints that limit provider expansion into secondary markets. This concentration shapes contract economics across the isthmus.
Panama City
Class A office towers along Avenida Balboa drive demand for integrated security-cleaning-landscaping bundles with bilingual operations teams. The Ministry of Health's updated sanitation protocols tighten compliance requirements for healthcare-adjacent commercial properties. Banking and logistics tenants in the metropolitan core specify hospital-grade protocols that exceed baseline regulatory standards.
Panama Pacifico Special Economic Zone
Multinational headquarters and logistics operations require technology-enabled facility management with IoT sensor networks for predictive HVAC monitoring. The Ministry of Commerce and Industry's labor regulations elevate specialized recruitment costs for providers serving this corridor. Customs-adjacent security protocols and energy efficiency mandates reshape procurement criteria for zone operators.
Colón
The Free Trade Zone's warehouse and logistics facilities remain underserved by integrated providers capable of bilingual operations and specialized security protocols. Port-adjacent infrastructure demands equipment calibration certifications from the Technical Standards and Industrial Metrology Unit that create procurement delays. Caribbean hub operators seek bundled services that reduce vendor fragmentation across security, cleaning, and maintenance functions.
Healthcare networks across Colón are extending outsourced contracts to cover biomedical waste handling and infection control protocols that align with Ministry of Health mandates.
David and Chiriquí Province
Secondary city commercial developments compete on cost efficiency rather than compliance premiums, limiting technology adoption rates among local providers. Agricultural processing and logistics facilities generate seasonal demand fluctuations that complicate workforce scheduling. Regional operators face margin compression from minimum wage adjustments without offsetting contract value from specialized service tiers.
Azuero Peninsula
Tourism and hospitality facilities in Los Santos and Herrera provinces drive demand for exterior grounds maintenance and seasonal irrigation management. Small-scale commercial properties rely on fragmented local vendor relationships rather than integrated national contracts. The absence of certified technicians for building automation systems restricts service quality differentiation in this sub-region.
Panama Facility Management Market Competitive Landscape
Top-tier vendors anchor premium compliance-intensive contracts, while mid-tier operators compete on labor arbitrage and geographic coverage. The market structure tilts toward consolidation around providers carrying specialized healthcare certifications and ETTI equipment calibration credentials. Two strategic archetypes dominate: integrated security-cleaning bundles for banking-logistics corridors, and technology-enabled workplace analytics platforms for multinational tenants. Competitive moves center on vendor consolidation to capture healthcare network contracts and IoT partnership formations to embed predictive maintenance capabilities.
Among Spanish-origin integrated service providers, EULEN Group exemplifies the bundled security-cleaning archetype targeting high-specification banking and logistics contracts. CBRE Group, Inc. occupies a position representing multinational real estate services platforms with proprietary workplace analytics capabilities. H&H Facility Management Corp anchors the healthcare specialization tier through sanitation protocols exceeding Ministry of Health baseline requirements. These three entities collectively illustrate the segmentation between compliance depth, technology integration, and sector-specific certification that defines competitive positioning in Panama's facility management sector.
| Leading Market Players |
|---|
| EULEN Group |
| H&H Facility Management Corp |
| CBRE Group, Inc. |
| Accuro Prime |
| One Facilities Asset Management |
| Sodexo Inc. |
| Hines Group |
| Newmark & Company Real Estate, Inc. |
| Ecolab Inc. |
| Others |
Value Network & Pricing Analysis
IoT sensor deployment across Panama City's Class A towers simultaneously compresses labor cost economics and concentrates procurement power with technology-enabled providers. Building owners deploying predictive maintenance networks favor vendors carrying ETTI equipment calibration certifications, reshaping supplier qualification thresholds.
Pricing Analysis
Bundled security-cleaning-landscaping contracts command premium positioning over unbundled standalone services. Pricing stratifies across healthcare-certified, technology-embedded, and basic labor tiers based on Ministry of Health compliance depth and bilingual operations capability. Cost compression in standard cleaning tiers intensifies because Panama's minimum wage adjustments and social security contribution requirements squeeze margins. Residential and educational segments exhibit highest price sensitivity, while Panama Pacifico multinationals accept premium rates for integrated compliance bundles.
Supply Chain Analysis
Warehouse-distribution layers concentrate certified technician pools and equipment calibration facilities within Panama City's metropolitan corridor. Supply draws from Costa Rica, Colombia, and domestic training centers for specialized medical-grade sanitation credentials. Critical inputs include IoT sensor hardware, industrial cleaning chemicals, and HVAC replacement components. Single-source vulnerability runs through Panama City-based ETTI certification bottlenecks that delay equipment deployment. Distribution runs through hub-and-spoke patterns radiating from Avenida Balboa service centers to Colón and secondary provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panama's facility management sector functions as a stable compounder anchored by healthcare infrastructure expansion and regulatory compliance deepening. Outsourced contract growth transfers operational liability while creating recurring revenue visibility.
For Market Incumbents: Anchor market position by consolidating healthcare network contracts before specialized sanitation mandates harden. Invest in ETTI equipment calibration credentials to reduce procurement delays that disadvantage competitors. Vertical integration into bilingual technician training programs defends against talent scarcity in Panama Pacifico and Colón corridors. For New Entrants and Emerging Players: Capture the Colón Free Trade Zone's underserved warehouse and logistics facilities where integrated providers remain scarce. Target bilingual operations capabilities and customs-adjacent security protocols as mandatory differentiators. Lead with technology-enabled occupancy sensor bundling to penetrate Class A office towers seeking dynamic sanitation scheduling. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional operators lacking healthcare certifications but holding geographic coverage in Chiriquí Province. Long-term viability centers on providers embedding IoT partnerships for predictive maintenance capabilities. Watch Ministry of Health enforcement intensity as the signal indicating compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Certification Investment | ETTI calibration credentials reduce procurement delays for Panama Pacifico multinationals. |
| IoT Partnership Formation | Sensor network embedding captures premium pricing from Avenida Balboa Class A towers. |
| Geographic Expansion to Colón | Free Trade Zone logistics facilities lack integrated bilingual facility management providers. |
| Technician Training Program Development | Certified medical-grade sanitation specialists concentrate disproportionately in Panama City. |
| Performance-Based Contract Restructuring | Explicit KPIs for energy consumption transfer operational risk while retaining owner oversight. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture facility management contract dynamics across Panama. Primary discussions engaged facility directors at hospital networks, property managers in Avenida Balboa towers, procurement leads at Panama Pacifico multinationals, and operations heads at Colón Free Trade Zone logistics firms. Secondary validation drew from Ministry of Health sanitation protocol filings, ETTI equipment calibration registries, Panama Pacifico special economic zone investment disclosures, and Ministry of Commerce and Industry labor regulation updates. Bottom-up service provider revenue aggregation and top-down end-user spending estimates were triangulated for consistency.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including service type intensity, end-user sector liability exposure, technology embedding depth, and contract risk transfer structure. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated Ministry of Health enforcement timelines and energy efficiency mandate progression patterns.
Regulatory enforcement delays, labor cost acceleration beyond minimum wage schedules, and IoT sensor deployment cost volatility are the dominant revision risks that could reshape provider margin structures. Forecasts reflect documented assumptions regarding compliance deepening and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
GCC Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Romania Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Sweden Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Bulgaria Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
Belgium Facility Management Market