
 India Facility Management Market | 2026-2036
India Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Facility Management Market Outlook
Corporate occupiers are unwinding reliance on fragmented vendor networks and consolidating under integrated facility management contracts. CBRE South Asia leverages its pan-India property management platform to capture multi-year campus agreements. JLL India anchors its competitive position through technology-augmented workplace solutions serving Fortune 500 tenants. BVG India dominates the government and public sector vertical with its large-scale workforce deployment capabilities.
Facility management encompasses the integrated coordination of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, catering) to ensure operational continuity of built environments, governed by service level agreements specifying response times, uptime thresholds, and compliance metrics. Cleaning and security services constitute the volume base of the market, while Building Management Systems and IoT Solutions represent the fastest-growing margin pool as asset owners prioritize predictive maintenance and energy optimization. The outsourced deployment model is displacing captive facility teams across Corporate Offices and Healthcare Facilities as labor regulation complexity rises.
BIS building safety standards, the CEA energy efficiency framework, and state-level municipal bylaws collectively mandate fire system audits, electrical compliance certification, and water conservation protocols that FM providers must embed into service delivery. The PLI scheme for manufacturing is creating a parallel compliance layer as new industrial facilities require ISO-certified facility operations from day one. Stakeholders must decide whether to build in-house IoT-integrated command centers or partner with technology-native FM platforms as the definition of baseline service delivery shifts.
Market Dynamics
Corporate occupiers across Indian metros are consolidating fragmented vendor networks into single-source integrated facility management contracts, compressing procurement cycles and elevating compliance requirements as BIS building safety standards and CEA energy mandates harden.
Growth Catalysts
- PLI Manufacturing Incentives:New industrial facilities under the Production Linked Incentive scheme require ISO-certified facility operations from commissioning, creating immediate demand for specialized hard and soft service bundles.
- IT-ITeS Campus Expansion:Hyderabad, Bengaluru and Pune clusters are outsourcing entire facility ecosystems as lease structures shift to managed service models with uptime guarantees.
- IoT-Enabled Predictive Maintenance:Building Management Systems integration is replacing reactive maintenance schedules with sensor-driven asset monitoring, reducing downtime penalties in pharmaceutical and data center environments.
Market Restraints
- Skilled Technician Scarcity:Certified MEP engineers and fire safety auditors command wage premiums that compress margins on fixed-price annual contracts.
- State Regulatory Fragmentation:Maharashtra, Karnataka and Telangana maintain divergent municipal bylaws for electrical compliance and water conservation, forcing multi-location operators to maintain parallel certification protocols.
- Captive Team Inertia:Public sector institutions and legacy manufacturing units retain in-house facility teams despite higher lifecycle costs, delaying outsourcing conversion.
Strategic Opportunities
- Tier-II City Penetration:Coimbatore, Indore and Visakhapatnam industrial corridors lack integrated FM capacity, creating first-mover advantages for operators establishing localized command centers.
- Healthcare Facility Specialization:NABH accreditation requirements for infection control and biomedical waste management are opening dedicated service verticals distinct from standard commercial offerings.
- Green Building Integration:IGBC and GRIHA certification mandates are converging energy audit, water recycling and waste management services into unified sustainability contracts.
Industry Challenges
- Workforce Deployment Scale:Large campus contracts require same-day mobilization of 500+ security and housekeeping personnel with verified background documentation, straining recruitment pipelines.
- Legacy System Integration:Brownfield commercial properties operate incompatible mechanical and electrical infrastructures that resist standardized IoT sensor deployment without capital-intensive retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Facility Management Market |
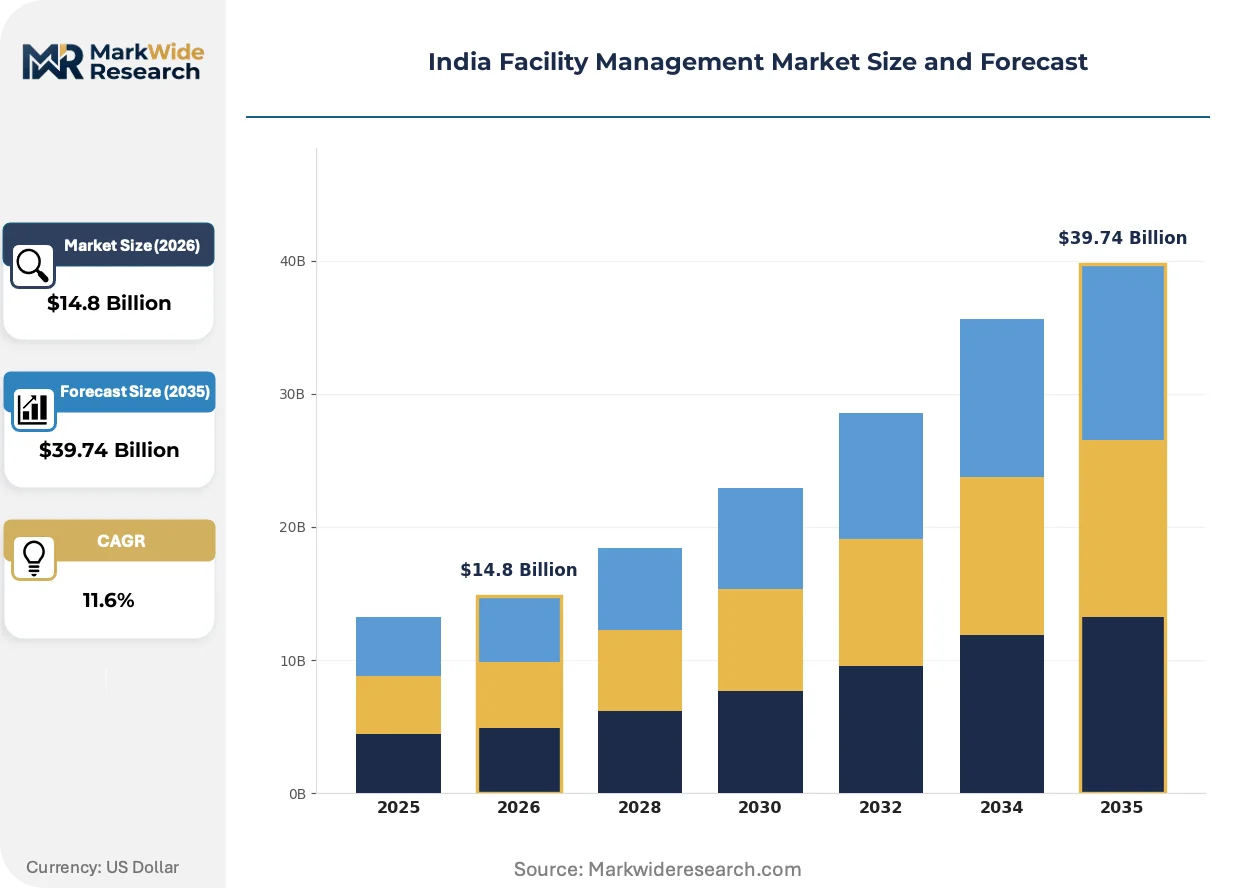
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Catering End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Residential Complexes Technology: Building Management Systems, Energy Management, Security Systems, IoT Solutions Deployment: On-site, Remote Monitoring, Hybrid, Outsourced |
| Companies Covered | Sodexo Facilities Management, Quess Corp, CBRE South Asia, G4S India, Cushman & Wakefield, JLL India, BVG India, Tenon Group, ISS Facility Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Facility Management Market Strategic Shifts
Technology convergence and regulatory compression are redefining baseline service delivery, with asset owners demanding predictive capabilities and compliance automation that legacy operational models cannot support.
Edge-computing sensor arrays for HVAC and electrical monitoring are miniaturizing from rack-mounted controllers to wireless node networks. IT-ITeS campuses in Hyderabad and Bengaluru are deploying these systems at scale during fit-out phases. The technology is miniaturizing hardware footprints while expanding real-time data granularity, enabling sub-hour response commitments that previously required on-site engineering presence.
BIS fire safety audit mandates and CEA energy efficiency frameworks are tightening certification cycles for commercial buildings. Facility operators must now embed continuous compliance documentation into service delivery rather than periodic inspection reporting. Pharmaceutical manufacturing hubs in Telangana face the steepest compliance density, with dual BIS and ISO certification requirements driving specialized operator selection.
Corporate procurement functions are unbundling traditional bundled contracts into outcome-based service level agreements with penalty structures tied to measurable uptime, energy efficiency and occupant satisfaction metrics. Integrated FM providers are displacing standalone security and cleaning vendors in Mumbai and Delhi-NCR corporate complexes. The shift is most pronounced among Fortune 500 occupiers with standardized global facility KPIs requiring Indian portfolio alignment.
India Facility Management Market Segmentation
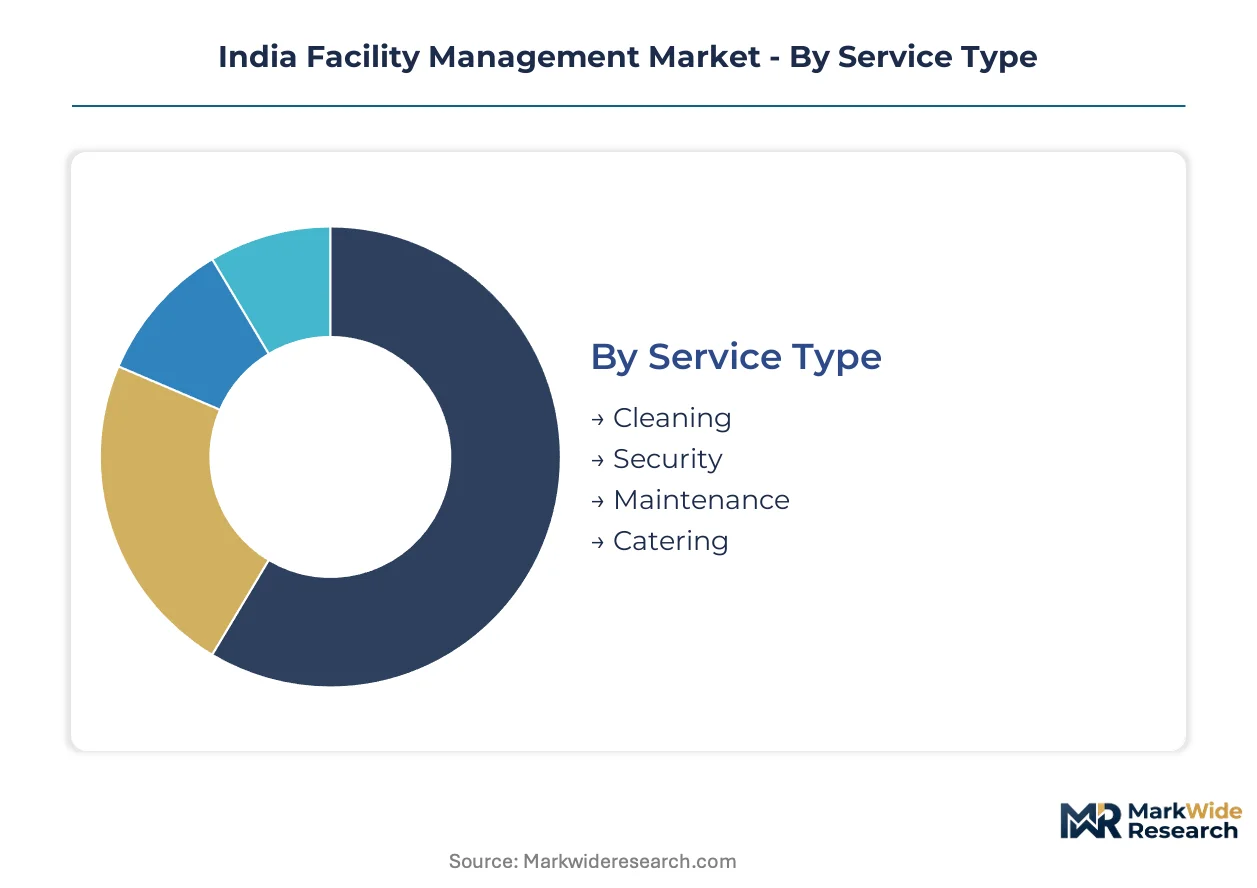
Facility management procurement in India diverges sharply by service intensity and compliance burden. Corporate occupiers segment contracts based on whether services require physical presence, specialized certification, or real-time technology integration.
Service Type:
Channel distribution varies by labor intensity versus equipment intensity, with manpower-heavy services flowing through regional staffing networks and technology-enabled services consolidating under national platforms.
- Cleaning:Labor-intensive operations requiring background-verified personnel deployment at scale. Maharashtra and Karnataka corporate campuses drive volume as lease agreements mandate daily frequency standards with BIS hygiene protocols.
- Security:Personnel-based service with rising technology augmentation through biometric access and CCTV integration. Hyderabad IT-ITeS clusters demand PSARA-licensed guards with command center connectivity.
- Maintenance:Hard services spanning MEP systems governed by CEA energy efficiency mandates and state electrical inspectorate requirements.
- Catering:FSSAI-compliant food service operations concentrated in technology parks and healthcare facilities with 24/7 operational requirements.
By volume, Cleaning leads. By growth pace, Maintenance is ahead.
End User:
Customer procurement maturity determines contract structure complexity, with Fortune 500 tenants demanding integrated SLAs and public institutions retaining fragmented purchasing.
- Corporate Offices:Integrated FM contracts with uptime guarantees and IoT-enabled asset monitoring. Bengaluru and Pune IT campuses are consolidating vendor networks under single-source agreements.
- Healthcare Facilities:NABH accreditation requirements for infection control and biomedical waste management create specialized procurement distinct from commercial standards.
- Educational Institutions:Seasonal demand patterns with security and cleaning bundled under annual tenders governed by state education department bylaws.
- Residential Complexes:RERA-mandated maintenance funds driving outsourced facility management in Mumbai and Delhi-NCR high-rise developments.
Corporate Offices command premium pricing. Healthcare Facilities show the steepest expansion trajectory.
Technology:
Margin concentration follows data granularity, with platforms capturing recurring SaaS revenue displacing one-time hardware sales.
- Building Management Systems:Centralized HVAC and electrical control platforms with predictive maintenance algorithms. Pharmaceutical manufacturing hubs in Telangana require BMS integration for continuous environmental monitoring.
- IoT Solutions:Wireless sensor networks for real-time asset health monitoring with edge computing capabilities reducing response latency below one hour.
- Energy Management:CEA-compliant audit and optimization services with penalty-linked performance contracts.
- Security Systems:Integrated access control and surveillance with central monitoring station connectivity.
BMS dominates current deployment. IoT Solutions are climbing the fastest.
Deployment:
Model selection hinges on regulatory risk transfer, with PLI manufacturing facilities mandating outsourced ISO-certified operations from commissioning.
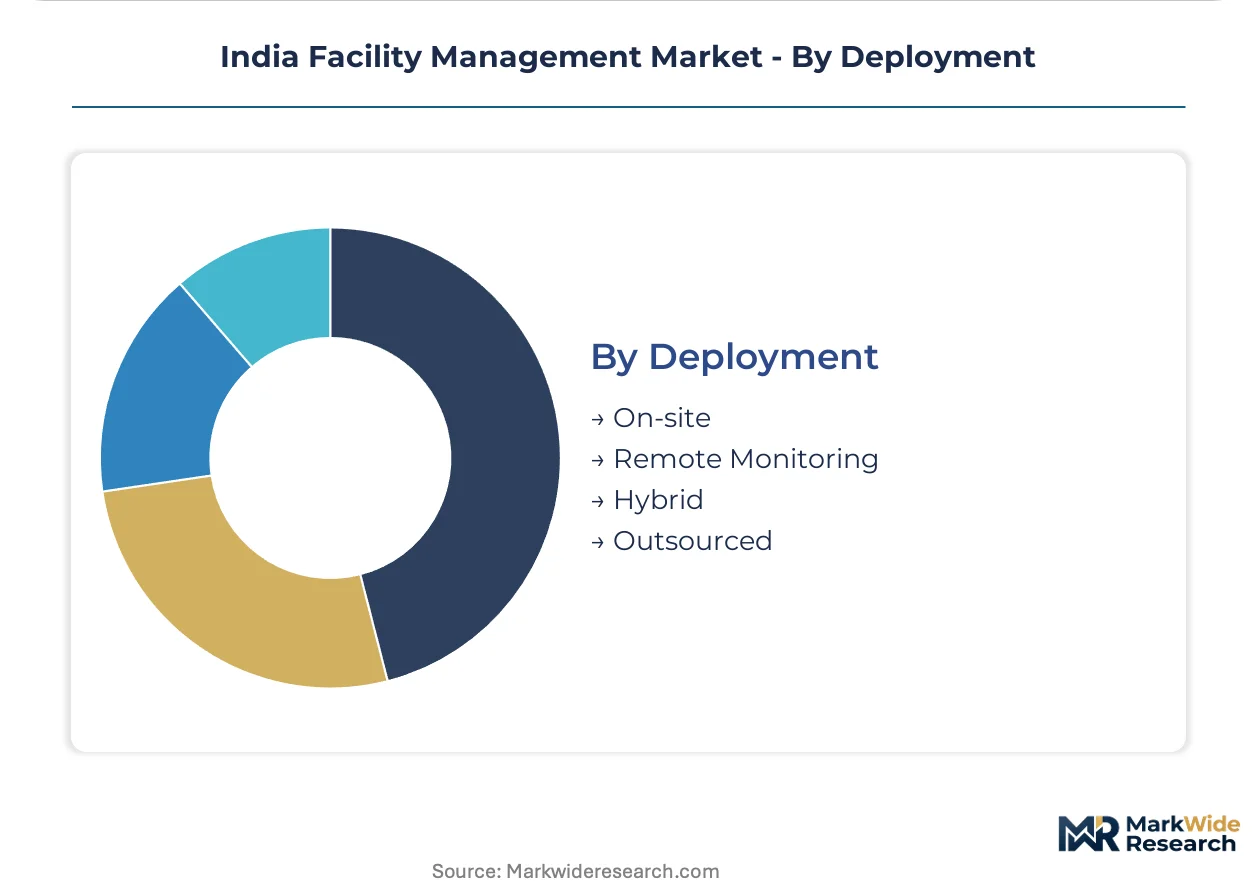
- Outsourced:Full risk transfer with fixed-price contracts and SLA penalties. IT-ITeS campuses in Hyderabad and Bengaluru prefer this model for compliance burden absorption.
- Hybrid:Core engineering staff retained with soft services outsourced, common in legacy manufacturing units transitioning from captive teams.
- On-site:Traditional manned presence model with direct employment, persisting in public sector institutions despite higher lifecycle costs.
- Remote Monitoring:Technology-enabled oversight with limited physical presence, suitable for standardized commercial assets with BMS infrastructure.
Outsourced deployment holds the largest share. Hybrid models are gaining share fastest as brownfield assets retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's facility management demand flows from manufacturing and IT services exports to North American and European corporate buyers, with domestic metros serving as operational command centers for global delivery.
Maharashtra
Mumbai's financial district and Pune's automotive corridor drive integrated FM contracts with uptime mandates. The state's municipal bylaws enforce strict electrical compliance certification for commercial high-rises. Thane-Belapur industrial belt is absorbing outsourced facility teams as PLI-backed manufacturing facilities commission.
Karnataka
Bengaluru's IT-ITeS campuses account for concentrated demand for IoT-enabled building management and 24/7 security staffing. CEA energy efficiency audits are mandatory for commercial buildings exceeding specified consumption thresholds. Electronics City and Whitefield clusters are consolidating fragmented vendor networks under single-source agreements.
Telangana
Hyderabad's pharmaceutical manufacturing hubs require specialized hard services with continuous environmental monitoring protocols. BIS fire safety standards and dual ISO certification requirements filter operator selection. Genome Valley and Pocharam IT parks are deploying predictive maintenance systems at scale during fit-out phases.
Delhi-NCR
Gurugram and Noida corporate complexes are shifting lease structures to managed service models with SLA penalties. RERA-mandated maintenance funds are accelerating outsourced facility management in residential high-rises. The sub-region's regulatory fragmentation across Haryana, Uttar Pradesh and Delhi municipal jurisdictions complicates multi-location operator certification.
Tamil Nadu
Chennai's automotive and electronics manufacturing base generates demand for ISO-certified facility operations from commissioning. State-level energy conservation building codes mandate audit-linked performance contracts. Sriperumbudur-Oragadam industrial corridor is attracting integrated FM providers establishing localized command centers.
India Facility Management Market Competitive Environment
Player mix skews toward diversified property services platforms with pan-India deployment infrastructure. Market structure concentrates around three strategic tiers: global real estate consultancies with integrated FM divisions, domestic workforce specialists with government sector anchoring, and technology-native platforms targeting IoT-enabled contracts. Dominant competitive moves include geographic densification in Tier-II industrial corridors and backward integration into command center software development.
Within the global consultancy tier, CBRE South Asia and JLL India exemplify technology-augmented workplace solutions targeting Fortune 500 tenants with standardized global facility KPIs. BVG India occupies a distinct position in the public sector vertical, leveraging large-scale workforce deployment capabilities for government and institutional contracts. These three anchors represent divergent strategic postures: technology-led premium positioning, integrated real estate services bundling, and labor-scale government specialization.
| Leading Market Players |
|---|
| Sodexo Facilities Management |
| Quess Corp |
| CBRE South Asia |
| G4S India |
| Cushman & Wakefield |
| JLL India |
| BVG India |
| Tenon Group |
| ISS Facility Services |
| Others |
Value Chain & Pricing Dynamics
BIS fire safety certification and CEA energy audit mandates gate both supplier qualification and price differentiation simultaneously, forcing operators to absorb compliance costs upfront while competing on outcome-based SLAs. Corporate procurement teams exploit this bifurcation to extract tiered pricing based on certification density and technology integration depth.
Pricing Analysis
Legacy manned-service contracts trade at substantial discounts to IoT-augmented predictive maintenance bundles, with next-generation BMS-integrated offerings commanding premiums of two to three tiers above baseline cleaning and security staffing. Pricing stratifies across ISO-certified hard services, PSARA-licensed security deployments, and FSSAI-compliant catering operations, with wage inflation for certified MEP engineers compressing margins on fixed-price annual contracts. Cost compression in volume-based soft services is intensifying because background-verified personnel deployment at scale requires recruitment infrastructure investments that smaller operators cannot amortize. Public sector institutions exhibit highest price sensitivity due to tender-driven procurement, while pharmaceutical manufacturing hubs in Telangana demonstrate lowest sensitivity given dual BIS-ISO compliance requirements.
Supply Chain Analysis
Just-in-time workforce mobilization dominates security and cleaning operations, while strategic stockpiling of MEP spare parts and IoT sensor hardware buffers against supply disruption in hard services. India draws from domestic labor pools for personnel-intensive services, sources Building Management Systems hardware from Taiwan and South Korea, and imports specialized fire safety equipment from Germany and USA. Single-source vulnerability concentrates in wireless sensor networks and edge-computing controllers, where three vendors control upstream manufacturing. Distribution runs through regional staffing networks for soft services and direct OEM relationships for technology-enabled platforms, with pan-India operators maintaining localized command centers to compress response latency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's facility management market functions as a service-attach opportunity where recurring SaaS revenue from IoT-enabled asset monitoring expands faster than one-time hardware deployment, creating durable margin pools for technology-integrated operators.
For Market Incumbents: Shield core corporate campus contracts by embedding predictive maintenance capabilities that standalone cleaning and security vendors cannot replicate, while backward integration into command center software development raises switching costs for Fortune 500 tenants facing standardized global facility KPIs. Consolidate fragmented vendor networks in Bengaluru and Hyderabad IT-ITeS clusters before technology-native platforms establish footholds. For New Entrants and Emerging Players: Anchor in Tier-II industrial corridors—Coimbatore, Indore, Visakhapatnam—where integrated FM capacity remains underdeveloped and first-mover advantages accrue to localized command center investments. Target NABH-accredited healthcare facilities with specialized infection control and biomedical waste management verticals distinct from saturated commercial offerings, deploying FSSAI-certified catering as the initial wedge for campus expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-enabled facility management platforms as sensor hardware and edge-computing infrastructure displace labor-heavy models, favoring scaled operators with amortized technology investments. Acquisition targets should display pan-India deployment infrastructure with existing BMS integration capabilities and government sector anchoring for revenue stability. Monitor PLI manufacturing facility commissioning announcements as the signal to watch for outsourced ISO-certified operations demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Command Center Software | Raises switching costs for Fortune 500 tenants requiring standardized global facility KPIs across Indian portfolios. |
| Tier-II City Command Center Establishment | Captures first-mover advantages in Coimbatore, Indore, and Visakhapatnam industrial corridors lacking integrated FM capacity. |
| NABH-Accredited Healthcare Vertical Development | Opens dedicated service lines for infection control and biomedical waste management distinct from commercial offerings. |
| IoT Sensor Hardware Partnership | Secures supply continuity for edge-computing arrays as Taiwan and South Korea vendors control upstream manufacturing. |
| Green Building Certification Bundling | Converges IGBC and GRIHA-mandated energy audit, water recycling, and waste management into unified sustainability contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with facility management executives, corporate real estate directors, and government procurement officers, combined with secondary validation through BIS certification databases, CEA energy audit filings, and state municipal bylaw repositories. Primary fieldwork encompassed discussions with MEP engineering heads, security operations managers, and healthcare facility administrators across Maharashtra, Karnataka, and Telangana. Bottom-up triangulation aggregated contract values and deployment scales by service type, while top-down cross-checks verified totals against PLI scheme facility commissioning announcements and IT-ITeS campus expansion disclosures.
Across the analysis window, forecasts modeled service type segmentation by labor intensity versus equipment intensity, end-user procurement maturity tiers, technology integration levels from basic manned presence to full BMS deployment, and deployment model evolution from captive teams through outsourced risk transfer. CAGRs derived from fitted growth curves incorporating regulatory mandate implementation timelines, manufacturing incentive scheme uptake rates, and technology adoption S-cycles specific to predictive maintenance penetration in pharmaceutical and data center environments.
Decision-makers should treat outputs as directional under assumptions of continued PLI scheme extension, stable state-level regulatory fragmentation, and gradual IoT hardware cost decline; material deviation in any assumption vector would warrant model refresh. Revision becomes warranted when skilled technician wage inflation crosses thresholds that trigger contract repricing clauses or when BIS mandates accelerate certification cycles beyond modeled compliance cost absorption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Spain Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Soft Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Bahrain Facility Management Market