
 Saudi Arabia Soft Facility Management Market | 2026-2036
Saudi Arabia Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Soft Facility Management Market Insights
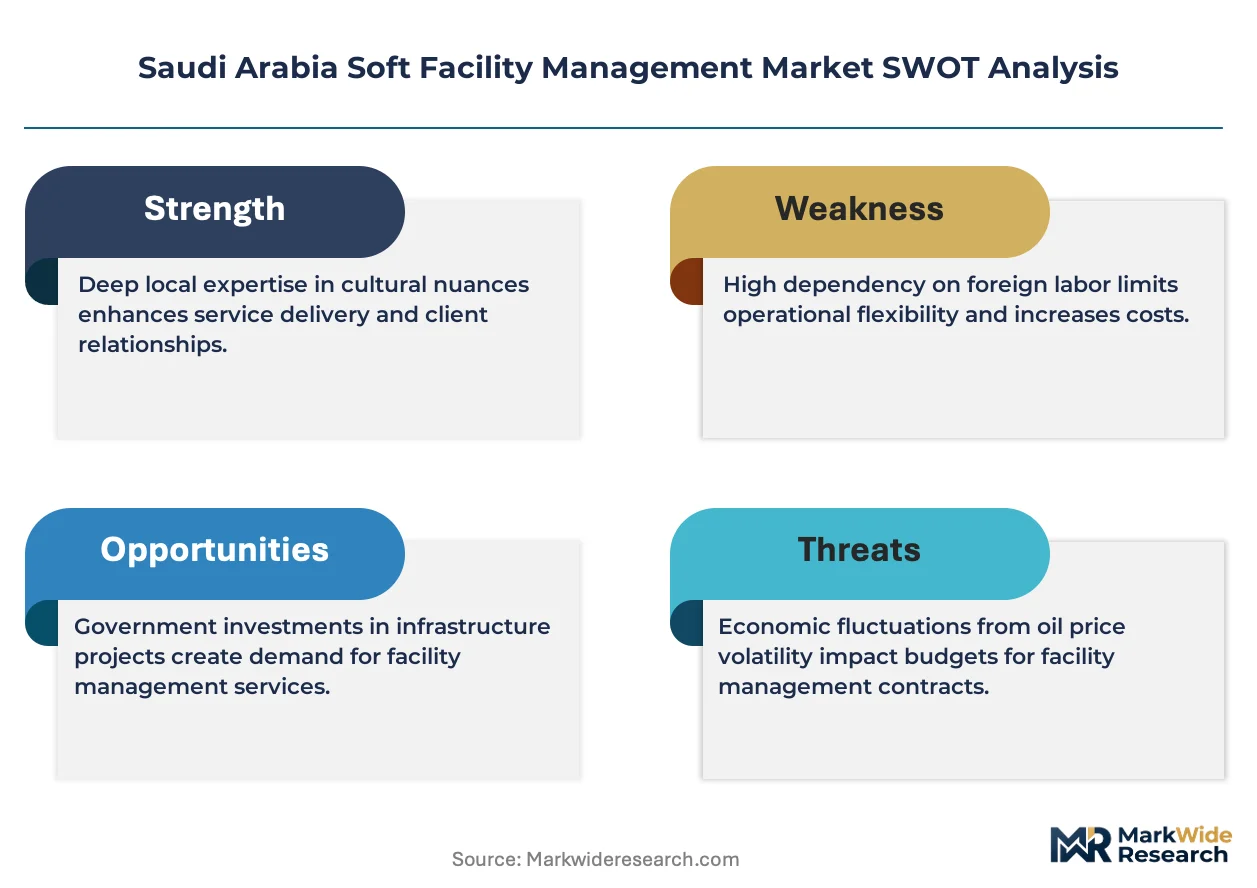
Saudi Vision 2030 is consolidating the competitive landscape for soft facility management by mandating privatization across public infrastructure. Khidmah leverages its integrated service platform to capture multi-site contracts in healthcare and education. EFS Facilities Services Group anchors its position through technology-driven delivery models that reduce labor dependency. Nesma United Industries competes via specialized industrial cleaning capabilities aligned with petrochemical site requirements.
Soft facility management encompasses non-technical building services including cleaning, security, catering, and landscaping, delivered through on-site, outsourced, hybrid, or technology-driven models with service level agreements typically measured by response time, occupancy satisfaction scores, and compliance audit results. Cleaning services dominate contract value due to frequency mandates in healthcare and food service environments, while technology-driven delivery represents the fastest-expanding segment as IoT-enabled work-order platforms replace paper-based dispatch. The outsourced delivery model captures premium pricing in commercial office buildings where landlords seek transfer of employment liability.
MOHAP and SASO enforce building hygiene and energy efficiency standards that shape procurement specifications for facility service contracts across hospitals and commercial properties. The Saudi Building Code mandates periodic compliance audits that elevate demand for certified facility operators over informal providers. Stakeholders must monitor how labor localization quotas under Nitaqat evolve to determine whether technology substitution or training investments become the preferred compliance pathway.
Market Dynamics
Saudi Vision 2030's privatization mandates are compressing procurement cycles across healthcare and education facilities, forcing incumbent operators to absorb employment liabilities while SASO energy audits ratchet up compliance costs for building hygiene standards.
Growth Catalysts
- SASO Energy Efficiency Standards:Mandatory building audits under the Saudi Building Code are disqualifying informal cleaning contractors and consolidating contract awards to certified facility operators with documented compliance protocols.
- Healthcare Privatization:MOHAP hospital outsourcing directives are transferring non-clinical service delivery to specialized vendors capable of meeting infection control frequency mandates in surgical and ICU environments.
- Giga-Project Construction:NEOM, Red Sea Global, and Qiddiya developments are pre-qualifying integrated facility management providers for multi-site service contracts spanning hospitality, retail, and residential clusters.
Market Restraints
- Labor Localization Quotas:Nitaqat program requirements for Saudi national employment ratios are inflating wage costs and constraining workforce scalability for labor-intensive cleaning operations.
- Petrochemical Site Concentration:Industrial cleaning demand clusters in Jubail and Yanbu, creating geographic dependency on cyclical energy sector capital expenditure cycles.
- Technology Substitution Lag:IoT-enabled work-order platforms require upfront sensor deployment and integration with legacy building management systems, delaying ROI realization for mid-size service providers.
Strategic Opportunities
- Western Province Expansion:Jeddah commercial office stock and Makkah hospitality infrastructure remain underpenetrated by integrated facility platforms compared to Riyadh saturation.
- Technology Convergence:Computer vision-enabled quality assurance systems combined with predictive maintenance algorithms are opening performance-based contract structures tied to occupancy satisfaction metrics.
- Education Sector Outsourcing:Ministry of Education school privatization pilots are creating entry points for specialized cleaning and security vendors with child safety certification protocols.
Industry Challenges
- Skilled Technician Scarcity:Certified HVAC and electrical maintenance personnel required for hybrid facility contracts are concentrated with oil sector employers offering premium compensation packages.
- Compliance Documentation Burden:SASO audit trails and MOHAP hygiene logs demand dedicated quality management systems that smaller operators lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Soft Facility Management Market |
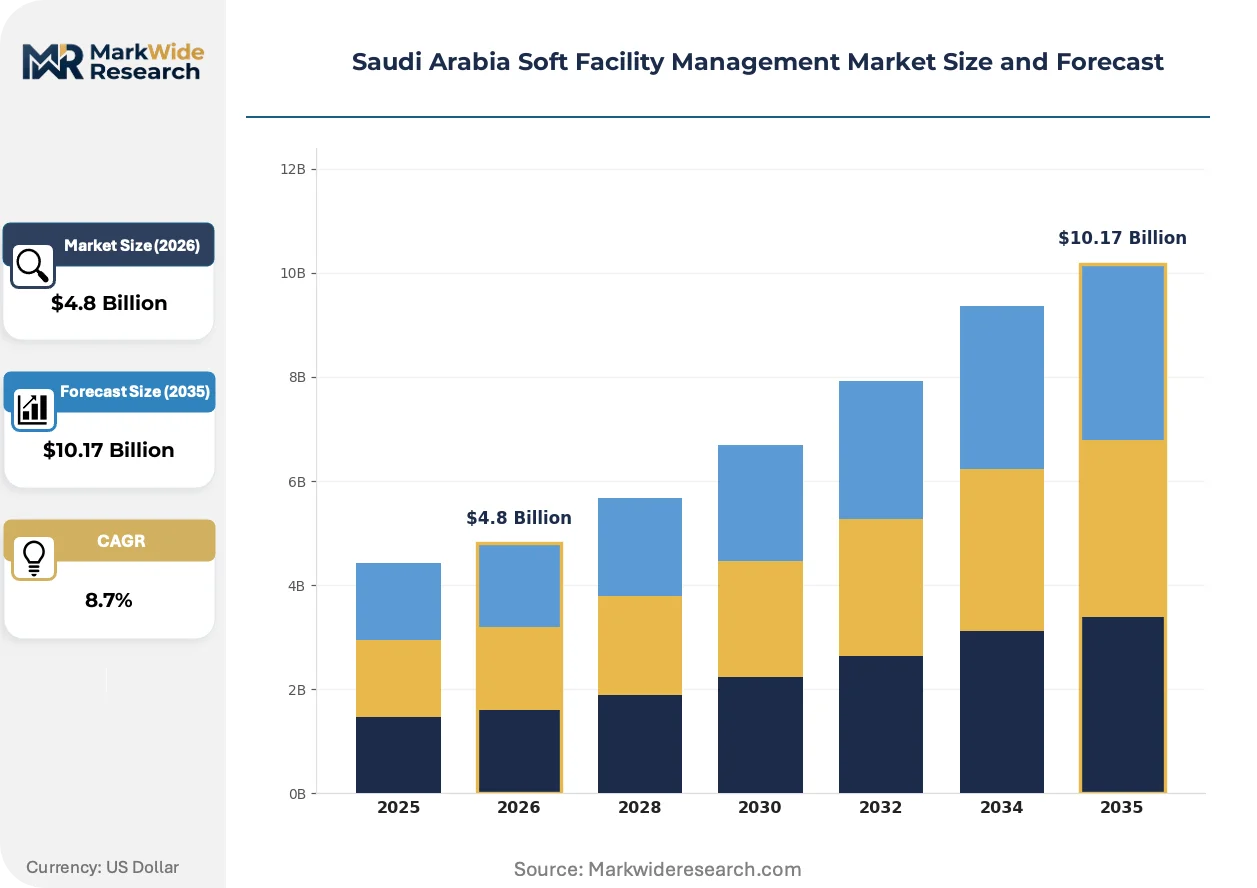
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Catering, Landscaping Client Type: Commercial, Residential, Educational, Healthcare Delivery Model: On-site, Outsourced, Hybrid, Technology-driven Application: Office Buildings, Shopping Malls, Hospitals, Industrial |
| Companies Covered | Initial Saudi Group, Khidmah, Crystal Facilities Management, SGS Saudi Arabia, ASMACS Group, Al Mofarreh Group, Nesma United Industries, EFS Facilities Services Group, Muheel Facilities Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Soft Facility Management Market Trends and Innovations
Facility service delivery is pivoting from labor arbitrage to technology-mediated performance guarantees, with contract structures absorbing outcome risk previously borne by building owners.
IoT-enabled dispatch platforms are rewriting operational economics for multi-site cleaning contracts. These systems aggregate sensor data from occupancy detectors and air quality monitors to trigger just-in-time service deployment rather than fixed schedules. Healthcare operators in Riyadh are adopting these platforms fastest, compressing response times from hours to minutes for spill and contamination events.
The Saudi Building Code's 2024 amendments mandate quarterly compliance documentation for commercial properties above 10,000 square meters. This regulatory friction is elevating procurement specifications to require certified facility operators with dedicated quality management personnel. Hospital landlords in Jeddah are responding by consolidating vendor relationships to reduce audit coordination overhead.
Building owners are unbundling service contracts from property management agreements and direct-sourcing specialized cleaning, security, and catering vendors. This disintermediation is displacing bundled facility management providers in premium commercial towers. The pattern is most visible in Riyadh's King Abdullah Financial District, where strata-titled buildings enable tenant-level procurement autonomy.
Saudi Arabia Soft Facility Management Market Segmentation
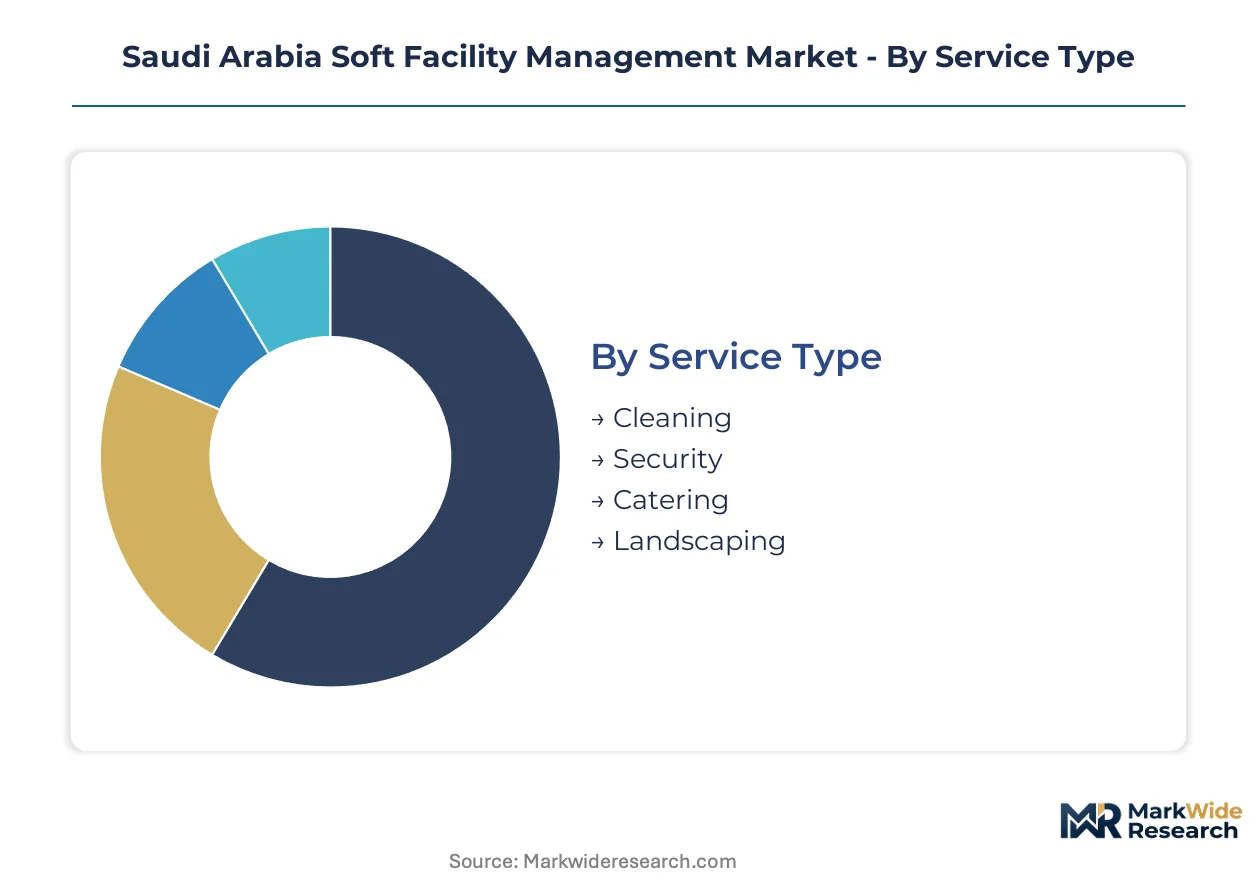
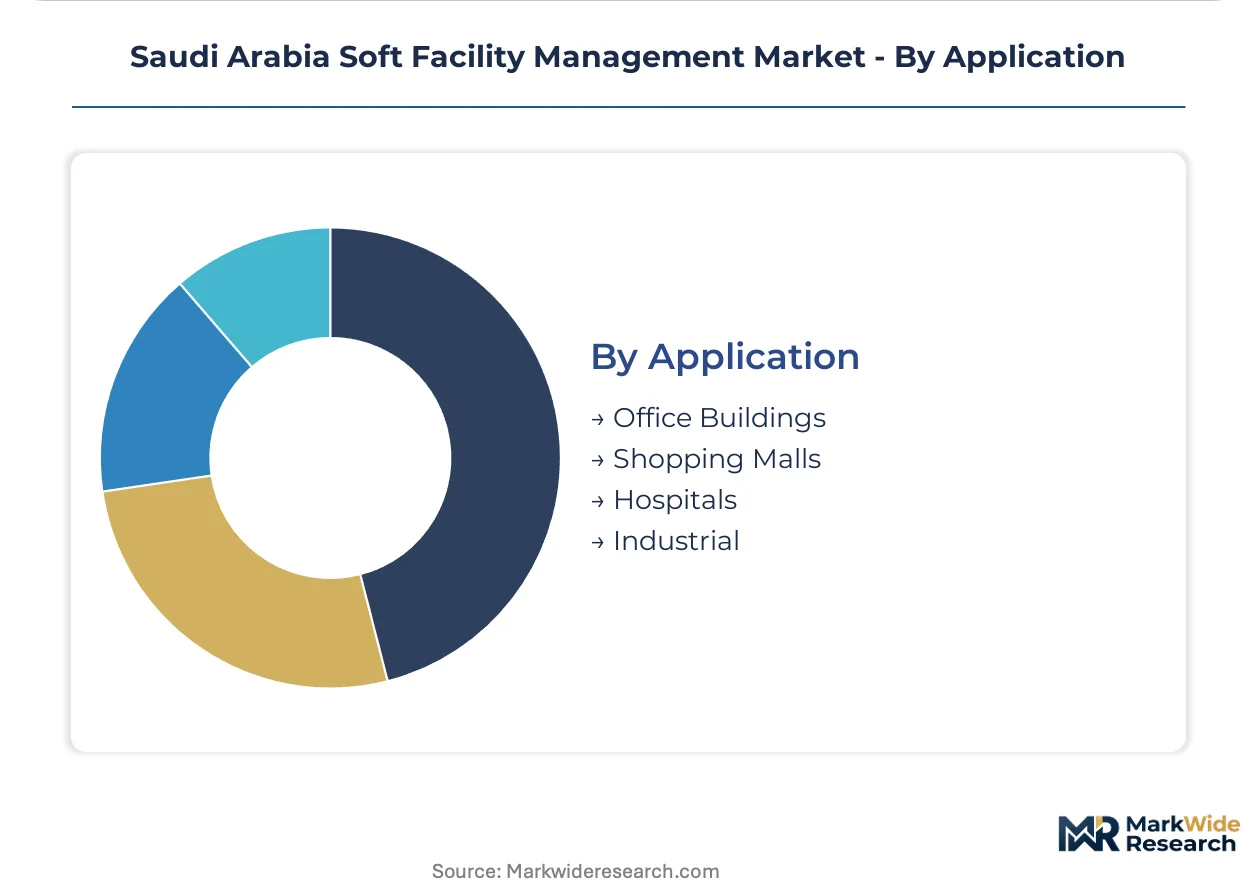
Soft facility management procurement in Saudi Arabia fragments across service intensity, asset class, and compliance burden. Contract structures vary dramatically between labor-intensive cleaning operations and sensor-mediated technology platforms.
Service Type:
Technical sophistication and regulatory frequency separate high-value contracts from commodity service tiers.
- Cleaning:Encompasses daily janitorial, deep sanitization, and infection control protocols certified to MOHAP hygiene standards. Demand concentrates in Riyadh's hospital clusters and Jeddah's food service environments where SASO audit frequency mandates documented compliance trails. Labor localization under Nitaqat inflates wage structures for this most employment-heavy segment.
- Security:Delivers access control, perimeter monitoring, and emergency response through manned guarding or integrated electronic systems. Demand concentrates in Makkah hospitality infrastructure and Qiddiya entertainment precincts where crowd management protocols require Saudi national supervisory ratios. Technology substitution via biometric access systems is compressing headcount requirements.
- Catering:Provides food preparation, meal delivery, and dietary compliance for institutional clients. Healthcare and education facilities in Jeddah drive contract volume.
- Landscaping:Maintains irrigation, horticulture, and hardscape aesthetics for commercial and residential properties. Water scarcity regulations in Riyadh constrain expansion.
Cleaning leads on scale; technology-driven security leads on momentum.
Client Type:
Asset ownership structure and regulatory oversight intensity shape vendor selection criteria and contract duration.
- Commercial:Encompasses office towers, retail centers, and mixed-use developments where landlords seek transfer of employment liability. Demand concentrates in King Abdullah Financial District and Jeddah's commercial corridors where strata titling enables tenant-level procurement autonomy. Outsourced delivery models capture premium pricing here.
- Healthcare:Covers hospitals, clinics, and medical office buildings subject to MOHAP infection control mandates. Demand concentrates in Riyadh's expanding hospital clusters where privatization under Vision 2030 is transferring non-clinical services to specialized vendors. Compliance documentation requirements exceed all other client categories.
- Residential:Serves compound housing, apartment towers, and villa communities. Giga-project residential clusters at NEOM and Red Sea Global are pre-qualifying integrated providers.
- Educational:Includes K-12 schools and university campuses where Ministry of Education privatization pilots are creating entry points for certified cleaning and security vendors. Child safety certification protocols differentiate qualified operators.
Commercial leads on contract value concentration; healthcare leads on compliance-driven vendor consolidation.
Delivery Model:
Capital intensity and labor dependency determine margin structure and scalability constraints.
- Technology-driven:Deploys IoT sensors, computer vision systems, and predictive analytics to trigger just-in-time service dispatch. Healthcare operators in Riyadh are adopting these platforms fastest, compressing response times from hours to minutes for contamination events. Upfront sensor deployment delays ROI realization for mid-size providers.
- Outsourced:Transfers full employment liability and operational risk to third-party vendors. Commercial office buildings in premium Riyadh towers favor this model for regulatory shielding.
- Hybrid:Combines in-house supervision with contracted labor for specialized functions. Industrial clients in Jubail petrochemical corridors use this structure.
- On-site:Maintains dedicated captive workforce under direct client employment. Large hospital systems retain this model for critical infection control roles.
Outsourced models lead on current contract volume; technology-driven platforms lead on expansion trajectory.
Application:
Building use intensity and occupancy patterns dictate service frequency specifications and performance metrics.
- Hospitals:Requires 24/7 cleaning coverage with surgical suite sterilization protocols and waste management compliance. MOHAP hygiene logs demand dedicated quality management systems that elevate procurement specifications to certified operators.
- Office Buildings:Encompasses Class A towers and business parks where occupancy sensors enable demand-responsive cleaning schedules. King Abdullah Financial District buildings are unbundling service contracts from property management agreements.
- Shopping Malls:Sustains high-footfall environments with food court sanitation and common area maintenance. Makkah and Madinah pilgrimage retail infrastructure drives seasonal demand spikes.
- Industrial:Covers petrochemical sites, manufacturing facilities, and logistics hubs requiring specialized cleaning for hazardous material handling. Demand clusters in Jubail and Yanbu with cyclical energy sector capital expenditure dependency.
Hospitals lead on compliance premium capture; office buildings lead on technology adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified facility technicians cluster in Riyadh and Jeddah, anchoring service delivery capacity for the kingdom's expanding healthcare and commercial infrastructure.
Riyadh
King Abdullah Financial District office towers and expanding hospital clusters under MOHAP privatization directives drive contract volume. The Saudi Building Code mandates quarterly compliance documentation for commercial properties above 10,000 square meters. NEOM giga-project procurement teams maintain satellite offices in Riyadh, pre-qualifying integrated facility operators for northwest development contracts.
Eastern Province
Petrochemical facilities in Jubail and Yanbu generate specialized industrial cleaning demand tied to energy sector capital expenditure cycles. SASO energy efficiency audits enforce documented compliance protocols that disqualify informal contractors. The concentration of hazardous material handling sites creates geographic dependency on cyclical downstream investment.
Western Region
Jeddah commercial office stock and Makkah hospitality infrastructure remain underpenetrated by integrated facility platforms. Red Sea Global developments are pre-qualifying multi-site service providers for hospitality, retail, and residential clusters. Water scarcity regulations constrain landscaping service expansion across the region.
NEOM Northwest
The linear city development is sourcing technology-driven facility management platforms with IoT-enabled dispatch capabilities. Vision 2030 giga-project procurement specifications favor certified operators capable of spanning hospitality, retail, and residential service clusters. Sensor deployment requirements for predictive maintenance algorithms are elevating upfront capital barriers for mid-size providers.
Saudi Arabia Soft Facility Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale advantages in Riyadh contrast with regional specialization in industrial corridors. The vendor base clusters around three strategic archetypes: integrated platforms capturing multi-site healthcare and education contracts, technology-enabled operators reducing labor dependency through IoT dispatch systems, and industrial specialists aligned with petrochemical site requirements. Consolidation pressure intensifies as SASO audit mandates disqualify informal providers, while Nitaqat localization quotas force workforce restructuring decisions.
Within the integrated platform tier, Khidmah and EFS Facilities Services Group occupy positions representing technology-mediated service delivery models. Nesma United Industries anchors the industrial specialization vector. These three exemplify how competitive positioning diverges between Riyadh-centric multi-site operators and Eastern Province-focused technical service providers.
| Leading Market Players |
|---|
| Initial Saudi Group |
| Khidmah |
| Crystal Facilities Management |
| SGS Saudi Arabia |
| ASMACS Group |
| Al Mofarreh Group |
| Nesma United Industries |
| EFS Facilities Services Group |
| Muheel Facilities Management |
| Others |
Pricing and Supply Chain Analysis
Certified operator premiums against informal contractor discounts bifurcate Saudi soft facility management, with SASO audit mandates compressing the middle tier while technology-enabled providers capture performance-linked uplifts and labor-intensive services face Nitaqat wage inflation.
Pricing Analysis
Bundled property management agreements command 15-25% premiums over unbundled direct sourcing as landlords transfer employment liability, though King Abdullah Financial District tenants increasingly disintermediate for specialized cleaning and security. Price differentiation rests on MOHAP certification grade and IoT platform integration depth, with healthcare sterilization protocols justifying substantial uplifts over commercial janitorial baselines. Cost compression in commodity cleaning intensifies as Nitaqat localization inflates Saudi national wage structures. Government hospital privatization tenders exhibit lowest price sensitivity; strata-titled commercial offices show highest.
Supply Chain Analysis
MOHAP and SASO qualification gating concentrates vendor accreditation capacity in Riyadh and Jeddah, where certified training facilities and audit documentation systems cluster around healthcare and commercial development corridors. Labor supply draws from India, Bangladesh, and the Philippines for technician and operative roles, while IoT sensor hardware sources from China and South Korea. Single-source vulnerability runs through Saudi national certification bottlenecks for infection control specialists. Distribution runs through direct procurement by giga-project developers and hospital privatization consortia, bypassing traditional facilities management intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia soft facility management functions as a stable compounder, with Vision 2030 privatization mandates generating predictable contract flow across healthcare and education infrastructure.
For Market Incumbents: To counter disintermediation by strata-titled commercial buildings, deepen technology platform differentiation through computer vision quality assurance and predictive maintenance algorithms. Absorb compliance documentation capabilities via dedicated quality management system investments that smaller operators cannot replicate, consolidating multi-site healthcare contracts under integrated service platforms. For New Entrants and Emerging Players: Launch via technology-enabled service delivery targeting Jeddah's underpenetrated commercial office stock and Makkah hospitality infrastructure, where integrated facility platforms remain sparse relative to Riyadh saturation. Pursue Ministry of Education school privatization pilots as the most penetrable entry vector, leveraging child safety certification protocols to differentiate from informal competitors in a compliance-light segment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale technology-enabled operators possessing IoT deployment capabilities but lacking multi-site scale, as consolidation pressure from SASO mandates accelerates acquisition demand. Five-to-ten-year viability favors certified platforms with documented compliance protocols over labor-arbitrage models. Watch Nitaqat enforcement intensity as the signal determining whether technology substitution or training investments become the preferred compliance pathway.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Deployment | Computer vision and sensor networks enable performance-based contracts tied to MOHAP hygiene metrics. |
| MOHAP Certification Investment | Infection control accreditation opens surgical suite sterilization contracts with documented compliance trails. |
| Western Province Geographic Expansion | Jeddah commercial corridors and Makkah hospitality clusters lack integrated facility platform penetration. |
| Education Sector Entry | Ministry of Education privatization pilots create certified vendor demand with child safety protocols. |
| Technology-Driven Labor Substitution | Automated dispatch platforms reduce Nitaqat localization exposure while compressing response times. |
Research Methodology
Bottom-up healthcare and education facility modeling reconciled against top-down commercial real estate development tracking forms the analytical core of this study. Primary interviews with facility management executives, hospital procurement directors, MOHAP compliance officers, and giga-project development leads combined with secondary validation from Saudi Building Code amendments, SASO energy audit protocols, and Vision 2030 privatization directives. Top-down supply-side assessment triangulates against bottom-up demand aggregation across Riyadh, Jeddah, and Eastern Province contract awards.
Historical trendline analysis of outsourcing penetration rates and technology adoption velocity informs projection modeling across the analysis window. Segmentation dimensions include service type intensity, client asset class, delivery model capital structure, and application compliance burden. CAGRs derive from facility expansion pipelines, privatization timelines, and regulatory enforcement trajectories. Forecast inputs incorporate Nitaqat localization quota evolution and IoT platform deployment cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical capital expenditure cyclicality and Nitaqat enforcement intensity shifts. Model assumptions reflect documented compliance cost trajectories and technology substitution elasticities. A model refresh is warranted upon material change in MOHAP privatization pace or SASO audit frequency mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Oman Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Portugal Facility Management Market
Facility Management
Sweden Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Serbia Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Facility Management Services Market
Facility Management
GCC Facility Management Market