
 Mexico Facility Management Market | 2026-2036
Mexico Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Facility Management Market Foresight
Project finance and operating lease structures for building systems is fragmenting competitive dynamics in Mexico's facility management sector, enabling mid-tier operators to bid against established incumbents. CBRE Mexico leverages its capital markets expertise to bundle property management with equipment leasing. JLL Mexico anchors its position through workplace consulting tied to long-dated corporate contracts. Sodexo Facilities Management Services differentiates via integrated food and facilities offerings across healthcare and education verticals.
Facility management encompasses the coordination of building operations, maintenance, cleaning, security, and energy systems through standardized service protocols and performance metrics to ensure asset functionality and occupant productivity. In Mexico, this discipline integrates IoT-enabled monitoring with manual labor pools to address both informal employment patterns and rising technical complexity in Class A commercial stock. Maintenance Services and Security Services command the largest revenue shares due to mandatory compliance requirements and persistent labor availability. IoT Solutions represent the fastest-expanding technology category as portfolio operators deploy sensor networks for predictive equipment servicing and real-time energy optimization.
CONUEE, Mexico's national energy efficiency commission, mandates minimum performance standards for commercial building systems, directly shaping technology procurement decisions. SEMARNAT environmental regulations and local civil protection codes further constrain service delivery methods and chemical handling protocols across cleaning and maintenance operations. Stakeholders must weigh the capital requirements of building management system upgrades against the operational savings and compliance certainty these investments yield.
Market Dynamics
Maquiladora manufacturers along Mexico's northern border are consolidating fragmented maintenance contracts into single-source agreements, compressing supplier margins while elevating technical capability requirements for integrated facility operators.
Growth Catalysts
- CONUEE Energy Standards:Mandatory efficiency benchmarks for commercial building systems are forcing HVAC and lighting retrofits across Class A office portfolios in Mexico City and Monterrey.
- Healthcare Infrastructure Expansion:New hospital construction in Guadalajara and Puebla is generating demand for specialized biomedical equipment maintenance and infection-control cleaning protocols.
- IoT Sensor Networks:Predictive maintenance algorithms are reducing unplanned downtime for critical building systems in premium commercial stock.
Market Restraints
- Skilled Technician Shortage:Mexico's informal labor pool lacks certification density for building automation system programming, constraining service quality at scale.
- Input Cost Volatility:Imported HVAC components and specialty cleaning chemicals face peso-dollar exchange rate exposure, compressing contracted margin structures.
- SEMARNAT Compliance Burden:Hazardous waste handling protocols for industrial cleaning operations add procedural overhead that informal competitors circumvent.
Strategic Opportunities
- Querétaro Industrial Corridor:Aerospace and automotive manufacturing clusters lack mature facility management infrastructure, creating first-mover positioning for technical service providers.
- Remote Monitoring Convergence:Integration of drone-based roof inspection with thermal imaging analytics is opening predictive maintenance contracts for large-format logistics facilities.
- Public-Private Hospital Partnerships:ISSSTE and IMSS outsourcing initiatives are transferring non-clinical operations to specialized facility operators under long-dated concessions.
Industry Challenges
- Building Management System Integration:Legacy pneumatic controls in Mexico's aging commercial stock resist seamless integration with digital monitoring platforms, requiring costly parallel infrastructure.
- Certification Timeline Compression:CONUEE compliance deadlines for energy audits are outpacing accredited auditor availability, creating backlog risks for portfolio operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Facility Management Market |
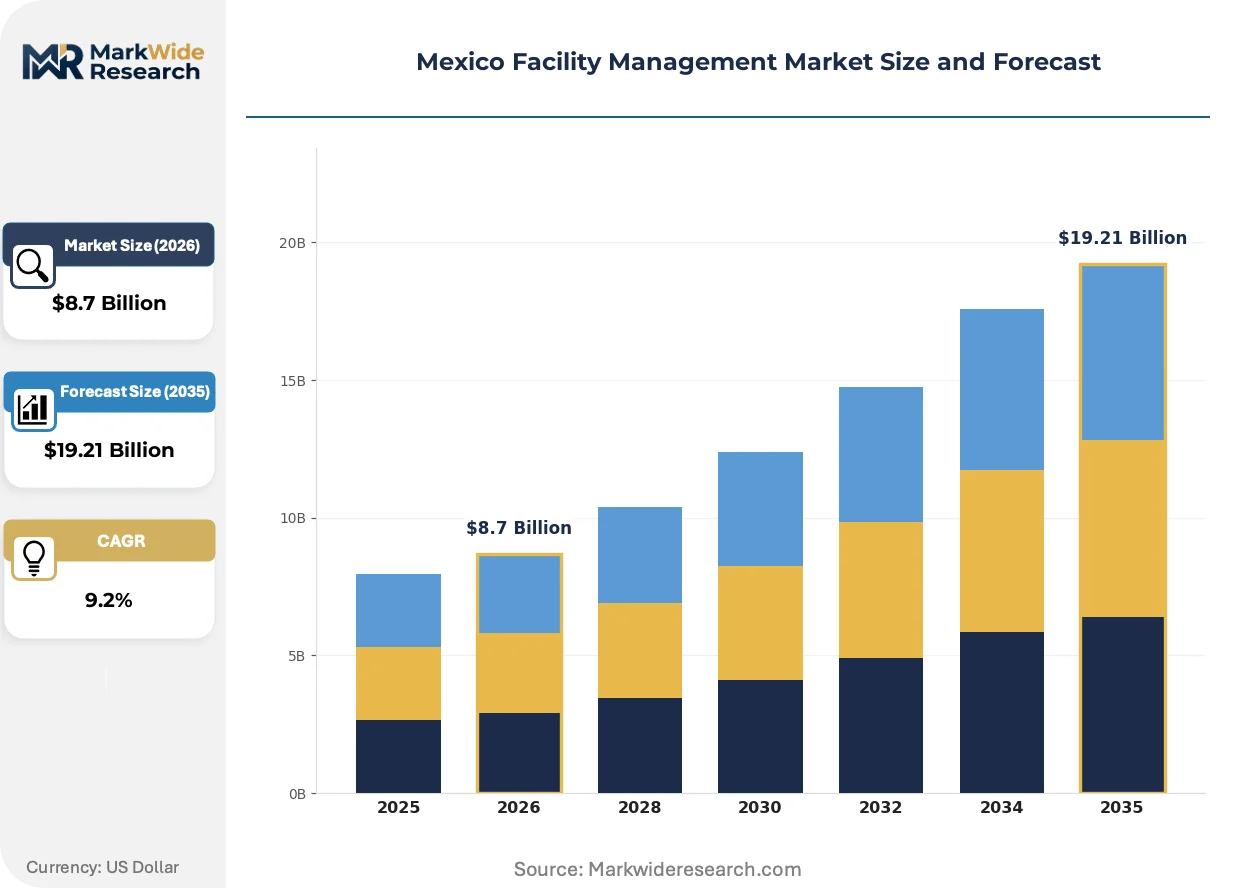
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Outlets Technology: IoT Solutions, Building Management Systems, Energy Management Systems, Integrated Workplace Management Systems Service Model: Outsourced Services, In-House Services, Hybrid Services, Managed Services |
| Companies Covered | ISS Mexico, Sodexo Facilities Management Services, CBRE Mexico, JLL Mexico, Grupo EULEN Mexico, Johnson Controls, Cushman & Wakefield, Compass Group, G4S Mexico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Facility Management Market Shifts & Advancements
Facility management in Mexico is transitioning from reactive break-fix models to data-driven asset lifecycle management, with technology vendors and service operators competing to own the operational data layer.
Digital twin platforms are replicating physical building performance in software environments for scenario testing and optimization. Industrial facility operators in Tijuana and Ciudad Juárez are piloting these systems for energy load forecasting. This capability is virtualizing commissioning and retro-commissioning processes that previously required physical intervention.
CONUEE's updated NOM-008-ENER standard for building envelope performance is mandating thermal imaging documentation for compliance certification. Property managers must now integrate infrared assessment into routine maintenance cycles. Healthcare and hospitality verticals face the steepest compliance ramps due to 24/7 operational requirements.
Corporate occupiers are unbundling facilities services from bundled property management agreements, creating direct contracting relationships with specialized operators. Multinational tenants in Mexico City's Santa Fe district are leading this disintermediation, seeking transparent KPI-based pricing. This pattern is most pronounced among technology and financial services firms with centralized procurement functions.
Mexico Facility Management Market Segmentation
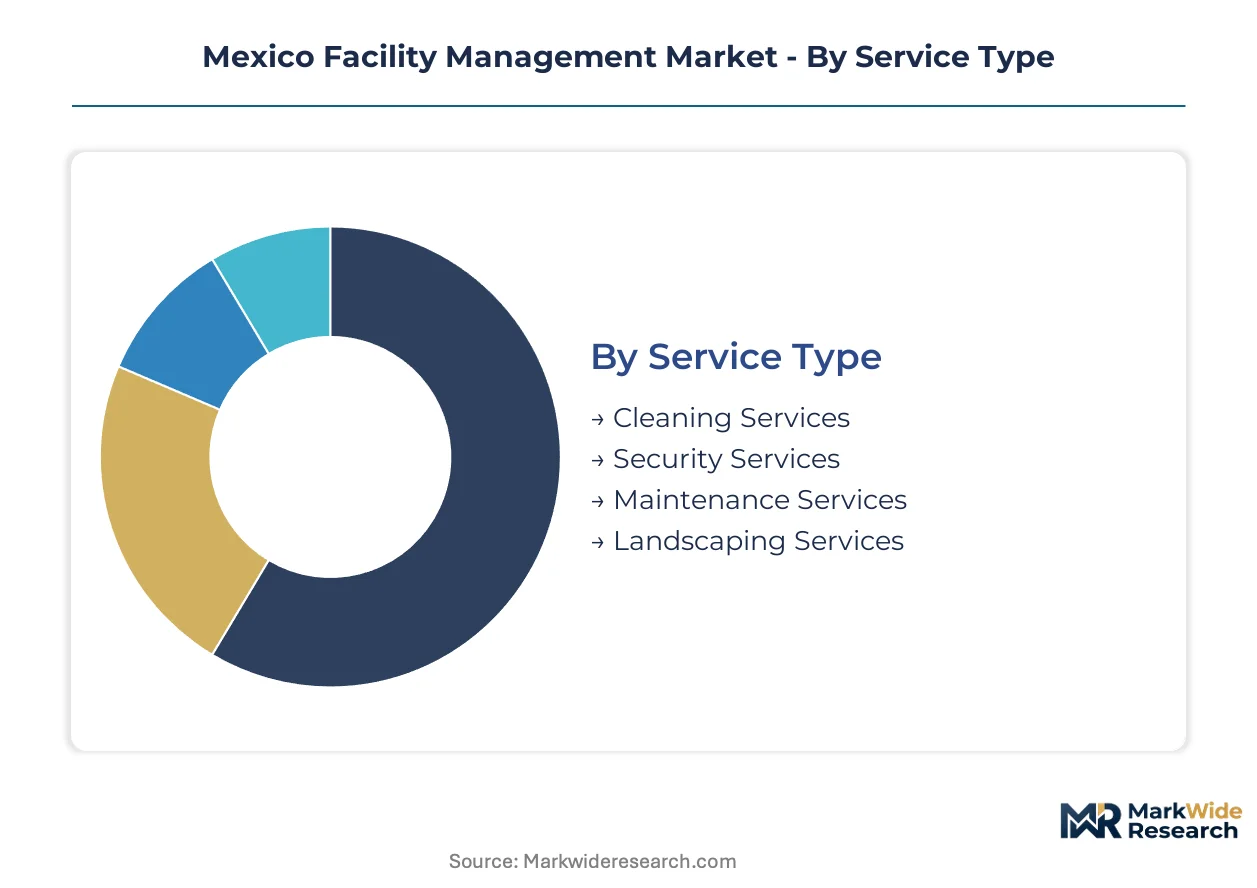
Mexico's facility management sector fragments across service delivery methods, end-user sophistication, and technology integration depth. Procurement patterns diverge sharply between multinational-occupied Class A stock and domestically owned mid-tier assets, creating distinct competitive arenas within each segment category.
Service Type:
Mature segments dominate revenue concentration while emerging specialties capture technology-enabled growth pockets.
- Maintenance Services:Encompasses HVAC, electrical, plumbing, and mechanical system upkeep through scheduled preventive protocols and emergency response frameworks. Demand concentrates in Monterrey's industrial parks and Mexico City's Santa Fe financial district, where equipment uptime directly impacts lease valuations and tenant retention.
- Security Services:Physical guarding, access control, surveillance monitoring, and threat assessment protocols delivered through manned posts and electronic systems. Healthcare facilities in Guadalajara and Puebla are expanding biometric integration and visitor management systems to meet evolving civil protection mandates.
- Cleaning Services:Routine janitorial, specialized disinfection, and infection-control protocols for commercial and institutional environments.
- Landscaping Services:Exterior grounds maintenance, irrigation management, and seasonal planting for corporate campuses and retail developments.
Maintenance Services handles the majority of throughput; Security Services is the fastest mover on share.
End User:
Cost tier stratification separates premium-grade requirements from price-sensitive volume accounts.
- Corporate Offices:Class A towers and business parks requiring integrated workplace experience management, concierge services, and sustainability certification support. Mexico City's Polanco and Reforma corridors drive demand for smart building integration and flexible space reconfiguration.
- Healthcare Facilities:Hospitals, clinics, and medical office buildings requiring specialized biomedical equipment maintenance, sterile environment protocols, and regulatory documentation. IMSS and ISSSTE outsourcing initiatives are transferring non-clinical operations to specialized operators under long-term concessions.
- Educational Institutions:Universities, K-12 campuses, and vocational training centers with seasonal occupancy patterns and specialized laboratory maintenance needs.
- Retail Outlets:Shopping centers, big-box stores, and quick-service restaurant chains prioritizing rapid response times and brand-standard environment consistency.
Corporate Offices commands the largest contract values; Healthcare Facilities is expanding most quickly as public-private partnerships proliferate.
Technology:
Application-specific deployment patterns separate building-automation infrastructure from occupant-facing workplace tools.
- IoT Solutions:Sensor networks for predictive equipment maintenance, real-time energy monitoring, and automated fault detection across distributed portfolios. Industrial operators in Tijuana and Ciudad Juárez are piloting digital twin platforms for energy load forecasting and scenario testing.
- Building Management Systems:Centralized control platforms integrating HVAC, lighting, and security subsystems through standardized communication protocols. Legacy pneumatic controls in aging commercial stock resist seamless integration, requiring costly parallel infrastructure investments.
- Energy Management Systems:Metering, analytics, and automated demand response tools for CONUEE compliance and utility cost reduction.
- Integrated Workplace Management Systems:Space planning, desk booking, and employee experience platforms for hybrid work environments.
Building Management Systems anchors installed base; IoT Solutions is gaining share fastest as portfolio operators prioritize predictive capabilities.
Service Model:
Customer type and internal capability maturity determine sourcing strategy selection.
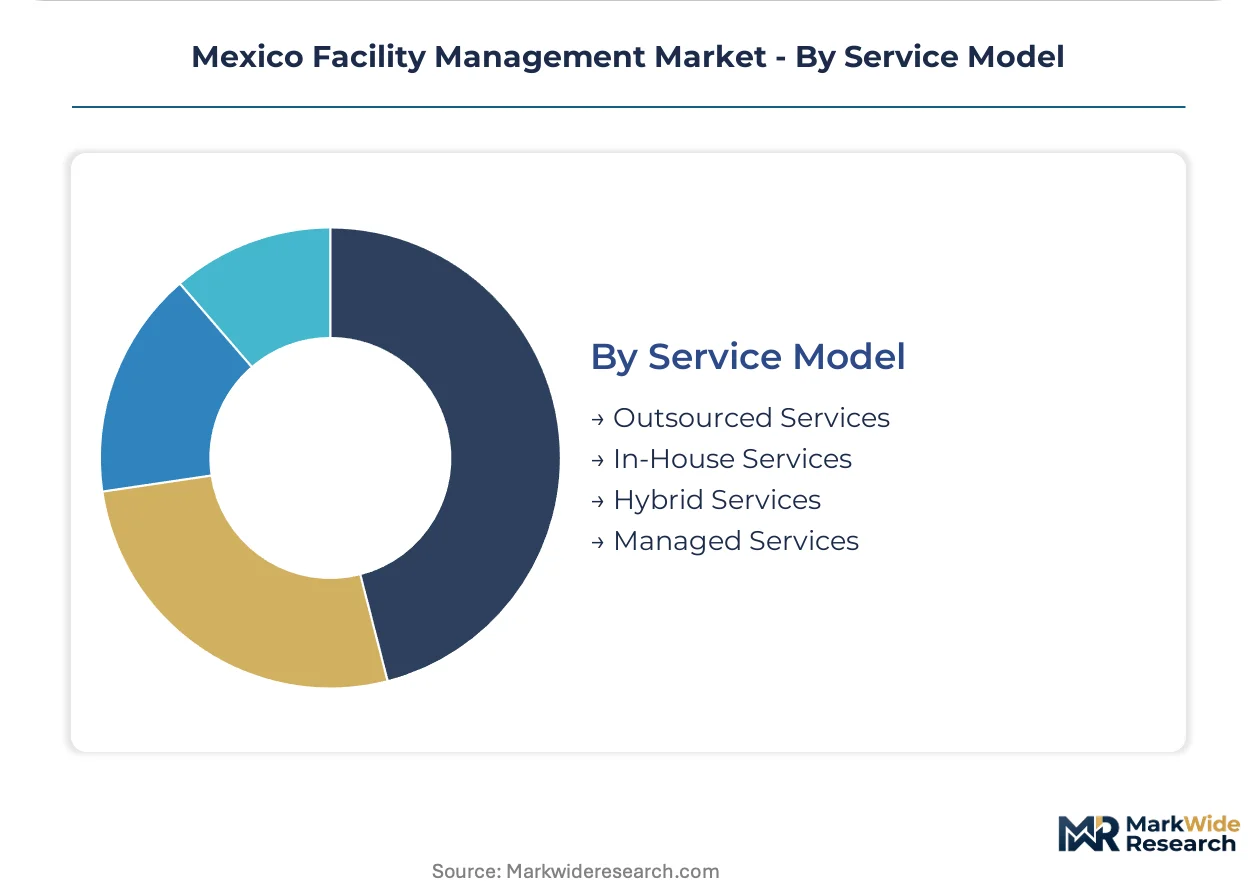
- Outsourced Services:Comprehensive facility operations transferred to third-party providers under multi-year contracts with SLA-defined performance metrics. Maquiladora manufacturers along the northern border are consolidating fragmented maintenance agreements into single-source arrangements.
- Managed Services:Outcome-based partnerships where operators assume risk for asset performance and energy consumption against guaranteed benchmarks. Premium office landlords in Monterrey are adopting this structure to align vendor incentives with net operating income targets.
- In-House Services:Direct employment of maintenance and operations staff, predominant among government institutions and industrial owner-occupiers with specialized process requirements.
- Hybrid Services:Blended structures retaining strategic control of critical systems while outsourcing commoditized functions.
Outsourced Services captures the dominant procurement mode; Managed Services is climbing the fastest as risk-transfer structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CONUEE's mandatory energy efficiency standards for commercial buildings are redistributing facility management procurement across Mexico's major economic corridors. Compliance deadlines are compressing vendor selection timelines and elevating technical certification requirements.
Mexico City Metro
Class A office towers in Polanco and Santa Fe are driving integrated workplace management contracts as multinational tenants unbundle services from traditional property management agreements. The capital's updated environmental regulations under SEMARNAT are mandating hazardous waste documentation for industrial cleaning operations. Santa Fe's financial district is witnessing rapid adoption of IoT-enabled building systems as landlords pursue CONUEE certification.
Nuevo León
Monterrey's premium industrial parks are consolidating fragmented maintenance contracts into single-source facility management agreements to reduce supplier complexity. The state's civil protection codes are tightening security service protocols for manufacturing facilities. Apodaca and Santa Catarina are emerging as concentrated demand zones for technical maintenance services supporting automotive and electronics clusters.
Jalisco
Guadalajara's healthcare infrastructure expansion is generating specialized demand for biomedical equipment maintenance and infection-control cleaning protocols. IMSS outsourcing initiatives are transferring non-clinical hospital operations to specialized facility operators under long-term concessions. The city's Zapopan district is attracting workplace consulting contracts from technology sector tenants.
Bajío Region
Querétaro's aerospace and automotive manufacturing clusters lack mature facility management infrastructure, creating positioning opportunities for technical service providers. The region's industrial development incentives are accelerating foreign direct investment in advanced manufacturing. San Luis Potosí's logistics corridor is piloting drone-based roof inspection integrated with thermal imaging analytics.
Northern Border States
Maquiladora facilities in Tijuana and Ciudad Juárez are expanding integrated service contracts to reduce operational complexity across cross-border supply chains. Mexico's customs and trade facilitation programs are streamlining equipment importation for building system upgrades. Ciudad Juárez industrial parks are deploying digital twin platforms for energy load forecasting and scenario testing.
Mexico Facility Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Mexico's facility management sector, creating tiered competitive dynamics. Integrated property managers leverage capital markets expertise to bundle leasing with operational services, while specialized operators capture niche technical contracts. Three archetypes dominate: full-service integrated providers, technology-enabled specialists, and labor-intensive regional operators. Consolidation through single-source contract awards and vertical capability expansion into energy management systems represent the primary competitive vectors.
Within the integrated services tier, CBRE Mexico and JLL Mexico occupy positions combining property management with workplace consulting. Sodexo Facilities Management Services exemplifies the vertical-specialist archetype through its integrated food and facilities offerings across healthcare and education. ISS Mexico anchors the multinational scale-driven segment with broad service portfolios spanning security, cleaning, and technical maintenance.
| Leading Market Players |
|---|
| ISS Mexico |
| Sodexo Facilities Management Services |
| CBRE Mexico |
| JLL Mexico |
| Grupo EULEN Mexico |
| Johnson Controls |
| Cushman & Wakefield |
| Compass Group |
| G4S Mexico |
| Others |
Supply & Pricing Matrix
Peso-dollar exchange rate volatility determines both pricing tier spreads and supply chain shape across Mexico's facility management sector, compressing margins on imported HVAC components while forcing procurement localization for cost containment.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with CONUEE-accredited energy auditors and ISO-certified maintenance operators commanding 20-40% contract premiums over informal competitors. Contract structures bifurcate into fixed-fee integrated service agreements for multinational maquiladora accounts and transactional spot pricing for domestically owned mid-tier assets. Cost compression in the standard tier is intensifying because peso depreciation inflates imported component costs that informal operators cannot hedge. Maquiladora manufacturers with centralized procurement functions exhibit lowest price sensitivity, while regional retail chains and owner-occupied industrial facilities drive hardest bargain negotiations.
Supply Chain Analysis
Upstream feedstock for building automation systems draws primarily from China, the United States, and Germany, with HVAC control modules, IoT sensor arrays, and thermal imaging equipment anchoring import dependency. Specialty cleaning chemicals, biometric security hardware, and predictive maintenance software licenses constitute secondary input categories. Single-source vulnerability concentrates in advanced building management system controllers, where two German and one U.S. manufacturer dominate technical certification pathways. Distribution runs through Monterrey and Mexico City-based technical distributors serving northern industrial corridors, with direct manufacturer relationships emerging for large-scale maquiladora accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity constrains service quality at scale across Mexico's facility management sector, with CONUEE energy auditor availability lagging compliance deadline acceleration and building automation programming expertise concentrated among a handful of metropolitan operators.
For Market Incumbents: Harden technical certification pipelines by partnering with Tecnológico de Monterrey and UNAM to accelerate CONUEE-accredited auditor training programs, insulating against compliance backlog risks. Deepen backward integration into energy management system deployment capabilities to capture retrofit margins currently leaking to specialized technology vendors. Consolidate regional maintenance operators in Querétaro and Bajío corridors before first-mover positioning solidifies.
For New Entrants and Emerging Players: Build out drone-based thermal inspection capabilities targeting San Luis Potosí logistics facilities, where predictive maintenance infrastructure remains underdeveloped and aerospace manufacturing clusters lack mature technical service relationships. Target ISSSTE and IMSS hospital outsourcing concessions in Guadalajara and Puebla as the most penetrable public-private vertical, leveraging specialized biomedical equipment maintenance credentials as entry wedge.
For Investors and Strategic Acquirers: Technology-enabled regional operators with established CONUEE compliance track records represent the most defensible acquisition archetype, combining localized labor relationships with digital platform deployment experience. Long-term viability hinges on 5-10 year energy efficiency mandate enforcement continuity and maquiladora manufacturing reshoring durability. Watch for CONUEE audit deadline extensions or accreditation requirement relaxations as negative inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| CONUEE Certification Investment | Positions operators for mandatory energy audit contracts across Class A office portfolios in Mexico City and Monterrey. |
| Biomedical Equipment Maintenance Capability | Captures IMSS and ISSSTE hospital outsourcing concessions requiring sterile environment protocols. |
| IoT Sensor Network Deployment | Enables predictive maintenance contracts for maquiladora manufacturers consolidating fragmented service agreements. |
| Drone-Based Thermal Inspection Service | Opens predictive maintenance revenue streams for large-format logistics facilities in San Luis Potosí corridor. |
| Technical Training Partnership | Addresses certified technician scarcity constraining building automation system programming quality at scale. |
Research Methodology
A standing panel of facility management executives, CONUEE compliance officers, maquiladora operations directors, and hospital procurement managers provided ongoing calibration throughout the primary research phase. Secondary validation drew from SEMARNAT regulatory filings, CONUEE energy standard documentation, IMSS and ISSSTE concession records, and customs import data for building automation components. Bottom-up service provider revenue estimates were triangulated against top-down construction and real estate investment flows across Mexico's major metropolitan markets.
Scenario bracketing around peso volatility bands, maquiladora contract consolidation velocity, and healthcare infrastructure buildout pace anchored the analytical framework across the projection horizon. Segmentation modeling incorporated service type, end-user vertical, technology integration depth, and regional procurement sophistication dimensions. CAGRs were derived from fitted trend extrapolation against historical contract value growth and verified against capital expenditure pipeline data from premium commercial development projects.
Stress conditions across exchange rate depreciation, skilled labor availability, and regulatory deadline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding CONUEE enforcement continuity and northern border manufacturing investment retention. Cross-checking against CBRE and JLL Mexico market transaction databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Bahrain Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Malaysia Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Europe Hard Facility Management Market