
 United Arab Emirates Facility Management Market | 2026-2036
United Arab Emirates Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Facility Management Market Analytics
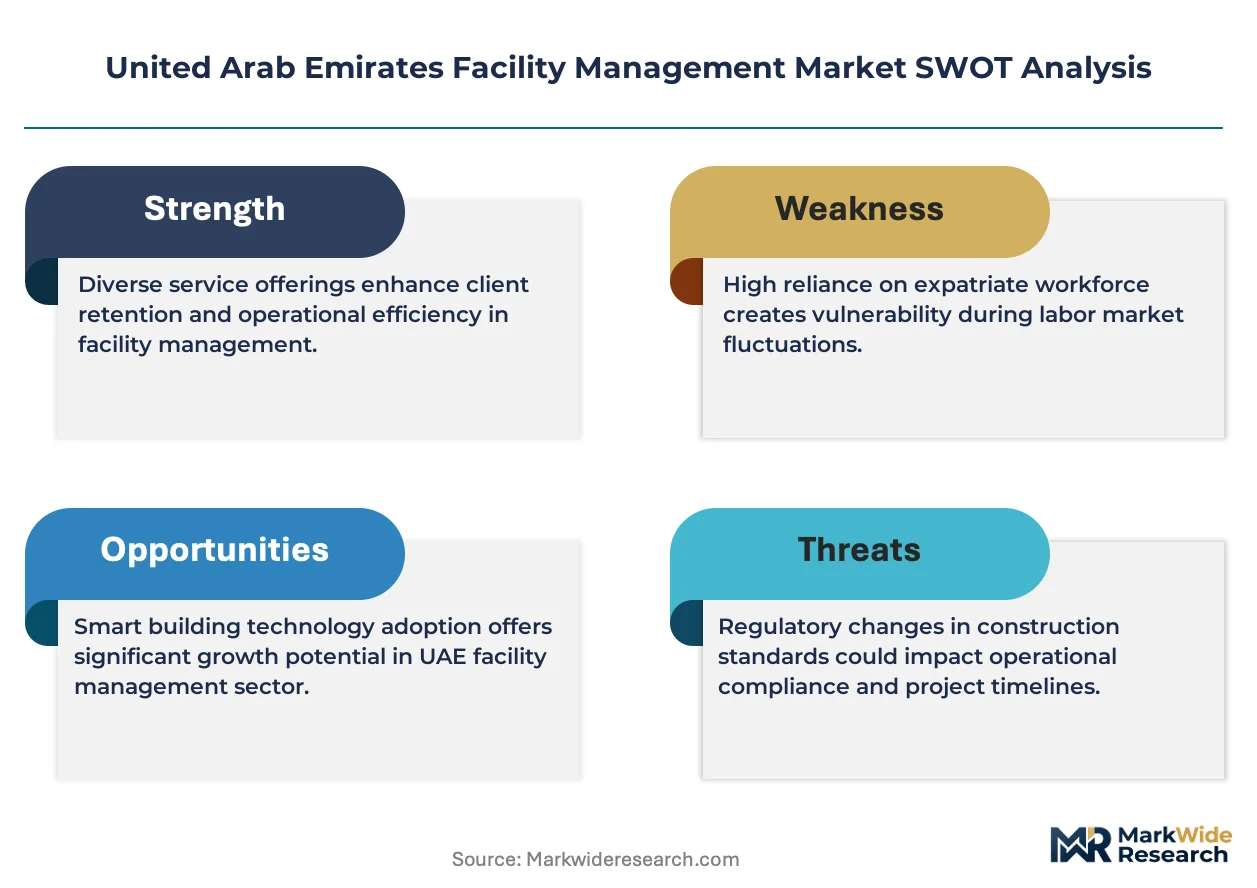
ISO 41001:2018 certification is rotating the competitive landscape, filtering out unqualified operators as UAE government contracts now mandate certified facility management providers. Engie UAE leverages its European technical heritage to dominate energy-intensive commercial portfolios. Imdaad LLC sustains a diversified service matrix spanning cleaning, security, and maintenance under one contract structure. Farnek Services LLC differentiates through sustainability auditing and green building compliance services.
Facility management encompasses the integration of processes, people, and technology to maintain and optimize the built environment across commercial, residential, and institutional assets, typically governed by service level agreements specifying response times, uptime thresholds, and energy performance benchmarks. Its primary purpose ensures operational continuity, occupant safety, and asset value preservation for property owners and institutional occupiers. Maintenance services command the largest revenue pool within Service Type segmentation due to mandatory equipment lifecycle obligations in high-rise buildings. IoT Solutions within Technology segmentation represents the fastest-expanding category as Dubai's building codes increasingly require predictive maintenance infrastructure. Commercial Buildings within End User segmentation anchors volume demand through the emirate's sustained office and retail construction pipeline.
MOHAP enforces healthcare facility hygiene protocols that elevate cleaning and infection-control service standards, while Dubai Municipality mandates building energy audits that drive adoption of Energy Management Systems. The UAE's dual carbon goals and net-zero pathway for Dubai 2050 compress retrofit timelines, forcing asset owners to upgrade legacy properties. Stakeholders must monitor how SAMR-aligned smart building standards and evolving emirate-level sustainability mandates reshape procurement criteria and vendor qualification thresholds.
Market Dynamics
MOHAP infection-control mandates and Dubai Municipality energy audit requirements are compressing procurement cycles, forcing asset owners to consolidate vendor relationships around certified operators capable of delivering integrated compliance, maintenance, and IoT-enabled monitoring under single contract structures.
Growth Catalysts
- ISO 41001:2018 Certification Mandates:UAE government contracts now require certified facility management providers, filtering unqualified operators and concentrating contract flow toward compliant vendors.
- Smart Building IoT Integration:Dubai's building codes increasingly mandate predictive maintenance infrastructure, accelerating sensor deployment and automated work order systems across commercial tower stock.
- Healthcare Facilities Expansion:MOHAP hygiene protocol enforcement elevates cleaning and infection-control service standards, expanding specialized service demand across hospital and clinic portfolios.
Market Restraints
- Labor Cost Escalation:Skilled technician wages in Dubai and Abu Dhabi are rising faster than contract escalation clauses, squeezing margin structures for maintenance-heavy service providers.
- Supply Concentration in Equipment:Critical HVAC and building automation components depend on concentrated European and East Asian manufacturing bases, exposing operators to extended lead times and currency volatility.
- Technical Debt in Legacy Assets:Pre-2010 commercial stock lacks the digital infrastructure required for predictive maintenance, forcing costly retrofit investments before IoT solutions can deploy.
Strategic Opportunities
- Net-Zero Retrofit Services:Dubai 2050 net-zero commitments compress upgrade timelines for legacy properties, creating demand for energy auditing, EMS installation, and green building compliance consulting.
- Integrated Single-Contract Structures:Asset owners are consolidating cleaning, security, and maintenance under unified service level agreements, rewarding operators with diversified technical capabilities.
- SAMR-Aligned Smart Building Standards:Adoption of SAMR smart building frameworks opens procurement pathways for vendors offering certified IoT integration and automated facility monitoring systems.
Industry Challenges
- Certification Timeline Compression:ISO 41001:2018 compliance requires documented quality management systems that smaller operators cannot assemble before contract qualification deadlines.
- Interoperability with Legacy BMS:New IoT platforms must integrate with existing building management systems from fragmented vendor ecosystems, extending deployment cycles and inflating integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Facility Management Market |
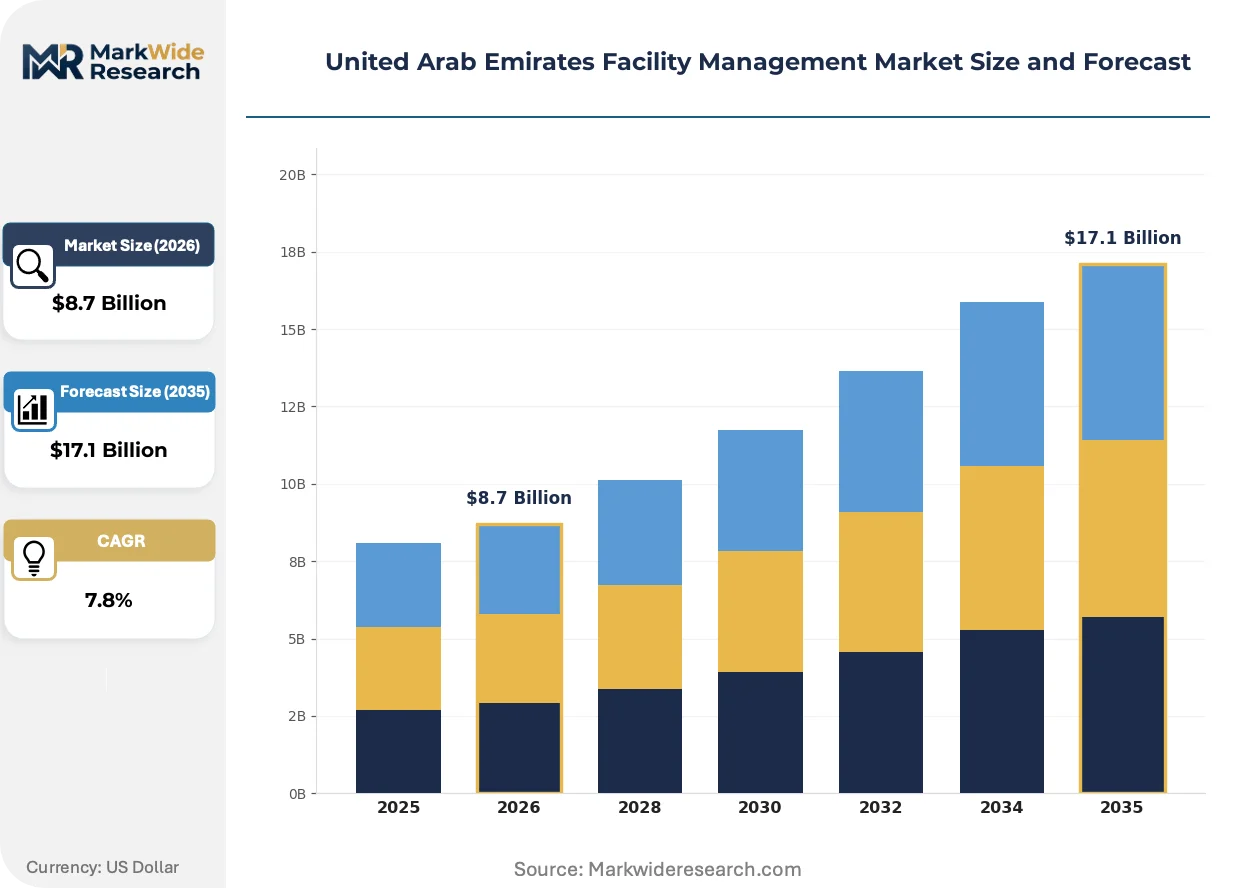
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Residential Complexes Technology: IoT Solutions, Cloud-Based Platforms, Energy Management Systems, Automated Systems Application: Real Estate Management, Property Management, Asset Management, Environmental Sustainability |
| Companies Covered | EFS Facilities Services Group, Al Shirawi Facilities Management, Emrill Services LLC, Engie UAE, Blue Diamond Facilities Management, Imdaad LLC, Transguard Group, ServeU LLC, Farnek Services LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Facility Management Market Evolving Landscape
Predictive maintenance platforms and automated compliance reporting are reshaping how facility operators deliver uptime guarantees, compressing response windows while expanding the data services bundled into standard contracts.
Digital twin technology is decomposing traditional reactive maintenance models by creating real-time virtual replicas of building systems. Large commercial landlords in Dubai's free zones are deploying these platforms to simulate equipment failure scenarios before they occur. This capability is decomposing the historical reliance on scheduled preventive maintenance contracts, shifting value toward continuous monitoring subscriptions.
Dubai Municipality building energy audit mandates are forcing asset owners to install certified Energy Management Systems and disclose consumption metrics. Commercial towers exceeding specified floor area thresholds must now submit verified audit documentation to maintain operating licenses. High-rise office stock in Business Bay and DIFC faces the steepest compliance costs, driving consolidation toward vendors with in-house energy engineering capabilities.
Integrated service bundling is displacing siloed vendor relationships as institutional buyers seek single-accountability structures. Property developers in Abu Dhabi's government district now specify unified facilities management contracts spanning cleaning, security, mechanical maintenance, and sustainability reporting. This pattern concentrates contract value among operators with cross-functional technical teams rather than specialized single-service providers.
United Arab Emirates Facility Management Market Segmentation
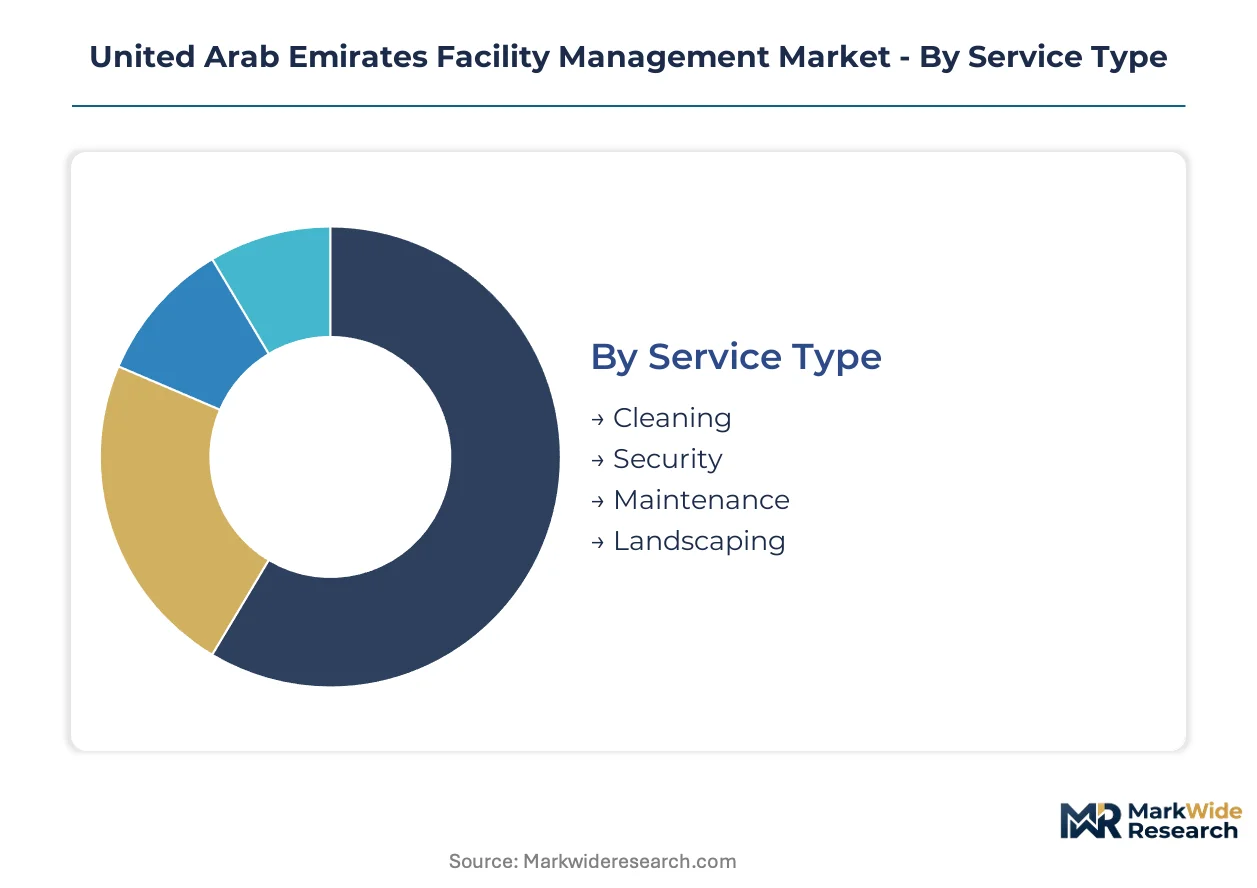
Facility management procurement in the UAE compresses around compliance mandates and asset-class requirements. Service bundling patterns vary sharply between Dubai's commercial free zones and Abu Dhabi's government district developments.
Service Type:
Margin pools concentrate in technical maintenance services where equipment lifecycle obligations and certification requirements create pricing power.
- Maintenance:Encompasses HVAC, electrical, and mechanical systems upkeep governed by Dubai Municipality equipment inspection schedules. Demand concentrates in Dubai's high-rise commercial towers where elevator and chiller uptime clauses carry penalty structures. MOHAP infection-control mandates for healthcare facilities elevate technical service specifications.
- Security:Includes manned guarding, access control, and surveillance systems deployment. Abu Dhabi's government district developments specify integrated security-maintenance contracts with unified accountability structures. Cyber-physical convergence in smart buildings is expanding scope beyond traditional perimeter protection.
- Cleaning:Covers janitorial and specialized hygiene services. Healthcare portfolios drive premium tier demand under MOHAP sterilization protocols.
- Landscaping:Encompasses grounds maintenance and irrigation management. Dubai's free zone commercial clusters specify aesthetic standards tied to lease valuations.
Maintenance holds installed capacity. Security is rotating up the share rankings.
End User:
Volume distribution tracks construction pipeline intensity and regulatory compliance burden by asset class.
- Commercial Buildings:Office towers and retail complexes in Business Bay and DIFC generate the deepest contract values. Dubai Municipality energy audit mandates force disclosure of consumption metrics, concentrating procurement toward vendors with in-house EMS engineering.
- Healthcare Facilities:Hospitals and clinics operate under MOHAP hygiene protocol enforcement that elevates cleaning and infection-control specifications. Specialized service demand is expanding across Dubai Healthcare City and Abu Dhabi's medical city developments.
- Educational Institutions:Schools and universities require integrated safety and maintenance coverage. Abu Dhabi's government district specifications favor unified contract structures.
- Residential Complexes:High-rise apartment buildings in Dubai Marina and Jumeirah Lakes Towers drive recurring maintenance demand. Community management associations consolidate vendor relationships around single-accountability providers.
Commercial Buildings anchor contract volume. Healthcare Facilities are gaining share fastest.
Technology:
Adoption velocity diverges sharply between greenfield smart building deployments and legacy asset retrofit constraints.
- IoT Solutions:Sensor networks and predictive maintenance platforms enable continuous equipment monitoring. Dubai's building codes increasingly mandate predictive infrastructure for commercial towers exceeding specified floor area thresholds.
- Energy Management Systems:Certified EMS installations satisfy Dubai Municipality audit requirements. Business Bay and DIFC high-rise stock faces steepest compliance cost concentration.
- Cloud-Based Platforms:Centralized work order and asset registry systems support multi-site portfolio management. Free zone commercial landlords deploy these for unified operational visibility.
- Automated Systems:Robotic cleaning and drone inspection technologies reduce labor dependency. Skilled technician wage escalation in Dubai accelerates automation business case validation.
IoT Solutions command premium deployment timelines. Energy Management Systems are climbing the fastest in procurement priority.
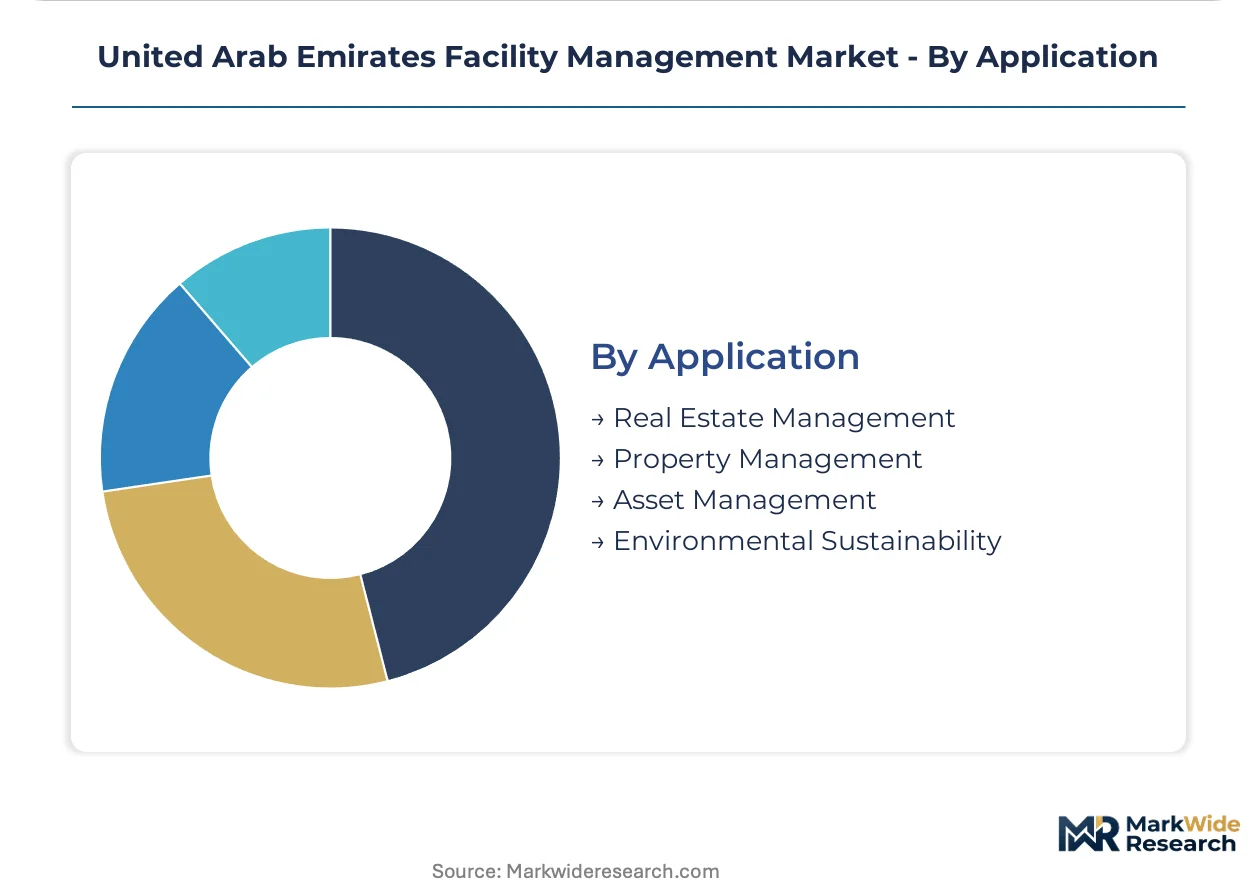
Application:
Value capture shifts from reactive service delivery toward data-enabled advisory and compliance documentation.
- Real Estate Management:Lease administration and tenant experience optimization for commercial portfolios. Dubai's free zone clusters specify integrated service level agreements spanning technical and hospitality functions.
- Property Management:Day-to-day operational oversight of building systems and common areas. Abu Dhabi's government district developments consolidate cleaning, security, and maintenance under unified contracts.
- Asset Management:Lifecycle planning and capital expenditure forecasting for building systems. Digital twin technology is decomposing traditional reactive models in large commercial portfolios.
- Environmental Sustainability:Green building compliance consulting and carbon reporting. Dubai 2050 net-zero commitments compress retrofit timelines for legacy commercial stock.
Property Management holds baseline contract penetration. Environmental Sustainability is expanding most quickly in scope inclusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP infection-control mandates and Dubai Municipality energy audit requirements are compressing procurement cycles across the emirates, forcing asset owners to consolidate vendor relationships around certified operators capable of delivering integrated compliance services.
Dubai
Commercial tower stock in Business Bay and DIFC generates the deepest contract values under Dubai Municipality building energy audit mandates. Dubai's building codes increasingly require predictive maintenance infrastructure for commercial towers exceeding specified floor area thresholds. Free zone clusters including Dubai Internet City and Dubai Media City specify integrated service level agreements spanning technical and hospitality functions.
Abu Dhabi
Government district developments consolidate cleaning, security, and maintenance under unified contract structures with single-accountability provisions. The emirate's medical city developments operate under MOHAP hygiene protocol enforcement that elevates cleaning and infection-control specifications. Large-scale residential and institutional projects in Al Reem Island and Saadiyat Island drive recurring maintenance demand for diversified service providers.
Sharjah
Industrial zone expansions and university campus developments create steady demand for integrated facilities management across manufacturing and educational asset classes. Sharjah's cost-sensitive procurement environment favors operators with scalable service delivery models. The emirate's heritage district preservation projects require specialized conservation maintenance capabilities.
Northern Emirates
Ras Al Khaimah and Fujairah hospitality developments along the eastern coastline generate seasonal demand spikes for resort and hotel facilities management. Port and logistics infrastructure in Fujairah anchors industrial maintenance contracts. Lower labor cost structures compared to Dubai and Abu Dhabi attract regional operators establishing secondary service hubs.
United Arab Emirates Facility Management Market Competitive Landscape
Player mix skews toward diversified integrated service providers with cross-functional technical teams capable of delivering maintenance, security, cleaning, and sustainability reporting under single contract structures. The vendor base concentrates around operators holding ISO 41001:2018 certification as UAE government contracts now mandate certified providers. Three strategic archetypes dominate: European technical heritage firms with energy engineering capabilities, locally diversified service conglomerates spanning multiple facility functions, and sustainability-focused specialists offering green building compliance consulting. Competitive moves center on portfolio diversification into adjacent services and strategic consolidation of vendor relationships by institutional buyers seeking unified accountability.
Among UAE-based integrated service providers, Imdaad LLC and Farnek Services LLC exemplify the diversified conglomerate archetype with cross-functional capabilities spanning technical maintenance and specialized compliance services. Engie UAE represents the European technical heritage model, leveraging energy engineering expertise to anchor energy-intensive commercial portfolios. These three operators occupy positions within a market structure filtering toward certified providers capable of delivering IoT-enabled monitoring and predictive maintenance infrastructure under consolidated contract frameworks.
| Leading Market Players |
|---|
| EFS Facilities Services Group |
| Al Shirawi Facilities Management |
| Emrill Services LLC |
| Engie UAE |
| Blue Diamond Facilities Management |
| Imdaad LLC |
| Transguard Group |
| ServeU LLC |
| Farnek Services LLC |
| Others |
Value Network & Pricing Analysis
Scale advantages in multi-service contract execution compress cost structures for integrated operators while elevating price floors for specialized single-function vendors. Dubai's ISO 41001:2018 certification mandates concentrate procurement around compliant providers capable of absorbing compliance overhead across larger contract bases.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with ISO 41001:2018-compliant operators commanding 15-25% contract premiums over uncertified competitors. Three-tier pricing structure across integrated full-service, technical maintenance-only, and basic cleaning-guarding bundles reflects capability differentiation. Pricing pressure stems from skilled technician wage escalation in Dubai and Abu Dhabi outpacing contract escalation clauses. Government and institutional buyers exhibit lowest price sensitivity due to compliance mandate rigidity, while cost-sensitive Sharjah industrial clients drive hardest rate negotiations.
Supply Chain Analysis
Germany and Japan anchor HVAC component and building automation system manufacturing for UAE facility management operators. Critical equipment including chillers, elevators, and BMS controllers draws from concentrated European and East Asian production bases. Single-source vulnerability in semiconductor-dependent IoT sensor modules exposes operators to extended lead times and currency volatility. Distribution runs through Dubai-based regional warehousing hubs serving northern emirate secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent facility management operators face substitution pressure from technology-enabled platform entrants offering predictive maintenance as-a-service, threatening traditional time-and-materials contract structures.
For Market Incumbents: Fortify contract stickiness by embedding IoT-enabled monitoring subscriptions into base service agreements, creating switching costs that pure-play technology entrants cannot replicate. Deepen technical maintenance capabilities in-house to capture margin pools currently leaking to specialized subcontractors. Prioritize ISO 41001:2018 certification maintenance as MOHAP and Dubai Municipality procurement filters tighten.
For New Entrants and Emerging Players: Predictive maintenance platform gaps in pre-2010 commercial stock present immediate white-space opportunity for retrofit-focused technology vendors. Sharjah's cost-sensitive industrial zones offer lowest competitive density for scaled operators with automated service delivery models. Position around SAMR-aligned smart building certification as Dubai's building codes evolve.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators with government and healthcare contract exposure under multi-year service level agreements. Target diversified service providers with cross-functional technical teams spanning maintenance, security, and sustainability reporting. Monitor Dubai 2050 net-zero retrofit mandate acceleration as inflection indicator for energy auditing and EMS installation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001:2018 Certification Investment | Mandatory qualification for UAE government contract eligibility under MOHAP procurement rules. |
| IoT Platform Integration | Enables predictive maintenance subscriptions that displace reactive service revenue models. |
| Energy Management System Deployment | Satisfies Dubai Municipality audit mandates for commercial towers exceeding floor area thresholds. |
| Technical Maintenance Capability Buildout | Captures margin pools in HVAC and elevator lifecycle services with penalty-backed uptime clauses. |
| Net-Zero Retrofit Service Launch | Aligns with Dubai 2050 commitments compressing upgrade timelines for legacy commercial stock. |
Research Methodology
Initial hypotheses were tested against primary input from facility management operations directors, property developer procurement leads, and Dubai Municipality compliance officers and refined through secondary validation. Primary fieldwork encompassed structured interviews with integrated service provider executives, healthcare facility engineering managers, and free zone commercial landlord asset managers. Secondary sources included Dubai Municipality building energy audit filings, MOHAP healthcare facility hygiene compliance records, and UAE federal procurement contract disclosures. Bottom-up contract value estimates were triangulated against top-down market size benchmarks.
Variance decomposition across service type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. Segmentation modeling incorporated maintenance intensity by building vintage, regulatory compliance burden by asset class, and IoT adoption velocity by developer sophistication. CAGRs were derived from contract value growth trajectories and construction pipeline forecasts. Forecast inputs included Dubai's commercial tower completion schedules and Abu Dhabi government district development timelines.
Forecasts assume regulatory continuity in Dubai Municipality energy audit enforcement and MOHAP healthcare facility protocols; material policy shifts would require re-modeling. Supply chain disruption risks from concentrated HVAC component sourcing and skilled labor availability constraints represent primary forecast revision triggers. Recalibration cycles align with material shifts in emirate-level sustainability mandate evolution and smart building code adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
China Facility Management Market
Facility Management
Latin America Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Philippines Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Spain Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
GCC Facility Management Market